
 Vietnam Coffee Market | 2026-2036
Vietnam Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Coffee Market Outlook
Multi-source bean procurement is recalibrating how Vietnamese roasters manage supply risk and quality consistency. Trung Nguyên leverages its captive plantation network to secure Robusta volumes. Nestlé S.A. sustains large-scale soluble coffee operations through centralized processing hubs. Highlands Coffee competes by dominating urban café channels in major Vietnamese cities.
Coffee comprises roasted seeds of Coffea species, with Robusta (Coffea canephora) typically containing 2.2–2.7% caffeine and processed through wet-hulling for earthy, heavy-bodied profiles suited to instant manufacturing and dark-roast blends. Robusta leads volume due to Vietnam's climatic suitability and export economics, while washed Arabica commands premium positioning in specialty retail. Wet-hulled processing anchors mainstream output, though honey-processed lots are gaining traction among third-wave roasters seeking differentiated cup profiles.
Vietnam's Ministry of Agriculture and Rural Development sets phytosanitary and origin-certification requirements for export consignments, while the General Department of Customs enforces traceability documentation under trade facilitation agreements. The country's national standards body aligns grading protocols with ISO benchmarks to maintain European and North American market access. Stakeholders must monitor how evolving EU deforestation-free supply chain regulations reshape bean traceability investments and smallholder compliance costs.
Market Dynamics
EU deforestation-free supply chain regulations are forcing Vietnamese exporters to rebuild traceability infrastructure from farm gate to port, compressing margins for smallholders while accelerating consolidation among integrated processors.
Growth Catalysts
- Specialty café channel expansion:Urban Vietnamese consumers are migrating from street-side condensed-milk coffee to branded espresso-based formats, pulling Arabica demand and supporting premium roast-retail margins in Ho Chi Minh City and Da Nang.
- EU Deforestation Regulation compliance investments:Exporters upgrading geolocation tagging and batch-tracking systems are securing preferential offtake terms with European traders seeking deforestation-free documentation.
- Wet-hulled Robusta process optimization:Mechanical drying and standardized fermentation protocols are reducing defect rates, enabling more consistent cupping scores for commercial-grade lots bound for soluble manufacturing.
Market Restraints
- Input cost volatility:Fertilizer prices, particularly urea and potassium, swing with global energy markets, squeezing smallholder operating margins in Dak Lak and Lam Dong provinces.
- Supply concentration risk:The Central Highlands provinces—Dak Lak, Lam Dong, Gia Lai, and Kon Tum—produce over 90% of national volume, exposing the entire sector to localized drought or pest outbreaks.
- Regulatory friction:Phytosanitary certification delays at Vietnam's General Department of Customs create port congestion during peak harvest windows, eroding freshness premiums.
Strategic Opportunities
- Underpenetrated Mekong Delta:An Giang and Can Tho provinces remain underdeveloped for coffee cultivation despite suitable microclimates, offering greenfield expansion potential for mechanized plantation models.
- Carbon credit monetization:Shade-grown and agroforestry-certified farms can access voluntary carbon markets, creating ancillary revenue streams beyond bean sales.
- Direct-to-roaster digital platforms:Blockchain-enabled traceability tools are enabling Vietnamese exporters to bypass traditional trading houses and contract directly with North American and European specialty roasters.
Industry Challenges
- Q-grader and cupping technician scarcity:Vietnam produces fewer than 200 licensed Q-graders, creating bottlenecks for specialty-grade lot differentiation and export price realization.
- Wet-mill infrastructure capex intensity:Honey and natural processing equipment requires substantial upfront investment, discouraging smallholder adoption despite premium market premiums.
- EU deforestation compliance timeline compression:The December 2024 enforcement deadline for traceability documentation is outpacing smallholder digitization capacity, threatening market access for non-integrated producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Coffee Market |
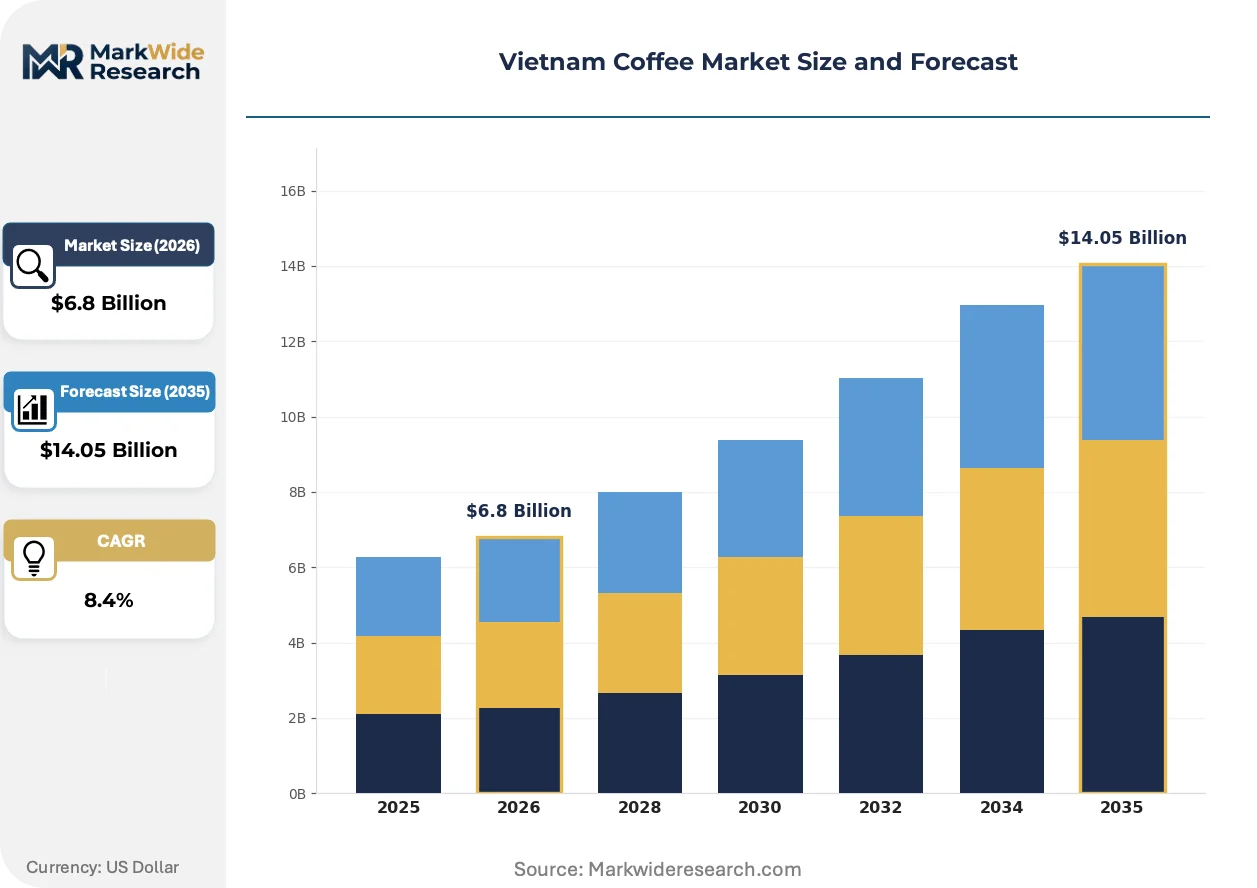
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robusta, Arabica, Excelsa, Liberica Processing Method: Washed, Natural, Honey, Wet-Hulled Distribution Channel: Retail, Wholesale, Online, Food Service Consumer Segment: Household, Cafes, Restaurants, Offices |
| Companies Covered | Trung Nguyên, Nestlé S.A., Vinacafé Bien Hoa Joint Stock Company, Highlands Coffee, Intimex Group, Starbucks Corporation, Masan Group, Anni Coffee, Son Duong Coffee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Coffee Market Strategic Shifts
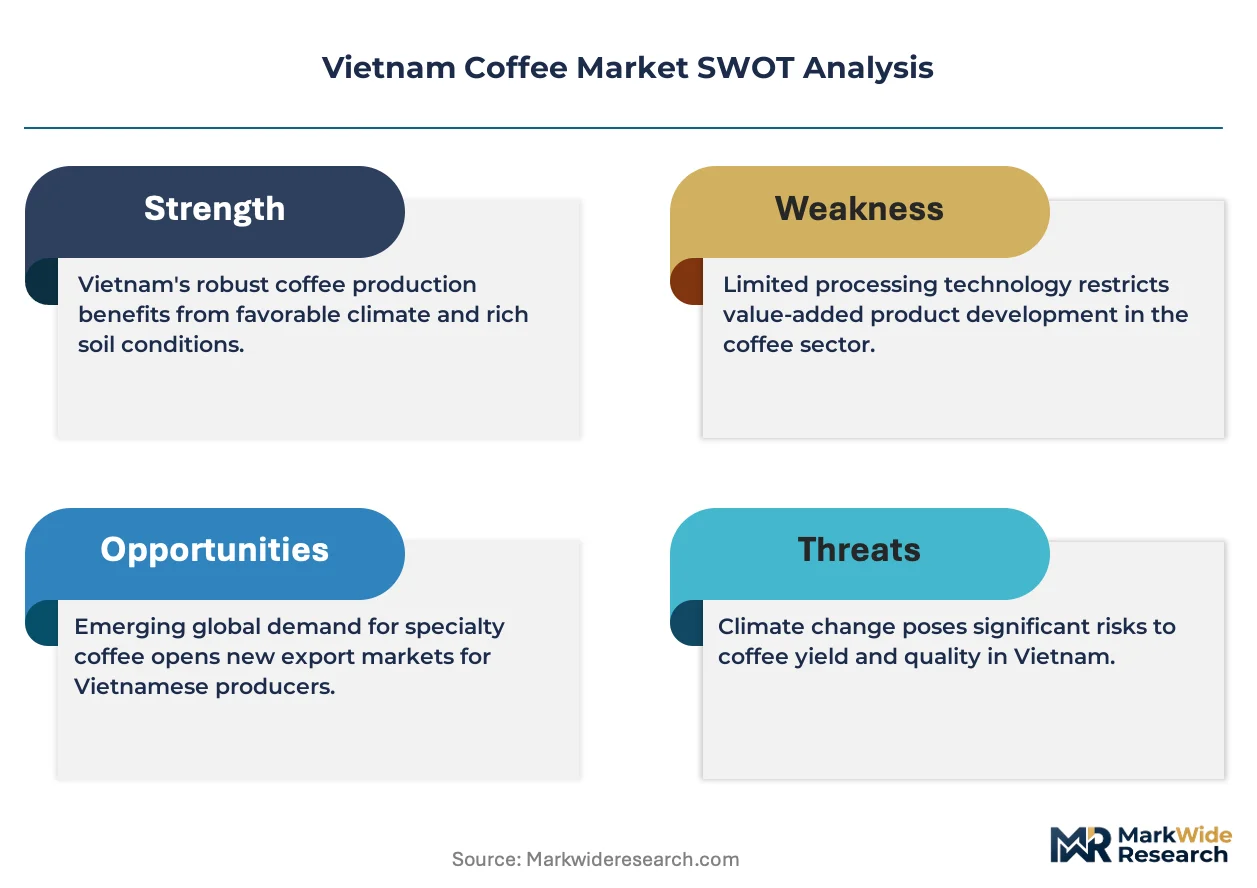
Processing technology, regulatory compliance architecture, and procurement transparency are converging to reshape how Vietnamese coffee moves from cherry to export container, with digitization acting as the common thread across all three domains.
Modular wet-milling equipment is modularizing estate-level processing capabilities. Medium-sized plantations in Lam Dong are adopting containerized pulping and fermentation units that scale from 5 to 50 tons daily. This technology is modularizing the traditional centralized mill model, enabling estate-holders to retain identity-preserved lots and capture traceability premiums previously reserved for cooperative or exporter-controlled channels.
EU Deforestation Regulation traceability mandates are restructuring exporter documentation workflows. The regulation requires geolocation coordinates for every production plot above 4 hectares, with due diligence statements filed before customs release. European-bound Robusta consignments are most affected, with major traders now requiring farm-level GPS tagging and mass-balance segregation from harvest through container stuffing.
Roaster-direct contracting is displacing spot-market procurement for specialty-grade Arabica. North American third-wave roasters are establishing multi-year offtake agreements with Vietnamese honey-processed producers, guaranteeing minimum volumes and quality tiers. This pattern is most visible in the Central Highlands, where pilot projects linking Dalat-area estates to Portland and Melbourne roasters are bypassing traditional Ho Chi Minh City trading floors entirely.
Vietnam Coffee Market Segmentation
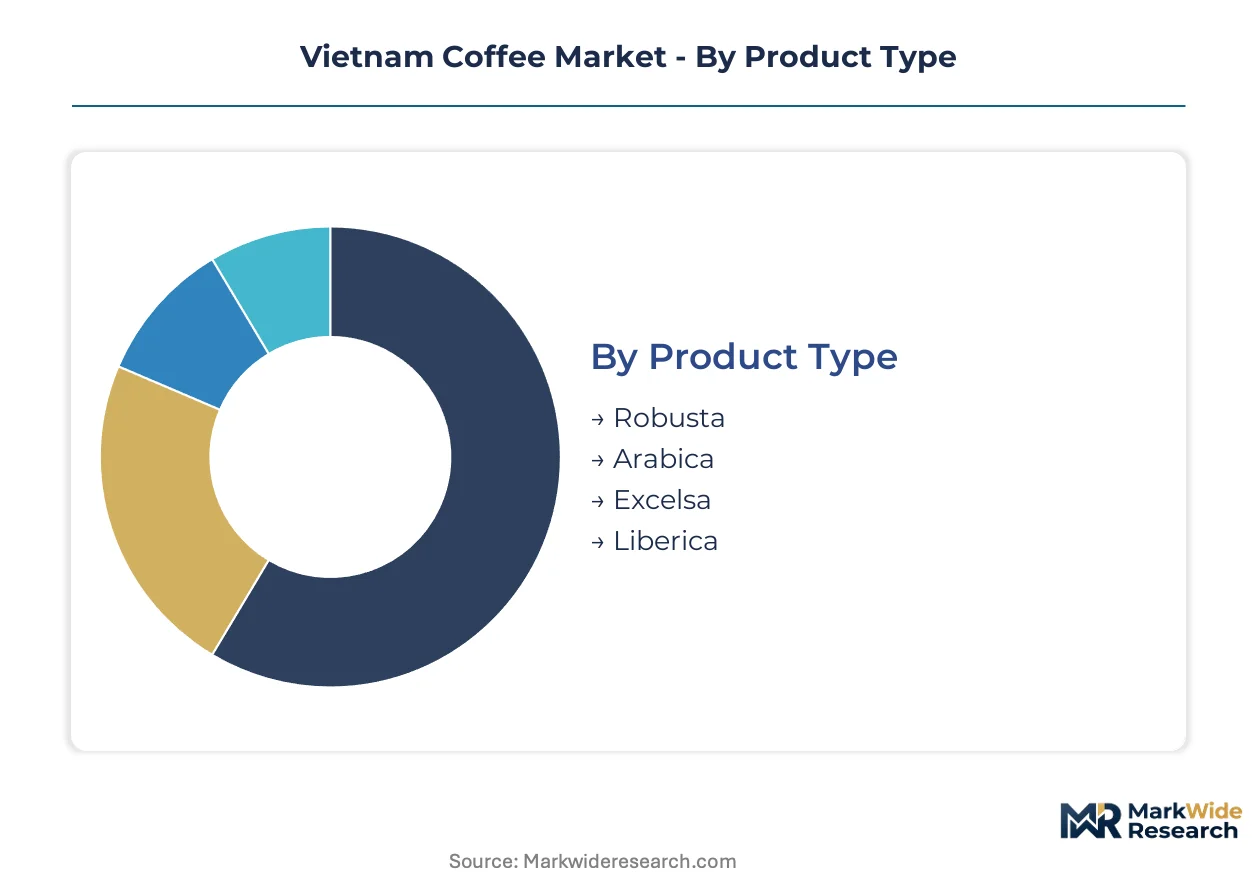
Segmentation in Vietnam's coffee market reveals how processing economics, distribution reach, and end-use specifications fragment procurement strategies across the value chain. Each dimension shapes margin capture differently—from farm-gate processing premiums to channel-specific branding investments.
Product Type:
Buyers differentiate by caffeine content tolerance, roast compatibility, and export market access rather than origin alone.
- Robusta:Higher chlorogenic acid and 2.2–2.7% caffeine content produces the dense crema and bitter backbone essential for Italian-style espresso blends and soluble manufacturing. Dak Lak and Lam Dong provinces supply the bulk of export volumes, with EU traders demanding geolocation-tagged lots to satisfy deforestation-free documentation requirements.
- Arabica:Washed processing yields cleaner acidity and lower caffeine (1.2–1.5%), commanding premium positioning in specialty retail channels across Ho Chi Minh City and Da Nang. Dalat-area estates are contracting directly with North American third-wave roasters, bypassing traditional trading floors through multi-year offtake agreements.
- Excelsa:Tart, fruity cup profile with distinct almond notes finds limited commercial cultivation in Vietnam's Central Highlands due to processing complexity and narrow export demand.
- Liberica:Woody, smoky flavor characteristics and irregular bean size restrict plantings to experimental plots in Gia Lai, with minimal commercial scale.
Robusta leads volumes today; Arabica is gaining share fastest.
Processing Method:
Processing choice determines capital intensity, defect tolerance, and which buyer segments a lot can access.
- Wet-Hulled:Mechanical pulping followed by partial drying and hulling while beans retain 30–40% moisture produces the earthy, heavy-bodied profile dominant in commercial Robusta exports. Lam Dong plantations are adopting containerized units scaling 5–50 tons daily, enabling estate-level identity preservation previously reserved for cooperative channels.
- Honey:Mucilage retention during drying creates sweetness complexity that Portland and Melbourne specialty roasters prize, though mechanical drying equipment demands substantial upfront investment discouraging smallholder adoption.
- Washed:Full fermentation and clean-water rinsing delivers the consistent cupping scores required for European specialty Arabica contracts, concentrated in Dalat-area estates with access to reliable water sources.
- Natural:Whole-cherry sun-drying maximizes fruit-forward notes but risks uneven fermentation; limited to experimental lots targeting niche third-wave markets.
Wet-hulled dominates export tonnage; honey processing is climbing the fastest as roaster-direct contracts expand.
Distribution Channel:
Channel selection dictates working capital cycles, traceability investment recovery, and brand control depth.
- Wholesale:Bulk container sales to European and North American trading houses remain the volume anchor, with EU Deforestation Regulation compliance now requiring farm-level GPS tagging and mass-balance segregation from harvest through stuffing.
- Retail:Branded packaged coffee through supermarkets and specialty stores captures premium margins in urban Vietnamese markets, with Highlands Coffee dominating Ho Chi Minh City shelf space.
- Online:Direct-to-consumer platforms enable small-batch roasters to reach diaspora and specialty buyers, though logistics costs compress margins on sub-container volumes.
- Food Service:Institutional supply contracts for hotels and restaurant chains demand consistent roast profiles and reliable delivery scheduling, favoring integrated processors with captive milling capacity.
Wholesale channels move the most volume; online distribution is expanding most quickly through blockchain-enabled traceability tools.
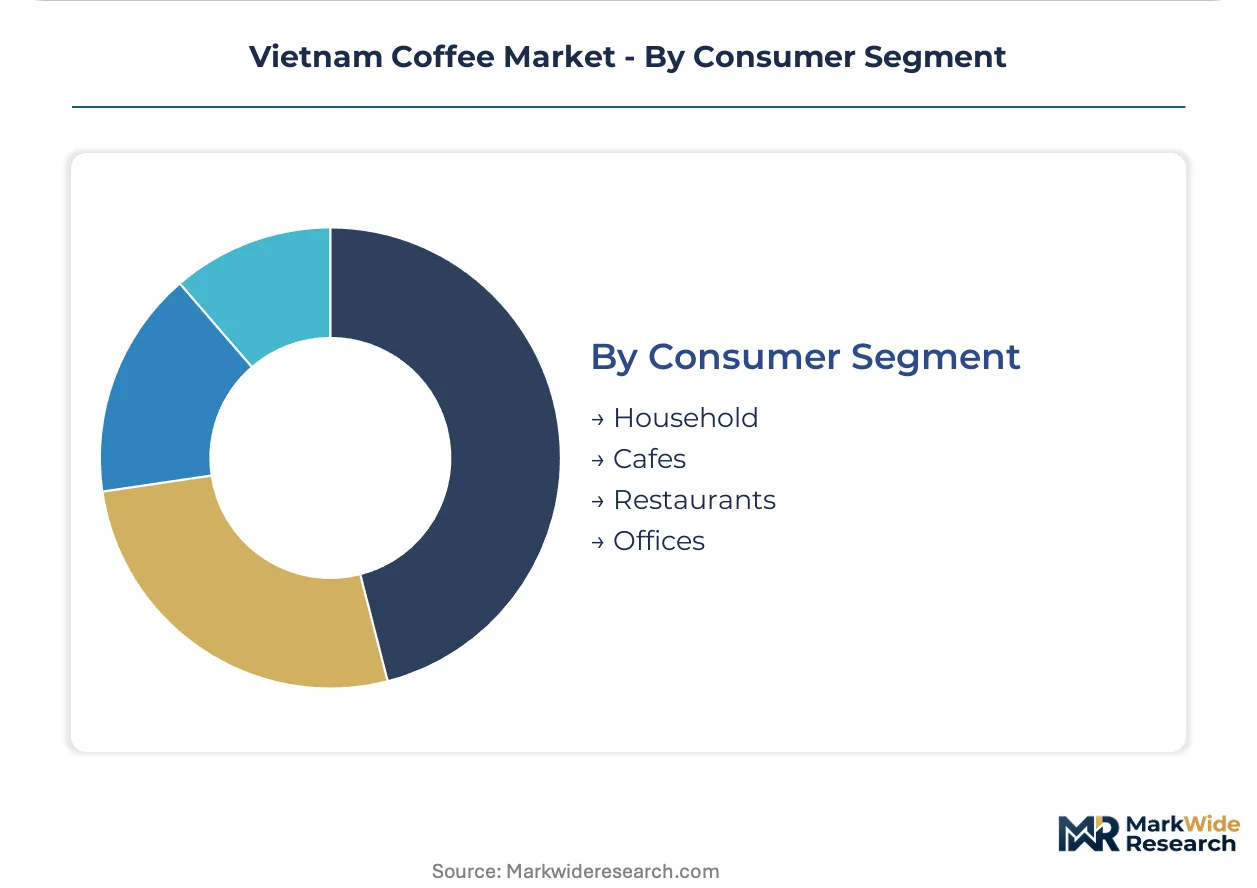
Consumer Segment:
End-use specifications fragment by preparation equipment, service format, and price sensitivity thresholds.
- Cafes:Branded espresso-based formats are displacing street-side condensed-milk coffee in Ho Chi Minh City and Da Nang, pulling Arabica demand and supporting premium roast-retail margins through beverage markup rather than bean sales alone.
- Household:soluble and ground coffee purchases concentrate in urban centers, with Nestlé sustaining large-scale operations through centralized processing hubs serving mass-market price points.
- Restaurants:post-meal coffee service demands consistent quality at controlled cost, typically sourcing through wholesale distributors rather than direct estate relationships.
- Offices:automated vending and capsule systems favor soluble and pre-ground formats, with procurement decisions driven by equipment supplier partnerships rather than origin traceability.
Cafe channel volumes lead today; household specialty migration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Highlands provinces anchor Vietnam's coffee production concentration, with Dak Lak, Lam Dong, Gia Lai, and Kon Tum generating over ninety percent of national output through estate and smallholder cultivation systems.
Dak Lak Province
Robusta cultivation dominates Dak Lak's agricultural economy, with Buon Ma Thuot city serving as the primary collection and processing hub for export-bound volumes. The Ministry of Agriculture and Rural Development operates quality certification stations here to enforce phytosanitary standards for European-bound consignments. Estate holders around Lak Lake are deploying containerized wet-milling units to retain identity-preserved lots and capture traceability premiums.
Lam Dong Province
Arabica production concentrates in Lam Dong's cooler highland microclimates, with Dalat-area estates contracting directly with North American specialty roasters. The province's Department of Agriculture promotes honey-processed coffee adoption through technical extension programs targeting medium-sized plantations. Da Lat city hosts Vietnam's highest concentration of Q-grader training facilities, though licensed technician scarcity persists.
Gia Lai Province
Robusta expansion in Gia Lai follows mechanized plantation models that reduce labor dependency during harvest windows. Provincial authorities coordinate with the General Department of Customs to streamline traceability documentation for EU Deforestation Regulation compliance. Pleiku city functions as a secondary processing center for volumes diverted from Dak Lak during peak season congestion.
Kon Tum Province
Kon Tum remains the least developed Central Highlands coffee province, offering greenfield expansion potential for integrated estate development. The Ministry of Agriculture and Rural Development designates portions of the province for agroforestry pilot programs that qualify for voluntary carbon credit markets. Smallholder cooperatives along the border with Laos are experimenting with natural processing methods for niche third-wave export contracts.
Ho Chi Minh City
Ho Chi Minh City concentrates domestic consumption demand and export logistics coordination for the entire Central Highlands production base. The city's branded café chains—Highlands Coffee, Trung Nguyên, and international entrants—are displacing street-side condensed-milk coffee culture with espresso-based formats. Port facilities at Cat Lai handle the majority of container stuffing for European and North American bound shipments, with mass-balance segregation now mandatory for deforestation-free documentation.
Vietnam Coffee Market Competitive Environment
Global majors compete with regional champions across procurement networks and retail channel access in Vietnam's coffee sector. The market structure tiers between integrated plantation-to-retail conglomerates, multinational soluble processors, and domestic café chain operators. Three archetypes dominate: captive estate holders controlling upstream supply, centralized processing specialists serving export commodity markets, and urban retail brands capturing domestic consumption premiums. Competitive moves concentrate on backward integration into plantation assets and blockchain-enabled traceability investments that secure EU market access.
Within the integrated plantation tier, Trung Nguyên leverages its captive estate network across the Central Highlands to secure Robusta volumes for domestic roasting and retail distribution. Nestlé S.A. exemplifies the multinational processing archetype through large-scale soluble coffee operations serving mass-market price points across Southeast Asia. Highlands Coffee anchors the urban retail channel, dominating branded café presence in Ho Chi Minh City and Da Nang while sourcing through contracted estate relationships rather than spot markets.
| Leading Market Players |
|---|
| Trung Nguyên |
| Nestlé S.A. |
| Vinacafé Bien Hoa Joint Stock Company |
| Highlands Coffee |
| Intimex Group |
| Starbucks Corporation |
| Masan Group |
| Anni Coffee |
| Son Duong Coffee |
| Others |
Value Chain & Pricing Dynamics
European specialty roasters and soluble manufacturers anchor pricing power in Vietnam's coffee market, compressing farm-gate margins while rewarding exporters who deliver geolocation-tagged lots compliant with EU Deforestation Regulation requirements.
Pricing Analysis
Input-cost pass-through from fertilizer and energy markets shapes contract structures across the value chain. Pricing stratifies across premium honey-processed Arabica, standard washed Robusta, and economy-grade wet-hulled commercial lots. Arabica premiums widen against Robusta as Dalat-area estates secure multi-year offtake agreements with North American roasters. Smallholders in Dak Lak face acute price sensitivity due to limited bargaining power against consolidated exporters.
Supply Chain Analysis
Warehouse-distribution layers concentrate through Ho Chi Minh City's Cat Lai port facilities, where mass-balance segregation for EU-bound containers occurs. Supply draws from the Central Highlands provinces—Dak Lak, Lam Dong, Gia Lai, and Kon Tum—with over ninety percent of national output. Dependency on imported urea and potassium fertilizers creates exposure to global energy price swings. Single-source vulnerability concentrates in wet-mill infrastructure, where mechanical drying capacity shortages bottleneck honey-processed volume expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's coffee market functions as a geographic-arbitrage play where Central Highlands production costs undercut Brazilian and Colombian origins while EU regulatory compliance investments create entry barriers against untraceable competitors.
For Market Incumbents: Anchor market position through backward integration into Lam Dong and Dak Lak plantation assets, securing captive Robusta supply against Nestlé's soluble manufacturing scale. Invest in blockchain-enabled traceability infrastructure to preempt EU Deforestation Regulation enforcement gaps. Control wet-mill capacity expansion to limit specialty-grade Arabica supply flooding from emerging Dalat-area competitors.
For New Entrants and Emerging Players: Direct-to-roaster digital platforms offer the lowest-friction entry path, bypassing Ho Chi Minh City trading floors to contract with Portland and Melbourne specialty roasters. Target honey-processed Arabica from underdeveloped Kon Tum cooperatives, where agroforestry certification unlocks carbon credit revenue streams. Deploy containerized wet-milling units to retain identity-preserved lots and capture traceability premiums previously reserved for estate holders.
For Investors and Strategic Acquirers: Integrated plantation-to-export conglomerates are the most active acquirer in this space, consolidating fragmented smallholder supply through cooperative buyouts. The five-to-ten year viability window favors targets with existing EU Deforestation Regulation compliance infrastructure and licensed Q-grader capacity. Monitor geolocation tagging adoption rates among Central Highlands cooperatives as the inflection indicator for smallholder market access contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Trung Nguyên's captive estate network secures Robusta supply against volatile spot markets. |
| Blockchain-Enabled Traceability Investment | EU Deforestation Regulation compliance creates preferential offtake terms with European traders. |
| Q-Grader Training Program Expansion | Dalat-area facilities address technician scarcity bottlenecks for specialty-grade lot differentiation. |
| Honey Processing Equipment Deployment | Mechanical drying adoption unlocks premium contracts with North American third-wave roasters. |
| Carbon Credit Monetization Program | Agroforestry-certified farms in Kon Tum access voluntary carbon markets beyond bean sales. |
Study Parameters
Direct dialogue with plantation estate managers, cooperative leaders, export trading house procurement directors, and Ministry of Agriculture extension officers grounded qualitative findings. Secondary validation drew from Vietnam General Department of Customs trade statistics, EU Deforestation Regulation implementation guidance, ICO production databases, and Central Highlands provincial agricultural reports. Bottom-up volume estimates from estate-level yield data triangulated against top-down export flow analysis.
Top-down macroeconomic drivers and bottom-up segment economics converged across the analysis window. Segmentation modeling incorporated product type, processing method, distribution channel, and consumer segment dimensions. CAGRs derived from historical export volume trajectories, urban café channel expansion rates, and regulatory compliance investment cycles. Forecast inputs included fertilizer price volatility indices and EU traceability infrastructure deployment timelines.
Weather-induced yield shocks, regulatory enforcement timeline acceleration, and specialty roaster demand migration to alternative origins are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Global Automatic Coffee Machines Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Germany Coffee Market
Coffee
Take Out Coffee Market
Coffee
Coffee Extracts Market
Coffee
Decaffeinated Coffee Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Global Cafe Market
Coffee
Raw Coffee Beans Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
Smart Coffee Maker Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Drip Coffee Machine Market