
 Single Origin Coffee Market | 2026-2036
Single Origin Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Single Origin Coffee Market Analytics
Single-serve pod unbundling is restructuring how consumers access origin-specific coffees, shifting purchases from café experiences to at-home brewing systems. Starbucks Corporation leverages its Reserve program to sustain direct-trade relationships with specific estates. Blue Bottle Coffee anchors its brand identity on micro-lot transparency and roast-date freshness. Intelligentsia Coffee competes through its in-house sourcing operation and barista training infrastructure.
Single origin coffee denotes beans harvested from one geographic location, processed without blending, with cupping scores typically exceeding 80 points on the Specialty Coffee Association scale to qualify as specialty grade. Its primary commercial purpose is to command traceability premiums through terroir documentation and farm-level storytelling. Whole bean formats dominate margin pools as grinding-at-home preserves volatile aromatic compounds that degrade within minutes of milling. Washed processing leads volume in East African origins while natural processing grows fastest among Brazilian and Ethiopian lots seeking fruit-forward cup profiles. Online retail channels expand fastest for subscription-based direct trade, though specialty stores retain the highest per-transaction value through guided tastings and equipment bundling.
The FDA enforces pesticide residue thresholds under the Federal Food, Drug, and Cosmetic Act for green coffee imports entering the United States. The EU Green Deal and EUDR deforestation regulation mandate geolocation verification and supply chain due diligence for coffee sold in European markets. Organic certification under USDA and EU organic frameworks shapes farm-level input protocols and export eligibility. Stakeholders must monitor how emerging carbon accounting standards and living wage benchmarks reshape origin sourcing decisions and price negotiation frameworks.
Market Dynamics
The EU Green Deal and EUDR deforestation regulations are compressing sourcing timelines for European-bound lots, forcing roasters to build geolocation-verified supply chains before the compliance deadline.
Growth Catalysts
- Third-wave café expansion:Specialty coffee shops in urban centers across Germany, Japan, and Australia are building direct-trade relationships with specific estates, creating guaranteed offtake for micro-lot producers.
- EUDR compliance infrastructure:The EU Green Deal's geolocation verification mandate is accelerating investment in farm-level traceability systems, locking in premium pricing for compliant origins.
- Natural processing innovation:Controlled fermentation protocols in Ethiopian and Brazilian wet mills are expanding the addressable market for fruit-forward cup profiles among home brewers.
Market Restraints
- Arabica price volatility:Futures contracts on the Intercontinental Exchange expose small-scale importers to margin compression when certified stocks tighten.
- Origin concentration risk:Washed Ethiopian Yirgacheffe and Colombian Huila lots dominate high-scoring auction channels, creating supply bottlenecks during harvest delays.
- Substitution by commodity blends:Roasters facing input cost pressure can downgrade to certified commercial grades without losing USDA organic claims.
Strategic Opportunities
- Underpenetrated Indonesian archipelago:Sulawesi Toraja and Flores estates lack the traceability infrastructure of Central American origins, presenting first-mover advantages for direct-trade investors.
- Carbon accounting integration:Emerging voluntary carbon markets are creating price premiums for farms with verified agroforestry shade coverage and soil carbon sequestration protocols.
- Subscription channel maturation:Direct-to-consumer platforms are displacing traditional import-export margins, allowing roasters to capture lifetime value through recurring revenue models.
Industry Challenges
- Q-grader certification scarcity:The Specialty Coffee Association's licensed cupping professional pipeline constrains quality control scaling for rapidly growing micro-lot portfolios.
- Living wage verification complexity:Farmgate price transparency requirements under emerging EU due diligence frameworks demand payroll audit capabilities that most small importers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Origin Coffee Market |
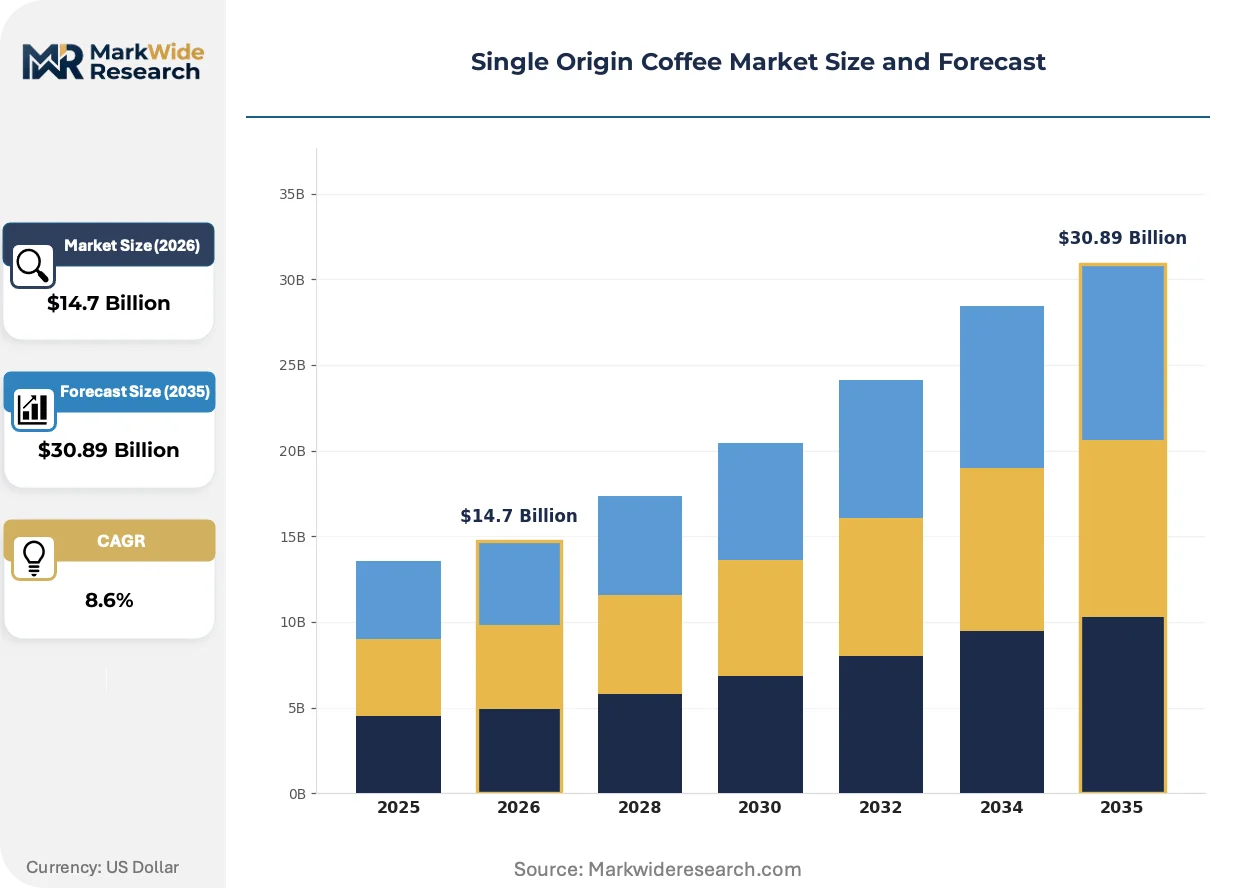
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Bean, Ground Coffee, Pods, Instant Coffee Processing Method: Washed, Natural, Honey, Semi-Washed Packing Type: Bag, Canister, Box, Bulk Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Coffee Shops |
| Companies Covered | Starbucks Corporation, Keurig Dr Pepper Inc., The Kraft Heinz Company, Luigi Lavazza S.p.A, Peet’s Coffee, Intelligentsia Coffee, Stumptown Coffee Roasters, Blue Bottle Coffee, Onyx Coffee Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Origin Coffee Market Evolving Landscape
Processing technology, regulatory compliance infrastructure, and at-home consumption formats are converging to restructure how provenance documentation translates to consumer willingness-to-pay.
Near-infrared spectroscopy is automating green coffee grading at origin, replacing manual defect sorting with spectral fingerprinting that identifies moisture content, density, and fermentation markers in seconds. Large Brazilian cooperatives and Colombian federations are deploying portable units at receiving stations during peak harvest windows. This compression of quality assessment timelines is automating the pre-export sorting pipeline, reducing cupping labor costs and accelerating lot segregation.
The EU Green Deal's deforestation-free supply chain regulation is mandating polygon-level geolocation data for every farm plot supplying European markets, with full traceability required by the enforcement date. Roasters must now integrate satellite verification and chain-of-custody documentation into their ERP systems. East African cooperatives and Central American exporter associations are the most exposed, scrambling to digitize farm boundary records ahead of customs inspections.
Home espresso system penetration is fragmenting the café-dependent discovery model that built single-origin demand, with consumers now accessing traceable lots through capsule-compatible formats and precision grinder-brewer bundles. Specialty roasters are responding with roast-date-guaranteed subscription tiers and brewing parameter cards. This channel rotation is most visible in South Korean and Australian metropolitan markets, where apartment-sized equipment dominates kitchen counter space.
Single Origin Coffee Market Segmentation
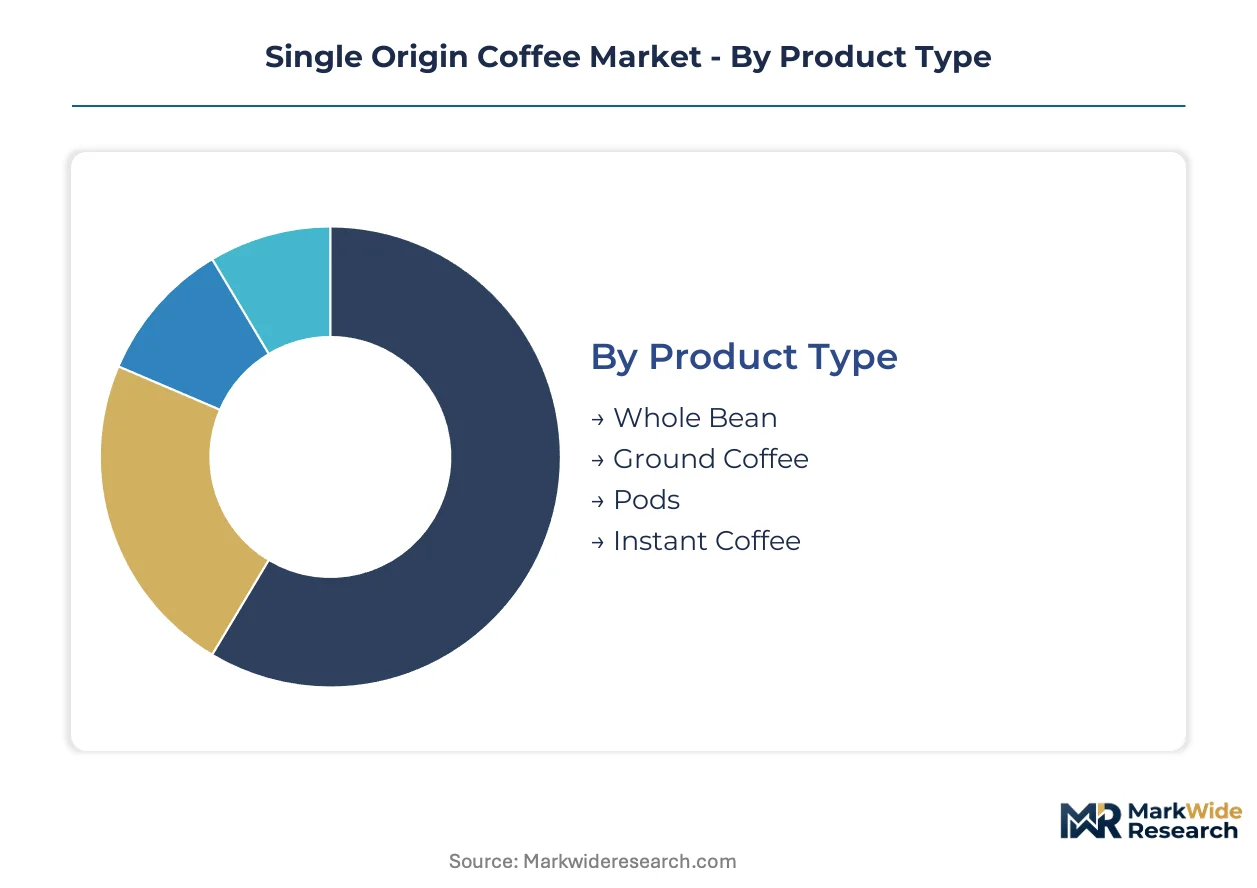
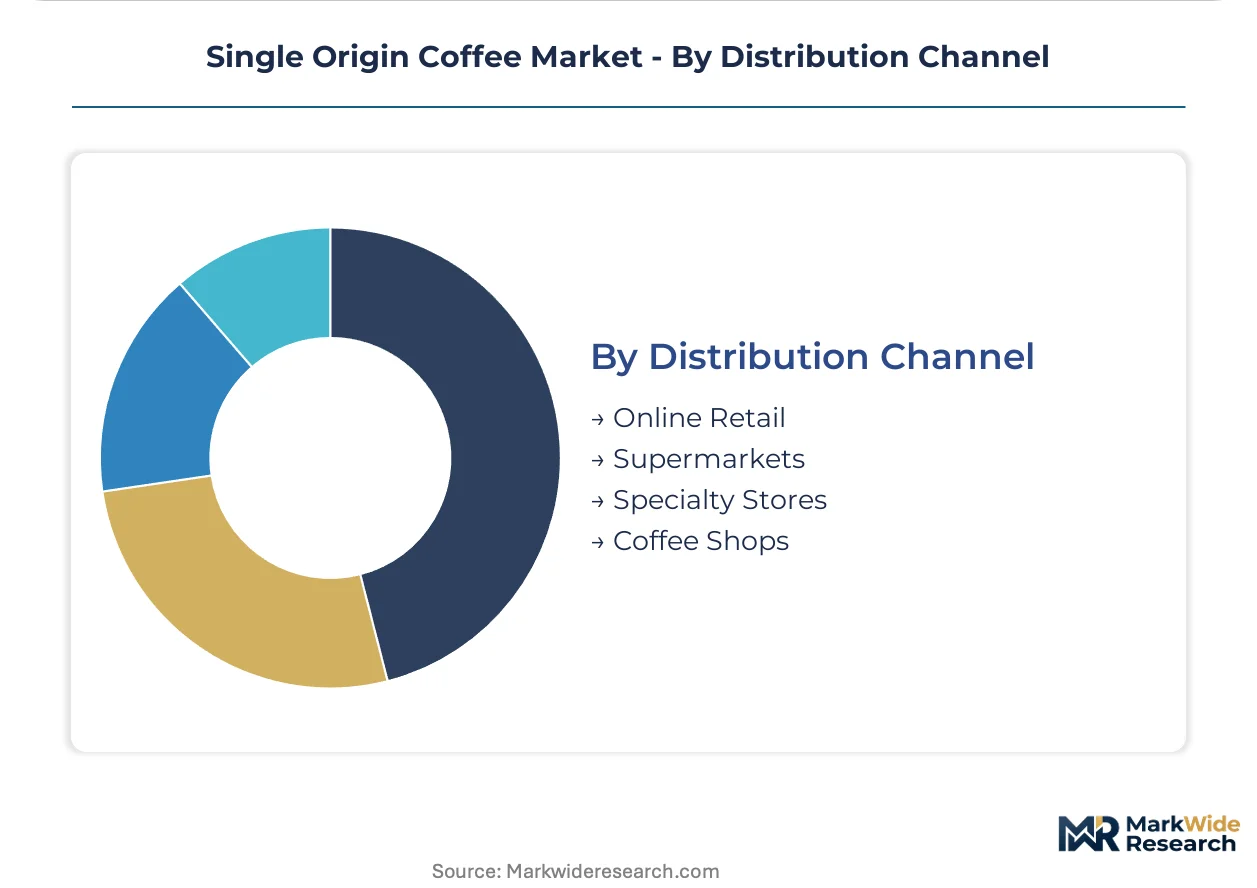
Segmentation in single origin coffee separates volume pools from margin capture. Format and channel choices determine whether producers retain traceability premiums or surrender them to intermediaries.
Product Type:
Buyers choose format based on equipment ownership and freshness priorities, with grinding behavior the decisive split.
- Whole Bean:Unmilled beans preserve volatile aromatic oils that oxidize within minutes of grinding. Specialty roasters in Germany, Japan, and Australia concentrate procurement here, as home grinder penetration climbs in metropolitan markets.
- Ground Coffee:Pre-milled formats sacrifice cup quality for convenience, dominating subscription services targeting entry-level single-origin buyers. Roasters offset margin compression through volume commitments and automated packaging lines.
- Pods:Single-serve capsules fragment café-dependent discovery into at-home brewing, with South Korean and Australian consumers driving compatibility demand for precision equipment.
- Instant Coffee:Spray-dried and freeze-dried extracts occupy the lowest tier, lacking terroir documentation and commanding commodity pricing regardless of origin claims.
Volume sits with Ground Coffee; growth tilts toward Pods.
Processing Method:
Processing protocol selection determines flavor profile and export eligibility under emerging EU due diligence frameworks.
- Washed:Depulped and fermented parchment dries with minimal fruit contact, producing clean cup profiles that dominate East African export grades. Ethiopian cooperatives and Colombian federations standardize on this method for European specialty buyers.
- Natural:Whole cherry drying intensifies fruit sugars and berry notes, with Brazilian and Ethiopian mills expanding controlled fermentation protocols to meet home-brewer demand for adventurous cup profiles.
- Honey:Mucilage-retained parchment creates intermediate sweetness between washed clarity and natural intensity, gaining traction among Central American micro-lot producers seeking differentiation.
- Semi-Washed:Mechanical demucilaging shortcuts fermentation time, reducing water consumption but limiting cup complexity; Brazilian cooperatives deploy this for volume lots.
Volume concentrates in Washed; Natural processing climbs the fastest.
Packing Type:
Packaging format signals freshness commitment and determines retail placement access.
- Bag:Multi-layer laminate with one-way degassing valves dominates specialty retail, preserving volatile aromatics during the critical post-roast off-gassing period.
- Canister:Rigid metal or composite containers command gift-tier pricing and extend shelf stability for infrequent brewers.
- Box:Folding carton formats accommodate pod assortments and subscription sampling programs.
- Bulk:Food-service sacks supply roasting operations and café chains with green or roasted volume, bypassing consumer packaging costs entirely.
Bag formats anchor revenue; Bulk captures roast-house procurement.
Distribution Channel:
Channel selection determines traceability premium retention and customer acquisition economics.
- Online Retail:Direct-to-consumer platforms displace import-export margins, allowing roasters to capture lifetime value through subscription tiers with roast-date guarantees and brewing parameter cards.
- Supermarkets:Mass retail placement sacrifices provenance storytelling for volume velocity, with private-label single-origin lines compressing specialty margins.
- Specialty Stores:Guided tastings and equipment bundling sustain the highest per-transaction value, though footprint constraints limit geographic reach.
- Coffee Shops:Third-wave cafés in urban centers build direct-trade relationships with specific estates, creating guaranteed offtake for micro-lot producers.
Supermarkets move the most units; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethiopia and Colombia harvest the majority of certified single-origin arabica, while Germany, Japan, and the United States absorb the highest premiums for traceable micro-lots. This geographic split forces roasters to manage origin risk against consumer willingness-to-pay for provenance documentation.
United States
Specialty roasters in Portland, Seattle, and Brooklyn drive direct-trade procurement for auction-grade Ethiopian and Colombian lots. The FDA enforces pesticide residue thresholds under the Federal Food, Drug, and Cosmetic Act for all green coffee imports. Third-wave cafés in Los Angeles and Austin anchor equipment bundling strategies that sustain the highest per-transaction values in domestic retail.
Germany
Berlin and Hamburg host Europe's densest concentration of micro-roasters seeking EUDR-compliant supply chains ahead of enforcement deadlines. The EU Green Deal mandates polygon-level geolocation verification for every farm plot supplying European markets. Munich-based importers are digitizing chain-of-custody documentation to lock in premium pricing for compliant East African origins.
Japan
Tokyo and Osaka consumers command cupping scores above 85 points for single-origin lots, driving precision-focused procurement from Yirgacheffe and Huila micro-regions. METI oversees food labeling standards that require origin specificity beyond country-level claims. Specialty shops in Fukuoka and Sapporo are expanding hand-drip bar infrastructure to differentiate guided tasting experiences.
Australia
Melbourne and Sydney roasters pioneered subscription-based direct trade, now displacing traditional import-export margins through recurring revenue models. The country's national food standards regulator enforces truth-in-labeling requirements for origin claims. Home espresso penetration in Brisbane and Perth is fragmenting café-dependent discovery into at-home capsule-compatible formats.
South Korea
Seoul's apartment-dwelling consumers drive fastest adoption of precision grinder-brewer bundles for single-origin brewing. The MFDS monitors food import safety for green coffee entering through Busan port. Specialty roasters in Gangnam and Hongdae districts are deploying roast-date-guaranteed subscription tiers with brewing parameter cards to capture lifetime value.
Single Origin Coffee Market Competitive Landscape
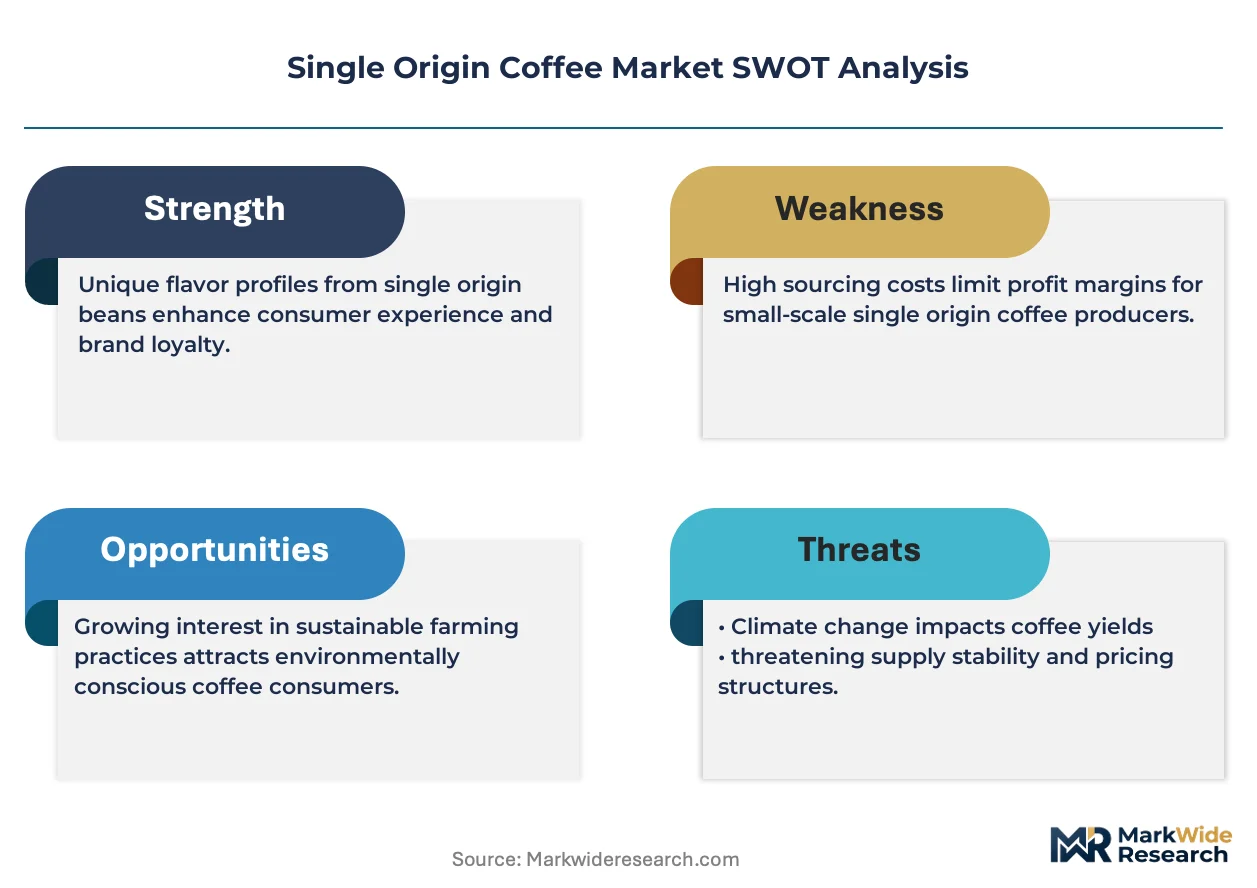
Diversified conglomerates compete with focused pure-play specialists across a fragmented vendor base. Starbucks Corporation and Keurig Dr Pepper Inc. leverage global distribution infrastructure and brand recognition to secure shelf placement, while Intelligentsia Coffee and Blue Bottle Coffee anchor premium positioning through direct-trade relationships and micro-lot transparency. Three archetypes dominate: multinational beverage conglomerates with coffee divisions, regional roasting chains with subscription platforms, and estate-linked micro-roasters with single-origin depth. Competitive moves concentrate on EUDR compliance infrastructure investment and backward integration into origin sourcing operations.
Among multinational beverage conglomerates, Starbucks Corporation and Keurig Dr Pepper Inc. exemplify scale-driven market presence through diversified retail and at-home format portfolios. Within the pure-play specialty tier, Blue Bottle Coffee and Intelligentsia Coffee occupy positions defined by in-house sourcing operations and barista training infrastructure. Stumptown Coffee Roasters represents the regional chain archetype with direct-trade depth and subscription channel maturation. These named entities illustrate how competitive positioning splits between volume velocity and traceability premium capture.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Keurig Dr Pepper Inc. |
| The Kraft Heinz Company |
| Luigi Lavazza S.p.A |
| Peet's Coffee |
| Intelligentsia Coffee |
| Stumptown Coffee Roasters |
| Blue Bottle Coffee |
| Onyx Coffee Lab |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty roasters anchor supply discipline through centralized green coffee procurement desks, compressing farmgate-to-retail spreads while enforcing lot segregation standards that preserve traceability premiums. Their ownership concentration funnels working capital into EUDR-compliant origin infrastructure, locking in first-mover pricing power before compliance deadlines reshape competitive access.
Pricing Analysis
Margin tightening in micro-lot tiers reflects Arabica futures volatility on the Intercontinental Exchange and the cost of geolocation verification systems mandated by EU Green Deal enforcement. Three-tier pricing structure across auction-grade, certified specialty, and commercial organic levels separates cupping scores above 85 points from 80-84 point lots and undifferentiated commodity grades. Cost-down pressure on washed Ethiopian and Colombian origins accelerates because roasters must absorb polygon-mapping expenses without passing full tariffs to price-sensitive subscription buyers. Home brewers in South Korea and Australia show least price sensitivity, while supermarket private-label buyers in Germany compress premiums to parity with commodity blends.
Supply Chain Analysis
Regional distribution centers in Hamburg, Tokyo, and Melbourne consolidate containerized green coffee arrivals before hub-and-spoke dispatch to micro-roasters and subscription fulfillment operations. Supply concentrates in Ethiopia, Colombia, and Guatemala for auction-grade arabica, with Brazilian cooperatives feeding volume lots into semi-washed and natural processing channels. Farm-level dependencies on seasonal picker labor, fermentation tank capacity, and moisture-controlled drying patios create harvest-window bottlenecks. Single-source vulnerability intensifies when Ethiopian cooperatives face delayed rainfall or Colombian federations encounter social unrest in Huila micro-regions. Distribution runs through direct-trade relationships for specialty tiers and commodity brokers for commercial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy at receiving stations is replacing manual defect sorting, compressing quality assessment timelines and automating lot segregation before export.
For Market Incumbents: Acquire Q-grader certification pipelines and in-house cupping infrastructure to defend micro-lot portfolio scaling against emerging roasters with automated grading. Lock EUDR-compliant supply chains through backward integration into Ethiopian cooperative digitization projects and Colombian farm boundary mapping. Certify existing direct-trade relationships under emerging living wage audit frameworks before EU due diligence enforcement creates compliance bottlenecks. For New Entrants and Emerging Players: Enter via Indonesian archipelago origins—Sulawesi Toraja and Flores estates lack traceability infrastructure of Central American competitors, presenting first-mover advantages for geolocation-verified supply chain construction. Target carbon accounting integration as the most penetrable premium mechanism, leveraging voluntary carbon markets for agroforestry shade coverage verification. Deploy subscription-native platforms with roast-date guarantees and brewing parameter cards to bypass traditional import-export margin capture. For Investors and Strategic Acquirers: EUDR enforcement date acceleration is the leading indicator that compliant origin infrastructure will command scarcity premiums over the next decade. Target estate-linked micro-roasters with single-origin depth and existing polygon-verified supply chains as acquisition archetypes. Monitor Specialty Coffee Association Q-grader certification waitlist expansion as the signal that quality control scaling constraints are tightening competitive access to auction channels.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Compliance Infrastructure Investment | Polygon-level geolocation verification secures European market access before enforcement deadlines. |
| Backward Integration into Origin Sourcing | Direct-trade relationships with Ethiopian cooperatives lock in micro-lot offtake and traceability premiums. |
| Near-Infrared Spectroscopy Deployment | Automated green coffee grading at Colombian and Brazilian receiving stations reduces cupping labor costs. |
| Subscription Channel Maturation | Recurring revenue models in Australian and South Korean markets displace traditional import-export margins. |
| Carbon Accounting Integration | Verified agroforestry shade coverage creates price premiums through voluntary carbon market participation. |
Research Methodology
Independent corroboration across green coffee importers, micro-roaster operations directors, and EU regulatory compliance officers underwrites the qualitative findings on EUDR implementation timelines. Primary interviews with Ethiopian cooperative managers, Colombian federation export leads, and specialty café procurement heads in Berlin, Tokyo, and Melbourne combined with secondary validation from customs records, ICO trade statistics, and SEC filings of publicly traded roasters. Bottom-up lot-level volume aggregation and top-down channel revenue estimates triangulate market sizing.
Rate-of-change decomposition across the analysis window separates volume growth in subscription channels from value capture in micro-lot tiers, with CAGRs derived from segment-level growth rate reconciliation. Segmentation dimensions modeled include product format, processing method, packaging type, and distribution channel, with origin-specific regulatory compliance status as an industry-specific overlay. Forecast inputs incorporate Arabica futures curve shapes and EU Green Deal enforcement phase-in assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Arabica price spikes, harvest failures in Yirgacheffe or Huila regions, or accelerated EU due diligence payroll audit requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Decaffeinated Coffee Market
Coffee
Coffee Fruit Extract Market
Coffee
Italy Coffee Market
Coffee
Global Coffee Machine Market
Coffee
Cold Brew Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Capsules Market
Coffee
Reusable Coffee Cup Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Take Out Coffee Market
Coffee
Cold Brew Coffee Pots Market
Coffee
North America Coffee Market
Coffee
Coffee Grinder Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Global Portable Coffee Makers Market