
 Cod Liver Oil Market | 2026-2036
Cod Liver Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Cod Liver Oil Market Analysis
The cod liver oil category is pivoting between pharmaceutical-grade molecular distillates and unrefined traditional oils. Nordic Naturals Inc. leverages pharmaceutical-grade purification infrastructure to command premium shelf positioning. LYSI Iceland anchors its supply through North Atlantic fishery partnerships and vertically integrated rendering operations. NOW Health Group Inc. competes on volume throughput across softgel and liquid formats in North American retail channels.
Cod liver oil is the rendered lipid extracted from Gadus morhua liver tissue, typically containing 800–1,200 IU vitamin D and 3,000–5,000 IU vitamin A per teaspoon, with EPA and DHA omega-3 fatty acids comprising 15–25% of total lipids; manufacturers cold-press or molecularly distill the raw material for pharmaceutical, nutraceutical, and cosmetic applications. Liquid formulations retain the highest absolute volume share due to institutional and traditional consumer loyalty, while softgel capsules capture faster growth through pharmacy and online retail channels where unit-dose convenience drives repeat purchase behavior. Emulsion formats occupy a narrower but defensible niche in pediatric and geriatric applications where palatability governs compliance.
Norway's Mattilsynet food safety authority and the EU's EFSA enforce maximum vitamin A and contaminant thresholds that determine which refining processes qualify for human consumption labeling. The US FDA and EPA jointly regulate fish oil supplements through Good Manufacturing Practice mandates and marine pollutant screening protocols. Stakeholders must monitor tightening heavy metal limits in the EU and evolving USP monograph revisions that could disqualify unrefined products from pharmacy distribution.
Market Dynamics
The cod liver oil market pivots on tightening EU contaminant thresholds that are disqualifying unrefined cold-pressed oils from pharmacy distribution, forcing manufacturers toward molecular distillation infrastructure and pharmaceutical-grade certification pathways.
Growth Catalysts
- EFSA vitamin thresholds:The EU's updated maximum vitamin A limits are accelerating reformulation toward standardized potency grades that command premium positioning in German and Norwegian retail channels.
- Triglyceride-form omega-3 preference:Consumer demand for re-esterified triglyceride molecular structures is electrifying investment in enzymatic re-esterification equipment among North Atlantic processors.
- Scandinavian coastal processing zones:Concentrated rendering infrastructure in Iceland and Norway enables integrated supply chains from catch to capsule, compressing lead times for softgel manufacturers.
Market Restraints
- Raw material volatility:North Atlantic Gadus morhua quotas fluctuate with ICES stock assessments, creating input cost uncertainty for unintegrated renderers.
- Heavy metal accumulation:Bioaccumulation of mercury and PCBs in liver tissue requires expensive adsorption or molecular distillation, raising minimum viable scale for human-grade production.
- Plant-based omega-3 substitution:Algal DHA and EPA isolates from Schizochytrium fermentation are capturing vegan-formulation contracts in cosmetic and pediatric segments.
Strategic Opportunities
- Pediatric emulsion formats:Palatability-engineered emulsions for children represent underdeveloped white space where compliance rates govern prescription renewals.
- EU Green Deal biowaste protocols:Incentives for marine byproduct valorization are redirecting fishmeal processors toward pharmaceutical-grade liver oil extraction.
- Direct-to-consumer pharmacy channels:Unit-dose subscription models bypass traditional wholesale markups, capturing repeat purchase behavior in urban Nordic markets.
Industry Challenges
- Pharmaceutical-grade certification timelines:USP monograph compliance and EDQM CEP documentation require 18-24 month validation cycles that delay market entry.
- Skilled rendering technician scarcity:Molecular distillation operation and GMP cleanroom protocols demand specialized training unavailable in coastal fishing communities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cod Liver Oil Market |
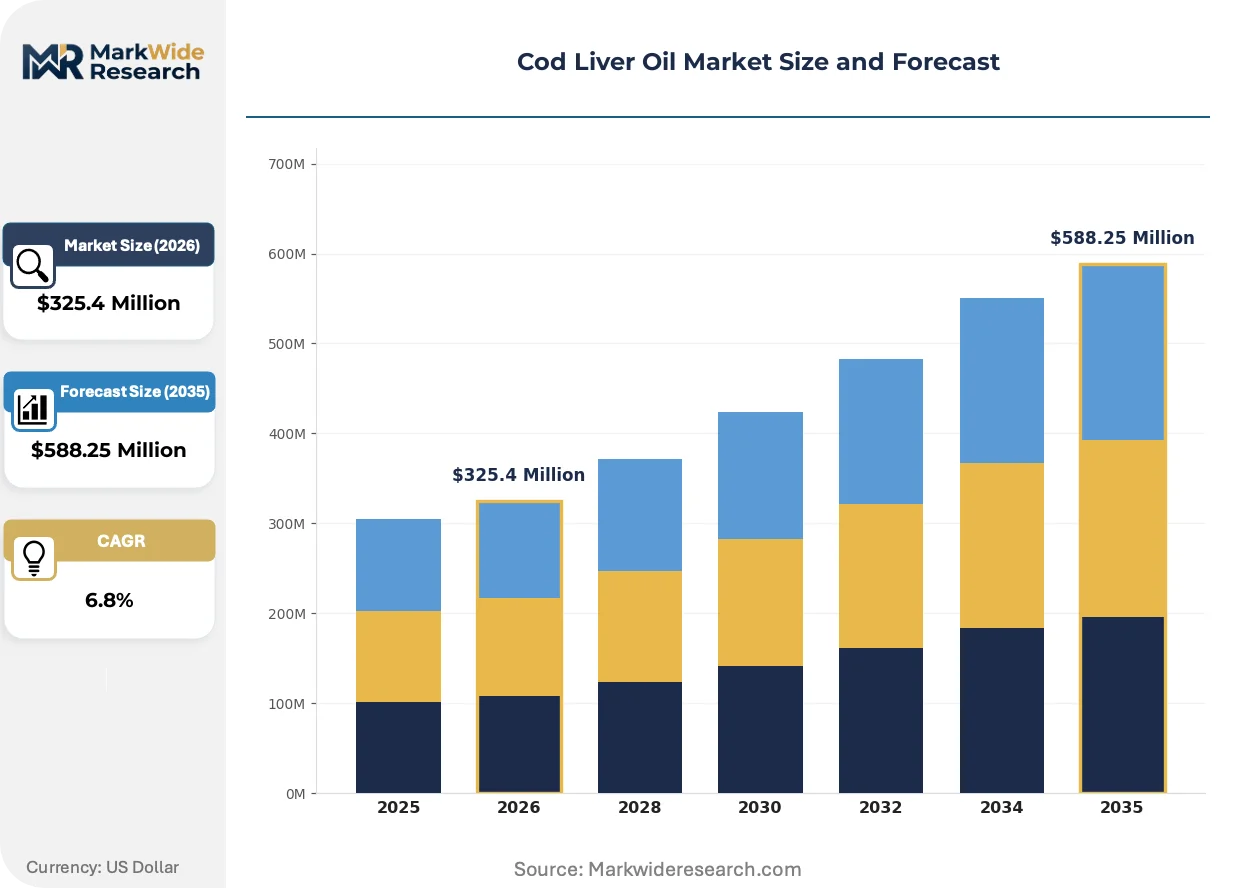
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $588.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Softgel, Capsule, Emulsion Packaging Type: Glass Bottle, Plastic Bottle, Blister Pack, Tube Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Adults, Infants, Elderly, Pregnant Women |
| Companies Covered | Nordic Naturals Inc., BASF SE, LYSI Iceland, Omega Protein Corporation, NOW Health Group Inc., Nestlé SA, Carlson Laboratories Inc., Croda International Plc, Olvea Fish Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cod Liver Oil Market Emerging Trajectories
Formulation science and regulatory precision are converging to restructure how cod liver oil is refined, positioned, and consumed across pharmaceutical and nutraceutical channels.
Molecular distillation with thin-film evaporator technology is electrifying the separation of heat-sensitive omega-3 fatty acids from oxidized lipids and persistent organic pollutants. German and Norwegian dietary supplement manufacturers are adopting this equipment at accelerated cadence to meet pharmacy-grade specifications. The technology is compressing the viable supply base to processors with capital-intensive purification infrastructure, marginalizing traditional cold-press renderers.
REACH authorization requirements for processing solvents and the EU's updated Novel Food Regulation are reshaping extraction chemistry choices across North Atlantic operations. Manufacturers must now submit full toxicological dossiers for new solvent systems, extending product development timelines. Small-scale Icelandic and Norwegian renderers lacking regulatory affairs capacity are outsourcing compliance to specialized consultancies or exiting human-grade segments entirely.
Unit-dose convenience is displacing bulk liquid loyalty among repeat purchasers in Nordic pharmacy and online retail channels. Softgel capsules and single-serve sachets are capturing subscription-based replenishment models that bypass traditional wholesale distribution. This pattern is most visible in urban Norwegian and Swedish markets where pharmacy chains operate integrated digital fulfillment platforms.
Cod Liver Oil Market Segmentation
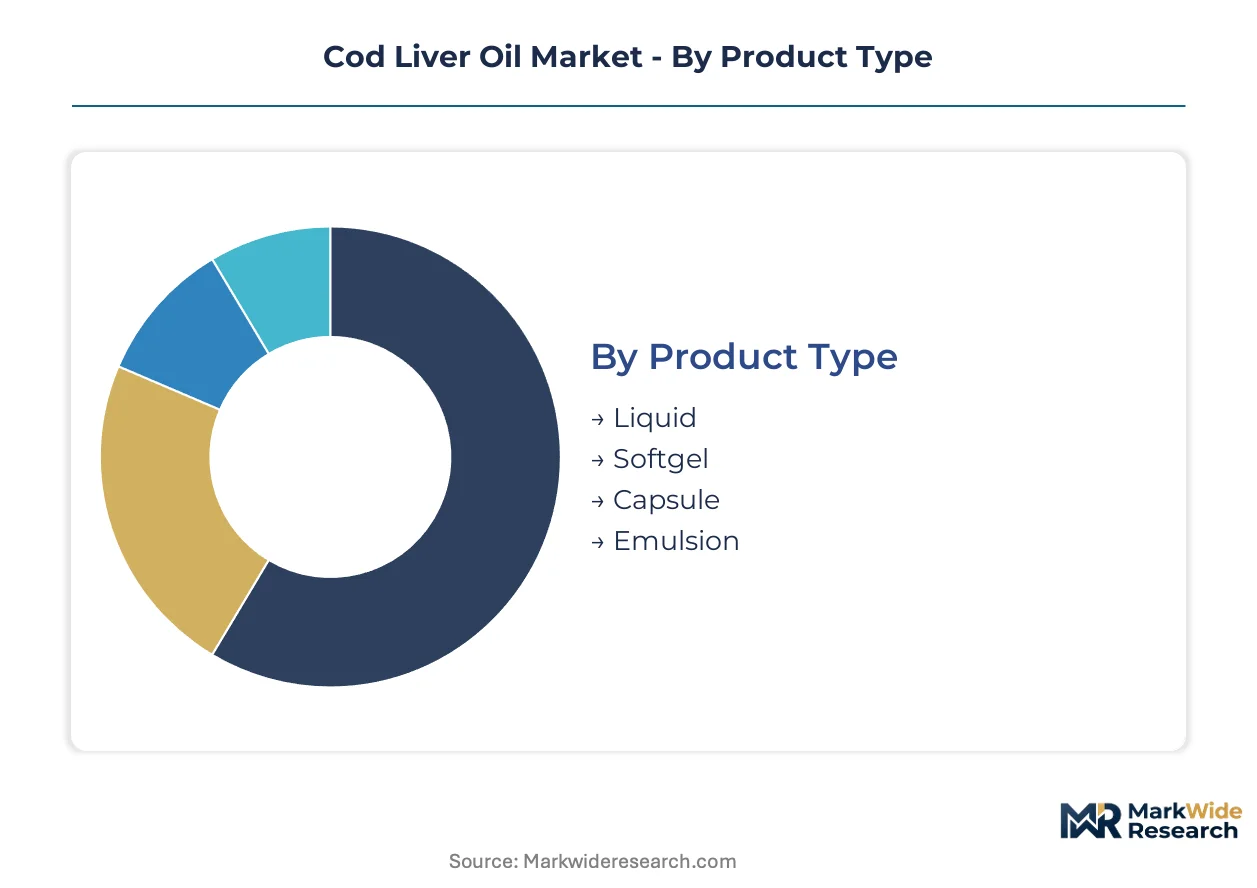
Segmentation in cod liver oil reveals how capital allocation, regulatory compliance, and consumer compliance requirements fragment manufacturing priorities. Each dimension exposes different margin structures and infrastructure demands.
Product Type:
Capital intensity varies sharply across product categories, with molecular distillation equipment and cleanroom infrastructure creating steep barriers for pharmaceutical-grade formats.
- Liquid:Traditional cold-pressed or molecularly distilled oils in amber glass or bulk packaging retain the highest absolute volume through institutional contracts and Scandinavian consumer loyalty. Norwegian and Icelandic coastal processors dominate supply through vertically integrated rendering operations serving pharmacy and direct-to-consumer channels.
- Softgel:Encapsulated unit-dose formats demand pharmaceutical-grade certification, enzymatic re-esterification equipment, and blister-packaging cleanrooms. German and Norwegian dietary supplement manufacturers are expanding procurement of triglyceride-form softgels to capture subscription-based replenishment models in urban Nordic markets.
- Capsule:Hard-shell gelatin or vegetable-derived capsules offer intermediate unit-dose convenience with lower packaging complexity than softgels. Standard potency grades serve mass-market retail in North American health store channels.
- Emulsion:Palatability-engineered water-in-oil dispersions target pediatric and geriatric applications where taste governs compliance. Limited installed capacity concentrates among specialized pharmaceutical formulators.
Most installed capacity flows through Liquid. Expansion is steepest in Softgel.
Packaging Type:
Packaging selection tracks distribution channel requirements, with pharmacy-grade specifications driving material and barrier-property investments.
- Glass Bottle:Amber or cobalt glass provides UV protection and oxidation resistance for liquid formulations. Premium positioning in German and Norwegian retail channels supports higher price realization despite freight cost penalties.
- Plastic Bottle:HDPE or PET containers reduce breakage and shipping weight for high-volume supermarket and online retail distribution. Oxygen scavenger additives extend shelf life in North American mass-market channels.
- Blister Pack:Unit-dose aluminum-PVC or aluminum-aluminum configurations protect softgel integrity through temperature fluctuation. Pharmacy and travel-retail formats favor this configuration for compliance and portability.
- Tube:Collapsible aluminum or laminate tubes serve emulsion formats requiring precise dosing control. Pediatric prescription markets in Scandinavian jurisdictions specify tube packaging for household safety.
Glass Bottle retains the premium positioning margin. Plastic Bottle captures the steepest volume expansion.
Distribution Channel:
Channel selection determines regulatory documentation requirements, with pharmacy distribution demanding the most extensive certification dossiers.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment and bypass wholesale markups. Urban Norwegian and Swedish pharmacy chains operate integrated digital fulfillment capturing repeat purchase behavior.
- Supermarkets:Mass-market placement requires competitive unit pricing and standardized potency grades. Shelf space concentration in German retail chains favors established brands with EFSA-compliant labeling.
- Health Stores:Specialist retailers emphasize cold-pressed or unrefined positioning for traditional consumer segments. Staff recommendation influence sustains premium pricing for molecularly distilled alternatives.
- Pharmacies:Pharmacy-grade specifications and pharmacist endorsement drive highest compliance rates. EFSA vitamin thresholds and USP monograph compliance create documentation barriers limiting supplier base.
Pharmacy channels concentrate the highest-margin transactions. Online Retail is climbing the fastest.
End User:
End-user segmentation governs formulation potency, palatability engineering, and regulatory safety thresholds.
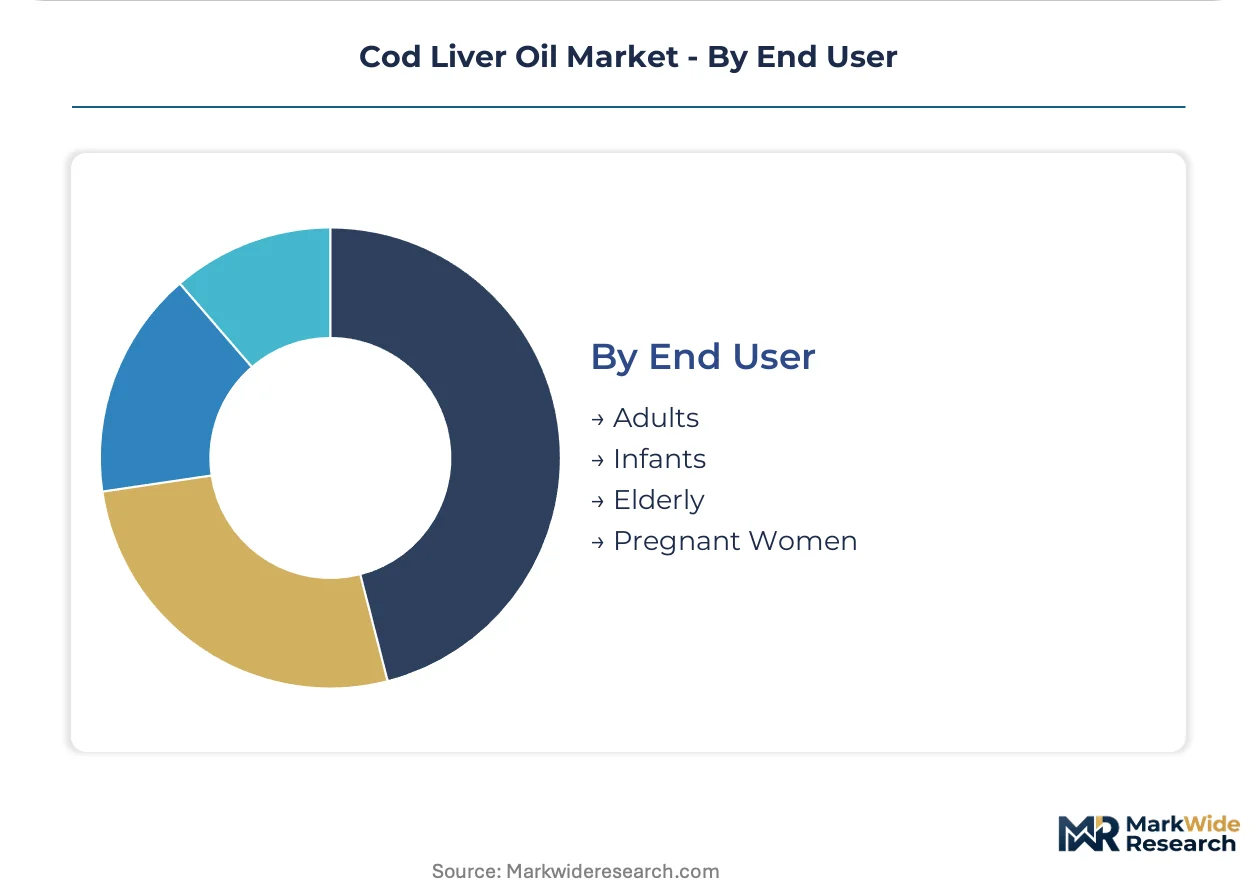
- Adults:Standardized potency grades with EPA and DHA omega-3 fatty acids at 15-25% of total lipids serve general wellness and cardiovascular positioning. German and Norwegian retail channels dominate volume.
- Infants:Emulsion formats with masked flavor profiles and precisely titrated vitamin A and D content address compliance challenges. Pediatric prescription renewals depend on palatability engineering.
- Elderly:Softgel or emulsion formats with enhanced absorption characteristics target age-related compliance barriers. Pharmacy channel concentration supports higher adherence monitoring.
- Pregnant Women:Low-vitamin-A or vitamin-A-free molecularly distilled grades address teratogenic risk concerns. EFSA maximum limits and obstetrician recommendation patterns shape formulation investments.
Adults segment absorbs most production volume. Infants applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rendering technicians and marine biochemists cluster around North Atlantic fishery jurisdictions and German pharmaceutical manufacturing corridors. These talent concentrations anchor cod liver oil processing infrastructure from catch to finished dosage form.
Norway
Pharmaceutical-grade molecular distillation capacity expands near Bergen and Ålesund as Mattilsynet enforces tightened vitamin A thresholds. The EU's EFSA maximum limits accelerate reformulation investments toward standardized potency grades. Coastal processing zones integrate vertically from North Atlantic Gadus morhua catch to softgel encapsulation.
Germany
Enzymatic re-esterification equipment procurement surges among dietary supplement manufacturers targeting triglyceride-form omega-3 preference. REACH authorization requirements for processing solvents reshape extraction chemistry choices. Hamburg and Frankfurt pharmacy chains drive subscription-based replenishment models through integrated digital fulfillment platforms.
Iceland
North Atlantic fishery partnerships secure raw material access for vertically integrated rendering operations. The EU Green Deal biowaste protocols incentivize marine byproduct valorization toward pharmaceutical-grade liver oil extraction. Reykjavik-area processors compress lead times for softgel manufacturers through captive supply from catch to capsule.
United States
USP monograph compliance and FDA Good Manufacturing Practice mandates screen unrefined products from pharmacy distribution. NOW Health Group Inc. competes on volume throughput across softgel and liquid formats. EPA marine pollutant screening protocols and evolving heavy metal limits redirect formulation investments toward molecular distillation infrastructure.
United Kingdom
Pharmacy-grade specifications and pharmacist endorsement drive highest compliance rates in London and Manchester retail channels. EFSA vitamin thresholds create documentation barriers limiting supplier base to certified processors. Health store channels emphasize cold-pressed positioning for traditional consumer segments while molecularly distilled alternatives capture premium shelf space.
Cod Liver Oil Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade certification pathways, while mid-scale renderers compete on volume throughput and coastal raw material access. The vendor base stratifies across molecular distillation specialists, vertically integrated North Atlantic processors, and mass-market softgel manufacturers. Three archetypes dominate: certification-driven pharmacy-grade suppliers, fishery-integrated coastal renderers, and retail-channel volume players. Competitive moves concentrate on enzymatic re-esterification equipment acquisition and direct-to-consumer subscription platform development.
Among North Atlantic-integrated specialists, LYSI Iceland exemplifies fishery-captive supply chain configuration, while Nordic Naturals Inc. occupies a position within the pharmaceutical-grade purification tier. NOW Health Group Inc. represents the volume-driven retail-channel archetype. These three anchors illustrate how geographic integration, certification investment, and channel focus segment competitive positioning across the category.
| Leading Market Players |
|---|
| Nordic Naturals Inc. |
| BASF SE |
| LYSI Iceland |
| Omega Protein Corporation |
| NOW Health Group Inc. |
| Nestlé SA |
| Carlson Laboratories Inc. |
| Croda International Plc |
| Olvea Fish Oils |
| Others |
Supply Flow & Price Mechanics
Triglyceride-form omega-3 procurement preferences among German and Norwegian dietary supplement manufacturers are compressing supplier margins for cold-pressed renderers while rewarding molecular distillation investments with premium positioning power.
Pricing Analysis
Bundled pharmaceutical-grade certification with enzymatic re-esterification services commands substantial premiums over unbundled raw oil supply. Three-tier pricing structure across pharmaceutical-grade, standardized-potency, and bulk-commodity levels separates certified softgel suppliers from coastal cold-press renderers. Cost compression in unrefined grades is intensifying because algal DHA substitutes are capturing vegan-formulation contracts. Mass-market supermarket buyers exhibit highest price sensitivity; pharmacy chains and subscription direct-to-consumer platforms demonstrate lowest.
Supply Chain Analysis
Freight cost differentials between North Atlantic coastal zones and inland European processing hubs favor concentrated rendering infrastructure near Bergen, Ålesund, and Reykjavik. Raw material supply draws from Norwegian, Icelandic, and Faroese Gadus morhua quotas; molecular distillation equipment; and pharmaceutical-grade encapsulation materials. Single-source vulnerability concentrates in North Atlantic fishery jurisdictions where ICES stock assessments fluctuate annually. Distribution runs through vertically integrated catch-to-capsule processors, specialized softgel manufacturers, and pharmacy chain digital fulfillment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cod liver oil hinges on enzymatic re-esterification equipment deployment that shifts product mix toward premium triglyceride-form positioning.
For Market Incumbents: Cement pharmacy-grade certification pathways through USP monograph compliance and EDQM CEP documentation to defend against algal omega-3 substitution threats. Deepen backward integration into North Atlantic fishery partnerships to secure raw material access amid quota volatility. For New Entrants and Emerging Players: Enzymatic re-esterification technology with palatability-engineered emulsion formats offers the most penetrable wedge into pediatric prescription markets where compliance rates govern renewal patterns. Target direct-to-consumer subscription platforms in urban Nordic markets with unit-dose convenience positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with coastal processors possessing captive fishery supply and existing molecular distillation infrastructure. Long-term viability centers on regulatory capacity to navigate tightening EFSA vitamin thresholds and REACH solvent authorization requirements. Watch for ICES quota announcement patterns as inflection indicators for raw material cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Re-esterification Equipment Acquisition | Enables triglyceride-form omega-3 production that commands pharmacy-grade premium positioning. |
| North Atlantic Fishery Partnership Expansion | Secures Gadus morhua liver supply through vertically integrated catch-to-capsule operations. |
| Pharmaceutical-Grade Certification Investment | Qualifies products for USP monograph compliance and EDQM CEP pharmacy distribution pathways. |
| Pediatric Emulsion Format Development | Captures prescription renewal volume where palatability engineering governs compliance rates. |
| Direct-to-Consumer Subscription Platform Launch | Bypasses wholesale markups through urban Nordic pharmacy chain digital fulfillment integration. |
Methodological Framework
Direct dialogue with molecular distillation equipment operators, Mattilsynet regulatory affairs specialists, German dietary supplement procurement directors, and North Atlantic fishery quota administrators grounded qualitative findings. Secondary validation drew from EFSA scientific opinions, REACH authorization databases, ICES stock assessment reports, and USP monograph revision notices. Bottom-up volume modeling triangulated against top-down category spend analysis.
Bottom-up unit economics across liquid, softgel, capsule, and emulsion product types combined with top-down omega-3 category spend allocation across German, Norwegian, Icelandic, US, and UK regulatory clusters. Segmentation dimensions modeled include product format, distribution channel, end-user population, and regional certification requirement tier. CAGRs derived from installed capacity expansion timelines, equipment procurement patterns, and pharmacy channel penetration trajectories.
The model holds under stable ICES quota regimes and EFSA vitamin threshold enforcement; deviation in algal DHA cost curves or EU heavy metal limit tightening would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Nutritional Oil Powder Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Global Antioxidant Market