
 Vegan Vitamins and Supplements Market | 2026-2036
Vegan Vitamins and Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Vitamins and Supplements Market Analytics
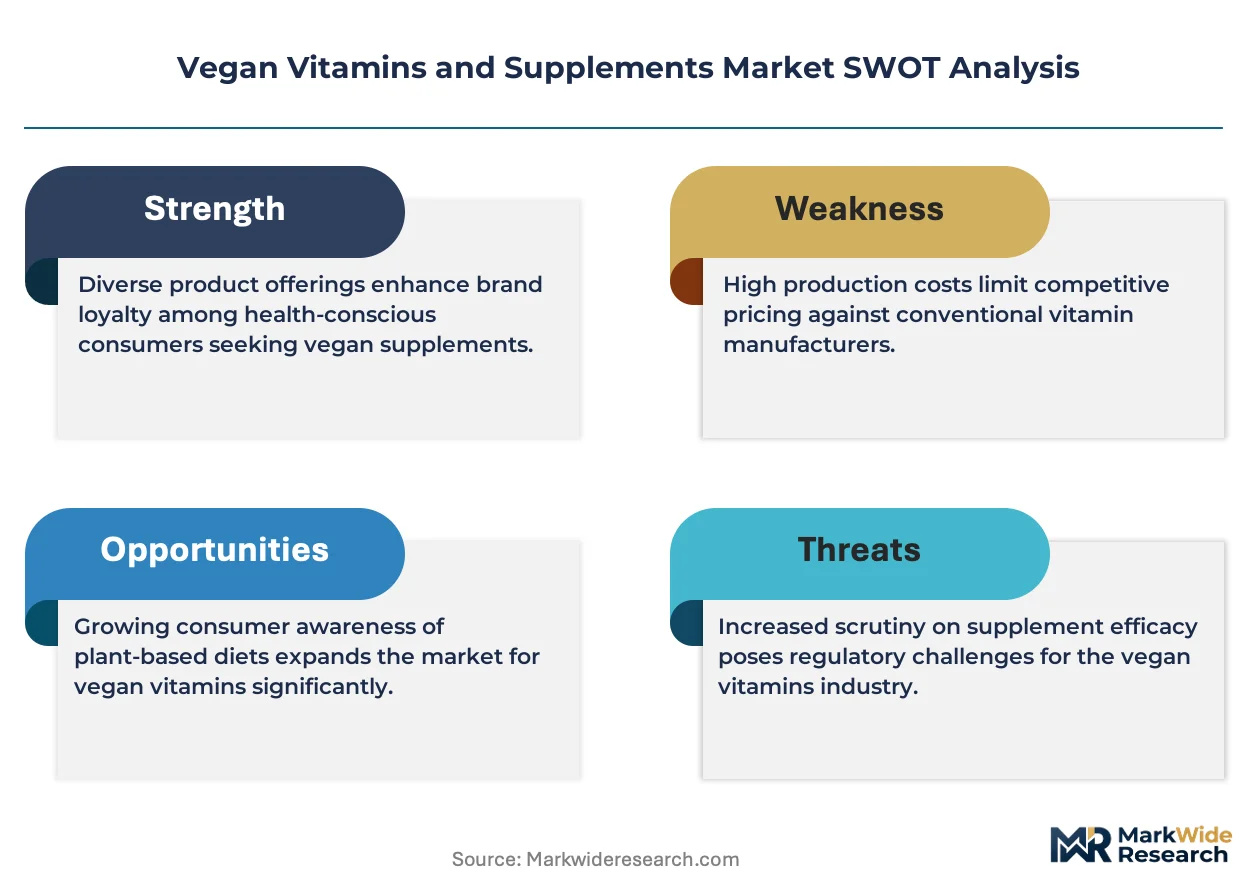
Aftermarket subscription revenue is reshaping profit architecture in the vegan vitamins and supplements space. Ritual leverages direct-to-consumer membership models to sustain recurring margins and reduce customer acquisition costs. Garden of Life anchors its position through certified organic supply chains and Whole Foods Market exclusivity. NOW Foods competes on manufacturing scale, operating vertically integrated production facilities that control raw material sourcing for plant-based B12 and iron complexes.
Vegan vitamins and supplements comprise nutrient formulations derived exclusively from non-animal sources, including algal DHA, lichen-sourced vitamin D3, and fermented B12, manufactured through cold-press tableting or vegan capsule filling to eliminate gelatin and animal-derived excipients. The multivitamins category leads volume due to comprehensive daily-use positioning among health-conscious consumers, while gummies represent the fastest-growing form segment as manufacturers overcome stability challenges in pectin-based matrices. Online stores capture expanding margin pools through subscription bundling, though health food stores retain loyalty among elderly consumers seeking pharmacist-guided selection.
The FDA regulates dietary supplement labeling and Good Manufacturing Practices, while EFSA governs novel food approvals and health claims across European markets, creating divergent compliance burdens for cross-border brands. India's FSSAI enforces vegan certification standards that influence export eligibility for Ayurvedic-heritage formulations. Stakeholders must monitor evolving allergen disclosure requirements and synthetic versus natural nutrient classification debates that threaten to recategorize established products.
Market Dynamics
Direct-to-consumer subscription models are compressing traditional retail margins while algae-derived nutrient extraction technologies reshape raw material sourcing economics across the vegan supplement value chain.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined approvals for algae-sourced omega-3 and lichen-based vitamin D3 accelerate product commercialization timelines across European markets.
- Fitness Enthusiast Segment Expansion:Plant-based athletic nutrition demand pulls specialized B12 and iron formulations into mainstream sports retail channels.
- Fermentation Technology Maturation:Microbial B12 production at commercial scale reduces dependency on synthetic petrochemical precursors.
Market Restraints
- Algal Oil Supply Concentration:DHA-rich microalgae cultivation clusters in controlled-climate facilities create geographic supply vulnerability.
- Pectin Matrix Stability Costs:Gummy format manufacturing requires specialized moisture-barrier packaging that elevates per-unit production expenses.
- Divergent Certification Standards:India's FSSAI vegan certification criteria mismatch with EU organic regulations forces dual compliance investments.
Strategic Opportunities
- Geriatric Pharmacist-Guided Channels:Health food stores with certified nutrition staff capture loyalty among elderly consumers seeking personalized regimen advice.
- Cold-Press Tableting Convergence:Integration of low-temperature compression with vegan capsule filling eliminates gelatin cross-contamination risks.
- Subscription Bundling Economics:Recurring revenue models reduce customer acquisition expenditure while capturing predictable margin pools.
Industry Challenges
- Synthetic-Natural Classification Disputes:Regulatory debates over fermented nutrient categorization threaten to recategorize established product lines.
- Cross-Border Labeling Complexity:FDA dietary supplement rules diverge from EFSA health claim restrictions, complicating unified packaging strategies.
- Allergen Disclosure Expansion:Evolving mandatory labeling for algal and fungal protein sources extends compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Vitamins and Supplements Market |
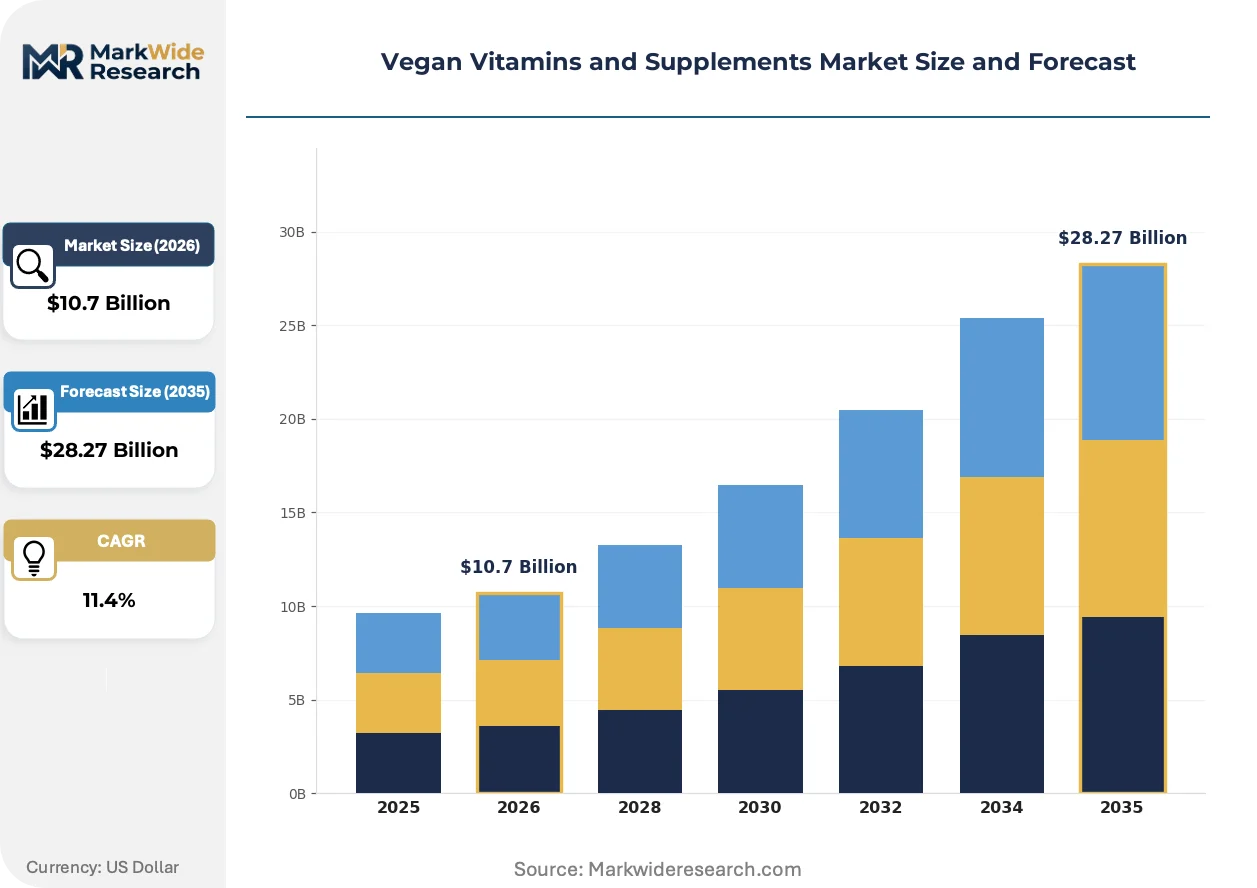
| Market Size in 2026 | $10.7 Billion |
| Market Size in 2035 | $28.27 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Minerals, Herbal Supplements, Amino Acids Form: Tablets, Capsules, Powders, Gummies End User: Fitness Enthusiasts, Vegetarians, Health-Conscious Consumers, Elderly Distribution Channel: Online Stores, Health Food Stores, Pharmacies, Supermarkets |
| Companies Covered | Future Kind, Ritual, NOW Foods, Solgar, Deva Nutrition, Garden of Life, Complement, HUM Nutrition, Nordic Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Vitamins and Supplements Market Evolving Landscape
Digital formulation platforms and precision fermentation are collapsing development cycles while regulatory divergence between FDA and EFSA frameworks forces parallel compliance architectures.
Precision fermentation for B12 and K2 production is virtualizing traditional chemical synthesis pathways. Biotech ingredient suppliers now license strains to contract manufacturers, compressing capital requirements for new market entrants. This distributed production model is virtualizing the concentrated supply base that historically dominated vitamin manufacturing.
EFSA's evolving novel food classification for algae-derived nutrients creates approval bottlenecks for DHA and EPA formulations. Brands must submit comprehensive toxicology dossiers that extend time-to-market by 18-24 months. European specialist retailers are responding by prioritizing formulations with established safety profiles over innovative extracts.
Fitness-oriented consumers now complete nutritional assessments through mobile applications before purchasing. This behavior fragments demand across personalized subscription services and displaces one-size-fits-all multivitamin purchases. Germany and the United Kingdom exhibit the strongest adoption of algorithm-driven supplement curation.
Vegan Vitamins and Supplements Market Segmentation
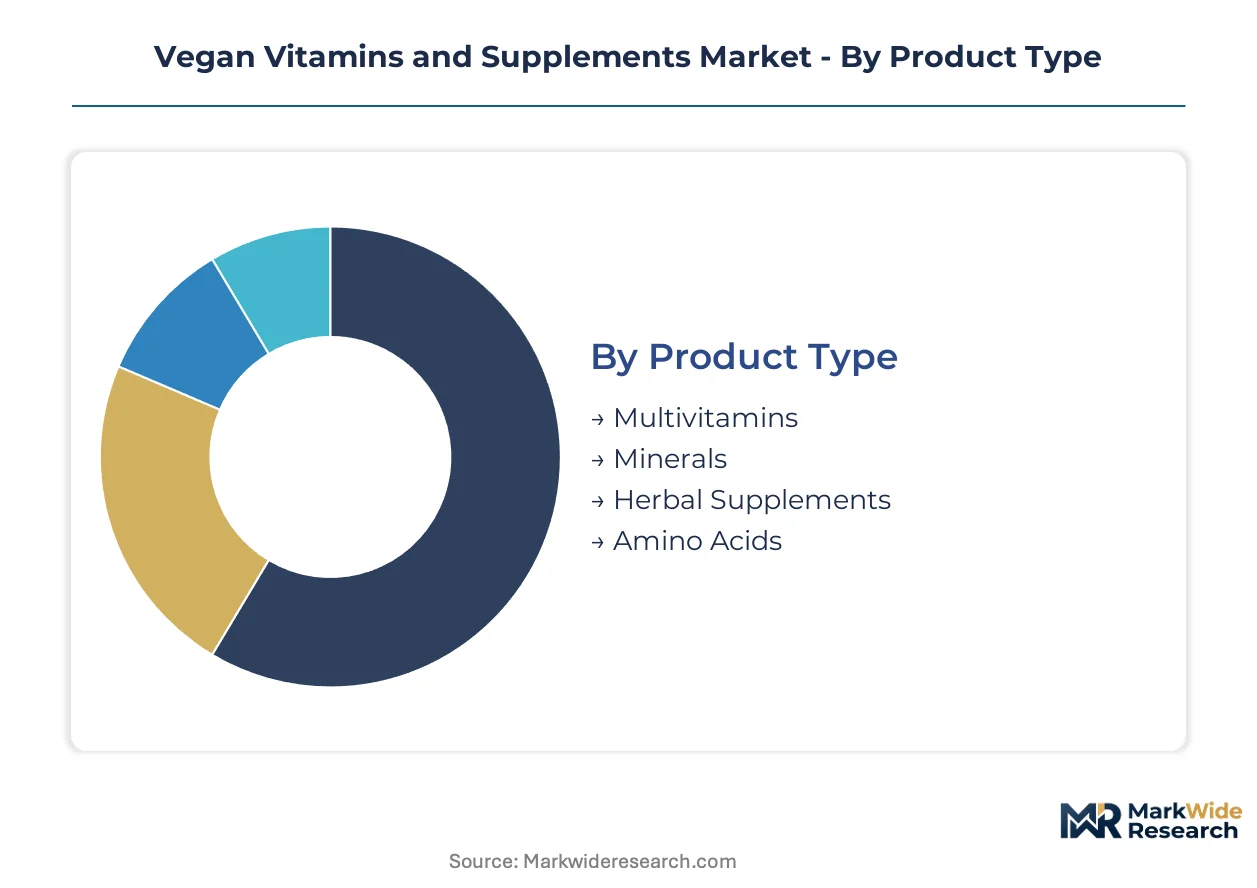
Segmentation in vegan vitamins and supplements determines formulation priorities, packaging investments, and channel economics. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Product Type:
Application focus separates daily-use maintenance from targeted therapeutic intervention across consumer wellness journeys.
- Multivitamins:Comprehensive formulations combining algal DHA, lichen-sourced vitamin D3, and fermented B12 address micronutrient gaps in plant-based diets. Demand concentrates among health-conscious consumers in Germany seeking convenient daily compliance, though EFSA novel food dossiers for innovative extracts extend approval timelines.
- Minerals:Chelated iron, zinc, and calcium complexes derived from marine algae and mineral-rich plant sources support athletic recovery and bone density. Fitness enthusiasts in Berlin and Munich drive specialized iron formulation purchases through sports nutrition retailers.
- Herbal Supplements:Ayurvedic-heritage formulations from ashwagandha and turmeric extracts require FSSAI vegan certification for Indian export eligibility.
- Amino Acids:Fermented L-carnitine and BCAAs serve plant-based athletic nutrition protocols.
Multivitamins commands the established base. The steepest expansion runs through Minerals.
Form:
Manufacturing complexity and stability requirements create divergent margin structures across delivery formats.
- Gummies:Pectin-based matrices replace gelatin through specialized moisture-barrier packaging that elevates per-unit costs. Germany and the United Kingdom show strongest adoption among younger consumers completing mobile nutritional assessments before purchase.
- Tablets:Cold-press compression eliminates heat degradation of heat-sensitive algal nutrients while enabling high-volume production economics. Elderly consumers in health food stores prefer pharmacist-guided tablet selection for regimen simplicity.
- Capsules:Vegan capsule filling using pullulan or HPMC eliminates gelatin cross-contamination risks.
- Powders:Bulk formats serve fitness enthusiasts customizing pre-workout and recovery stacks.
Tablets anchors volume leadership. Gummies gains share fastest through convenience positioning.
End User:
Customer type dictates channel preference, price sensitivity, and the depth of personalized guidance required at point of purchase.
- Fitness Enthusiasts:Plant-based athletic nutrition demand pulls specialized B12, iron, and amino acid formulations into mainstream sports retail. Algorithm-driven subscription curation in Germany and the United Kingdom fragments demand away from one-size-fits-all multivitamins.
- Elderly:Pharmacist-guided selection in health food stores captures loyalty for regimen advice on drug-nutrient interactions and absorption optimization.
- Vegetarians:Longstanding plant-based practitioners seek comprehensive micronutrient insurance against dietary gaps.
- Health-Conscious Consumers:Wellness-focused buyers prioritize certified organic supply chains and transparent sourcing.
Elderly commands the established base. Fitness enthusiasts shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines customer acquisition economics and the feasibility of subscription bundling versus transactional retail.
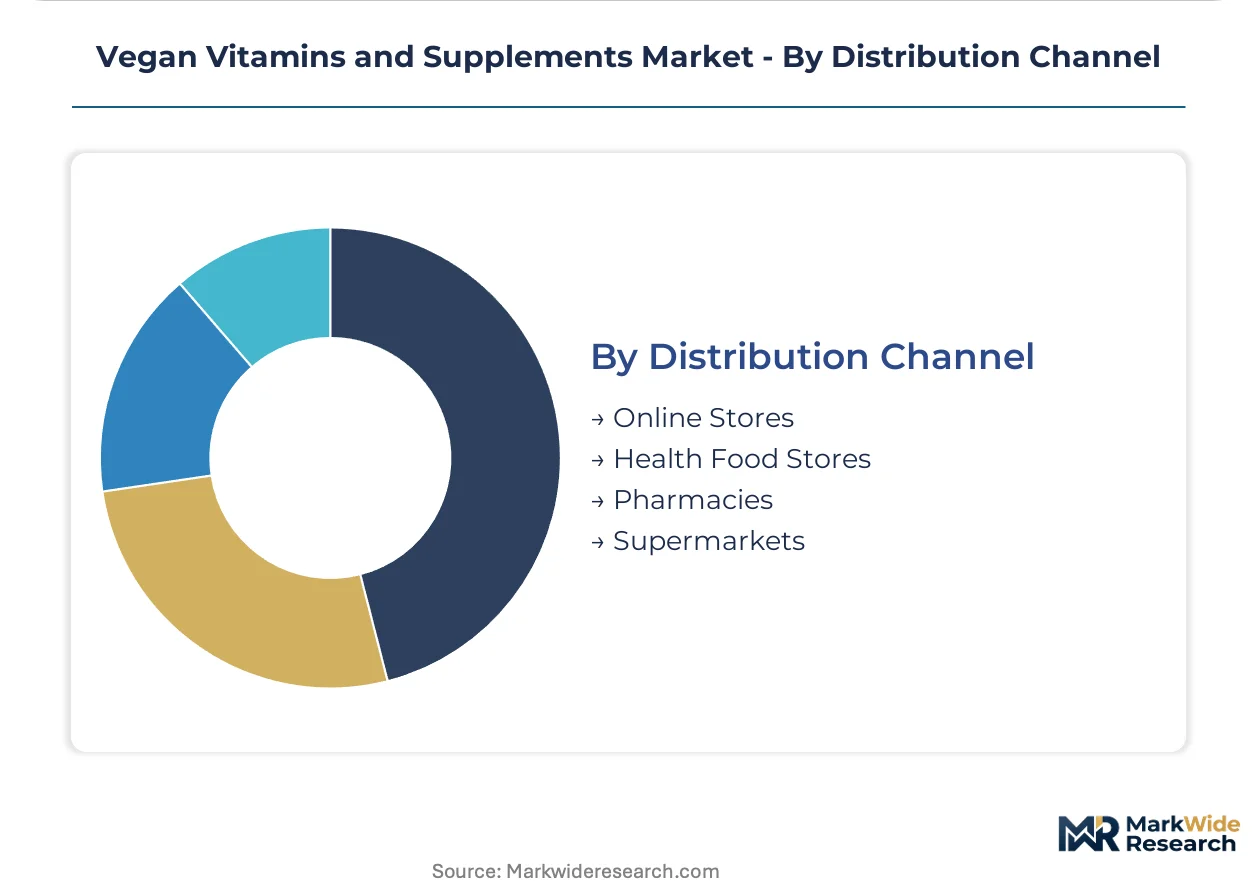
- Online Stores:Direct-to-consumer subscription models capture recurring margin pools while reducing acquisition expenditure through bundled regimen offerings. Digital formulation platforms enable personalized curation that displaces generic multivitamin purchases.
- Health Food Stores:Certified nutrition staff provide personalized regimen advice that builds loyalty among elderly consumers seeking guidance on algal oil sourcing and synthetic-natural classification distinctions.
- Pharmacies:Professional credibility supports premium positioning for clinically validated formulations.
- Supermarkets:Mass-market accessibility drives trial among price-sensitive newcomers to plant-based nutrition.
Health food stores commands the established base. Online stores gains share fastest through subscription economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algae cultivation facilities and fermentation-based nutrient production cluster in temperate zones with established pharmaceutical manufacturing infrastructure. Germany, the United States, India, the United Kingdom, and China anchor capacity across extraction, formulation, and packaging stages.
Germany
Berlin and Munich host Europe's densest concentration of vegan-certified supplement brands and specialized retail distribution. EFSA novel food regulations govern approval pathways for algae-derived omega-3 and lichen-sourced vitamin D3 formulations. Cold-press tableting facilities in Bavaria supply private-label manufacturers across the European Union.
United States
Fitness enthusiasts in California and New York drive demand for plant-based athletic nutrition through direct-to-consumer subscription channels. FDA dietary supplement labeling requirements and Good Manufacturing Practices create compliance benchmarks for domestic and imported formulations. Precision fermentation startups in Boston and San Francisco license microbial B12 production strains to contract manufacturers.
India
Ayurvedic-heritage formulations from ashwagandha and turmeric extracts require FSSAI vegan certification for export eligibility to European and North American markets. Hyderabad and Ahmedabad house contract manufacturing organizations serving international brands seeking cost-competitive pectin-based gummy production. The country's national pharmaceutical regulator enforces allergen disclosure standards that extend compliance timelines for algal protein sources.
United Kingdom
Algorithm-driven supplement curation platforms in London fragment demand away from generic multivitamin purchases toward personalized subscription regimens. The Medicines and Healthcare products Regulatory Agency oversees borderline product classifications between food supplements and medicinal claims. Manchester and Birmingham distribution centers serve as fulfillment hubs for direct-to-consumer brands targeting European markets post-Brexit.
China
Domestic demand for plant-based nutrition concentrates in Shanghai and Beijing among health-conscious urban consumers. The National Medical Products Administration regulates dietary supplement registration through blue hat certification requirements. Contract manufacturers in Zhejiang province specialize in vegan capsule filling using pullulan and HPMC alternatives to gelatin.
Vegan Vitamins and Supplements Market Competitive Landscape
Direct-to-consumer subscription specialists and vertically integrated manufacturers split the market between recurring revenue models and captive supply chain control. The vendor base clusters around three strategic archetypes: certified organic purists competing on transparency, scale-driven producers optimizing manufacturing economics, and digital-native brands capturing algorithm-driven personalization. Consolidation pressure intensifies as fermentation technology licensing reduces capital barriers for new entrants. Geographic expansion and strategic partnerships dominate competitive moves as brands navigate divergent FDA and EFSA regulatory requirements.
Within the certified organic tier, Garden of Life exemplifies supply chain transparency through Whole Foods Market exclusivity and certified organic sourcing protocols. NOW Foods occupies a position among scale-driven manufacturers with vertically integrated production facilities controlling raw material sourcing. Ritual anchors the digital-native archetype through membership-based direct-to-consumer models that reduce customer acquisition expenditure.
| Leading Market Players |
|---|
| Future Kind |
| Ritual |
| NOW Foods |
| Solgar |
| Deva Nutrition |
| Garden of Life |
| Complement |
| HUM Nutrition |
| Nordic Naturals |
| Others |
Value Network & Pricing Analysis
Undercapacity in European algal oil extraction facilities is driving contract manufacturers toward multi-year offtake commitments that compress margin flexibility for finished goods producers while elevating input security premiums across the vegan supplement value chain.
Pricing Analysis
EFSA novel food classification dictates the pricing tier structure across European markets, separating premium-positioned formulations with completed toxicology dossiers from economy-tier synthetic alternatives awaiting regulatory clarity. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and geographic delivery cost differentials. Cost compression in the standard tier is intensifying because contract manufacturers absorb extended EFSA approval timelines without price adjustment mechanisms. Fitness enthusiasts demonstrate lowest price sensitivity due to regimen personalization willingness, while elderly consumers in health food stores exhibit highest sensitivity to per-unit cost escalations.
Supply Chain Analysis
Extended payment terms from German and Dutch distributors are financing inventory carrying costs for pectin-based gummy manufacturers facing moisture-barrier packaging capital requirements. Algal DHA cultivation draws from controlled-climate facilities in Germany, the United States, and China, while lichen-sourced vitamin D3 extraction rests on Scandinavian and North American harvest networks. Single-source vulnerability in DHA-rich microalgae strains creates geographic concentration risk. Distribution runs through direct-to-consumer subscription platforms and specialized health food retail with certified nutrition staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as algorithm-driven personalization fragments demand away from standardized multivitamin formats, creating niche entry points for specialized formulation specialists serving discrete consumer archetypes.
For Market Incumbents: Entrench position through backward integration into fermentation-based B12 production and captive supply of algal omega-3 extracts, neutralizing emerging precision fermentation licensing threats from biotech ingredient suppliers while securing margin control against synthetic-natural classification regulatory shifts.
For New Entrants and Emerging Players: Pharmacist-guided health food channels in Germany and the United Kingdom represent the most penetrable entry point for clinically positioned mineral complexes targeting elderly consumers seeking drug-nutrient interaction guidance. Subscription bundling economics enable recurring revenue capture without competing against established direct-to-consumer brands on acquisition spend.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital-native brands with algorithm-driven curation capabilities serving fitness enthusiast segments. Long-term viability centers on regulatory navigation expertise across divergent FDA and EFSA frameworks. Acquisition target archetype: vertically integrated manufacturers with certified organic supply chains and established novel food approval track records. Watch EFSA toxicology dossier backlog clearance rates as inflection indicator for European market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Licensing | Precision fermentation startups in Boston and San Francisco reduce capital barriers for microbial B12 production. |
| EFSA Novel Food Dossier Completion | Comprehensive toxicology submissions for algae-derived DHA accelerate European commercialization timelines. |
| Direct-to-Consumer Subscription Launch | Membership models capture recurring margin pools while reducing customer acquisition expenditure. |
| Certified Organic Supply Chain Integration | Whole Foods Market exclusivity and transparent sourcing protocols anchor premium positioning. |
| Cold-Press Tableting Capacity Expansion | Bavarian facilities supply private-label manufacturers across the European Union with heat-sensitive nutrient preservation. |
Research Methodology
The analysis maps multivitamins, minerals, herbal supplements, and amino acid formulations, each validated through formulation scientists at contract manufacturing organizations, regulatory affairs specialists navigating EFSA and FDA pathways, procurement managers at health food retail chains, and direct-to-consumer brand executives. Primary interview insights triangulate against secondary sources including EFSA novel food approval databases, FDA dietary supplement labeling guidance, FSSAI vegan certification standards, and customs records for algal oil trade flows. Bottom-up segment sizing and top-down market reconciliation ensure cross-validation.
Assumptions held fixed include prevailing EFSA novel food classification frameworks and FDA Good Manufacturing Practice enforcement intensity, while fermentation technology maturation timelines and fitness enthusiast segment expansion rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, delivery form, end-user archetype, and distribution channel structure. CAGRs derive from regression analysis against historical adoption curves for comparable nutraceutical categories, with inputs including mobile nutritional assessment platform penetration and subscription service retention benchmarks.
Practitioners should monitor EFSA toxicology dossier processing velocity and FSSAI certification requirement evolution for early signals of regulatory access constraint or relaxation. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Nutraceutical Flexible Packaging Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Astragalus Propinquus Market