
 Asia-Pacific Omega-3 Products Market | 2026-2036
Asia-Pacific Omega-3 Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Omega-3 Products Market Outlook
Marine biochemist talent shortages across Southeast Asian processing hubs is reorganizing how regional omega-3 concentrate production scales. Cargill anchors its position through backward integration into Peruvian and Chilean anchovy fisheries, securing raw material flows before regional competitors. Blackmores dominates Australian pharmacy and practitioner channels with TGA-registered formulations that command premium positioning. Nestle extends its reach through functional food applications, embedding microencapsulated omega-3 powders into mainstream dairy and infant nutrition lines across China and India.
Asia-Pacific omega-3 products encompass concentrated long-chain polyunsaturated fatty acids—primarily eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA)—extracted from marine biomass or cultivated microalgae and standardized to potencies ranging from 30% to 90% active content by weight. These bioactive lipids serve cardiovascular, cognitive, and anti-inflammatory therapeutic endpoints in human nutrition, pharmaceutical interventions, and aquaculture feed formulations. Fish oil maintains volume leadership due to established supply infrastructure and cost structures, though algal oil captures the fastest expansion trajectory as vegan label claims and contaminant-free positioning attract premium health supplement buyers in South Korea and Japan. Softgel formats occupy the dominant share of consumer-facing channels, while liquid concentrates concentrate margin pools within pharmaceutical and clinical nutrition segments where dosing precision and bioavailability enhancement justify higher unit economics.
China's National Medical Products Administration (NMPA) and India's Food Safety and Standards Authority of India (FSSAI) enforce divergent purity and label-claim standards that fragment compliance costs for multinational suppliers. TGA registration requirements in Australia and Ministry of Food and Drug Safety (MFDS) guidelines in South Korea further layer testing protocols for oxidation markers and heavy metal thresholds. Stakeholders must monitor how Japan's Ministry of Health, Labour and Welfare (MHLW) integrates omega-3 specific health claims into its Foods with Function Claims system, as this classification pathway could unlock direct-to-consumer marketing advantages unavailable through conventional supplement regulations.
Market Dynamics
Algal-derived EPA and DHA extraction capacity is reorganizing competitive positioning across Asia-Pacific, as pharmaceutical-grade concentration infrastructure shifts procurement patterns away from traditional marine sources toward controlled-cultivation systems.
Growth Catalysts
- Foods with Function Claims pathway:Japan's MHLW classification system permits direct cardiovascular and cognitive health messaging for omega-3 fortified products, unlocking premium positioning unavailable to conventional supplement formats.
- Aquaculture feed fortification:China's coastal provinces mandate DHA enrichment in farmed fish diets to improve fillet nutritional profiles for export markets, creating sustained bulk demand for high-potency concentrates.
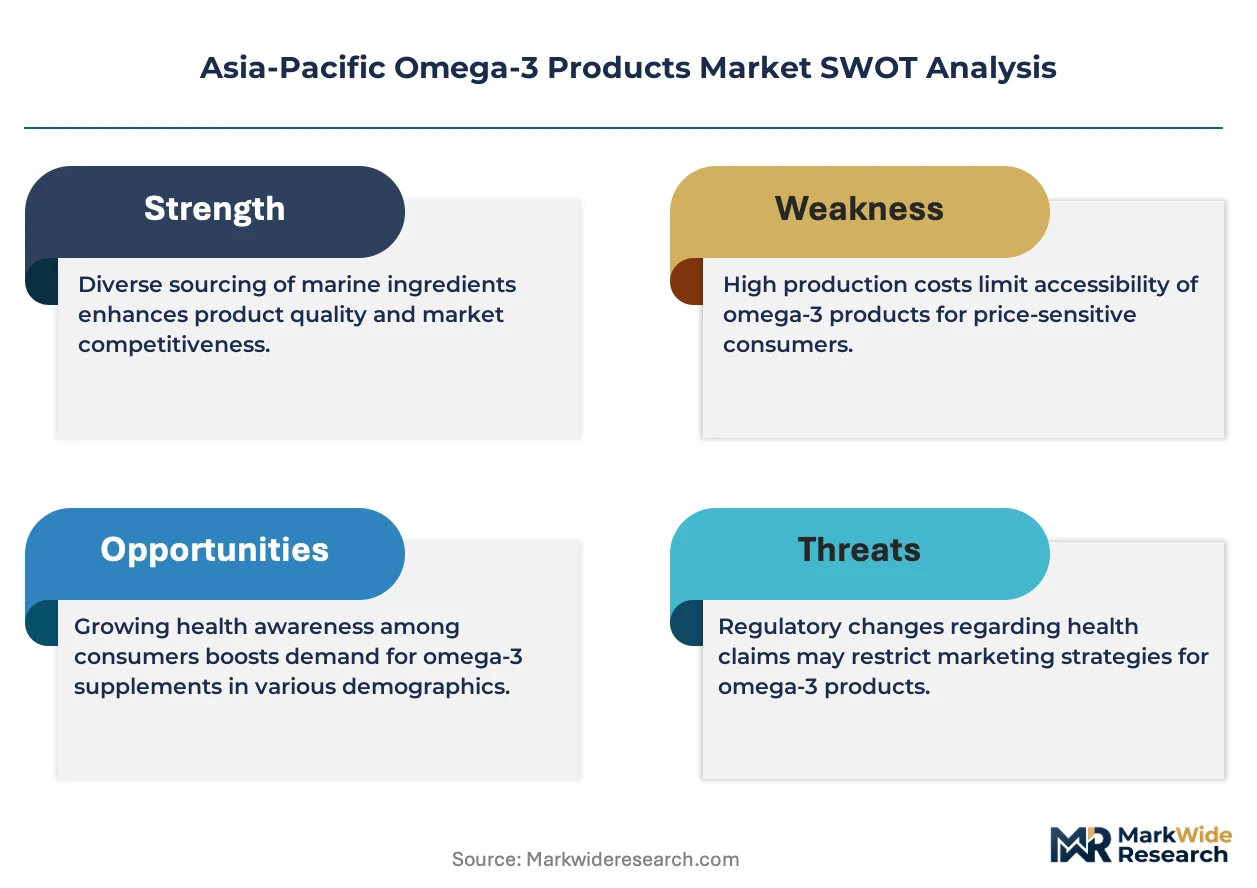
- Third-party certification adoption:TGA's tightened label-claim verification standards in Australia drive pharmacy and practitioner channel brands toward IFOS and GOED certification, raising barrier thresholds that favor established quality systems.
Market Restraints
- Anchovy biomass volatility:Peruvian and Chilean fishery quotas fluctuate with El Niño cycles, concentrating input cost risk for fish-oil-dependent processors unable to pivot toward algal alternatives.
- Divergent purity standards:NMPA and FSSAI enforce non-harmonized heavy metal and oxidation thresholds, fragmenting compliance testing requirements and raising batch rejection rates for cross-border suppliers.
- Plant-based omega-3 substitution:ALA-rich flax and chia seed oils capture price-sensitive segments in India and Southeast Asia, compressing addressable market for premium long-chain concentrates.
Strategic Opportunities
- Microencapsulation convergence:Embedding omega-3 powders into ambient-stable dairy and infant nutrition formats opens shelf-stable distribution into China's tier-three cities where cold-chain infrastructure remains underdeveloped.
- MFDS novel food ingredient pathway:South Korea's streamlined safety assessment for algal-derived DHA single-cell oils accelerates time-to-market for vegan-positioned supplements targeting K-beauty adjacent wellness consumers.
- Direct-to-consumer practitioner channels:Telehealth platforms in Australia and Singapore enable personalized dosing protocols for high-concentrate prescriptions, bypassing retail margin extraction for clinically positioned brands.
Industry Challenges
- Marine biochemist scarcity:Southeast Asian processing hubs face acute talent gaps in lipid oxidation control and molecular distillation optimization, constraining yield recovery rates at expansion-stage facilities.
- Dual certification timelines:Simultaneous TGA registration and MFDS novel food approval processes extend product launch cycles by 18-24 months for brands targeting trans-Tasman and North Asian markets concurrently.
- Legacy ERP integration:Batch-level traceability requirements for NMPA pharmaceutical-grade omega-3 tracking collide with existing inventory management systems, forcing mid-scale processors into disruptive system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Omega-3 Products Market |
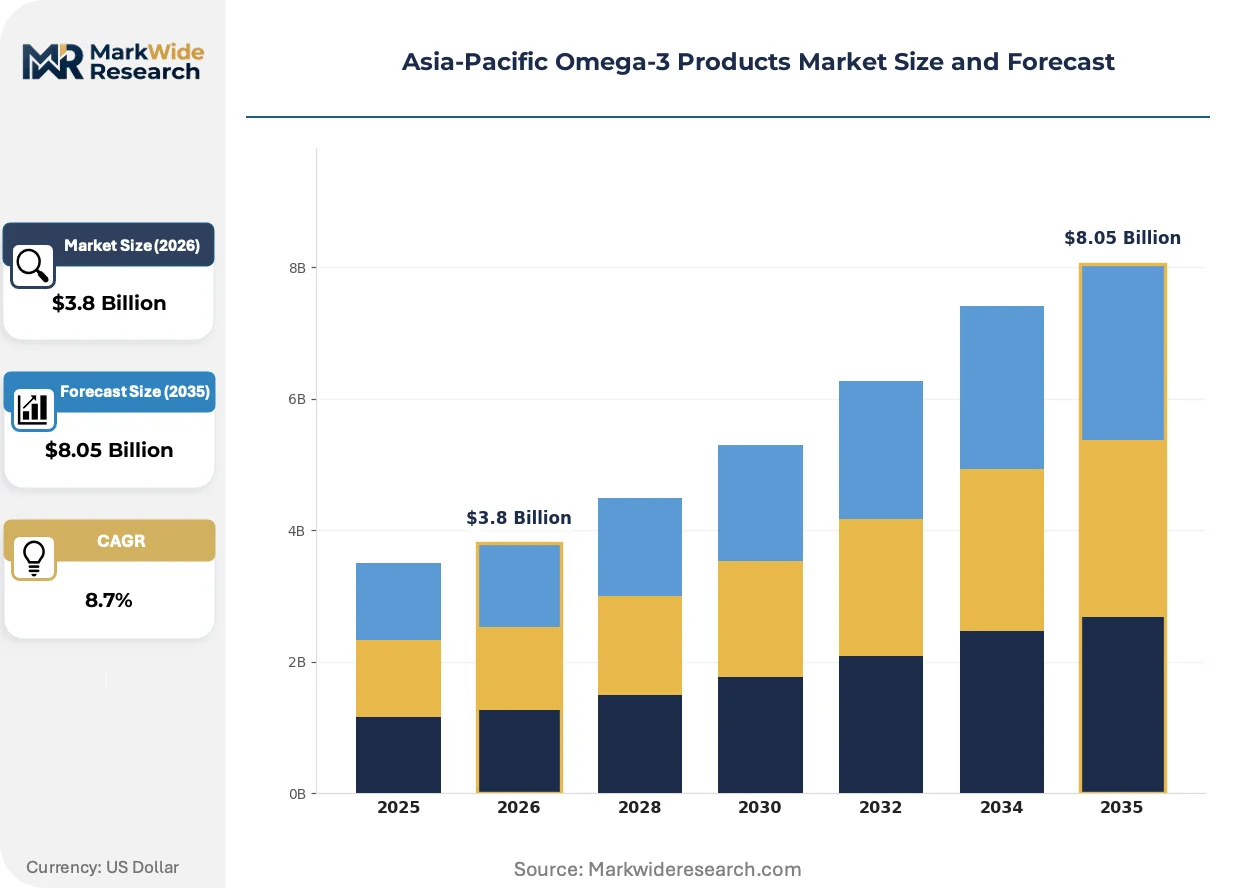
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Krill Oil, Algal Oil, Plant-Based Oil End User: Health Supplements, Pharmaceuticals, Animal Feed, Functional Foods Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Form: Capsules, Softgels, Liquid, Powder |
| Companies Covered | Unilever, Nestle, Amway, Abbott Laboratories, HealthViva, Reckitt Benckiser Group, Herbalife Nutrition, Blackmores, Cargill, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Omega-3 Products Market Strategic Shifts
Supercritical CO2 extraction and enzymatic concentration methods are redrawing process economics, while regulatory classification systems and procurement centralization reshape how value distributes across the value chain.
Supercritical CO2 extraction is fragmenting traditional molecular distillation's dominance in high-potency concentrate production. Pharmaceutical and clinical nutrition buyers in Japan and South Korea specify this solvent-free process for contaminant-sensitive applications. The technology compresses thermal degradation losses while enabling selective EPA-DHA ratio tailoring that batch distillation cannot achieve.
TGA's 2023 label-claim verification overhaul requires quantitative substantiation of EPA and DHA content per softgel, eliminating tolerance ranges previously exploited by lower-tier brands. Australian pharmacy chains now delist non-compliant SKUs, redirecting shelf space toward third-party certified alternatives. Blackmores and practitioner-channel competitors absorb testing cost premiums that import-only brands struggle to match.
Hospital and aged-care procurement consortia across China's Jiangsu and Zhejiang provinces consolidate omega-3 purchasing through centralized tender platforms, disintermediating traditional distributor networks. Volume commitments now flow directly to manufacturers with NMPA pharmaceutical-grade registrations, compressing margins for intermediaries without GMP-certified warehousing. This concentration rewards domestic producers with established regulatory relationships over import-reliant competitors.
Asia-Pacific Omega-3 Products Market Segmentation
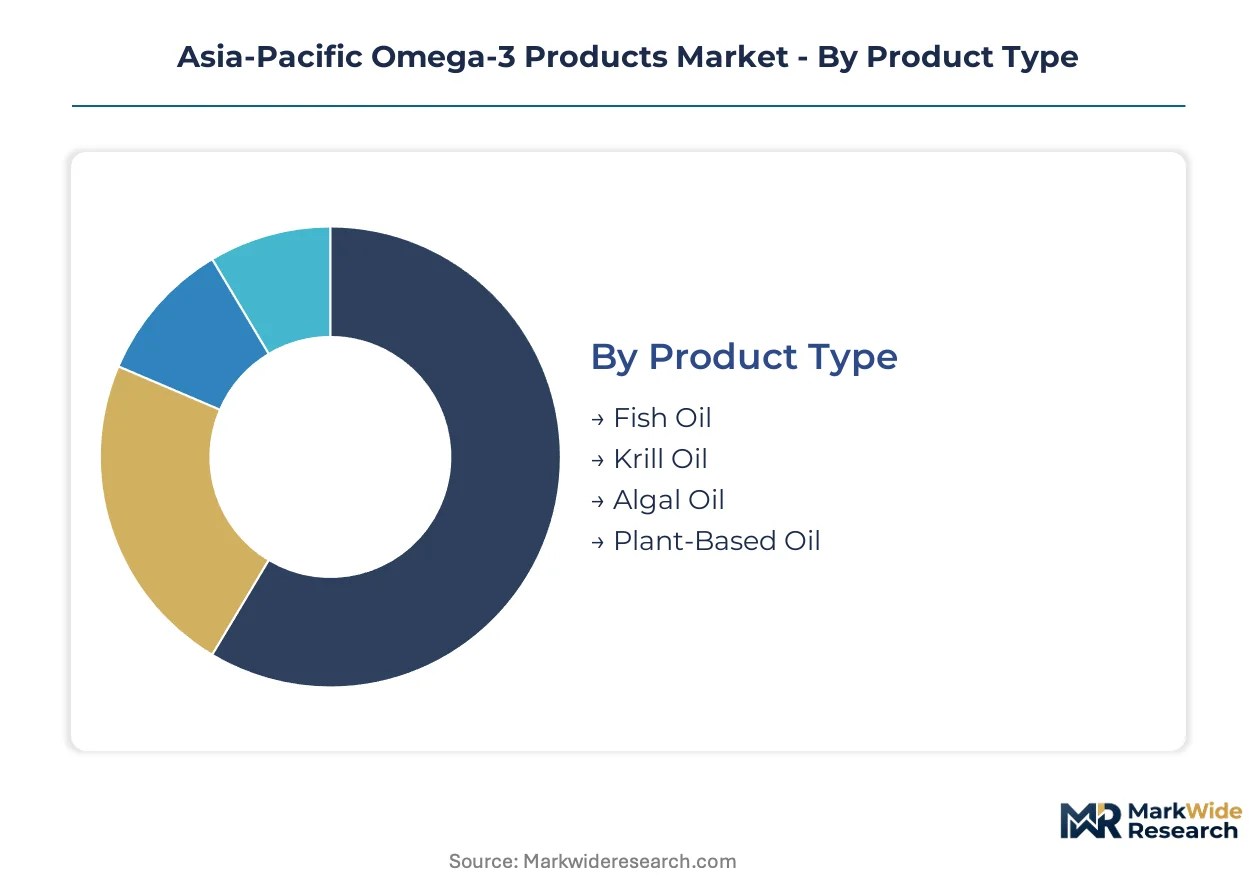
Omega-3 product segmentation in Asia-Pacific reflects divergent margin economics across extraction technologies and channel access. Procurement patterns split between bulk aquaculture feed contracts and premium direct-to-consumer formats with vastly different unit economics.
Product Type:
Margin pools concentrate in pharmaceutical-grade concentrates and vegan-positioned specialty oils where certification barriers limit competitor entry.
- Fish Oil:Anchovy and sardine-derived crude oils refined through molecular distillation to 30-90% EPA-DHA concentrations. China's coastal provinces absorb volume for aquaculture feed fortification while Japanese and South Korean buyers specify supercritical CO2 extraction for contaminant-sensitive applications.
- Algal Oil:Fermentation-cultivated Schizochytrium and Crypthecodinium strains yielding DHA-dominant oils free from marine contaminants. South Korea's MFDS novel food pathway accelerates brand launches targeting K-beauty adjacent wellness consumers willing to pay vegan premiums.
- Krill Oil:Antarctic Euphausia superba extracts combining omega-3s with phospholipid carriers and astaxanthin antioxidants.
- Plant-Based Oil:Flax, chia, and algal-fermentation oils capturing price-sensitive segments in India and Southeast Asia where ALA conversion limitations matter less than label positioning.
Fish oil holds installed capacity across Malaysian and Indonesian processing hubs. Algal oil is rotating up the share rankings as pharmaceutical-grade fermentation scales in China and Singapore.
End User:
Application-driven demand splits between regulated clinical channels with extended approval timelines and fast-moving consumer goods with compressed innovation cycles.
- Health Supplements:Softgel and liquid concentrates distributed through pharmacy, practitioner, and direct-to-consumer channels. Australia's TGA registration requirements favor established brands with third-party certification over import-only competitors.
- Pharmaceuticals:Prescription-grade EPA and DHA concentrates for cardiovascular and cognitive therapeutic endpoints. Japan's MHLW Foods with Function Claims pathway permits direct health messaging unavailable to conventional supplement formats.
- Animal Feed:Bulk DHA enrichment for farmed salmon and shrimp diets to improve fillet nutritional profiles for export markets.
- Functional Foods:Microencapsulated omega-3 powders embedded into dairy, infant formula, and bakery applications requiring ambient stability.
Health supplements command shelf space density. Functional foods are rotating up the share rankings as microencapsulation unlocks distribution into China's tier-three cities.
Distribution Channel:
Channel economics fragment between high-touch pharmacy consultations and algorithm-driven e-commerce with divergent customer acquisition costs.
- Pharmacies:Practitioner-recommended and TGA-registered formulations commanding premium positioning through trusted intermediary validation. Australian pharmacy chains now delist non-compliant SKUs following 2023 label-claim verification overhauls.
- Online Retail:Direct-to-consumer platforms enabling personalized dosing protocols and subscription models. Telehealth integration in Singapore and Australia bypasses retail margin extraction for clinically positioned brands.
- Specialty Stores:Health food and sports nutrition retailers targeting enthusiast consumers with high-potency concentrates.
- Supermarkets:Mass-market functional food and standard-strength supplement placements competing on price-per-unit.
Pharmacies hold installed regulatory relationships. Online retail is rotating up the share rankings as logistics infrastructure penetrates secondary cities.
Form:
Format selection trades manufacturing complexity against dosing precision and consumer convenience preferences.
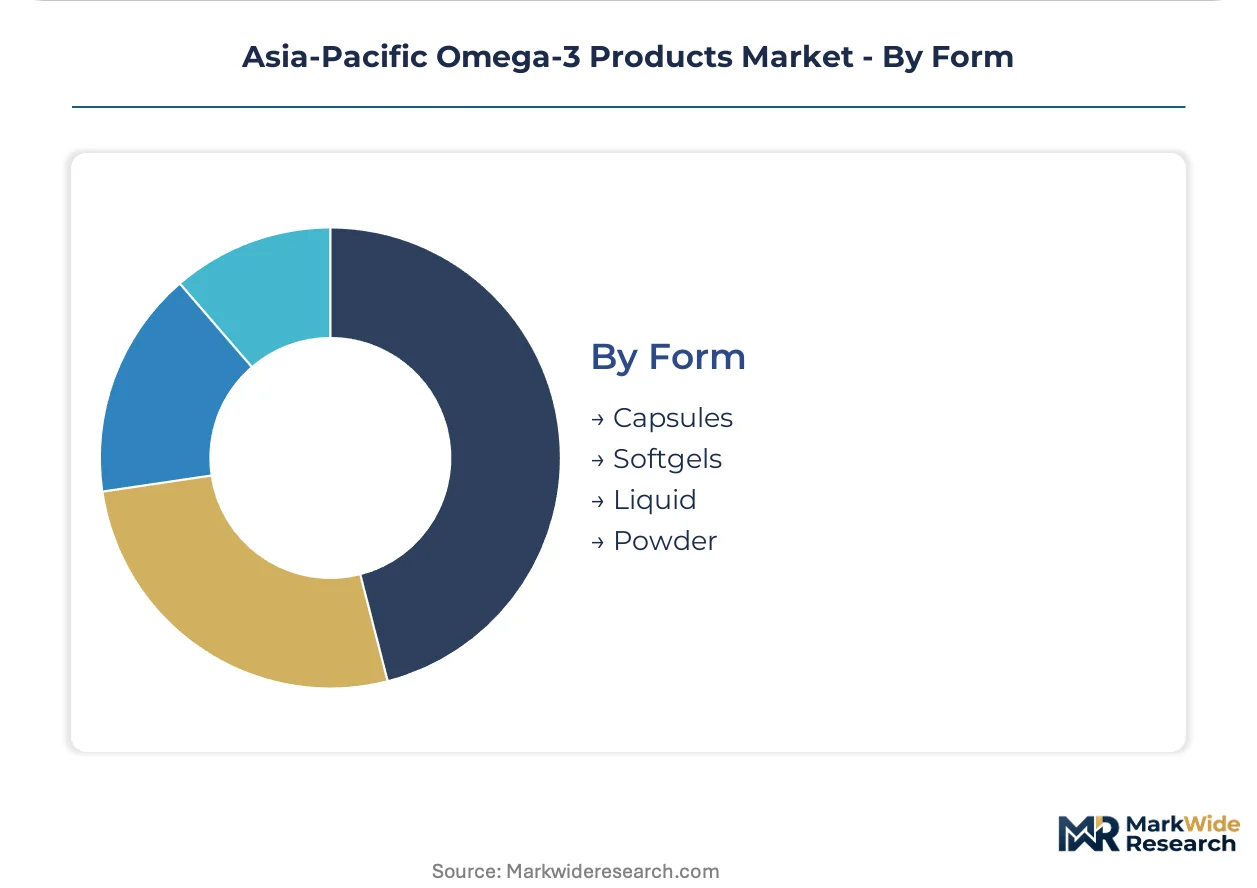
- Softgels:Gelatin or plant-based capsules containing 30-90% EPA-DHA concentrates, dominating consumer-facing channels through familiar dosing formats and oxidation protection.
- Liquid:High-potency concentrates for clinical nutrition and pediatric applications where weight-based dosing precision matters. Margin pools concentrate in pharmaceutical and aged-care procurement consortia across China's Jiangsu and Zhejiang provinces.
- Capsules:Two-piece hard shells for powder and granule formulations with modified-release characteristics.
- Powder:Microencapsulated and free-flowing formats for functional food integration and sachet-based convenience positioning.
Softgels hold installed capacity across Southeast Asian contract manufacturers. Powder is rotating up the share rankings as dairy and infant nutrition applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply: China and Vietnam prioritize aquaculture feed fortification, while Japan and South Korea concentrate spending on pharmaceutical-grade concentrates for aging populations. Australia's pharmacy channel anchors premium supplement demand through practitioner validation.
China
Coastal provinces Jiangsu and Zhejiang drive volume through hospital procurement consortia consolidating omega-3 purchasing for aged-care facilities. NMPA pharmaceutical-grade registration requirements filter supplier eligibility, favoring domestic producers with GMP-certified warehousing over import-reliant competitors. Qingdao and Dalian processing clusters expand algal-derived EPA and DHA fermentation capacity as pharmaceutical-grade extraction infrastructure scales.
Japan
Aging demographics and cardiovascular health awareness concentrate demand in high-potency concentrates for clinical nutrition. MHLW's Foods with Function Claims pathway permits direct cognitive and heart health messaging unavailable to conventional supplement formats, unlocking premium positioning. Tokyo and Osaka metropolitan areas anchor practitioner-channel distribution for prescription-grade EPA-DHA formulations.
South Korea
K-beauty adjacent wellness consumers drive fastest expansion in vegan-positioned algal oils. MFDS novel food ingredient pathway accelerates safety assessment timelines for single-cell DHA oils, compressing brand launch cycles. Seoul Capital Area and Busan-Ulsan clusters concentrate fermentation biotechnology investment from domestic nutraceutical manufacturers.
Australia
Pharmacy and practitioner channels dominate premium supplement distribution through TGA-registered formulations. TGA's 2023 label-claim verification overhaul delisted non-compliant SKUs from major chains, redirecting shelf space toward third-party certified alternatives. Sydney and Melbourne metropolitan markets anchor telehealth-integrated direct-to-consumer platforms enabling personalized dosing protocols.
Vietnam
Aquaculture export competitiveness drives DHA enrichment mandates for farmed pangasius and shrimp destined for EU and US markets. General Department of Fisheries feed quality standards align with importing jurisdiction requirements, creating compliance-driven demand for high-potency concentrates. Mekong Delta processing hubs integrate omega-3 fortification into integrated aquafeed manufacturing.
Asia-Pacific Omega-3 Products Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational nutrition conglomerates controlling raw material flows through backward integration while regional brands defend pharmacy-channel positioning. Market structure reflects dual consolidation patterns: upstream fisheries and fermentation capacity concentrate among agribusiness conglomerates, while downstream formulation fragments across domestic supplement specialists. Two strategic archetypes dominate—vertically integrated raw material processors and regulatory-certified pharmacy-channel brands. Competitive intensity centers on certification acquisition speed and practitioner-channel access rather than price compression.
Among Asia-Pacific anchored specialists, Blackmores exemplifies the TGA-registered pharmacy-channel archetype, while Cargill occupies the upstream integration position controlling Peruvian and Chilean anchovy supply flows. Nestle represents the functional food embedding strategy, leveraging microencapsulation technology to distribute omega-3 powders through mainstream dairy and infant nutrition lines. These three anchors illustrate how competitive positioning splits between raw material security, regulatory certification, and format innovation vectors.
| Leading Market Players |
|---|
| Unilever |
| Nestle |
| Amway |
| Abbott Laboratories |
| HealthViva |
| Reckitt Benckiser Group |
| Herbalife Nutrition |
| Blackmores |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Peruvian anchovy processors and Chinese aquaculture feed manufacturers lock in eighteen-month price visibility while insulating buyers from El Niño-driven quota volatility. These arrangements concentrate procurement power among NMPA-registered domestic producers with GMP-certified warehousing, compressing spot-market liquidity for import-reliant competitors.
Pricing Analysis
Contract-based long-term offtake dominates pharmaceutical-grade concentrate procurement, while spot transactions persist for standard-grade aquaculture feed applications. Price differentiation hinges on IFOS certification tier and supercritical CO2 processing premiums versus molecular distillation baseline. Cost compression in standard-grade fish oil intensifies as algal fermentation capacity scales in Singapore and Qingdao. Aquaculture feed buyers exhibit highest price sensitivity; clinical nutrition procurement consortia in Jiangsu province absorb certification premiums with minimal elasticity.
Supply Chain Analysis
Inventory cycles stretch to ninety days for pharmaceutical-grade concentrates subject to NMPA batch-release protocols, compressing working capital for mid-scale processors. Raw material flows draw from Peruvian and Chilean anchovy fisheries, Chinese Schizochytrium fermentation facilities, and Antarctic krill harvesting operations. Single-source vulnerability concentrates in Peruvian anchovy quotas, where El Niño cycles disrupt input availability without regional substitutes at equivalent cost structures. Distribution runs through hospital procurement consortia in coastal China, pharmacy chains in Australia, and direct-to-consumer platforms integrated with telehealth services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive dynamics as microencapsulation technology enables functional food embedding, creating interoperability between pharmaceutical-grade suppliers and mainstream dairy processors that bypasses traditional supplement channel gatekeepers.
For Market Incumbents: Secure backward integration into fermentation-cultivation capacity before algal oil cost curves intersect fish oil parity. Anchor pharmacy-channel positioning through TGA registration maintenance and IFOS certification renewal, as Australia's 2023 label-claim verification overhaul permanently delisted non-compliant competitors. Threat substitution from plant-based ALA oils in India demands premium-concentrate differentiation through clinical dosing protocols. For New Entrants and Emerging Players: Lead with vegan-positioned algal oils through South Korea's MFDS novel food pathway, where streamlined safety assessments compress launch timelines versus Japanese or Australian regulatory routes. Target K-beauty adjacent wellness consumers in Seoul Capital Area through subscription-based direct-to-consumer platforms. Go-to-market execution should emphasize telehealth-integrated personalized dosing to bypass retail margin extraction. For Investors and Strategic Acquirers: Fermentation-technology specialists with NMPA pharmaceutical-grade registrations represent the highest-conviction acquisition archetype, given China's hospital procurement consolidation and import-substitution policy tailwinds. Long-term viability across the analysis window rests on algal oil achieving cost parity with marine sources. Signal to monitor: MFDS approval velocity for single-cell DHA oils as proxy for regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captures algal oil margin expansion as pharmaceutical-grade extraction scales in China. |
| TGA Registration and IFOS Certification Investment | Secures pharmacy shelf access following Australia's 2023 label-claim verification overhaul. |
| Microencapsulation Technology Deployment | Enables ambient-stable distribution into China's tier-three cities lacking cold-chain infrastructure. |
| MFDS Novel Food Pathway Navigation | Accelerates time-to-market for vegan-positioned supplements targeting South Korean wellness consumers. |
| Telehealth Platform Integration | Bypasses retail margin extraction through personalized dosing protocols in Australia and Singapore. |
Study Parameters
Operator-level perspectives from marine biochemists at Southeast Asian processing hubs, procurement directors at Chinese aquaculture feed manufacturers, regulatory affairs specialists navigating NMPA pharmaceutical-grade registrations, and pharmacy category managers at Australian retail chains anchored the qualitative base. Secondary validation drew from NMPA drug approval databases, TGA registration filings, MFDS novel food safety assessments, customs trade records for anchovy oil imports, and GOED market reports. Bottom-up volume estimates from extraction capacity utilization triangulated against top-down demand aggregation across health supplement, pharmaceutical, and aquaculture feed end uses.
Sensitivity analysis tested forecast outputs against regulatory approval timeline variations, El Niño cycle intensity assumptions, and algal fermentation cost reduction trajectories. Segmentation dimensions modeled encompassed extraction technology, EPA-DHA potency tier, certification status, end-use application, and distribution channel structure. CAGRs were derived from segment-level growth rate synthesis weighted by current revenue contribution, with pharmaceutical-grade concentrate premiums and functional food embedding rates as key omega-3 specific inputs across the projection horizon.
Forecasts assume regulatory continuity in NMPA pharmaceutical-grade tracking requirements, TGA label-claim verification standards, and MFDS novel food assessment protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Energy Supplements Market