
 GLP-1 Hydration Product Market | 2026-2036
GLP-1 Hydration Product Market Size, Share, and Industry Trends Forecast 2026-2036
GLP-1 Hydration Product Market Insights
Modular bundling of electrolyte sachets with GLP-1 starter kits is recalibrating how patients initiate therapy. Abbott leverages its clinical nutrition heritage to anchor hospital pharmacy contracts. Nestlé Health Science sustains R&D intensity across metabolic health portfolios. Liquid I.V. differentiates through flavor-forward positioning in direct-to-consumer channels.
GLP-1 hydration products are electrolyte-dense formulations engineered to counteract the gastrointestinal side effects of incretin-based therapies, typically delivering sodium, potassium, and magnesium in ratios calibrated to osmotic balance. Oral solutions currently dominate pharmacy shelves due to immediate bioavailability and patient familiarity, while effervescent tablets represent the fastest-growing configuration as consumers prioritize portability and precise dosing. The therapy area segmentation reveals diabetes management as the mature revenue base, with weight control applications capturing expanding margin pools as off-label prescribing broadens the addressable population.
The FDA oversees hydration product labeling and health claims through its food and supplement regulatory pathways, while the EPA monitors water quality standards affecting base ingredient sourcing. ISO certification for medical-grade electrolyte manufacturing is becoming a de facto market access requirement for hospital procurement committees. Stakeholders must monitor evolving compounding pharmacy regulations that could reclassify certain hydration adjuncts as prescription-restricted items.
Market Dynamics
The GLP-1 Hydration Product Market is being fundamentally restructured by pharmacy chains consolidating shelf space into dedicated metabolic wellness aisles, creating a new gatekeeper layer between manufacturers and patients.
Growth Catalysts
- Hospital formulary expansion:Weight control clinics in the United States now bundle electrolyte sachets with incretin therapy starter kits, normalizing hydration adjuncts as standard-of-care components.
- REACH compliance alignment:European electrolyte manufacturers leveraging existing pharmaceutical-grade certification pathways are accelerating market entry for medical hydration products.
- Effervescent tablet chemistry:Advances in rapid-dissolution mineral bonding are enabling precise osmotic ratios without liquid formulation constraints, expanding portability for ambulatory patients.
Market Restraints
- Magnesium carbonate sourcing:Concentration of pharmaceutical-grade mineral suppliers in China's Sichuan province creates single-point vulnerability for electrolyte density specifications.
- Compounding pharmacy reclassification risk:Draft FDA guidance on pharmacy-manufactured hydration solutions threatens to shift certain adjuncts behind prescription barriers, constraining direct-to-consumer channels.
- Oral rehydration salt substitution:Low-cost WHO-formulation ORS packets remain clinically acceptable for mild GLP-1 side effects, capping premium pricing power in price-sensitive patient segments.
Strategic Opportunities
- Brazil's ANVISA fast-track:The regulatory pathway for metabolic support supplements offers first-mover positioning as GLP-1 adoption accelerates in Latin America's largest pharmacy market.
- Continuous glucose monitor integration:Data-linked hydration recommendations paired with real-time glycemic tracking create a new software-enabled service layer around physical products.
- Subscription pharmacy models:CVS and Walgreens auto-refill programs are opening dedicated slots for electrolyte replenishment cycles synchronized to injection schedules.
Industry Challenges
- ISO 13485 certification timelines:Medical-device-grade electrolyte manufacturing qualification requires 18-24 month validation cycles that lag behind formulation innovation.
- Flavor-chemistry talent scarcity:The intersection of pediatric palatability science and adult metabolic dosing precision demands specialists rarely found in conventional beverage R&D pools.
- Legacy pharmacy inventory systems:ERP platforms designed for pill-count dispensing struggle with weight-based powder dosing and reconstitution instructions, forcing manual workaround implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GLP-1 Hydration Product Market |
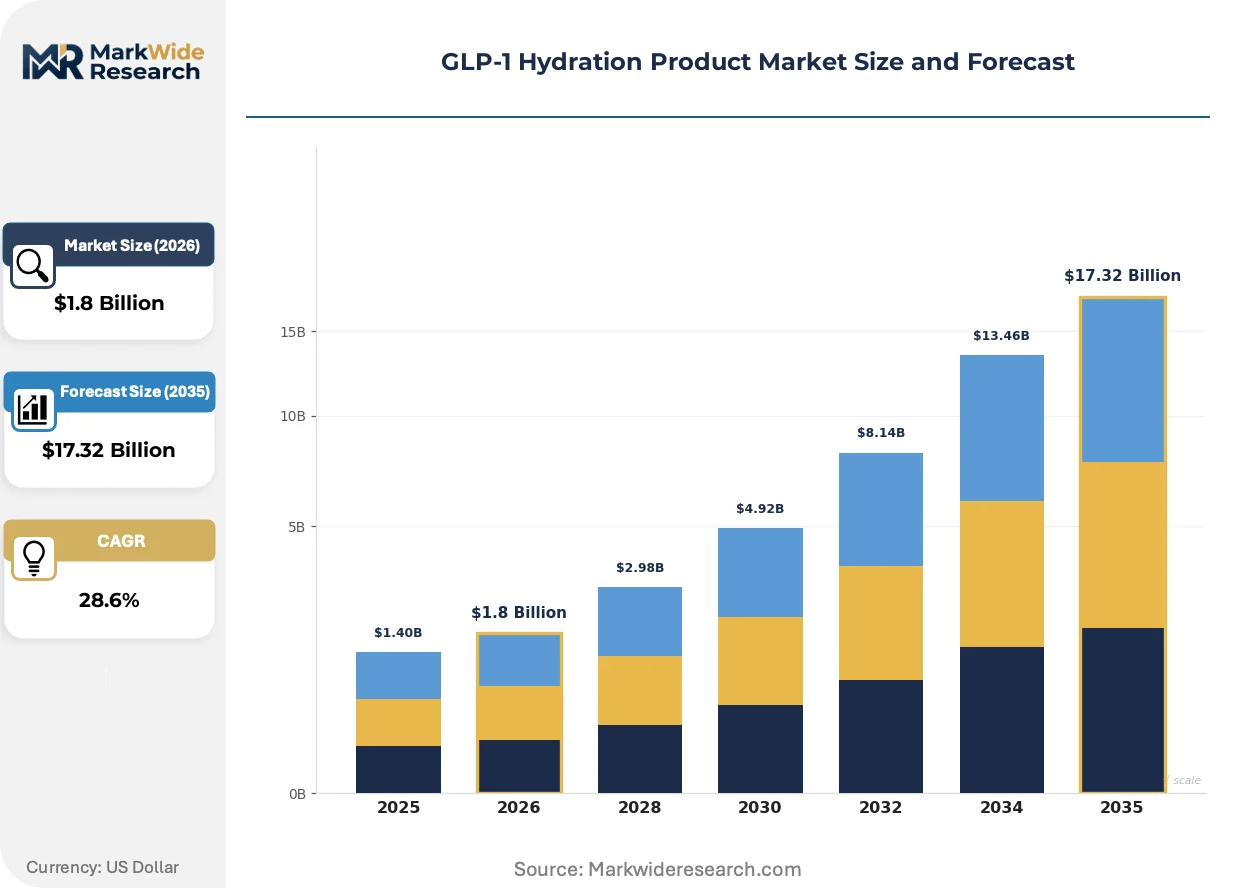
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Solutions, Injectable Formulations, Powders, Capsules, Effervescent Tablets Therapy Area: Diabetes Management, Weight Control, Appetite Regulation, Metabolic Syndrome, Cardiovascular Support End User: Hospitals, Outpatient Clinics, Wellness Centers, Home Healthcare Providers, Specialized Pharmacies Distribution Channel: Pharmacies, Online Retailers, Direct Sales, Hospitals Pharmacy Units, Health Food Stores |
| Companies Covered | Abbott, Nestlé Health Science, Liquid I.V., Electrolit, DripDrop, Nuun, Ultima Replenisher, LMNT, Smoothie King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GLP-1 Hydration Product Market Trends and Innovations
Formulation science and channel architecture are diverging sharply as manufacturers bet on contrasting paths to patient adherence. The next phase favors precision over convenience.
Effervescent electrolyte tablets is overtaking ready-to-drink bottles as the dominant delivery format among patients managing weekly injection schedules. Hospital discharge planners in the United States now specify effervescent configurations for home-bound diabetes patients, compressing liquid logistics costs while preserving dosing accuracy. This shift is overtaking the historical pharmacy preference for pre-mixed solutions, forcing reformulation of mineral stability matrices.
The FDA's expanded labeling requirements for electrolyte health claims are tightening permissible language around nausea mitigation and fluid balance. Manufacturers must now submit clinical substantiation for any mention of GLP-1 therapy adjacency, raising documentation burdens but also creating defensible positioning for compliant entrants. Diabetes management applications face the steepest compliance adjustment, while weight control segments exploit regulatory gray zones with broader functional claims.
Patients are consolidating purchasing decisions through prescriber-affiliated digital pharmacies rather than retail aisles. Endocrinology practices in Texas and Florida now white-label hydration products through proprietary patient portals, disintermediating traditional drugstore channels. This concentration is most visible in Medicare Advantage populations where integrated care contracts bundle supplies into capitated payments.
GLP-1 Hydration Product Market Segmentation
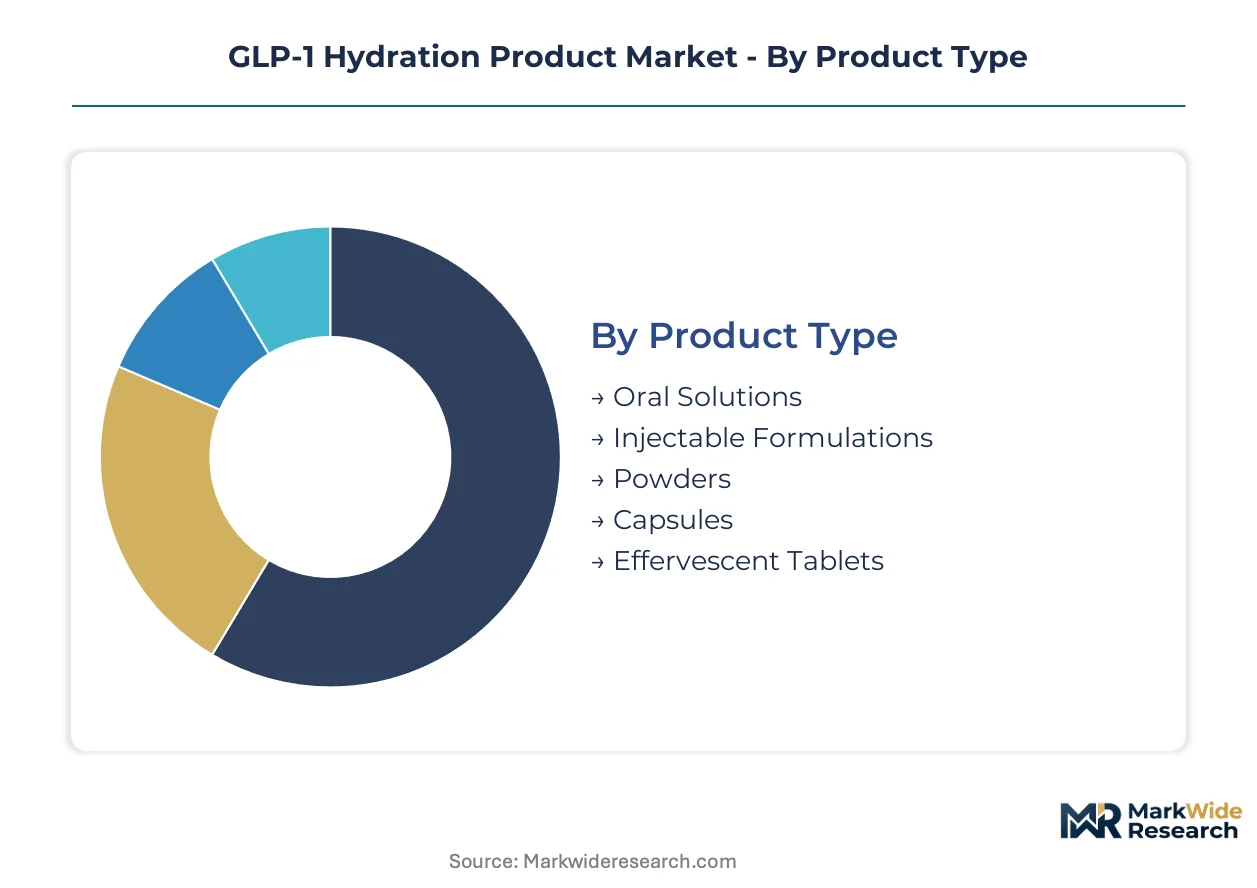
GLP-1 hydration products fragment across formulation chemistry, clinical application, and procurement pathway. Each segmentation axis reveals divergent margin structures and regulatory exposure that determine competitive positioning.
Product Type:
Supply concentration in pharmaceutical-grade mineral sourcing favors manufacturers with backward integration into electrolyte bonding chemistry.
- Oral Solutions:Pre-mixed sodium-potassium-magnesium formulations dominate hospital discharge protocols due to immediate bioavailability. Demand concentrates in United States weight control clinics where starter kit bundling normalizes adjunct hydration as standard-of-care.
- Effervescent Tablets:Rapid-dissolution mineral matrices enable precise osmotic ratios without liquid logistics. United States Medicare Advantage populations favor this format for home-based weekly injection schedules, compressing shipping costs while preserving dosing accuracy.
- Injectable Formulations:Parenteral electrolyte delivery reserved for acute dehydration cases in hospital settings.
- Powders:Weight-based sachet dosing requires reconstitution, creating inventory tracking challenges for legacy pharmacy ERP systems.
- Capsules:Solid-dose mineral delivery trades hydration speed for patient convenience in travel scenarios.
Today's leader: Oral Solutions. Tomorrow's challenger: Effervescent Tablets.
Therapy Area:
Cost tier stratification separates premium-priced weight control applications from reimbursement-constrained diabetes management.
- Diabetes Management:Mature reimbursement pathways through Medicare Part D anchor volume but cap pricing power. FDA labeling requirements for electrolyte health claims impose steepest compliance burdens here, demanding clinical substantiation for nausea mitigation language.
- Weight Control:Off-label incretin prescribing expands addressable population beyond diabetes-coded patients. United States pharmacy chains capture expanding margin pools through dedicated metabolic wellness aisles that bundle hydration adjuncts with GLP-1 prescriptions.
- Appetite Regulation:Adjunct hydration supporting peptide therapy tolerance in eating disorder protocols.
- Metabolic Syndrome:Multi-condition patients requiring polypharmacy-compatible electrolyte profiles.
- Cardiovascular Support:Potassium-constrained formulations for patients on concurrent ACE inhibitor therapy.
Diabetes Management holds current volume dominance. Weight Control climbs the fastest trajectory as direct-to-consumer channels exploit regulatory gray zones.
End User:
Customer type determines procurement rigor — hospital formulary committees demand ISO 13485 certification that excludes commodity beverage suppliers.
- Hospitals:Inpatient electrolyte replacement protocols specify medical-grade manufacturing with 18-24 month validation cycles. Formulary expansion in United States weight control clinics now bundles sachets with incretin starter kits.
- Outpatient Clinics:Ambulatory settings prioritize portability and patient education materials over institutional packaging.
- Wellness Centers:Non-clinical metabolic support programs favor flavor-forward positioning over clinical dosing precision.
- Home Healthcare Providers:Logistics networks optimized for durable medical equipment struggle with temperature-sensitive liquid formulations.
- Specialized Pharmacies:Compounding pharmacy reclassification risk threatens to shift certain hydration adjuncts behind prescription barriers.
Hospitals command procurement standards today. Specialized Pharmacies face the steepest structural uncertainty tomorrow.
Distribution Channel:
Geography of patient access is shifting from retail aisle browsing toward prescriber-affiliated digital portals.
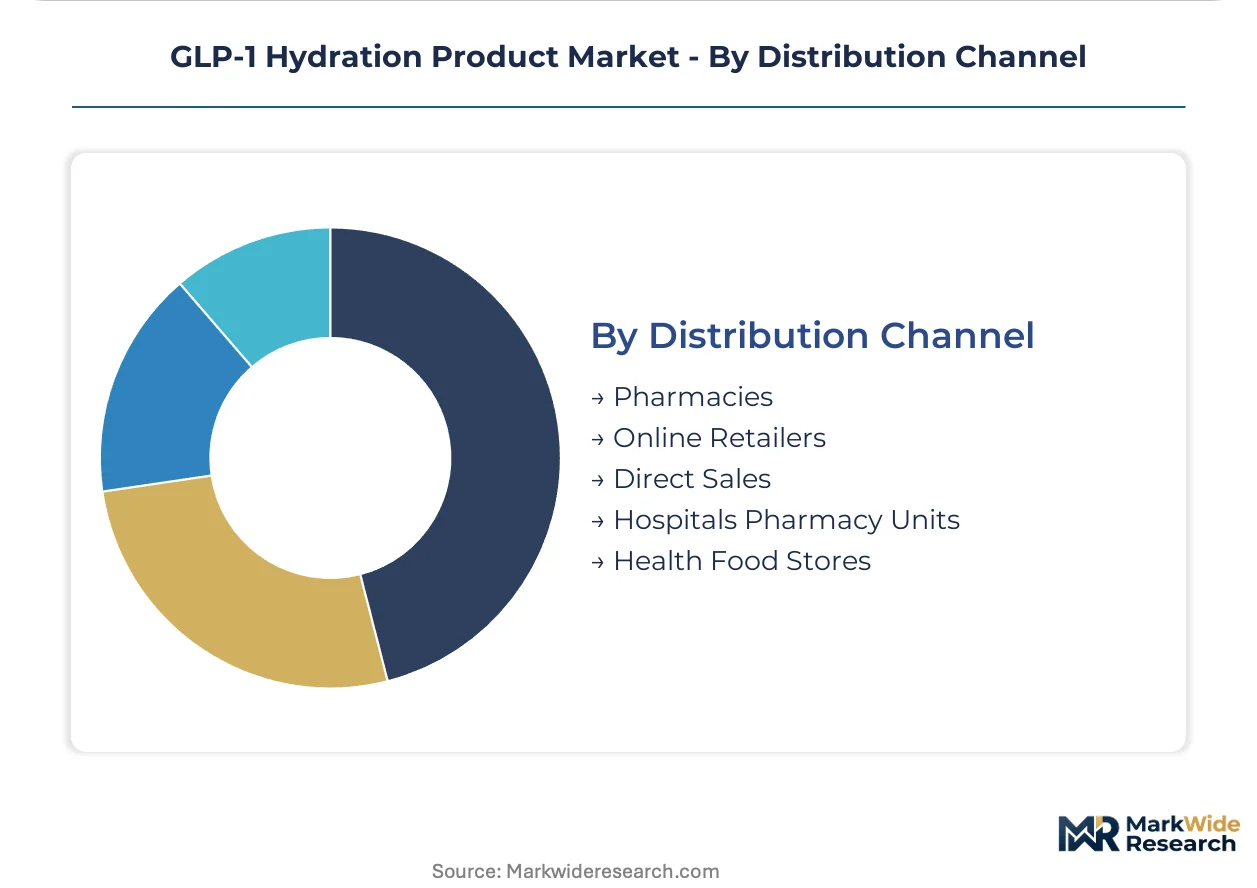
- Pharmacies:United States chains CVS and Walgreens consolidate shelf space into dedicated metabolic wellness aisles, creating new gatekeeper leverage. Auto-refill programs now synchronize electrolyte replenishment cycles to injection schedules.
- Online Retailers:Direct-to-consumer velocity depends on flavor-chemistry differentiation and subscription mechanics.
- Direct Sales:Endocrinology practices in Texas and Florida white-label hydration products through proprietary patient portals, disintermediating traditional drugstore channels.
- Hospitals Pharmacy Units:Captive demand from discharge planning specifications favors effervescent configurations.
- Health Food Stores:WHO-formulation ORS substitution risk caps premium positioning in price-sensitive segments.
Pharmacies anchor current volume. Direct Sales gains share fastest as integrated care contracts bundle supplies into capitated payments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GLP-1 hydration product industry traces its commercial origins to United States pharmacy chains that pioneered dedicated metabolic wellness aisles alongside incretin therapy rollouts.
United States
CVS and Walgreens auto-refill programs now synchronize electrolyte replenishment cycles to weekly injection schedules. FDA expanded labeling requirements for electrolyte health claims tighten permissible nausea mitigation language. Texas and Florida endocrinology practices white-label hydration products through proprietary patient portals, disintermediating traditional drugstore channels.
Brazil
ANVISA fast-track regulatory pathways for metabolic support supplements attract first-mover positioning as GLP-1 adoption accelerates. The national pharmaceutical regulator maintains streamlined supplement registration distinct from pharmaceutical approval. São Paulo pharmacy chains build dedicated wellness sections mirroring United States retail consolidation patterns.
Germany
REACH compliance alignment enables European electrolyte manufacturers to leverage existing pharmaceutical-grade certification for medical hydration entry. EMA oversight of borderline products between food and medical categories shapes formulation documentation burdens. Bavaria-based clinical nutrition specialists anchor hospital formulary contracts across German-speaking markets.
China
Pharmaceutical-grade magnesium carbonate sourcing concentrates in Sichuan province, creating single-point vulnerability for electrolyte density specifications. NMPA medical device classification pathways for hydration adjuncts remain under draft consultation. Shanghai and Beijing hospital procurement committees increasingly require ISO 13485 certification for electrolyte manufacturing.
Japan
PMDA consultation on functional food claims for GLP-1 adjacency products proceeds through 2025 review cycles. METI industrial standards for medical-grade mineral bonding chemistry influence regional supplier qualification. Osaka-Kobe pharmaceutical manufacturing clusters develop effervescent tablet rapid-dissolution capabilities for export markets.
GLP-1 Hydration Product Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier differentiation, with ISO 13485 medical-grade qualification separating hospital formulary winners from retail commodity suppliers. The vendor base spans clinical nutrition heritage companies, direct-to-consumer flavor specialists, and pharmaceutical-grade mineral bonders. Three archetypes dominate: hospital-contract anchors, subscription-channel disrupters, and compounding pharmacy suppliers. Competitive moves concentrate on backward integration into electrolyte sourcing and white-label portal partnerships with prescriber networks.
Among clinical nutrition anchors, Abbott and Nestlé Health Science exemplify the hospital-contract tier through their metabolic health portfolio breadth. Liquid I.V. occupies a position within the direct-to-consumer flavor-forward archetype, representing subscription-channel mechanics that bypass traditional pharmacy gatekeepers. These three entities collectively illustrate how certification depth, channel architecture, and formulation chemistry define competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Abbott |
| Nestlé Health Science |
| Liquid I.V. |
| Electrolit |
| DripDrop |
| Nuun |
| Ultima Replenisher |
| LMNT |
| Smoothie King |
| Others |
Pricing and Supply Chain Analysis
Backward integration into pharmaceutical-grade mineral bonding chemistry anchors both supply security and pricing power for electrolyte manufacturers serving hospital formulary committees. Abbott and Nestlé Health Science leverage captive production of sodium-potassium-magnesium matrices to defend margin positions against commodity beverage competitors while ISO 13485 certification requirements create tiered procurement access that separates medical-grade suppliers from retail-channel entrants.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the GLP-1 hydration product landscape. Premium tiers command formulary placement through ISO 13485 medical-device certification and clinical substantiation packages submitted to FDA labeling reviewers, while standard tiers compete on pharmacy shelf space through flavor-forward positioning and subscription mechanics. Price differentiation rests on certification grade and channel control, with cost compression in the economy tier intensifying because WHO-formulation oral rehydration salts remain clinically acceptable substitutes. Medicare Advantage populations show least price sensitivity due to capitated bundled payments, whereas cash-pay patients in health food stores exhibit highest substitution elasticity toward generic electrolyte alternatives.
Supply Chain Analysis
Direct-to-hospital pharmacy units handle institutional demand through formulary contracting, while direct-to-consumer channels and prescriber-affiliated digital portals manage ambulatory patient access. Pharmaceutical-grade magnesium carbonate sourcing concentrates in China's Sichuan province, with secondary mineral bonding capacity in Germany's Bavaria region and Japan's Osaka-Kobe pharmaceutical clusters. Raw material dependencies center on sodium chloride, potassium citrate, and magnesium carbonate feedstocks. Single-source vulnerability in Sichuan province creates supply chain risk for electrolyte density specifications, particularly as NMPA medical device classification pathways remain under draft consultation. Distribution runs through three parallel pathways: hospital discharge specifications, pharmacy chain metabolic wellness aisles, and endocrinology practice white-label portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GLP-1 hydration product market functions as a stable compounder anchored by the structural expansion of pharmacy-chain metabolic wellness aisles that normalize hydration adjuncts as standard-of-care components alongside incretin therapy rollouts.
For Market Incumbents: To counter compounding pharmacy reclassification risk threatening to shift hydration adjuncts behind prescription barriers, incumbents should deepen backward integration into pharmaceutical-grade mineral sourcing to secure supply continuity while accelerating ISO 13485 certification investments that lock hospital formulary positions before regulatory thresholds tighten. Channel control through prescriber-affiliated digital portal partnerships offers defensive moat construction against retail commoditization. For New Entrants and Emerging Players: Prescriber-affiliated digital pharmacy routes offer the most penetrable entry vector for challengers lacking hospital formulary heritage. Brazil's ANVISA fast-track pathway for metabolic support supplements represents the most accessible geographic white space, with São Paulo pharmacy chains replicating United States retail consolidation patterns. Flavor-chemistry differentiation paired with subscription mechanics enables direct-to-consumer velocity without confronting Abbott's hospital-contract dominance head-on. For Investors and Strategic Acquirers: Roll-up economics work for clinical nutrition specialists with backward integration into electrolyte bonding chemistry because certification depth creates durable procurement barriers that compound over extended holding periods. Target acquisition profiles center on mid-cap manufacturers possessing ISO 13485 qualification but lacking prescriber portal distribution, where channel integration unlocks revenue synergies. The signal to watch is FDA draft guidance finalization on compounding pharmacy reclassification, which would inflect competitive positioning toward prescription-adjacent regulatory expertise.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Medical-device-grade qualification opens hospital formulary access that retail competitors cannot replicate. |
| Prescriber Portal White-Label Partnership | Endocrinology practice disintermediation captures Medicare Advantage bundled payment flows from pharmacy chains. |
| Backward Integration into Mineral Bonding | Captive supply of pharmaceutical-grade magnesium carbonate insulates against Sichuan sourcing concentration risk. |
| Flavor-Chemistry R&D Expansion | Pediatric palatability expertise applied to adult metabolic dosing addresses talent scarcity constraining formulation innovation. |
| ANVISA Fast-Track Market Entry | First-mover positioning in Brazil's accelerating GLP-1 adoption builds Latin American beachhead before competitors consolidate. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with drug development executives at clinical nutrition heritage companies, regulatory affairs leads navigating FDA expanded labeling requirements, formulary directors at United States hospital systems, and pharmacy chain category managers building metabolic wellness aisles. Secondary validation drew from FDA guidance documents, ANVISA regulatory filings, EMA borderline product consultations, hospital procurement database extracts, and pharmacy retail audit data. Bottom-up patient-flow modeling and top-down therapy-area spend analysis were triangulated against manufacturer-reported volume disclosures.
Historical reference periods anchored the projection horizon through documented pharmacy-chain aisle consolidation timelines and incretin therapy adoption curves across diabetes and weight control applications. Segmentation dimensions modeled include formulation chemistry, therapy area, end-user procurement pathway, and distribution channel architecture. CAGRs were derived from patient population expansion, dosing frequency assumptions, and bundled payment penetration rates across Medicare Advantage contracts.
Regulatory reclassification triggers, raw material supply disruptions, and substitution elasticity toward generic oral rehydration salts are the dominant revision risks that could compress forecast trajectories. Forecasts reflect assumptions about formulary expansion continuity and pharmacy-chain shelf-space allocation stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market