
 Bread Emulsifier Market | 2026-2036
Bread Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Emulsifier Market Insights
Enzyme-modified emulsification is narrowing the performance gap between synthetic and plant-derived systems in industrial dough conditioning. Cargill, Incorporated leverages its integrated oilseed processing network to secure raw material cost advantages across European bakery supply chains. Kerry Group plc sustains formulation leadership through specialized bakery application labs in Ireland and the United Kingdom. Palsgaard A/S anchors its competitive position with backward integration into palm oil fractionation and emulsifier manufacturing.
Bread emulsifiers comprise surface-active agents—principally monoglycerides, diglycerides, lecithin derivatives, and sorbitan esters—that reduce interfacial tension between hydrophilic and lipophilic phases in dough systems, typically functioning at inclusion rates of 0.25–1.0% flour weight to improve gas retention, crumb softness, and shelf-life extension. Phospholipid-based formulations command premium positioning in clean-label bakery segments where non-GMO and allergen-free claims determine retail placement. Monoglycerides dominate volume demand across industrial baking channels where cost efficiency and standardized performance outweigh label complexity. Sorbitan esters occupy a specialized niche in frozen dough applications requiring freeze-thaw stability without protein interaction.
EFSA evaluates novel emulsifier safety dossiers under updated food additive protocols, while REACH registration requirements govern chemical intermediate handling for synthetic production routes. Germany's BfR issues specific migration limits for processing aids in direct-contact bakery equipment, influencing emulsifier selection in automated production environments. Stakeholders must monitor evolving EU Single-Use Plastics Directive implications for emulsifier delivery formats and packaging sustainability credentials.
Market Dynamics
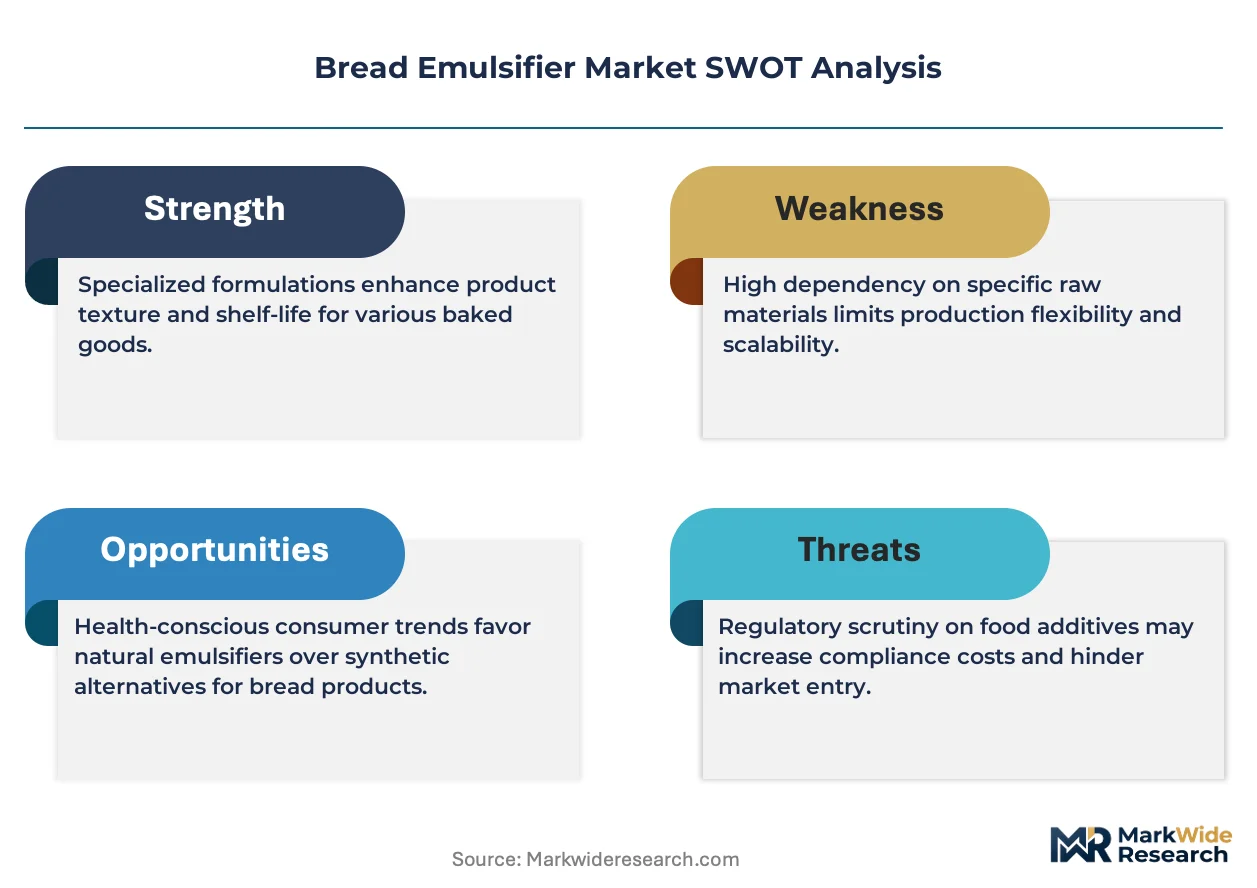
Enzyme-modified emulsification systems are compressing the performance premium historically commanded by synthetic alternatives, forcing reformulation investments across European industrial bakeries and reshaping supplier R&D allocation.
Growth Catalysts
- Clean-label mandates:EFSA's updated food additive evaluation protocols are accelerating manufacturer migration toward phospholipid-based and plant-derived emulsifier portfolios in retail-facing bakery products.
- Artisan bakery expansion:Small-batch producers in Germany, France, and Italy are adopting specialized monoglyceride systems to achieve industrial-grade shelf stability without synthetic additive declarations.
- Frozen dough channels:Sorbitan ester formulations with freeze-thaw stability profiles are capturing specialized demand from commercial foodservice distributors supplying hotel and restaurant chains.
Market Restraints
- Palm oil supply concentration:Backward-integrated emulsifier manufacturers face raw material cost volatility tied to Malaysian and Indonesian palm oil fractionation capacity constraints.
- REACH compliance burden:Chemical intermediate registration requirements for synthetic production routes impose fixed compliance costs that disadvantage smaller European compounders.
- Enzyme substitution threat:Lipase and phospholipase enzyme systems in industrial dough conditioning are displacing volume demand for traditional emulsifier inclusions in certain high-speed baking applications.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania present white-space expansion potential as modern retail bakery formats replace traditional unpackaged bread distribution.
- EU Single-Use Plastics Directive alignment:Emulsifier delivery format innovation—concentrated pastes and water-dispersible granules—addresses packaging sustainability credential requirements in premium retail segments.
- Clean-label certification convergence:Non-GMO Project and EU organic certification stacking creates premium positioning for lecithin derivatives sourced from identity-preserved oilseed supply chains.
Industry Challenges
- Application technical talent scarcity:Industrial bakeries face recruitment gaps for formulation scientists capable of optimizing enzyme-emulsifier synergies in high-hydration dough systems.
- Legacy equipment retrofit costs:Automated production lines designed for powder emulsifier dosing require capital-intensive modification to handle concentrated liquid and paste delivery formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Emulsifier Market |
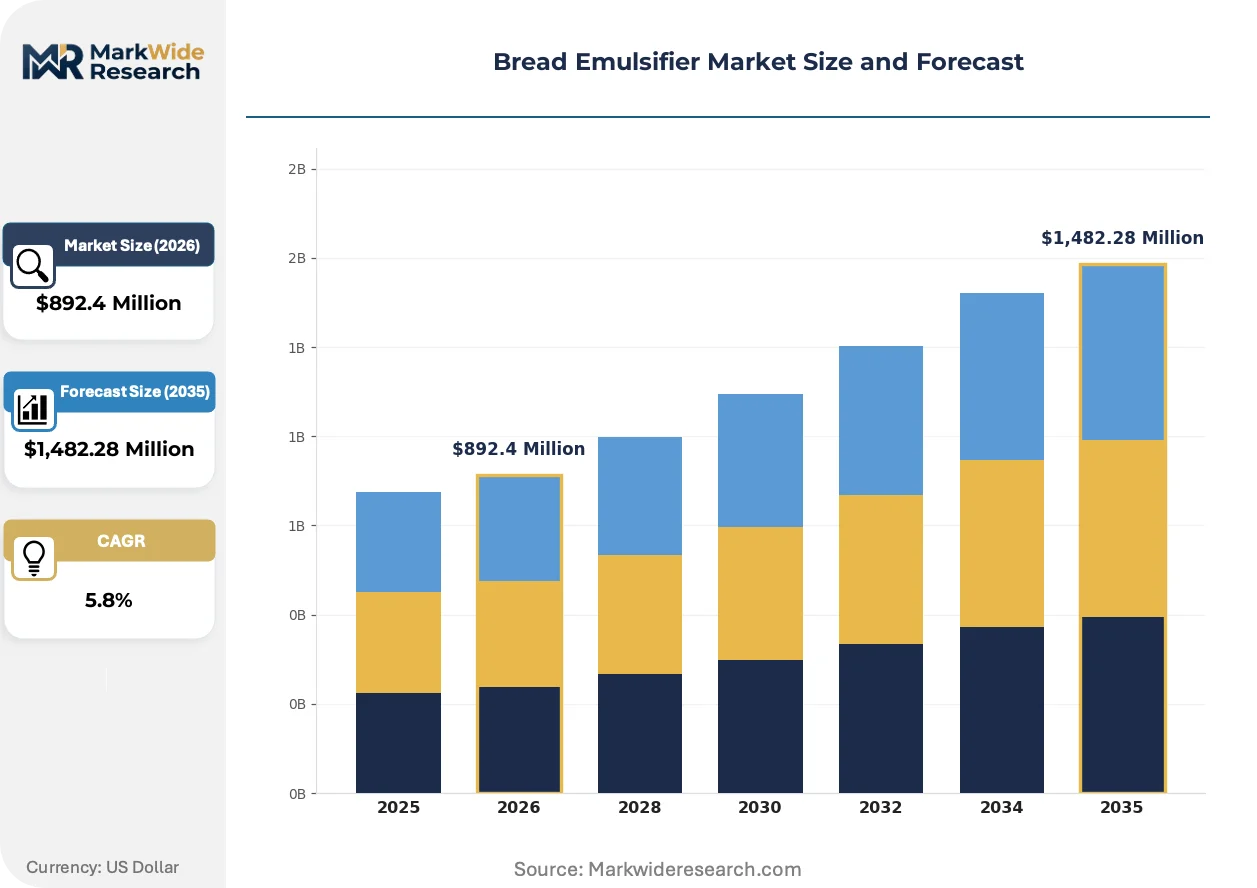
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoglycerides, Diglycerides, Phospholipids, Sorbitan Esters Application: Baking, Snacks, Confectionery, Dairy Formulation Type: Liquid, Powder, Granulated, Emulsion End User: Bakeries, Food Manufacturers, Catering Services, Retail |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, International Flavors & Fragrances, Kerry Group plc, BASF SE, Corbion N.V., Ingredion Incorporated, Palsgaard A/S, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Emulsifier Market Trends and Innovations
Formulation science is converging with regulatory compliance architecture to redefine competitive advantage, as performance specifications and sustainability credentials become inseparable purchasing criteria across European bakery supply chains.
Enzyme-modified emulsification technology is hybridizing the functional profiles of plant-derived and synthetic systems, enabling industrial bakers to achieve standardized crumb softness and gas retention with reduced synthetic additive load. Artisan and mid-scale producers in France and Italy are piloting these hybrid systems at accelerated adoption cycles compared to five-year reformulation norms. The technology is compressing the price-performance tradeoff that previously segmented premium clean-label from standard industrial formulations.
REACH registration requirements for chemical intermediates are tightening documentation burdens on synthetic emulsifier production routes, favoring manufacturers with established compliance infrastructure. EFSA's updated safety dossier protocols are extending novel ingredient approval timelines, creating competitive moats for established phospholipid and monoglyceride suppliers with grandfathered regulatory status. Industrial baking channels are responding by consolidating supplier relationships toward vertically integrated compounders with captive regulatory affairs capabilities.
Buyer procurement patterns are compressing switching cycles as clean-label reformulation mandates accelerate contract renegotiation frequency. Frozen dough and foodservice distributors are disintermediating traditional ingredient merchants through direct sourcing relationships with emulsifier manufacturers, particularly in Germany's centralized bakery supply infrastructure. This channel shift is most visible in the commercial foodservice vertical, where procurement centralization at distributor level is concentrating volume with fewer qualified suppliers capable of delivering combined technical service and sustainability documentation.
Bread Emulsifier Market Segmentation
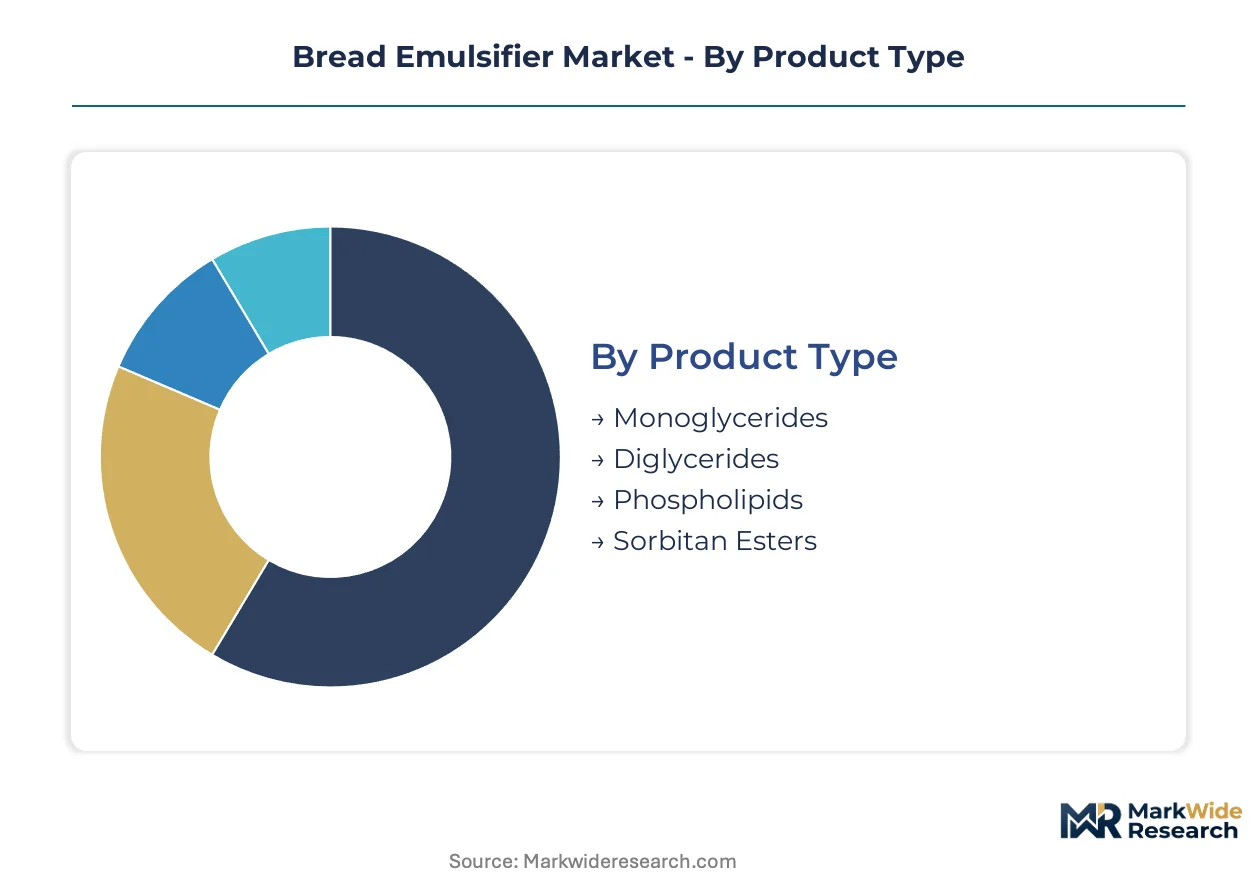
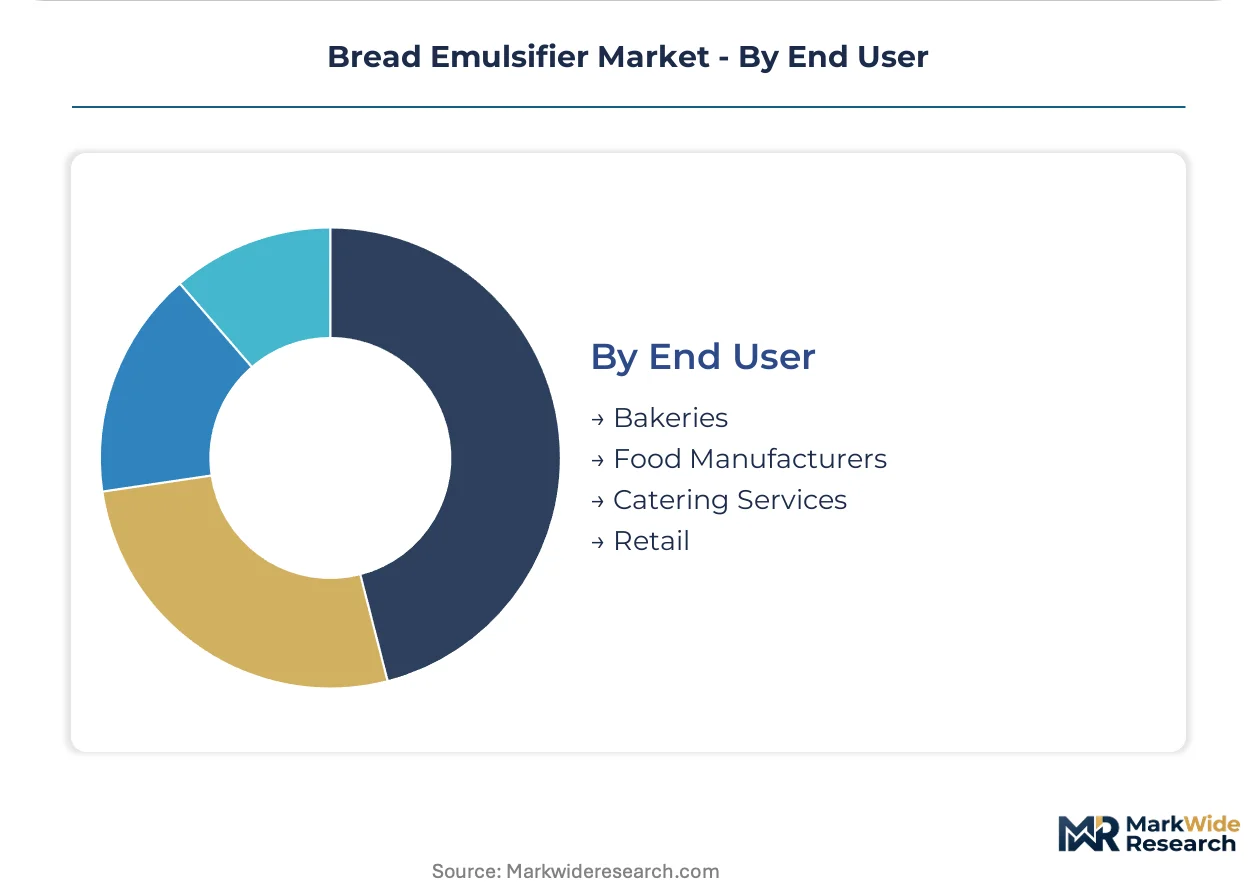
Bread emulsifier segmentation reveals how functional requirements, processing constraints, and label positioning split demand across incompatible technical specifications. Manufacturers optimize formulation investments by mapping these divides to specific production environments and regulatory exposure.
Product Type:
Mature industrial applications anchor volume, while emerging clean-label alternatives reshape premium positioning.
- Monoglycerides:Partial esters of fatty acids and glycerol provide standardized dough conditioning at inclusion rates of 0.25–0.5% flour weight. Industrial bakeries in Germany concentrate demand here, prioritizing cost efficiency and consistent gas retention over label complexity.
- Phospholipids:Lecithin derivatives and modified phospholipids deliver non-GMO and allergen-free credentials for retail-facing products. France and Italy drive adoption as artisan producers seek industrial-grade shelf stability without synthetic additive declarations.
- Diglycerides:Complementary emulsifiers function alongside monoglycerides in high-speed baking lines requiring precise fat distribution control.
- Sorbitan Esters:Specialized freeze-thaw stability profiles serve frozen dough channels and commercial foodservice distributors supplying hotel chains.
Monoglycerides handle the majority of throughput; phospholipids are climbing the fastest on share.
Application:
Cost tier stratification separates commodity-scale baking from premium confectionery and specialized dairy applications.
- Baking:Bread, rolls, and pastry production consumes emulsifiers for crumb softening, volume expansion, and shelf-life extension. German industrial bakeries and France's artisan sector represent the core demand concentration, with clean-label mandates accelerating phospholipid substitution.
- Snacks:Extruded and baked snack applications require emulsifiers for fat encapsulation and texture modification. Poland and Romania show emerging demand as modern retail formats replace traditional distribution.
- Confectionery:Chocolate and coating applications leverage lecithin derivatives for viscosity control and fat bloom prevention.
- Dairy:Whipped toppings and processed cheese systems utilize specialized emulsifier blends for stability and mouthfeel.
Baking commands absolute volume; snacks are expanding most quickly as Eastern European retail modernizes.
Formulation Type:
Customer type divides sharply between automated powder-handling facilities and flexible liquid-dosing operations.
- Powder:Free-flowing granular forms suit high-throughput industrial lines with pneumatic conveying and automated dosing systems. Legacy equipment across Germany's centralized bakery infrastructure locks in powder preference despite handling limitations.
- Liquid:Pumpable concentrates enable precise metering and rapid dispersion in continuous mixing operations. Italy's mid-scale producers favor liquid systems for formulation flexibility and reduced dust exposure.
- Granulated:Low-dust, free-flowing variants bridge powder handling convenience with liquid functional performance.
- Emulsion:Pre-hydrated water-dispersible systems simplify incorporation for bakeries lacking high-shear mixing capacity.
Powder retains installed-base dominance; liquid formats are gaining share fastest through new facility investment.
End User:
Supply concentration favors vertically integrated compounders serving consolidated food manufacturers over fragmented catering channels.
- Food Manufacturers:Industrial-scale producers of packaged bread, frozen dough, and co-manufactured bakery goods source emulsifiers through direct supplier relationships. Centralized procurement in Germany's bakery supply infrastructure concentrates volume with qualified compounders delivering combined technical service and REACH documentation.
- Bakeries:Artisan and mid-scale operations in France and Italy pilot enzyme-modified hybrid systems, compressing adoption cycles compared to five-year reformulation norms.
- Catering Services:Commercial foodservice distributors disintermediate traditional merchants through direct manufacturer relationships, particularly for sorbitan ester formulations with freeze-thaw specifications.
- Retail:Private-label bakery product developers face clean-label certification requirements driving lecithin derivative demand from identity-preserved supply chains.
Food manufacturers handle the majority of throughput; bakeries are the fastest mover on share as artisan adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in emulsifier feedstocks and finished formulations vary sharply across major producing and consuming markets. Palm oil fractionation capacity in Southeast Asia supplies European compounders, while specialized phospholipid production concentrates in North American and European oilseed processing hubs.
Germany
Industrial bakery automation and centralized procurement infrastructure concentrate emulsifier demand in North Rhine-Westphalia and Bavaria. EFSA food additive protocols and BfR migration limits for processing aids govern formulation selection in automated production environments. The Rhine-Ruhr industrial corridor hosts major compounder technical service operations serving pan-European bakery supply chains.
United States
Large-scale oilseed processing and lecithin derivative production anchor phospholipid supply for clean-label bakery applications. FDA food additive regulations and USDA organic certification requirements shape ingredient sourcing for retail-facing products. The Midwest agricultural belt integrates soybean crushing with emulsifier manufacturing, creating captive raw material advantages.
France
Artisan bakery traditions and premium retail positioning accelerate phospholipid adoption for non-GMO and allergen-free claims. ANSM and DGCCRF enforcement of EU food additive labeling rules pressure reformulation away from synthetic emulsifier declarations. The Paris Basin and Lyon corridor concentrate mid-scale producers piloting enzyme-modified hybrid systems.
China
Rapid bakery sector modernization and frozen dough channel expansion drive volume demand for monoglyceride and sorbitan ester formulations. SAMR food additive registration and GB standards for bakery ingredients govern import and domestic production compliance. The Yangtze River Delta industrial cluster concentrates emulsifier manufacturing capacity serving domestic and export markets.
Italy
Artisan bread culture and specialty frozen dough production create differentiated demand for clean-label emulsifier systems. Ministry of Health enforcement of EU food additive regulations shapes retail product formulation strategies. The Po Valley industrial zone balances traditional bakery equipment with liquid emulsifier dosing system adoption.
Bread Emulsifier Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated compounders with captive regulatory affairs capabilities and specialized application technical service infrastructure. Three strategic archetypes dominate: oilseed processors with backward integration into phospholipid production, specialized emulsifier manufacturers with palm oil fractionation assets, and diversified ingredient houses with bakery application laboratories. Competitive dynamics center on M&A activity targeting clean-label technology portfolios and strategic partnerships with industrial bakery automation suppliers.
Within the integrated processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify the oilseed-to-emulsifier supply chain model. Kerry Group plc and Palsgaard A/S occupy positions among specialized compounders with dedicated bakery application capabilities. BASF SE represents the diversified chemical producer archetype with synthetic emulsifier production heritage. These anchors illustrate how regulatory compliance infrastructure and formulation technical service differentiate competitive positioning across European and North American supply chains.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| International Flavors & Fragrances |
| Kerry Group plc |
| BASF SE |
| Corbion N.V. |
| Ingredion Incorporated |
| Palsgaard A/S |
| Tate & Lyle PLC |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp chemical corridor's freight cost dynamics compress margins for palm oil-derived emulsifier shipments while amplifying price differentiation between synthetic and plant-based formulations. This logistics chokepoint concentrates supply-side bargaining power with backward-integrated compounders possessing captive fractionation assets, forcing smaller European distributors into cost-pass-through positions.
Pricing Analysis
Prior-generation synthetic monoglyceride systems trade at commodity benchmarks, current-generation phospholipid formulations command certification premiums, and next-generation enzyme-modified hybrids occupy a narrowing price-performance middle ground. Three-tier pricing structure across premium clean-label, standard industrial, and economy synthetic levels reflects EFSA compliance tier and Non-GMO Project verification status. Cost compression in economy synthetic tiers intensifies because REACH registration burdens disadvantage smaller compounders. Industrial bakeries in Germany exhibit highest price sensitivity due to centralized procurement volume concentration, while French artisan producers show lowest sensitivity given retail premium capture.
Supply Chain Analysis
Contract-manufacturing concentration for phospholipid fractionation rests with integrated oilseed processors in the United States and European crushers in Germany and the Netherlands. Raw material flows draw from Malaysian and Indonesian palm oil plantations, Ukrainian sunflower seed crushing, and North American soybean processing. Single-source vulnerability concentrates in Southeast Asian palm oil fractionation where Indonesian export policy shifts disrupt European compounder feedstock planning. Distribution runs through pan-European bakery ingredient merchants in Germany's North Rhine-Westphalia corridor, with direct manufacturer relationships displacing traditional channels in frozen dough verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bread emulsifier markets sit in early-cycle expansion as clean-label reformulation mandates accelerate phospholipid substitution beyond prior five-year adoption norms. Enzyme-modified hybrid technology penetration in artisan channels signals widening addressable market beyond industrial bakery concentration.
For Market Incumbents: Build regulatory compliance infrastructure as a competitive moat by consolidating REACH documentation capabilities and EFSA dossier expertise before novel ingredient approval timelines extend. Defend against enzyme substitution threats by embedding application technical talent in customer R&D facilities to optimize hybrid system performance. Deepen backward integration into identity-preserved oilseed supply chains to secure Non-GMO Project certification stacking advantages. For New Entrants and Emerging Players: Build out clean-label phospholipid formulation capabilities targeting Poland and Romania where modern retail bakery expansion outpaces qualified local supplier presence. Eastern European industrial bakery automation presents the most penetrable geography given legacy equipment retrofit demand and limited incumbent technical service coverage. A direct sourcing partnership model with frozen dough distributors bypasses entrenched merchant channel relationships in Germany. For Investors and Strategic Acquirers: Specialized compounders with captive bakery application laboratories and palm oil fractionation assets represent the highest-conviction acquisition target archetype given regulatory compliance moat deepening. Long-term viability favors vertically integrated models over merchant distributors as procurement centralization concentrates volume with technical service-capable suppliers. Watch enzyme-modified hybrid adoption rates in French and Italian artisan channels as the signal indicating clean-label technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Captive phospholipid supply secures Non-GMO certification traceability for premium retail positioning. |
| Enzyme-Modified Formulation R&D Partnership | Hybrid technology access compresses clean-label price premiums and expands artisan channel penetration. |
| REACH Compliance Infrastructure Buildout | Regulatory affairs capabilities create competitive moats as EFSA dossier requirements tighten. |
| Eastern European Technical Service Expansion | Localized application laboratories capture Poland and Romania modern bakery format growth. |
| Direct Distributor Relationship Development | Foodservice channel disintermediation concentrates volume with qualified sustainability documentation suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from bakery R&D directors, procurement leads at industrial bread manufacturers, emulsifier compounder technical service heads, and regulatory affairs managers at ingredient houses, then refined against secondary validation from EFSA food additive safety opinions, REACH registration databases, EU customs trade flows, and SEC filings of listed ingredient suppliers. Bottom-up demand modeling across bakery, snack, confectionery, and dairy applications triangulated with top-down market sizing from oilseed processing capacity data.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, formulation format, and end-user category plus regional regulatory cluster differentiation. CAGRs were derived from installed base growth in automated bakery lines, clean-label certification stacking trends, and enzyme substitution elasticity estimates. Industry-specific forecast inputs included palm oil fractionation capacity utilization rates and EFSA novel food approval pipeline status.
Sensitivities concentrate around Indonesian palm oil export policy shifts, REACH registration cost inflation for synthetic intermediates, and enzyme technology performance breakthroughs in high-hydration dough systems. Forecasts embed assumptions about regulatory timeline stability and artisan channel adoption elasticity that warrant revision if EFSA protocols accelerate or clean-label retail mandates expand beyond current premium segments. Quarterly review of phospholipid import volumes, enzyme-modified formulation patent filings, and industrial bakery automation capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Gellan Gum Market