
 Italy Sodium Reduction Ingredients Market | 2026-2036
Italy Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Sodium Reduction Ingredients Market Foresight
EU Organic certification and ISO 22000 compliance cycles is rotating the competitive set, filtering out smaller ingredient traders unable to sustain audit costs. Cargill Inc. leverages its European supply chain infrastructure to anchor bulk potassium chloride deliveries across Italian food manufacturers. Kerry Group plc differentiates through taste-modulation technologies that mask bitterness in reduced-sodium cured meats. Jungbunzlauer Suisse AG specializes in mineral salt blends tailored to Mediterranean flavor profiles.
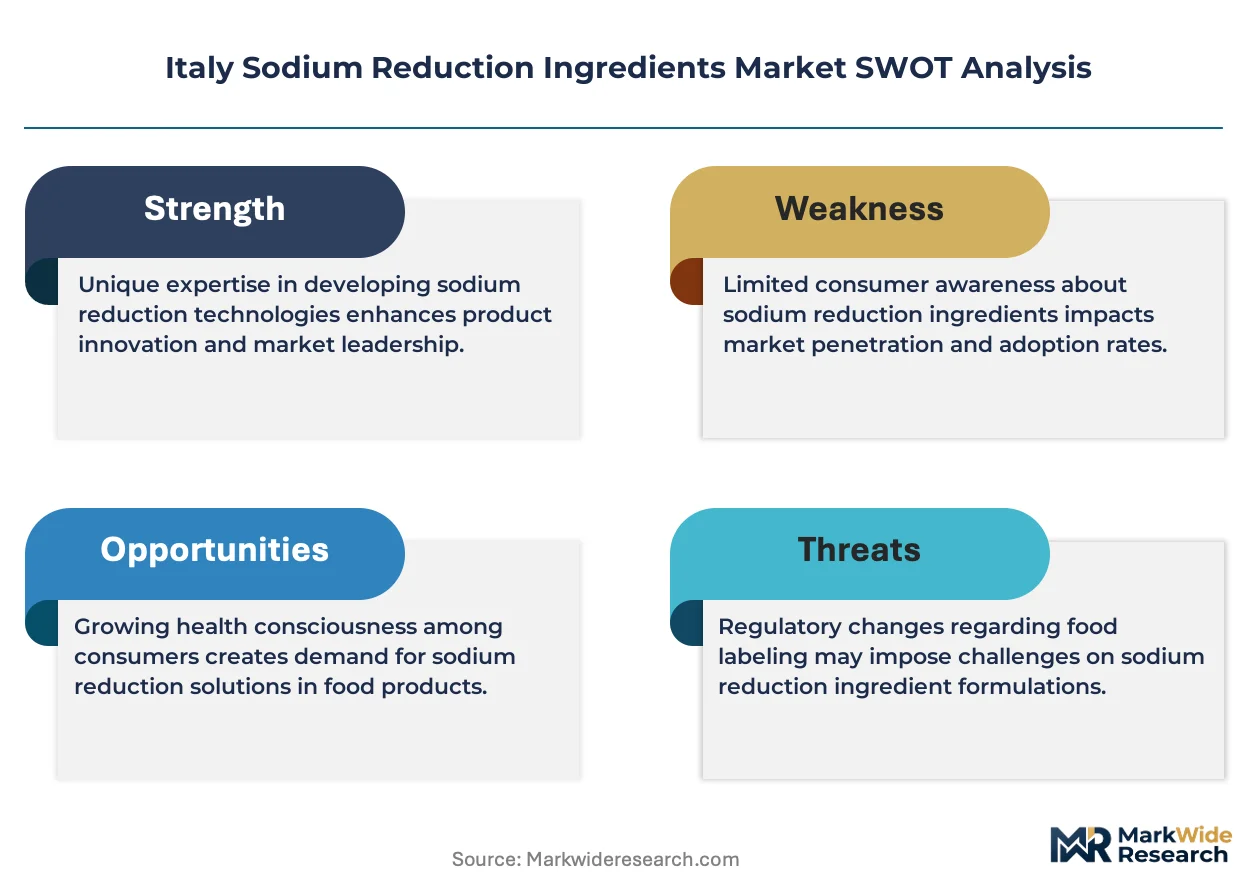
Sodium reduction ingredients comprise potassium chloride, yeast extracts, amino acid-based flavor enhancers, and mineral salt blends engineered to replicate sodium chloride's osmotic and sensory functions at 30-50% lower sodium content; these formulations preserve microbial stability, water-binding capacity, and taste perception in processed foods. Salt substitutes dominate volume flows due to their direct functional equivalence in cured meat and cheese applications, while yeast extracts capture expanding margin pools as clean-label demand intensifies among Italian food manufacturers reformulating without E-numbers. Flavor enhancers represent the fastest-growing product class as umami-boosting technologies reduce dependence on potassium chloride's metallic aftertaste.
Italy's Ministry of Health salt-reduction targets, coupled with EU Nutrition and Health Claims Regulation (EC) No 1924/2006 and EFSA sodium intake guidelines, compel food manufacturers to reformulate or risk exclusion from government procurement and front-of-pack labeling schemes. FSSAI-aligned importers face additional compositional scrutiny at Italian ports, tightening supply qualification timelines. Stakeholders must monitor pending revisions to EU-wide sodium benchmarks and pre-qualify alternative mineral salts before mandatory threshold reductions take effect.
Market Dynamics
Italy's Ministry of Health salt-reduction mandates are compressing formulation timelines across the northern industrial food belt, forcing processors in Parma and Milan to pre-qualify alternative mineral salts before mandatory threshold reductions take effect.
Growth Catalysts
- EFSA sodium intake guidelines:The European Food Safety Authority's updated benchmarks compel Italian cured meat manufacturers to reformulate products or risk exclusion from front-of-pack labeling schemes.
- Yeast extract technology:Clean-label demand among Italian food manufacturers is accelerating adoption of E-number-free flavor enhancers that mask potassium chloride's metallic aftertaste in reduced-sodium cheese applications.
- Parma-Milan processor cluster:Large-scale meat and bread manufacturers in Italy's northern industrial belt are expanding sodium reduction programs to maintain government procurement eligibility.
Market Restraints
- Potassium chloride price volatility:Bulk mineral salt supply concentrates among limited European traders, exposing Italian formulators to input cost swings that compress reformulation budgets.
- EU Organic certification audit burden:Smaller ingredient traders face elimination from the competitive set as ISO 22000 compliance cycles and organic certification costs escalate beyond sustainable thresholds.
- Metallic taste technical ceiling:Potassium chloride's functional equivalence in cured meat applications hits sensory limits at 30-50% sodium replacement, constraining deeper reduction targets without bitter-masking co-ingredients.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily food processors remain below national reformulation penetration rates, creating whitespace for mineral salt blend suppliers with Mediterranean flavor-profile expertise.
- Umami-boosting technology convergence:Amino acid-based flavor enhancers combined with yeast extract systems enable sodium reduction beyond potassium chloride's standalone technical limits.
- Nutri-Score regulatory tailwind:Italy's alignment with EU front-of-pack labeling schemes rewards reformulated products with improved color grades, driving packaged bread category adoption.
Industry Challenges
- FSSAI-aligned import scrutiny:Port-of-entry compositional testing for non-EU mineral salt shipments extends supply qualification timelines by 8-12 weeks, straining just-in-time reformulation schedules.
- Taste modulation skill scarcity:Italian food science programs produce insufficient formulation chemists trained in bitter-masking and umami-balancing techniques specific to reduced-sodium cured meat systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Sodium Reduction Ingredients Market |
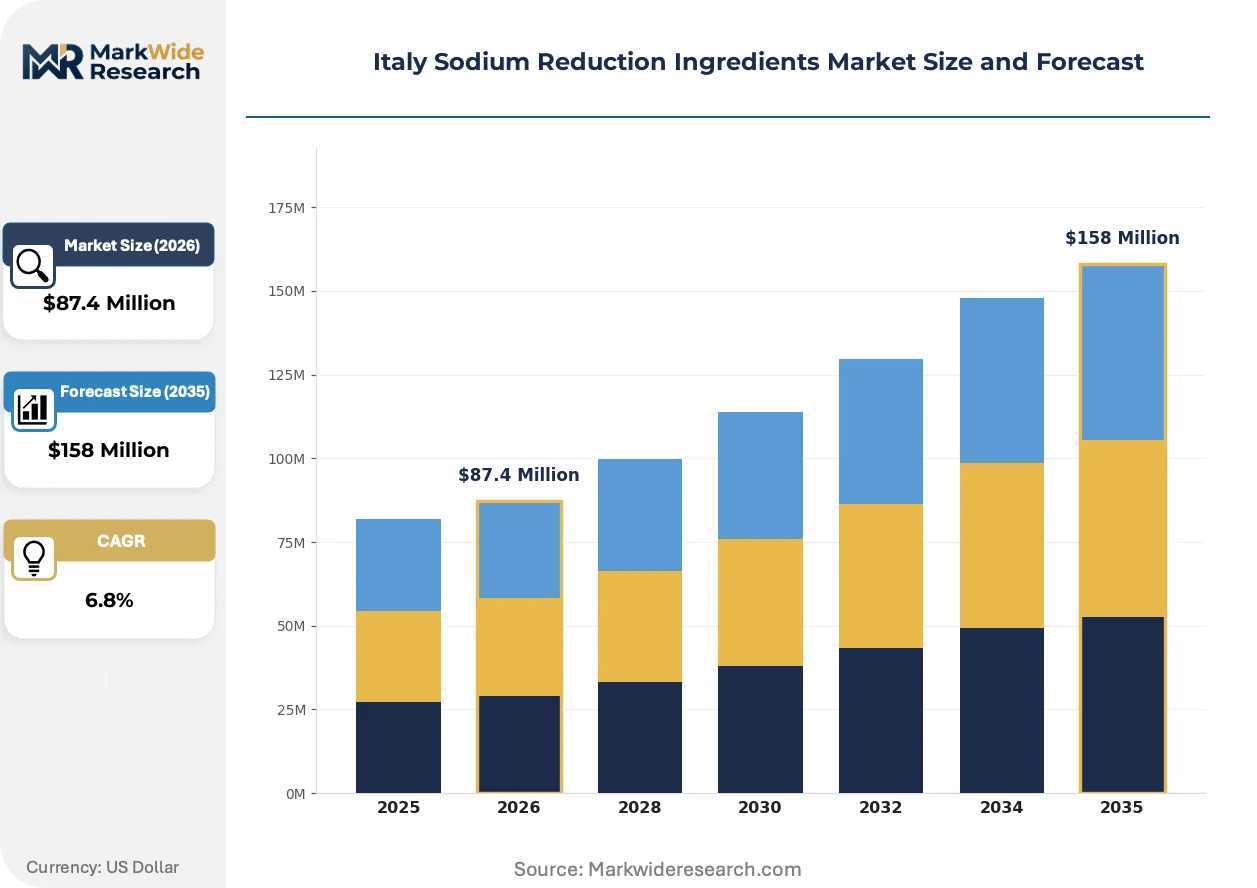
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Yeast Extracts, Acetic Acid Application: Processed Foods, Sauces, Dairy Products, Snack Foods End User: Food Manufacturers, Retail Consumers, Culinary Professionals, Food Service Distribution Channel: Supermarkets, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | DSM NV, Cargill Inc., Kerry Group plc, Tate & Lyle PLC, Corbion N.V., Givaudan SA, Jungbunzlauer Suisse AG, Sensient Technologies Corporation, Innophos Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Sodium Reduction Ingredients Market Shifts & Advancements
Reformulation technology is fragmenting along clean-label versus functional-performance axes, with Italian processors navigating divergent paths to sodium reduction depending on export destination and retail channel positioning.
Mineral salt blends engineered with potassium chloride, magnesium sulfate, and yeast extract are decomposing the traditional single-ingredient sodium replacement model. Cured meat manufacturers in Emilia-Romagna are adopting these composite systems at accelerated pace. This convergence is decomposing volume concentration among standalone potassium chloride suppliers while elevating margin capture for integrated taste-modulation providers.
Italy's National Plan for Salt Reduction, coordinated by the Ministry of Health, tightens sodium ceilings across retail food categories on rolling three-year cycles. Processors must submit reformulation roadmaps to maintain procurement contracts with public hospital and school feeding programs. Packaged bread and cheese applications face the most aggressive threshold compression, driving accelerated alternative mineral salt qualification.
Certification-driven preference rotation is restructuring supplier selection criteria among Italian food manufacturers. EU Organic and ISO 22000 compliance now filter competitive sets before technical evaluation begins. Procurement teams in Lombardy and Veneto are consolidating qualified supplier lists to three to five pre-audit-approved mineral salt providers, compressing switching flexibility but reducing compliance risk exposure.
Italy Sodium Reduction Ingredients Market Segmentation
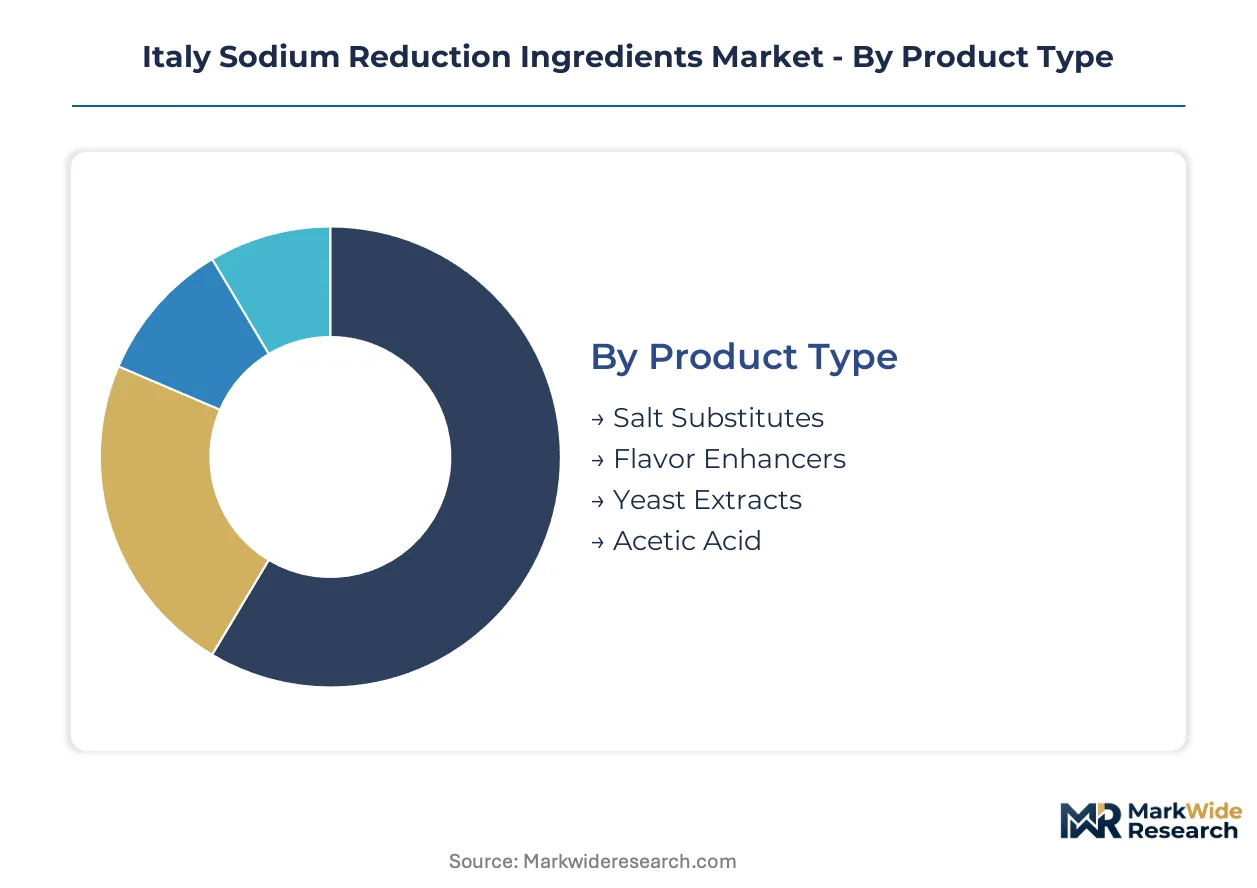
Ingredient substitution pressures fragment along product functionality lines, with mineral salt alternatives facing bitter-masking limitations while clean-label enhancers command premium positioning. Application-driven demand concentrates in cured meat and bread systems where EFSA sodium thresholds bite hardest.
Product Type:
Salt substitutes face the most acute substitution threat from umami-boosting technologies as potassium chloride's metallic ceiling drives formulators toward composite systems.
- Salt Substitutes:Potassium chloride and mineral salt blends replicate sodium chloride's osmotic and water-binding functions at 30-50% lower sodium content. Demand clusters in Parma's cured meat processors and Milan's industrial bakeries where EFSA compliance deadlines compress reformulation timelines. Metallic aftertaste constraints limit standalone deployment without bitter-masking co-ingredients.
- Flavor Enhancers:Amino acid-based systems and nucleotide compounds amplify umami perception, enabling deeper sodium reduction beyond potassium chloride's technical ceiling. Lombardy and Veneto procurement teams prioritize these for premium positioned retail lines where Nutri-Score color grades drive shelf placement.
- Yeast Extracts:Autolyzed yeast systems deliver clean-label E-number-free flavor modulation for Mediterranean cheese applications.
- Acetic Acid:pH-adjusting acidulant supports microbial stability in reduced-sodium sauce formulations.
Salt substitutes anchor the volume base while flavor enhancers gain share at the steepest rate.
Application:
Cost tier stratification separates commodity reformulation from premium clean-label positioning across Italian food manufacturing.
- Processed Foods:Cured meats and packaged breads dominate tonnage flows as Ministry of Health procurement contracts mandate sodium ceiling compliance. Emilia-Romagna processors adopt composite mineral salt systems at accelerated pace to maintain hospital and school feeding program eligibility.
- Sauces:Tomato-based and condiment applications leverage acetic acid pH management alongside potassium chloride reduction to preserve shelf stability.
- Dairy Products:Cheese manufacturers in Lombardy integrate yeast extract bitter-masking for clean-label positioning without E-numbers.
- Snack Foods:Seasoning applications favor mineral salt blends engineered to Mediterranean flavor profiles for regional retail differentiation.
Processed foods command the largest reformulation budgets while dairy products expand most quickly as clean-label premiums justify ingredient cost premiums.
End User:
Customer type determines specification rigor, with industrial manufacturers facing audit-heavy qualification cycles that filter supplier pools.
- Food Manufacturers:Large-scale processors in the northern industrial belt around Parma and Milan drive specification standards. ISO 22000 and EU Organic certification requirements compress qualified supplier lists to three to five pre-audit-approved mineral salt providers.
- Retail Consumers:Home cooking substitution demand concentrates in health-conscious urban demographics seeking table-top salt alternatives.
- Culinary Professionals:Restaurant and catering procurement favors Mediterranean-profile mineral blends for flavor authenticity.
- Food Service:Institutional feeding programs align with Ministry of Health salt-reduction targets for public contract eligibility.
Food manufacturers dominate volume procurement while food service channels climb fastest as public sector mandates tighten.
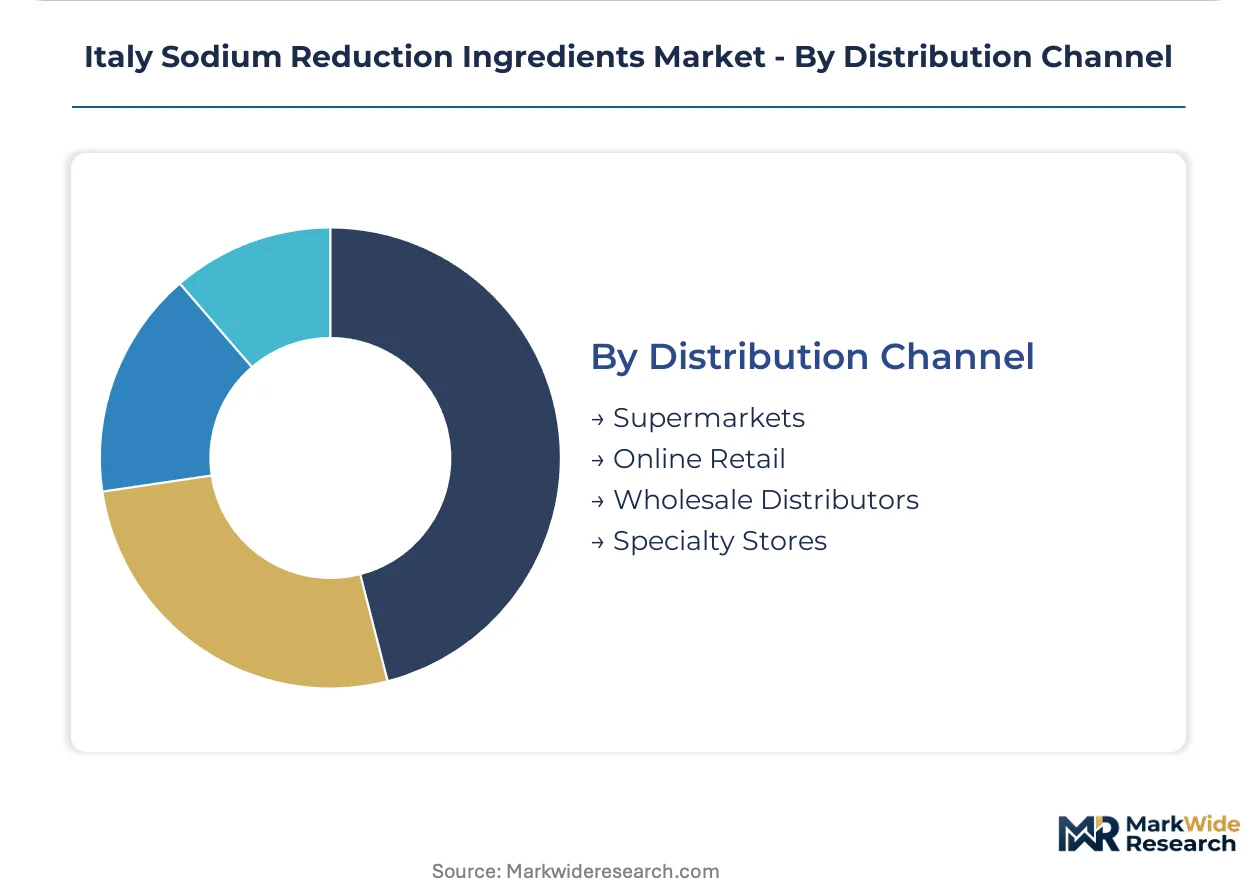
Distribution Channel:
Supply concentration among wholesale distributors shapes pricing power and qualification timelines for mineral salt ingredients.
- Supermarkets:Retail shelf placement for consumer-facing salt substitutes and table-top alternatives.
- Online Retail:Direct-to-consumer yeast extract and specialty mineral salt sales bypass traditional distribution markups.
- Wholesale Distributors:Bulk mineral salt and potassium chloride flows concentrate through limited European traders serving Lombardy and Veneto processors. FSSAI-aligned import scrutiny at Italian ports extends supply qualification timelines by 8-12 weeks, straining just-in-time reformulation schedules.
- Specialty Stores:Premium clean-label and organic-certified ingredient access for artisan food producers.
Wholesale distributors control the volume base while online retail expands most quickly as procurement teams seek supply chain redundancy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's National Plan for Salt Reduction, coordinated by the Ministry of Health, tightens sodium ceilings across retail food categories on rolling three-year cycles. This regulatory framework compresses reformulation timelines for processors seeking to maintain government procurement contracts. Demand clusters most intensively in the northern industrial food belt.
Lombardy
Milan anchors the country's largest concentration of industrial bakery and dairy processing facilities. EFSA sodium intake guidelines compel manufacturers to reformulate or risk exclusion from front-of-pack Nutri-Score labeling schemes. Procurement teams in the region consolidate qualified supplier lists to three to five pre-audit-approved mineral salt providers, compressing switching flexibility.
Emilia-Romagna
Parma's cured meat processors drive specification standards for potassium chloride and mineral salt blends. The Ministry of Health's procurement contract requirements for public hospital and school feeding programs mandate sodium ceiling compliance. Composite mineral salt systems combining yeast extract bitter-masking technologies are accelerating adoption across the region's aging facilities.
Veneto
Large-scale meat manufacturers in Verona and Padua face compressed qualification timelines due to FSSAI-aligned import scrutiny at Italian ports. EU Organic certification and ISO 22000 compliance cycles filter out smaller ingredient traders unable to sustain audit costs. Clean-label demand intensifies adoption of E-number-free flavor enhancers in premium positioned retail lines.
Piedmont
Turin's food technology corridor specializes in taste-modulation research for reduced-sodium cheese applications. Metallic aftertaste constraints limit standalone potassium chloride deployment without bitter-masking co-ingredients. The region's technical universities produce formulation chemists trained in umami-balancing techniques specific to Mediterranean flavor profiles.
Campania
Naples and surrounding food processors remain below national reformulation penetration rates, creating whitespace for mineral salt blend suppliers. Tomato-based sauce manufacturers leverage acetic acid pH management alongside potassium chloride reduction to preserve shelf stability. Southern Italy's underpenetration offers expansion opportunity for suppliers with Mediterranean flavor-profile expertise.
Italy Sodium Reduction Ingredients Market Competitive Landscape
Player mix skews toward diversified ingredient conglomerates with European supply chain infrastructure. Market structure concentrates around bulk mineral salt traders and integrated taste-modulation technology providers. Three archetypes dominate: multinational agricultural processors with captive potassium chloride supply, specialty chemical firms with mineral salt blend formulation capabilities, and flavor houses with bitter-masking intellectual property. Competitive moves center on pre-qualification for government procurement contracts and certification-driven supplier consolidation.
Within the multinational processor tier, Cargill Inc. anchors bulk potassium chloride deliveries through its European supply chain infrastructure. Kerry Group plc exemplifies the taste-modulation specialist archetype, occupying a position in clean-label flavor enhancement. Jungbunzlauer Suisse AG represents the mineral salt blend specialist segment, sitting within the Swiss chemical tradition of precision-engineered food ingredients. These three companies collectively illustrate the competitive fault lines between volume-scale mineral supply and premium-positioned sensory technology.
| Leading Market Players |
|---|
| DSM NV |
| Cargill Inc. |
| Kerry Group plc |
| Tate & Lyle PLC |
| Corbion N.V. |
| Givaudan SA |
| Jungbunzlauer Suisse AG |
| Sensient Technologies Corporation |
| Innophos Holdings Inc. |
| Others |
Supply & Pricing Matrix
EU Organic certification and ISO 22000 compliance cycles gate both supply qualification timelines and price differentiation tiers, compressing qualified supplier lists to three to five pre-audit-approved mineral salt providers while elevating audit-passing premiums above commodity potassium chloride benchmarks.
Pricing Analysis
Certification level creates the primary spread between premium and standard mineral salt tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 and EU Organic audit status alongside volume scale commitments from Lombardy and Veneto processors. Cost compression in economy-grade potassium chloride intensifies because bulk mineral salt supply concentrates among limited European traders. Food manufacturers with government procurement contracts exhibit lowest price sensitivity due to reformulation mandate rigidity, while small artisan producers in southern Italy face acute budget constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate northern Italian processor preferences, though FSSAI-aligned import scrutiny at Italian ports extends supply qualification timelines and forces strategic stockpiling of alternative mineral salts. Supply concentrates in Germany, Switzerland, and the Netherlands for potassium chloride and yeast extract inputs. Raw material dependencies rest on potash mining outputs, fermentation-derived nucleotides, and magnesium sulfate refining. Single-source vulnerability runs through bulk mineral salt traders serving the Parma-Milan industrial belt. Distribution runs through wholesale distributors controlling bulk flows to Lombardy and Veneto processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates among large-scale processors in Italy's northern industrial belt, with procurement teams consolidating qualified supplier lists and compressing switching flexibility for mineral salt providers.
For Market Incumbents: Compound certification advantages by accelerating EU Organic and ISO 22000 compliance cycles ahead of pending Ministry of Health threshold revisions. Deepen backward integration into yeast extract fermentation capacity to offset potassium chloride metallic aftertaste limitations. Defend against umami-boosting technology substitutes by acquiring bitter-masking intellectual property from Piedmont taste-modulation research clusters. For New Entrants and Emerging Players: Anchor in Campania and Sicily food processors where reformulation penetration rates trail national averages. Target tomato-based sauce manufacturers seeking acetic acid pH management alongside potassium chloride reduction. Pursue Mediterranean flavor-profile specialization as the primary go-to-market angle, leveraging regional taste authenticity preferences absent from northern supplier portfolios. For Investors and Strategic Acquirers: Italy's National Plan for Salt Reduction rolling three-year threshold cycles reshapes the acquisition landscape toward integrated taste-modulation technology providers. Long-term viability favors mineral salt blend specialists with proprietary umami-boosting capabilities over standalone potassium chloride traders. Monitor Ministry of Health procurement contract awards as the signal indicating which reformulation technologies achieve commercial scale in hospital and school feeding programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Extract Fermentation | Captive supply of bitter-masking technology reduces dependence on external nucleotide suppliers for cured meat applications. |
| EU Organic Certification Acceleration | Pre-qualification for Lombardy and Veneto procurement teams ahead of mandatory threshold reductions secures volume anchoring. |
| Mediterranean Flavor-Profile R&D Investment | Regional taste authenticity capabilities unlock Campania and Sicily processor segments below national reformulation penetration. |
| Long-term Supply Agreement with Parma Cured Meat Processors | Hospital and school feeding program eligibility locks in government procurement contract stability across EFSA compliance deadlines. |
| Joint Venture with Piedmont Technical Universities | Umami-balancing formulation chemist pipeline addresses taste modulation skill scarcity constraining deeper sodium reduction targets. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, procurement directors at Lombardy and Veneto food manufacturers, Ministry of Health regulatory affairs leads, and wholesale distribution channel heads anchors the qualitative findings. Secondary validation draws from EFSA sodium intake guideline publications, EU Nutrition and Health Claims Regulation filings, Italian customs mineral salt import records, and SEC 10-K disclosures from listed ingredient suppliers. Bottom-up volume estimates from individual processor reformulation programs triangulate against top-down market sizing from trade flow analysis.
Sensitivity analysis across potassium chloride price volatility scenarios, certification audit failure rates, and Ministry of Health threshold acceleration timelines informs projection robustness. Segmentation dimensions modeled include product functionality tier, application category, end-user procurement scale, and regional reformulation penetration status. CAGRs derive from processor expansion capex disclosures and government procurement contract award trajectories. Forecast inputs incorporate EFSA guideline revision probability and FSSAI-aligned import scrutiny duration assumptions.
Underlying assumptions cover stable EU Organic certification cost structures and Ministry of Health three-year cycle continuity, with deviation risk concentrated in potassium chloride supply disruptions and abrupt EFSA threshold acceleration. Revision becomes warranted when FSSAI-aligned port scrutiny timelines exceed current qualification buffers or when umami-boosting technology adoption crosses inflection thresholds among Emilia-Romagna cured meat processors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Food Texturing Agents Market