
 Food Coating Ingredients Market | 2026-2036
Food Coating Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Food Coating Ingredients Market Intelligence
Quick-service restaurant chains are unwinding the historical dominance of retail-packaged coated foods as their in-house preparation volumes climb. Cargill, Incorporated leverages its integrated oilseed and starch supply chains to control input costs for batter and breading systems. Kerry Group PLC sustains formulation leadership through dedicated savory taste and coating technology centers across multiple continents. Newly Weds Foods anchors North American supply through specialized manufacturing plants serving protein processors and QSR distributors.
Food coating ingredients comprise functional mixtures of flours, starches, hydrocolloids, seasonings, and lipids applied to substrates through batter deposition, breading adhesion, or topical dusting to create crispness, flavor retention, and moisture barriers during frying or baking. The application dimension shows snack foods commanding the largest volume share while meat products generate premium pricing through specialized adhesion and yield-improving formulations. Batter systems lead product-type value pools due to their technical complexity and customization requirements for industrial fryer lines.
The FDA governs coating ingredient safety through GRAS determinations and allergen labeling mandates, while the USDA FSIS regulates coated meat and poultry products through inspection protocols that affect formulation choices. EFSA and national EU regulators enforce the Food Additives Regulation and novel food assessments that constrain hydrocolloid and modified starch deployment. Stakeholders must monitor evolving clean-label thresholds as regulatory scrutiny tightens on phosphate-based moisture retention systems and synthetic antioxidant carriers.
Market Dynamics
Quick-service restaurant chains are unwinding retail dominance through vertical in-house preparation, while the EU's updated Food Additives Regulation forces reformulation toward cleaner-label coating systems. This dual pressure compresses legacy phosphate-based moisture retention and synthetic antioxidant carriers.
Growth Catalysts
- Clean-Label Mandates:EFSA enforcement of the Food Additives Regulation accelerates demand for native starches and natural hydrocolloids in batter systems. Reformulation pipelines at protein processors now prioritize phosphate-free adhesion.
- QSR Capacity Expansion:Quick-service restaurant chains in Southeast Asia are building dedicated coating kitchens, pulling volume from retail-packaged channels. Regional processing capacity in Vietnam and Indonesia concentrates demand for localized seasoning blends.
- Frying Technology Advancement:Industrial air-fryer line deployment enables water-based batter systems that reduce oil absorption. Equipment manufacturers in Germany and Japan are retrofitting existing fryer infrastructure.
Market Restraints
- Input Cost Volatility:Wheat and modified starch prices fluctuate with Black Sea grain flows, compressing margin on standard breading formulations. Batter system producers face margin pressure from edible oil price swings.
- Supply Concentration Risk:Specialized hydrocolloid production clusters in China create dependency for gellan and xanthan gum used in premium adhesion systems. Geopolitical friction threatens just-in-time delivery to European formulators.
- Technical Limitation:Clean-label moisture retention lacks functional parity with phosphate-based systems, forcing yield trade-offs in coated poultry. Protein processors report 3-5 point yield gaps in trials.
Strategic Opportunities
- Underpenetrated Geography:India's organized poultry processing sector remains underdeveloped for industrial coating, presenting white space for turnkey batter-breading system providers. FSSAI harmonization with Codex standards reduces import friction.
- Regulatory Tailwind:The EU Green Deal's farm-to-fork targets incentivize upcycled ingredient streams—spent grain and okara—for sustainable coating substrates. First-movers secure preferential sourcing contracts with brewers and soymilk processors.
- Technology Convergence:Precision fermentation-derived lipids and enzymatic starch modification converge to create next-generation barrier coatings. Startups in the Netherlands and California are piloting scale-up.
Industry Challenges
- Reformulation Timeline Compression:EU regulatory deadlines for phosphate reduction in meat coatings force 18-month reformulation cycles. Technical teams must validate adhesion, yield, and shelf-life simultaneously.
- Capex Intensity:Dedicated allergen-segregated coating lines require capital outlays that mid-sized protein processors defer. Shared toll-coating facilities face utilization uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Coating Ingredients Market |
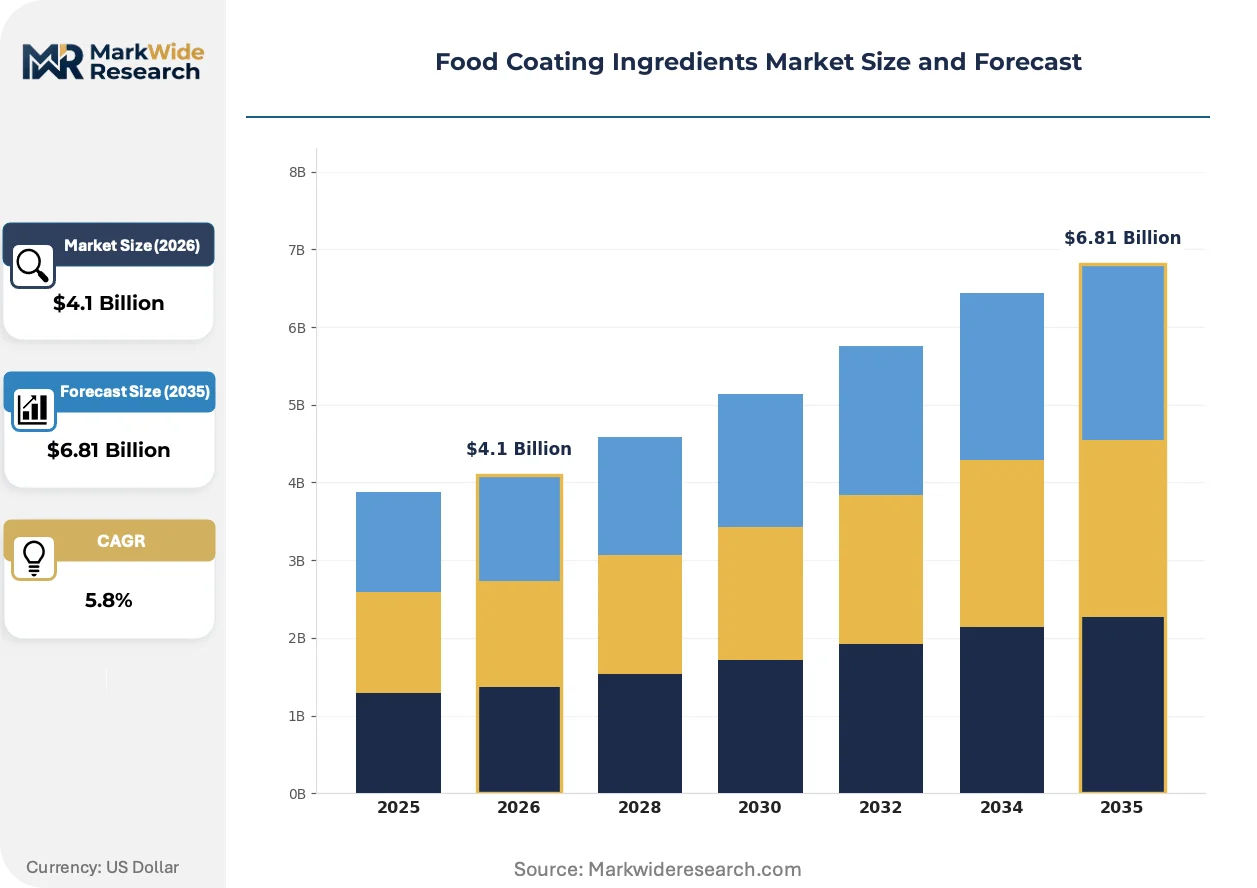
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Batter, Bread Crumbs, Seasoning Application: Snack Foods, Meat Products, Bakery, Seafood Form: Dried, Liquid, Powdered, Granular End User: Food Manufacturers, Restaurants, Catering Services, Retailers |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Kerry Group PLC, Tate & Lyle PLC, Newly Weds Foods, Dohler GmbH, Agrana Beteiligungs-AG, Bowman Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Coating Ingredients Market Strategic Shifts & Innovations
Active reformulation is reshaping competitive positioning as coating chemistry pivots from synthetic functional additives toward biobased and enzymatically processed alternatives. Three intersecting developments are compressing legacy system viability.
Enzymatically modified starches are decomposing the technical monopoly of chemically cross-linked alternatives in high-shear batter applications. QSR fryer operators in Southeast Asia and North America are adopting these systems at accelerating rates to meet clean-label procurement specifications. The shift is decomposing price premiums historically commanded by specialized modified starch suppliers and compressing formulation differentiation to seasoning complexity.
EFSA's tightened scrutiny of phosphate additives under the Food Additives Regulation is forcing systematic removal of sodium tripolyphosphate from moisture-retention coatings. Protein processors serving EU retail channels must reformulate by specified deadlines or exit branded product lines. The constraint hits coated poultry most severely, driving investment in yeast extract and citrus fiber alternatives.
Consolidated QSR procurement teams are compressing supplier rosters and demanding integrated seasoning-coating-breading systems rather than discrete ingredient sourcing. Regional distributors in Southeast Asia are losing share to direct manufacturer-processor relationships. The pattern is most visible in Vietnam and Thailand, where Japanese and American QSR chains centralize supply chain control.
Food Coating Ingredients Market Segmentation
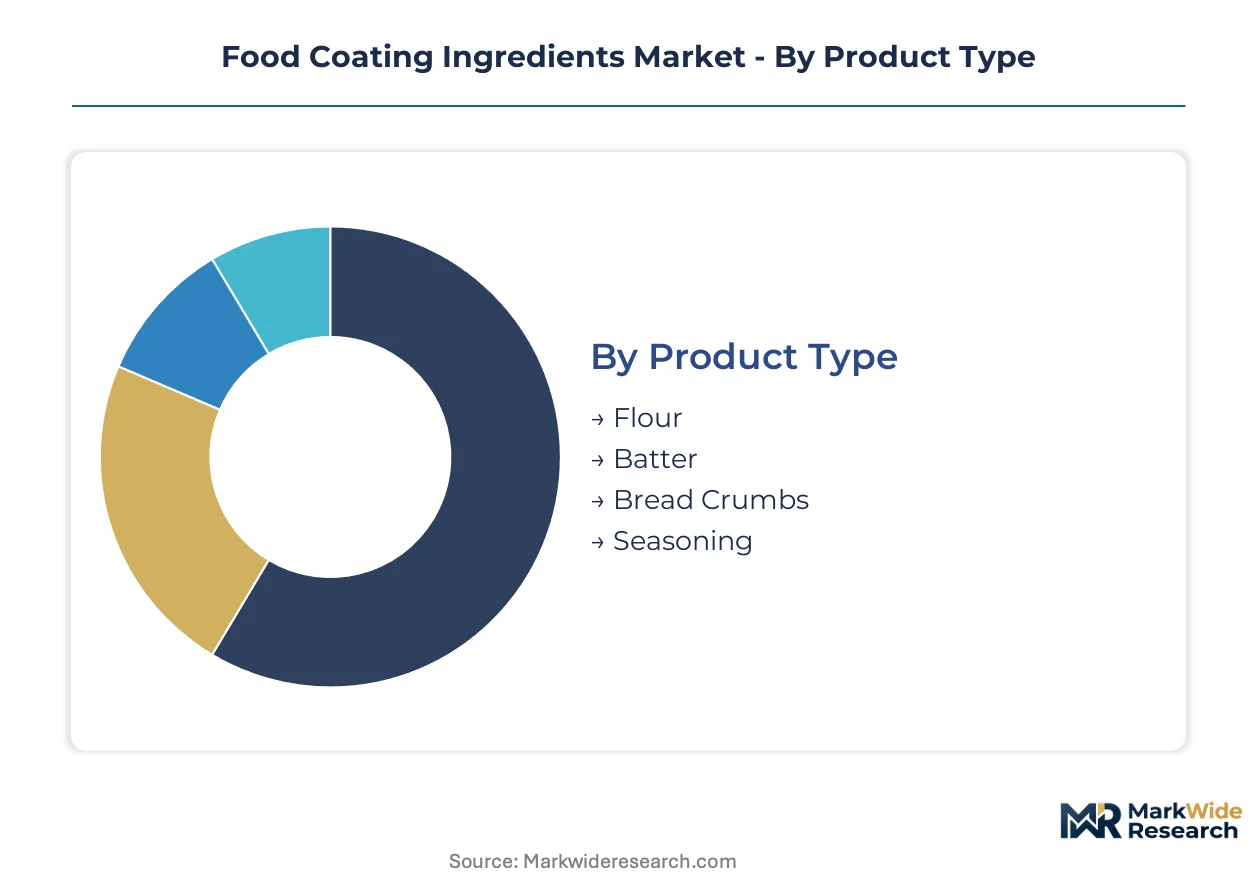
Coating ingredient procurement diverges sharply between export-oriented protein processors and domestic QSR chains, with each segment demanding distinct technical specifications and supply chain configurations. Understanding these splits reveals where margin pools concentrate and which formulation capabilities command premium positioning.
Product Type:
Domestic consumption dominates flour and breading volumes in wheat-growing regions, while batter systems flow disproportionately to export-led poultry and seafood processing hubs in Southeast Asia and Latin America.
- Flour:Wheat and rice flours constitute the foundational substrate for adhesion layers and dusting applications. North American and Black Sea suppliers anchor this segment, though drought cycles in the US Plains and Ukraine compress availability for industrial breading operations.
- Batter:Complex aqueous suspensions of starches, hydrocolloids, and leavening agents engineered for viscosity stability under high-shear pump conditions. Demand concentrates in Vietnamese and Thai export-processing zones where Japanese and American QSR chains specify custom rheology profiles for dedicated fryer lines.
- Bread Crumbs:Japanese panko variants command premium positioning in upscale foodservice, while standard wheat crumbs serve cost-sensitive retail frozen applications.
- Seasoning:Dry spice blends and flavor systems applied pre- or post-coating for regional taste differentiation.
Batter commands the established base. The steepest expansion runs through seasoning systems as QSR chains localize menus across Southeast Asian markets.
Application:
Cost tiering separates commodity snack coating from precision-formulated meat systems, with protein applications absorbing three to four times the R&D investment per kilogram.
- Snack Foods:High-volume extruded and sheeted substrates requiring uniform oil-barrier coatings for extended shelf stability. Southeast Asian palm oil price volatility directly squeezes margin on standard snack seasoning systems.
- Meat Products:Poultry, pork, and beef coatings demanding yield-improving adhesion, freeze-thaw stability, and moisture retention under EFSA phosphate constraints. German and Dutch processors lead clean-label reformulation trials, trading 3-5 point yield gaps for regulatory compliance.
- Bakery:Egg washes, glazes, and topical finishes for crust color and shelf-life extension in artisan and industrial bread lines.
- Seafood:Delicate adhesion systems for battered and breaded fish portions, with Nordic processors specializing in freeze-resistant formulations for whitefish exports.
Meat Products anchor value capture. Snack Foods deliver volume scale but compress pricing power through commoditized sourcing.
Form:
Supply concentration in Chinese hydrocolloid production shapes liquid and granular availability, while dried and powdered forms disperse across regional milling networks with lower import dependency.
- Dried:Dehydrated batter and breading mixes with extended ambient shelf life, dominating retail channel distribution and emergency stockpiling protocols.
- Liquid:Ready-to-use batter slurries requiring cold-chain integrity but eliminating on-site hydration variables. Japanese equipment manufacturers in Osaka and Nagoya optimize fryer-line integration for these systems.
- Powdered:Fine-milled starches and seasonings for topical dusting and dry adhesion, prevalent in snack seasoning towers.
- Granular:Coarse breadcrumb textures and crystalline salt-sugar carriers for controlled release in high-temperature frying.
Dried forms hold the volume base. Liquid systems are climbing fastest as QSR central kitchens eliminate hydration labor and variability.
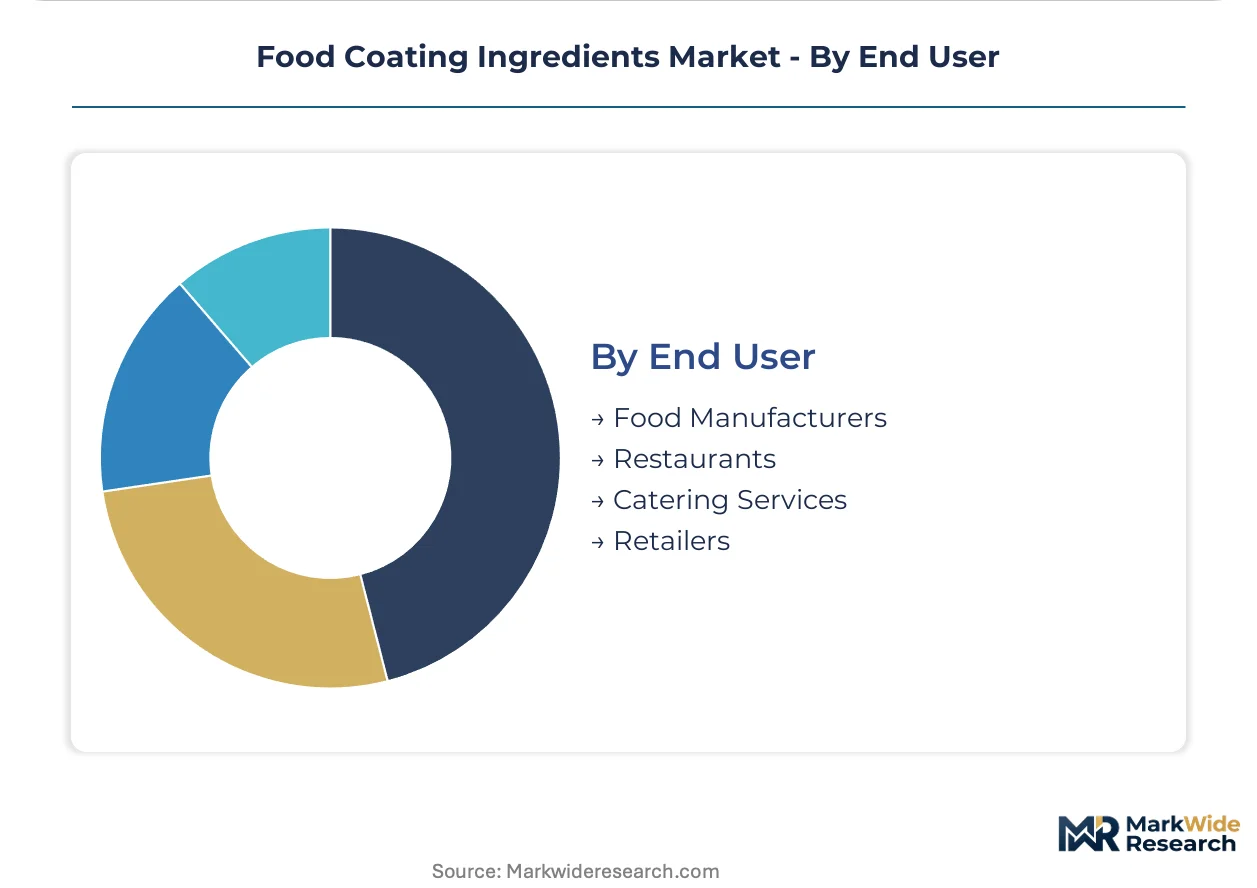
End User:
Customer type stratifies procurement sophistication, with food manufacturers demanding technical co-development while restaurants and caterers prioritize logistical reliability and menu flexibility.
- Food Manufacturers:Industrial processors of frozen and chilled coated proteins, operating dedicated coating lines with allergen segregation protocols. These buyers specify custom batter rheology and negotiate multi-year starch supply contracts.
- Restaurants:Quick-service chains building in-house coating capacity in Vietnam, Indonesia, and Thailand, pulling volume from legacy distributor relationships toward direct manufacturer partnerships.
- Catering Services:Volume foodservice operators requiring consistent portion control and holding stability for buffet and event applications.
- Retailers:Private-label frozen food programs with price-sensitive specifications, though European clean-label mandates are elevating formulation requirements for store-brand coated proteins.
Food Manufacturers retain the deepest technical integration. Restaurants are gaining share fastest through verticalized coating kitchen investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European coating ingredient distribution, while Vietnam's Cai Mep deepwater port complex funnels Southeast Asian export volumes. These maritime gateways concentrate starch and hydrocolloid flows from Black Sea grain origins and Chinese hydrocolloid clusters.
United States
QSR chains in the Southeast and Midwest are building captive coating kitchens, displacing distributor intermediaries. The FDA's GRAS determinations and USDA FSIS inspection protocols govern phosphate-based moisture retention in poultry coatings. Chicago and Dallas-Fort Worth concentrate protein processing capacity where Newly Weds Foods operates specialized manufacturing plants.
Germany
Industrial air-fryer line deployment accelerates demand for water-based batter systems with reduced oil absorption. EFSA enforcement of the EU Food Additives Regulation forces phosphate reformulation in meat coatings by specified deadlines. The Cologne-Düsseldorf corridor hosts equipment manufacturers retrofitting fryer infrastructure for enzymatically modified starch systems.
Vietnam
Japanese and American QSR chains are constructing dedicated coating facilities in Binh Duong and Dong Nai provinces. FSSAI-aligned import standards reduce friction for regional seasoning blend suppliers. Ho Chi Minh City's processing zones concentrate custom batter rheology development for export-oriented seafood and poultry operations.
China
Specialized hydrocolloid production in Shandong and Jiangsu provinces supplies gellan and xanthan gum for premium adhesion systems. The country's national food safety regulator maintains GB standards for modified starch deployment in coating applications. Qingdao's port infrastructure handles bulk starch imports from Black Sea origins for redistribution across Asia-Pacific.
India
Organized poultry processing in Maharashtra and Telangana remains underdeveloped for industrial coating, creating white space for turnkey system providers. FSSAI harmonization with Codex standards streamlines ingredient import protocols. Mumbai-Pune industrial corridors attract initial investments in allergen-segregated coating line infrastructure.
Food Coating Ingredients Market Key Industry Players
Concentration sits with integrated agribusiness conglomerates controlling upstream oilseed and starch supply chains. The vendor base stratifies across three tiers: multinational ingredient platforms with global formulation centers, regional specialists in savory taste technology, and commodity millers competing on wheat and rice flour sourcing. Dominant competitive moves include backward integration into specialty hydrocolloid production and direct partnerships with QSR procurement teams bypassing legacy distribution.
Within the integrated supply chain tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify upstream control over oilseed and grain inputs. Kerry Group PLC occupies a position representing formulation leadership through dedicated savory taste and coating technology centers. Newly Weds Foods anchors North American supply relationships through specialized manufacturing infrastructure serving protein processors and QSR distributors directly.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Kerry Group PLC |
| Tate & Lyle PLC |
| Newly Weds Foods |
| Dohler GmbH |
| Agrana Beteiligungs-AG |
| Bowman Ingredients |
| Others |
Cost & Logistics Intelligence
Scale economies in enzymatic starch modification concentrate production among integrated agribusiness conglomerates, compressing price floors for standard breading formulations while elevating premiums for clean-label batter systems. Capacity utilization at Black Sea milling clusters and Southeast Asian hydrocolloid plants shapes margin distribution across the value chain.
Pricing Analysis
Volume-discount tiering structures separate contract-based long-term offtake agreements for QSR procurement teams from spot-market transactions serving mid-sized protein processors. Price differentiation hinges on clean-label certification tier and customization level for fryer-line integration. Cost compression in standard wheat flour breading intensifies because Black Sea grain flow disruptions compress availability. Retail private-label programs exhibit highest price sensitivity, while export-oriented seafood processors absorbing enzymatically modified starch systems show lowest.
Supply Chain Analysis
Inbound logistics costs from Qingdao port congestion and container availability constraints on Asia-Europe trade lanes elevate working capital requirements for European formulators sourcing Chinese hydrocolloids. Supply concentrates in Shandong and Jiangsu provinces for gellan and xanthan gum, with Black Sea origins for wheat starch and German equipment clusters for fryer-line integration. Single-source vulnerability in specialized hydrocolloid production creates dependency risk. Distribution runs through Rotterdam liquid bulk terminals for European redistribution and Cai Mep deepwater port for Southeast Asian export volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory inflections across EU and Southeast Asian markets are compressing legacy phosphate-based system viability, creating high-growth disruption for enzymatically processed alternatives and natural hydrocolloid platforms.
For Market Incumbents: Shield formulation leadership by accelerating backward integration into specialty hydrocolloid production in Shandong corridor alternatives, and secure multi-year starch supply contracts with Black Sea suppliers before drought cycles tighten availability. Synthetic antioxidant carrier displacement by natural alternatives represents the priority threat demanding R&D reallocation toward yeast extract and citrus fiber yield-improvement systems.
For New Entrants and Emerging Players: Anchor in India's underpenetrated organized poultry processing sector, where FSSAI harmonization reduces import friction for turnkey batter-breading system providers. Precision fermentation-derived lipids for barrier coatings in Netherlands and California pilot facilities represent the most penetrable technology convergence. Go-to-market through direct partnerships with Maharashtra and Telangana protein processors bypassing legacy distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platforms controlling upstream oilseed and starch supply chains with embedded savory taste technology centers. Five-to-ten year viability rests on regulatory compliance speed and QSR procurement team consolidation tolerance. Signal to monitor: EFSA enforcement acceleration on phosphate reduction deadlines forcing exit-or-reformulate decisions among coated poultry processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrocolloid Production | Captive supply of gellan and xanthan gum reduces dependency on Shandong clusters for European formulators. |
| Direct QSR Procurement Partnerships | Bypassing Vietnamese and Thai distributors captures volume migrating to centralized coating kitchen investments. |
| Enzymatic Starch Modification Scale-Up | Decomposes price premiums historically commanded by chemically cross-linked modified starch suppliers. |
| Upcycled Ingredient Stream Sourcing | Spent grain and okara contracts with brewers and soymilk processors align with EU Green Deal farm-to-fork targets. |
| Allergen-Segregated Coating Line Infrastructure | Shared toll-coating facilities address capex barriers deferring dedicated line investments by mid-sized processors. |
Research Approach
Cross-validation between primary interviews with protein processing plant managers, QSR supply chain directors, savory technology R&D leads, and regulatory affairs specialists anchors the qualitative findings against secondary validation through customs and trade data, EFSA additive assessments, FSSAI harmonization documentation, and SEC filings from integrated agribusiness conglomerates. Bottom-up volume modeling across batter, breading, and seasoning product types triangulates with top-down market sizing.
Sensitivity analysis on input cost volatility and regulatory deadline acceleration informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application substrate, form factor, and end-user procurement sophistication, with regional processing capacity expansion patterns as an industry-specific overlay. CAGRs derive from trend extrapolation validated against capacity buildout announcements and QSR expansion commitments.
Material uncertainties — Black Sea grain flow disruptions, EFSA phosphate enforcement timing, and geopolitical friction affecting Chinese hydrocolloid just-in-time delivery — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as clean-label yield-gap closure and precision fermentation lipid scale-up evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Italy Food Preservatives Market