
 Coated Recycled Paperboard Market | 2026-2036
Coated Recycled Paperboard Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Recycled Paperboard Market Analysis
FSC Chain of Custody certification is bifurcating the competitive landscape into qualified suppliers and secondary converters. WestRock leverages integrated pulp-to-board operations across the southeastern United States to sustain volume leadership in coated folding cartons. Mondi anchors European supply through kraftliner-adjacent R&D platforms that specialize in barrier-coated recycled grades for food contact.
Coated recycled paperboard denotes a multi-ply substrate manufactured from recovered fiber, finished with a clay or polymer barrier coating to achieve printability and moisture resistance. The coating layer typically ranges from 8 to 15 grams per square meter, enabling rotogravure and offset lithography on surfaces that would otherwise absorb ink. Coated folding cartons command the largest share of value as consumer goods brands prioritize shelf differentiation, while coated linerboard is gaining traction in e-commerce shipper applications where print-ready exteriors reduce secondary labeling steps. The bleached grade segment occupies premium price tiers in pharmaceutical and cosmetics packaging where whiteness and hygiene perception drive specification.
EPA guidelines on recycled content claims, EU REACH restrictions on coating chemistries, and FDA food contact notifications collectively determine which barrier formulations gain commercial traction. These frameworks push converters toward water-based coating technologies and post-consumer fiber verification systems that satisfy multiple jurisdiction requirements. Stakeholders must monitor evolving state-level extended producer responsibility legislation in the United States and pending amendments to the EU Packaging and Packaging Waste Regulation that could redefine minimum recycled content thresholds for coated paperboard applications.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are restructuring coated recycled paperboard procurement, forcing brands to verify post-consumer fiber content through chain-of-custody systems that favor qualified suppliers over secondary converters.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation amendments:Pending recycled content thresholds are compelling food and beverage brands to accelerate specification of certified coated grades ahead of enforcement deadlines.
- Fast-moving consumer goods retrofitting:Indian FMCG companies are rebuilding domestic supply chains around locally sourced coated recycled paperboard to reduce import dependency and logistics exposure.
- Water-based barrier coatings:Advances in clay-polymer hybrid formulations are enabling compliance with FDA food contact notifications while maintaining moisture resistance for premium shelf-ready applications.
Market Restraints
- Recovered fiber cost volatility:Post-consumer fiber prices fluctuate with municipal collection program funding cycles, compressing converter margins during supply shortages.
- Coating chemistry restrictions:EU REACH limitations on specific polymer barrier components force reformulation investments that smaller converters cannot absorb.
- Substitution by flexible plastic:Stand-up pouches and film laminates retain cost advantages in moisture-critical applications, limiting coated paperboard penetration in wet-food segments.
Strategic Opportunities
- E-commerce shipper applications:Coated linerboard with print-ready exteriors is displacing corrugate-plus-label configurations in direct-to-consumer fulfillment, eliminating secondary labeling steps.
- Pharmaceutical compliance packaging:Bleached grade specifications for hygiene-perception-critical drug cartons command premium positioning as FDA serialization mandates expand.
- Indian domestic capacity expansion:PLI scheme incentives for paperboard manufacturing are attracting capital toward integrated pulp-to-board facilities serving regional FMCG demand.
Industry Challenges
- FSC Chain of Custody certification timelines:The 12-18 month audit and documentation process delays supplier qualification, creating bottlenecks for brands with near-term compliance deadlines.
- Rotogravure-to-offset conversion complexity:Printers face capex burdens and technician retraining requirements when shifting between coating-optimized print processes for different end-use specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Recycled Paperboard Market |
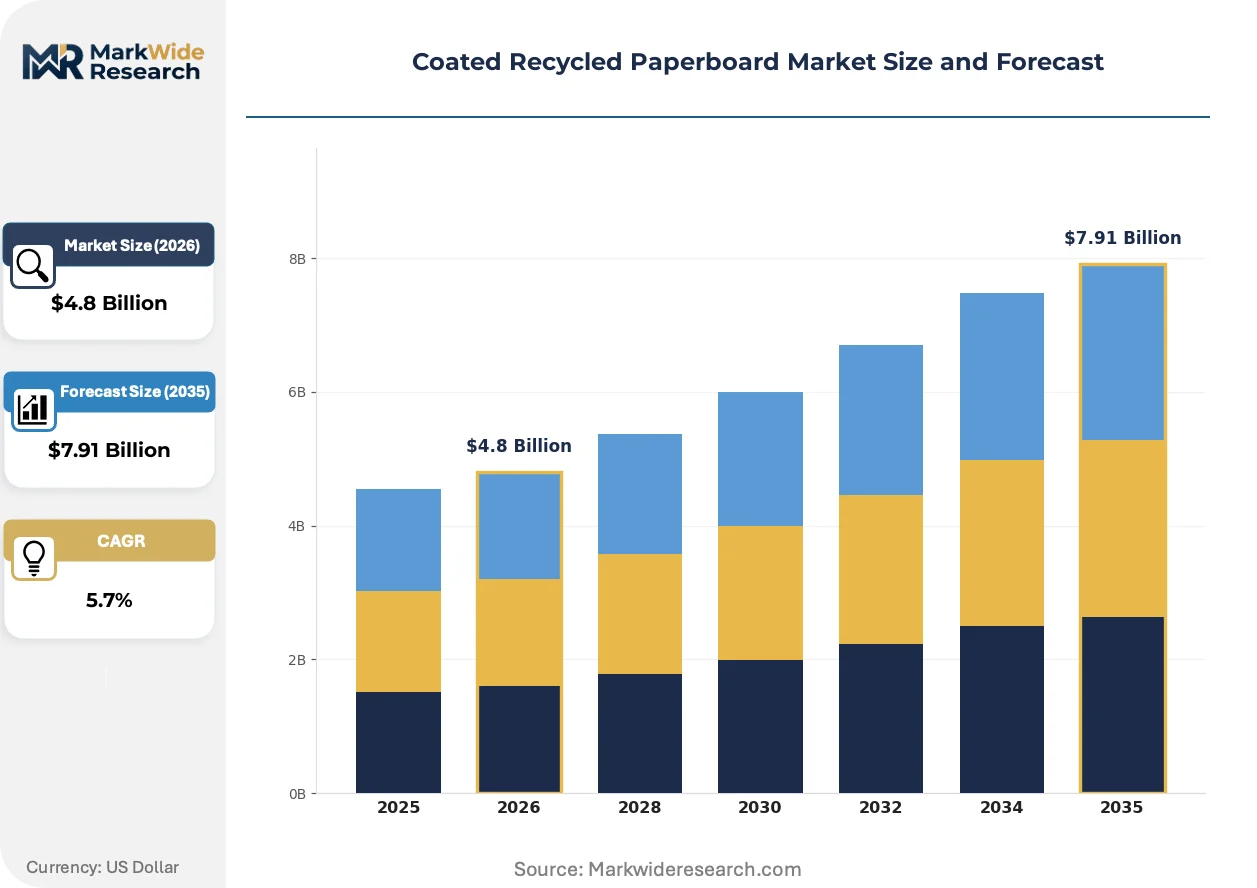
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
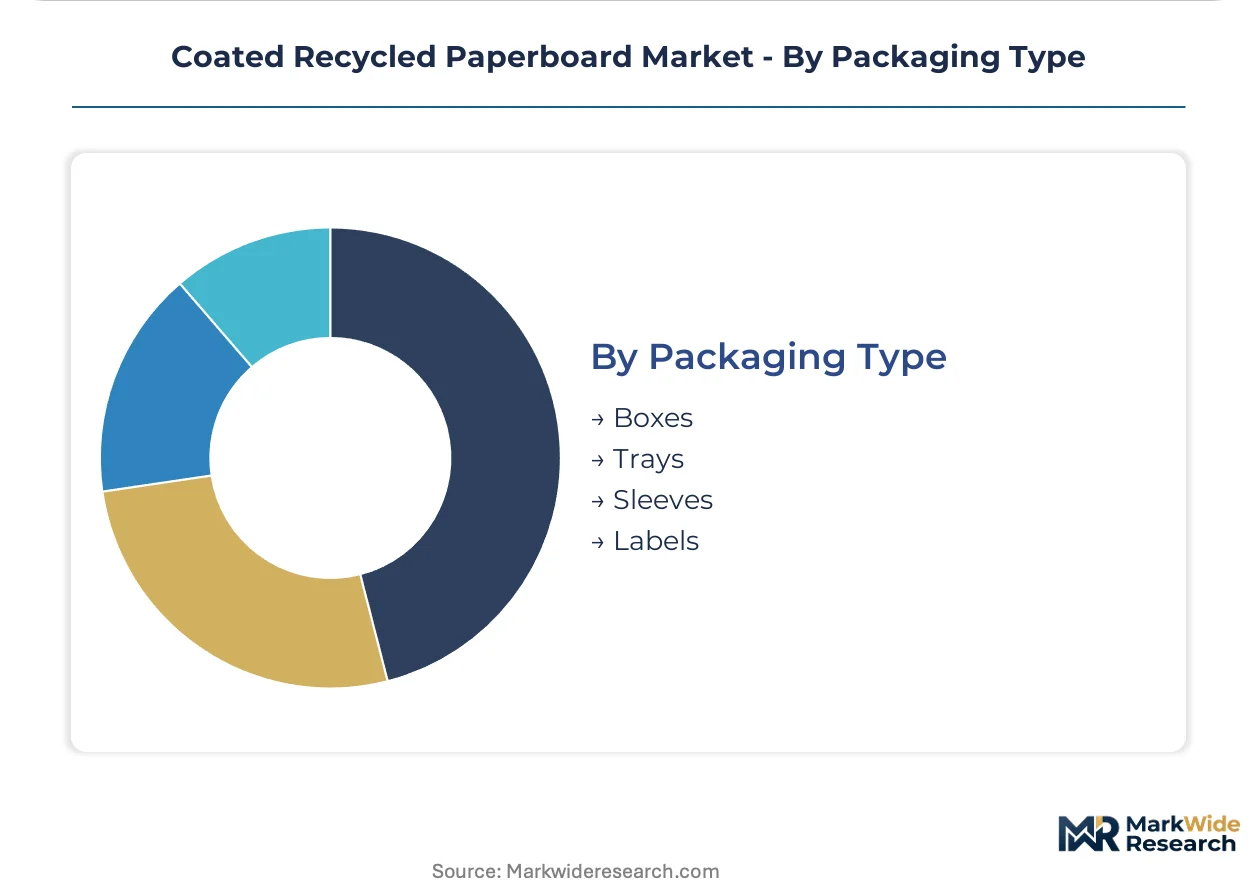
| Segmentation | Product Type: Coated Folding Cartons, Coated Linerboard, Coated Newsprint, Coated Corrugated End Use Industry: Consumer Goods, Food & Beverage, Electronics, Pharmaceuticals Grade: Semi-chemical, Bleached, Unbleached, Others Packaging Type: Boxes, Trays, Sleeves, Labels |
| Companies Covered | Caraustar Industries, PaperWorks Industries, WestRock, Mondi, Cascades, Graphic Packaging International, Sonoco, Evergreen Packaging, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Recycled Paperboard Market Emerging Trajectories
Barrier coating technologies are bifurcating the competitive landscape between integrated manufacturers with captive R&D and converters dependent on external formulation suppliers, reshaping how value is captured across the supply chain.
Water-based polymer-clay hybrid coatings are fragmenting the barrier solutions market by enabling FDA-compliant food contact performance without perfluorinated chemistry. Mid-sized folding carton converters in Germany and France are adopting these formulations fastest to preempt REACH restriction expansions. The technology is fragmenting incumbent fluoropolymer coating franchises and compressing their pricing power in premium applications.
EU Green Deal implementation timelines are accelerating recycled content verification requirements across member states. The European Commission's delegated acts under the Packaging and Packaging Waste Regulation are forcing brands to document post-consumer fiber percentages through mass-balance accounting. Pharmaceutical and cosmetics packaging specifications in France and Germany are most affected, with procurement teams now requiring third-party certification as a table-stakes qualification.
Brand procurement teams are consolidating supplier relationships around integrated pulp-to-board operators with captive coating capabilities. Direct contracting with mills rather than through merchant distributors is displacing traditional two-step distribution in North American food and beverage accounts. This concentration is most visible in the southeastern United States, where CPG headquarters proximity to integrated manufacturing clusters enables just-in-time inventory partnerships.
Coated Recycled Paperboard Market Segmentation
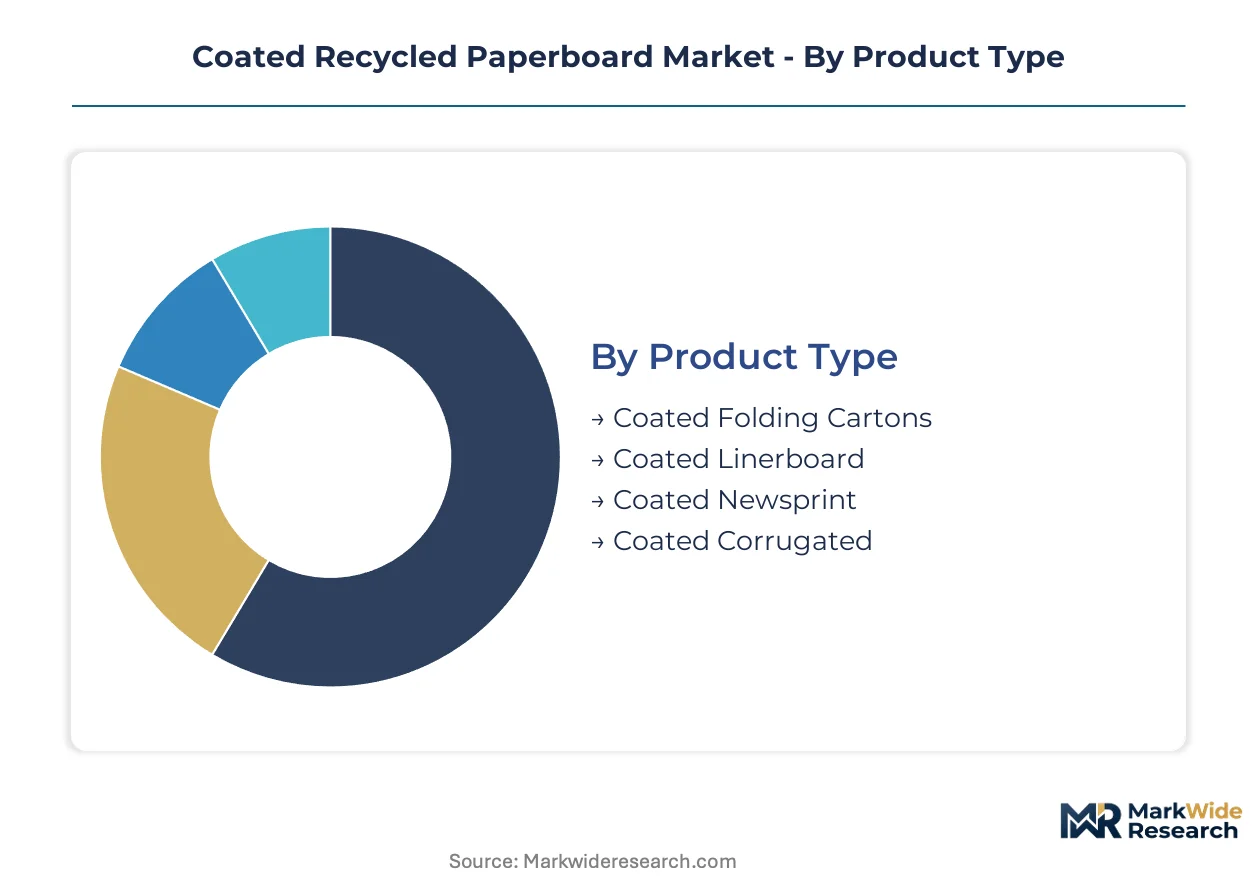
Segmentation in coated recycled paperboard reveals how substitution pressures reshape competitive priorities across substrate categories. Brand procurement teams weight printability, barrier performance, and compliance certification differently depending on end-use exposure to flexible plastic alternatives.
Product Type:
Flexible pouches and film laminates threaten certain paperboard grades more aggressively than others, forcing product-level differentiation around moisture resistance and structural integrity.
- Coated Folding Cartons:Multi-ply construction with clay or polymer surface coatings delivers rotogravure-quality print reproduction for shelf-ready packaging. Demand concentrates in North American consumer goods headquarters corridors where CPG brands prioritize point-of-sale differentiation. FDA food contact notification requirements for direct food applications sustain premium positioning against uncoated alternatives.
- Coated Linerboard:Single-ply or double-ply substrate with exterior coating layers enables print-ready e-commerce shipper exteriors without secondary labeling. Indian FMCG retrofitting of domestic supply chains accelerates specification for direct-to-consumer fulfillment applications where logistics exposure reduction outweighs corrugated cost premiums.
- Coated Newsprint:Lightweight recycled fiber base with mineral coating supports insert and promotional print applications. Retail circular and direct mail segments in Germany and France specify certified post-consumer content grades under EU Green Deal procurement mandates.
- Coated Corrugated:Fluted medium with coated liner facings bridges structural protection with brandable surfaces. E-commerce secondary packaging in the southeastern United States adopts these grades for reduced touchpoint packaging configurations.
Coated folding cartons retain volume leadership; coated linerboard holds the steepest expansion curve.
End Use Industry:
Regulatory scrutiny intensity varies sharply across end-use segments, with food contact and pharmaceutical applications facing the most demanding certification requirements.
- Consumer Goods:Cosmetics and personal care cartons demand bleached-grade whiteness specifications for hygiene perception. French and German procurement teams now require FSC Chain of Custody documentation as table-stakes qualification under extended producer responsibility frameworks.
- Food & Beverage:Direct food contact applications specify water-based barrier coatings compliant with FDA notifications and EU REACH restrictions. Brand retrofitting in India concentrates demand for domestically sourced grades with verified post-consumer fiber content.
- Electronics:Anti-static coating formulations protect sensitive components during transit. Premium unboxing experiences drive specification of high-gloss coated folding cartons for mobile device and accessory packaging.
- Pharmaceuticals:Serialization mandates and tamper-evident requirements command bleached-grade specifications with controlled substance barrier properties. North American drug packaging specifications prioritize FDA compliance documentation over cost minimization.
Food and beverage commands the largest addressable base; pharmaceutical applications generate the highest margin realization per ton.
Grade:
Raw fiber sourcing and bleaching chemistry create tiered performance and compliance profiles that segment procurement behavior across end-use applications.
- Semi-chemical:Neutral sulfite semi-chemical pulping yields high-strength fiber with moderate brightness. Industrial packaging and agricultural applications in India specify these grades for cost-optimized structural performance.
- Bleached:Elemental chlorine-free or totally chlorine-free processing achieves brightness targets above 80 ISO for premium cosmetic and pharmaceutical cartons. EU REACH restrictions on coating chemistries drive reformulation investments specifically in bleached-grade barrier systems.
- Unbleached:Natural fiber coloration supports sustainability messaging in organic and natural product segments. Kraftliner-adjacent R&D platforms in Europe specialize in barrier-coated unbleached grades for food contact.
- Others:Specialty grades including colored and textured substrates serve niche premium positioning requirements. Limited commercial scale constrains widespread adoption outside artisanal and gift packaging segments.
Bleached grades dominate premium tier positioning; unbleached grades are expanding most quickly in sustainability-positioned product lines.
Packaging Type:
Secondary packaging automation compatibility and retail shelf configuration requirements drive format selection across distribution channels.
- Boxes:Rigid structural formats for primary product containment and protection. Folding carton boxes for North American food and beverage applications specify clay-coated surfaces for high-speed filling line compatibility.
- Trays:Shallow-depth formats for display-ready presentation and portion-controlled servings. Ready-meal and fresh produce applications in France and Germany adopt coated recycled trays under single-use plastic restriction timelines.
- Sleeves:Wraparound or band formats for multi-pack consolidation and promotional messaging. Beverage multi-packs and confectionery applications leverage sleeve formats for reduced material intensity versus full cartons.
- Labels:Pressure-sensitive or cut-and-stack formats requiring coated facestock for print adhesion and moisture resistance. Wine and spirits labeling in North American markets specifies wet-strength coated grades for ice bucket durability.
Box formats retain structural dominance; sleeve applications are gaining share fastest in beverage consolidation packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates and India's PLI scheme incentives are redirecting capital toward integrated pulp-to-board facilities. Germany and France enforce extended producer responsibility frameworks that favor qualified suppliers. The United States maintains volume leadership through southeastern manufacturing clusters.
Germany
FMCG brands in Bavaria and North Rhine-Westphalia specify FSC-certified coated grades for cosmetics and pharmaceutical cartons. The country's national packaging regulator enforces delegated acts under the EU Packaging and Packaging Waste Regulation requiring mass-balance accounting for post-consumer fiber. The Hamburg industrial corridor hosts kraftliner-adjacent R&D platforms specializing in barrier-coated recycled grades for food contact.
United States
CPG headquarters in Atlanta and Charlotte drive specification of coated folding cartons for shelf-ready food and beverage packaging. FDA food contact notifications and EPA recycled content claims guidelines determine which barrier formulations gain commercial traction. The southeastern United States manufacturing belt sustains integrated pulp-to-board operations with captive coating capabilities.
India
FMCG companies in Maharashtra and Gujarat retrofit domestic supply chains around locally sourced coated recycled paperboard grades. The PLI scheme for paperboard manufacturing attracts capital toward integrated facilities serving regional demand. The Mumbai-Pune industrial corridor concentrates new capacity expansion targeting import substitution.
France
Cosmetics brands in Île-de-France require bleached-grade specifications with FSC Chain of Custody documentation as table-stakes qualification. Extended producer responsibility frameworks administered by the national environmental agency tighten recyclability mandates for premium packaging. The Lyon-Auvergne-Rhône-Alpes cluster specializes in pharmaceutical compliance cartons with serialization-ready barrier properties.
Canada
E-commerce fulfillment networks in Ontario specify coated linerboard with print-ready exteriors for direct-to-consumer shipper applications. Health Canada food contact regulations align with FDA notifications to enable cross-border formulation approvals. The Quebec manufacturing corridor concentrates unbleached-grade production for organic and natural product segments.
Coated Recycled Paperboard Market Vendor Landscape
Listed leaders compete with private specialists across certification and coating capability dimensions. The vendor base stratifies into three tiers: integrated pulp-to-board operators with captive R&D, merchant converters dependent on external formulation suppliers, and regional specialists serving single-country demand. Strategic archetypes include FSC-qualified volume leaders, kraftliner-adjacent barrier innovators, and PLI-backed domestic capacity builders. Competitive moves concentrate on backward integration into coating chemistry and geographic expansion through qualified supplier status.
Among North American integrated operators, WestRock and Graphic Packaging International exemplify the volume-leader archetype with southeastern U.S. manufacturing concentration. European competition centers on Mondi as a representative of kraftliner-adjacent R&D platforms specializing in barrier-coated recycled grades. These three companies anchor the competitive structure without exhausting the participant set.
| Leading Market Players |
|---|
| Caraustar Industries |
| PaperWorks Industries |
| WestRock |
| Mondi |
| Cascades |
| Graphic Packaging International |
| Sonoco |
| Evergreen Packaging |
| Smurfit Kappa |
| Others |
Supply Flow & Price Mechanics
Water-based barrier coatings replacing fluoropolymer formulations are simultaneously shifting supply geography toward German and French mid-sized converters while compressing pricing power among incumbent specialty chemical suppliers. This substitution dynamic restructures how value distributes across integrated mills versus formulation-dependent converters.
Pricing Analysis
Certification level creates the primary spread between qualified suppliers and secondary converters. Three-tier pricing structure across FSC-certified premium, standard-grade, and uncertified economy levels dominates contract structures. Cost compression in the economy tier is intensifying because Indian domestic capacity expansion under PLI incentives adds volume without chain-of-custody overhead. Brand procurement teams in North American consumer goods corridors show least price sensitivity for pharmaceutical-grade bleached specifications.
Supply Chain Analysis
The United States and India anchor integrated pulp-to-board manufacturing with captive coating capabilities. Recovered fiber supply draws from municipal collection programs, clay coating minerals, and water-based polymer formulations. Single-source vulnerability concentrates in EU REACH-compliant barrier chemistry suppliers. Distribution runs through direct mill-to-brand contracting that displaces traditional merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coated recycled paperboard procurement increasingly attaches certification-as-a-service layers where third-party verification and compliance documentation generate recurring revenue streams expanding faster than substrate tonnage. This service-attach dynamic repositions supplier relationships toward ongoing partnership models.
For Market Incumbents: Fortify FSC Chain of Custody certification coverage ahead of EU Packaging and Packaging Waste Regulation enforcement timelines. Backward integration into water-based coating chemistry reduces exposure to REACH restriction expansions. Capacity addition in the Mumbai-Pune corridor captures Indian FMCG retrofitting demand before PLI-subsidized domestic competitors scale.
For New Entrants and Emerging Players: Post-consumer fiber verification services represent an under-served layer where incumbents lack dedicated compliance platforms. Indian domestic supply chain retrofitting offers the most penetrable geography for regionally focused qualification. A go-to-market angle centered on 12-18 month audit acceleration for brands facing near-term deadlines creates differentiation against established players.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant converters lacking captive coating R&D. The five-to-ten year viability window favors integrated operators with mass-balance accounting capabilities and multi-jurisdiction compliance infrastructure. Acquisition target archetypes include German and French mid-sized folding carton converters with fastest-adopter positioning in water-based hybrid formulations. The signal to watch is delegated act implementation timelines under EU extended producer responsibility frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | REACH-compliant formulation control reduces reformulation risk for EU food contact applications. |
| FSC Chain of Custody Certification Investment | Mass-balance documentation capability qualifies suppliers for French and German pharmaceutical procurement. |
| Indian Domestic Capacity Expansion | PLI scheme incentives enable integrated facilities serving Maharashtra and Gujarat FMCG demand. |
| Direct Mill-to-Brand Contracting | Elimination of merchant distributors captures margin in southeastern United States CPG corridors. |
| Water-Based Barrier R&D Partnership | Clay-polymer hybrid development preempts FDA notification requirements for direct food contact. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with procurement directors at North American consumer goods headquarters, plant managers at southeastern United States integrated mills, regulatory affairs leads at German and French converters, and category buyers at Indian FMCG companies. Secondary validation drew from EPA recycled content guidelines, EU Packaging and Packaging Waste Regulation delegated acts, FDA food contact notification databases, and FSC chain-of-custody audit records. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Across the modeling period, segmentation dimensions included product type, end-use industry, grade tier, and packaging format. CAGRs were derived from regression analysis of historical volume trends and scenario-weighted regulatory implementation timelines. Forecast inputs incorporated PLI scheme disbursement schedules, EU Green Deal delegated act progression, and recovered fiber price volatility indices.
Forecasts assume regulatory continuity in EU REACH, FDA food contact, and EPA recycled content regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in extended producer responsibility enforcement timelines and water-based coating technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Middle East and Africa Coated Paper Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market