
 Tea Filter Paper Market | 2026-2036
Tea Filter Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Filter Paper Market Analytics
Subscription-based filter replenishment programs for food service chains is broadening the addressable base beyond traditional bulk procurement. Ahlstrom-Munksjö leverages its European pulp supply network to sustain cost-competitive biodegradable grades. Purico Group anchors its position through deep specialization in heat-sealed formats for Asian tea manufacturers. Mitsubishi Paper Mills competes on technical precision in composite structures for high-speed filling equipment.
Tea filter paper consists of porous sheet structures engineered from abaca pulp, wood pulp, or synthetic fibers, typically calibrated to 12-25 gram per square meter basis weights and 15-40 micron pore sizes to balance infusion flow with particle retention. The material serves the essential industrial function of enabling controlled water permeation while preventing tea leaf escape during steeping. Heat-sealed and biodegradable categories command premium positioning as regulatory pressure on plastic content intensifies across European and North American buyer pools. Non-woven formats retain volume leadership in cost-sensitive bulk segments where polypropylene and polyethylene blends still dominate procurement specifications.
FDA food-contact substance notifications govern cellulose-based filter materials entering US distribution channels, while EU REACH and the F-Gas Regulation indirectly shape fiber sourcing decisions through chemical restriction cascades. China's SAMR enforces national food safety standards for paper products contacting beverages, creating compliance thresholds for imported filter substrates. Stakeholders must monitor evolving compostability certification requirements from BPI and TÜV Austria as retail chains harden sustainability procurement criteria without waiting for harmonized regulatory mandates.
Market Dynamics
Biodegradable substrate migration is compressing polypropylene's historical dominance as EU Single-Use Plastics Directive enforcement hardens procurement specifications across Northern European tea packers. Abaca pulp sourcing networks are tightening as Philippine fiber harvests face competing industrial demand.
Growth Catalysts
- EU Single-Use Plastics Directive:The phased ban on plastic-containing tea bags accelerates heat-sealed paper format adoption across German and Dutch private-label manufacturers.
- Specialty loose-leaf expansion:Premium tea brands in China and Japan are scaling filter paper procurement for pyramid and round bag formats targeting gift-channel distribution.
- Compostability certification:BPI and TÜV Austria standards are becoming mandatory entry criteria for retail chain supplier qualification programs in North America.
Market Restraints
- Abaca fiber supply concentration:Philippine cultivation zones supply over 80% of specialty pulp for high-wet-strength grades, creating geographic single-point vulnerability.
- Biodegradable cost premium:Heat-sealed and plastic-free substrates command 35-50% unit cost premiums over polypropylene blends, compressing margin at volume-tier packers.
- Heat-seal performance ceiling:Cellulose-based seal layers exhibit 15-20% lower burst strength than synthetic alternatives, limiting line speed at high-capacity filling equipment.
Strategic Opportunities
- Subscription replenishment channels:Food service chains and office beverage programs are adopting scheduled filter paper restocking models, bypassing traditional bulk tender processes.
- India specialty tea processing:Darjeeling and Assam estate modernization is creating demand for 15-18 gsm lightweight grades calibrated to orthodox leaf formats.
- SAMR compliance services:China's food-contact paper standards are creating paid-certification revenue streams for testing laboratories serving import-dependent substrate suppliers.
Industry Challenges
- Compostability testing backlog:BPI and TÜV Austria certification queues now extend 8-14 months, delaying product launches for reformulated biodegradable grades.
- Heat-seal technician scarcity:Converting equipment operators with cellulose-based adhesive calibration expertise are concentrated in Japanese and German machinery corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Filter Paper Market |
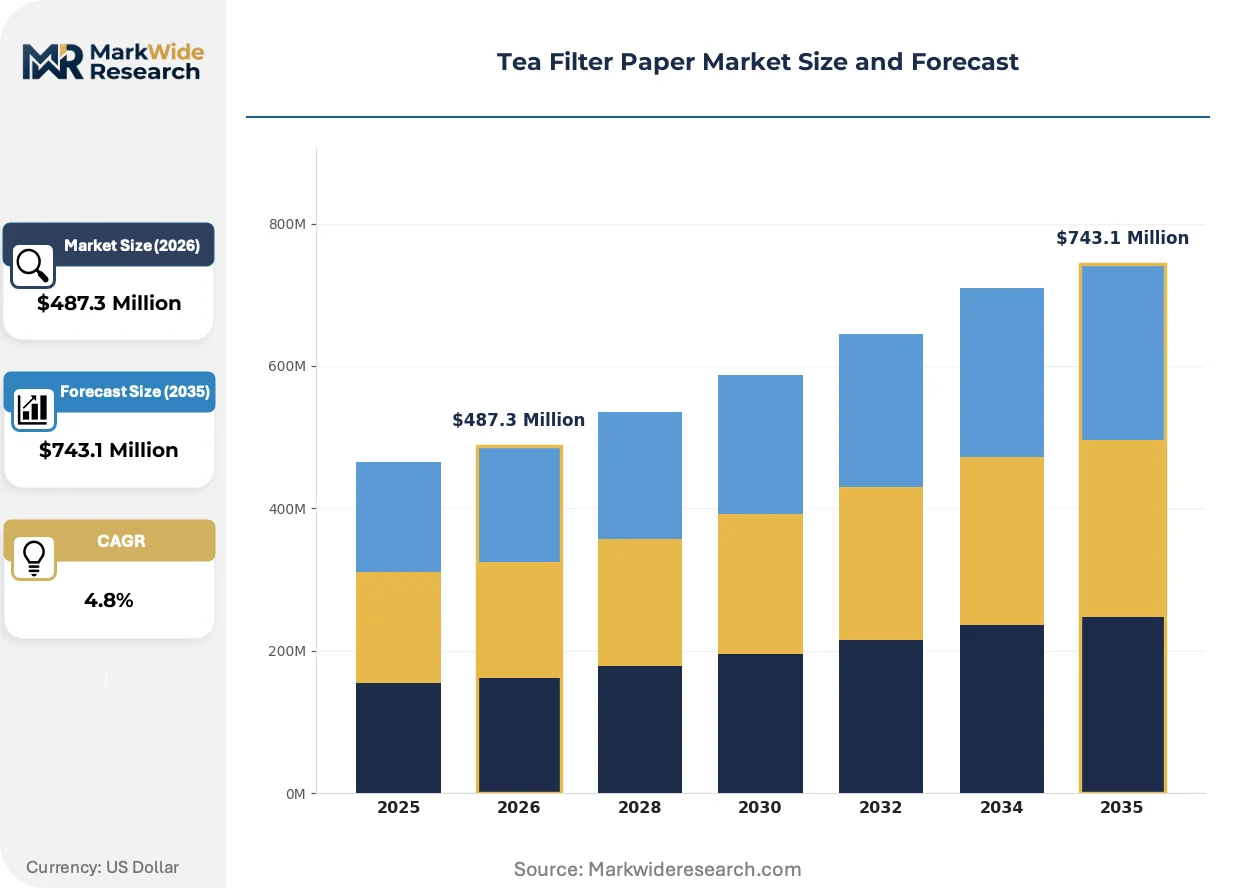
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat-Sealed, Non-Woven, Biodegradable, Composite End User: Tea Manufacturers, Food Service, Retailers, Home Users Material: Pulp, Polypropylene, Polyethylene, Nylon Packaging Type: Bulk Packaging, Retail Packs, Sachets, Eco-Friendly |
| Companies Covered | Glatfelter Corporation, Ahlstrom-Munksjö, Purico Group, Twin Rivers Paper Company, Terranova Papers, Mondi Group, Neenah Paper, Mitsubishi Paper Mills, Hebei Amusen Filter Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Filter Paper Market Evolving Landscape
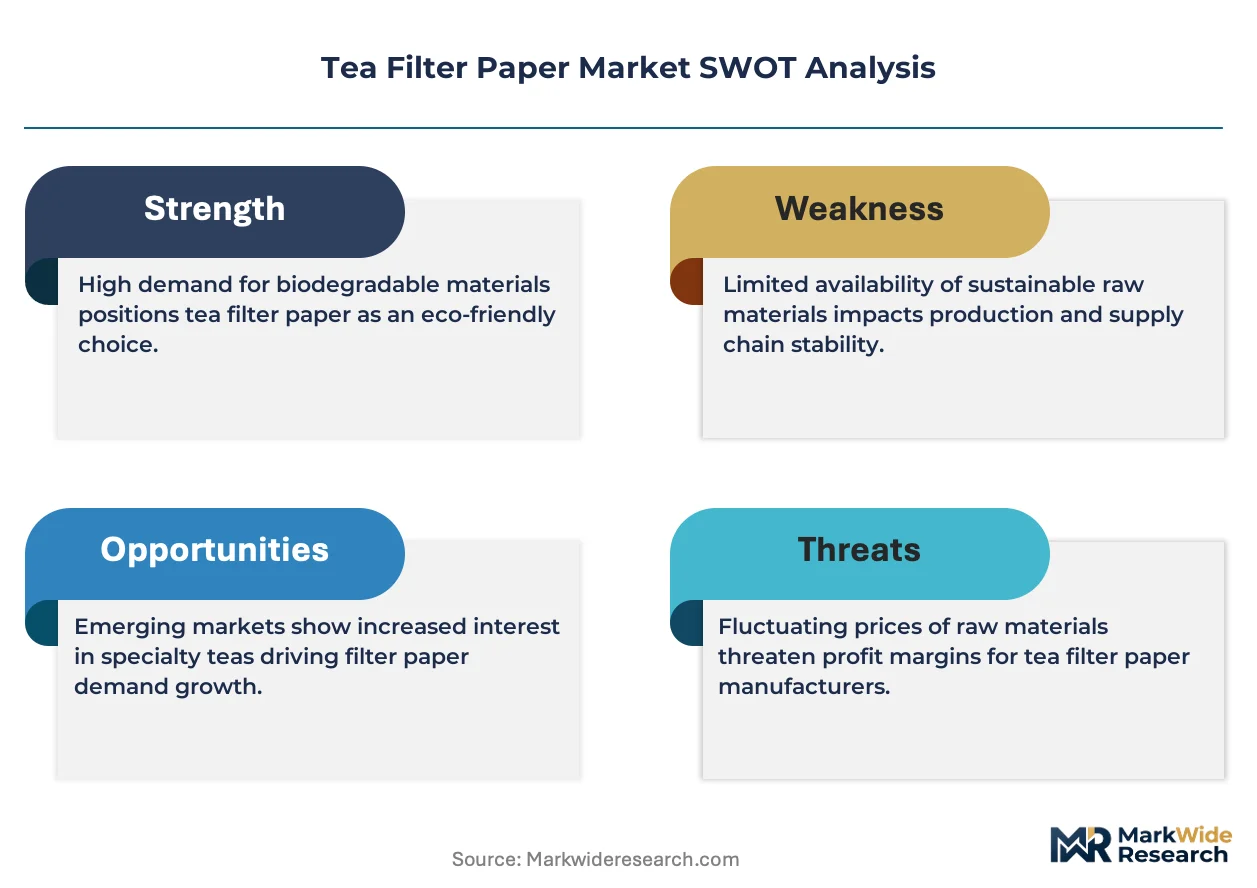
Filter paper manufacturing is bifurcating between precision-engineered biodegradable grades for premium channels and cost-optimized synthetics for commodity bulk segments. Equipment makers are retrofitting sealing stations to handle both substrate classes on shared production lines.
Multi-layer composite structures are modularizing heat-seal performance by separating infusion-control and structural functions into discrete fiber layers. Japanese high-speed bagging equipment manufacturers are adopting these formats for 400+ bags-per-minute lines. The technology is modularizing supplier relationships as converters specify layer compositions rather than purchasing monolithic substrate rolls.
REACH chemical restriction cascades are forcing pulp bleaching sequence modifications across European supply chains. ECHA substance candidate list updates are eliminating specific wet-strength resin chemistries previously standard in food-contact papers. Northern European tea packers are qualifying alternative fiber treatments ahead of formal restriction deadlines to avoid supply interruption.
Food service procurement teams are consolidating filter paper purchasing into beverage-system contracts rather than standalone substrate tenders. Casino and hotel chains in Las Vegas and Macau are bundling filter supply with brewing equipment leases. This bundling is most visible in North American and East Asian hospitality verticals where operational simplicity outweighs unit cost optimization.
Tea Filter Paper Market Segmentation
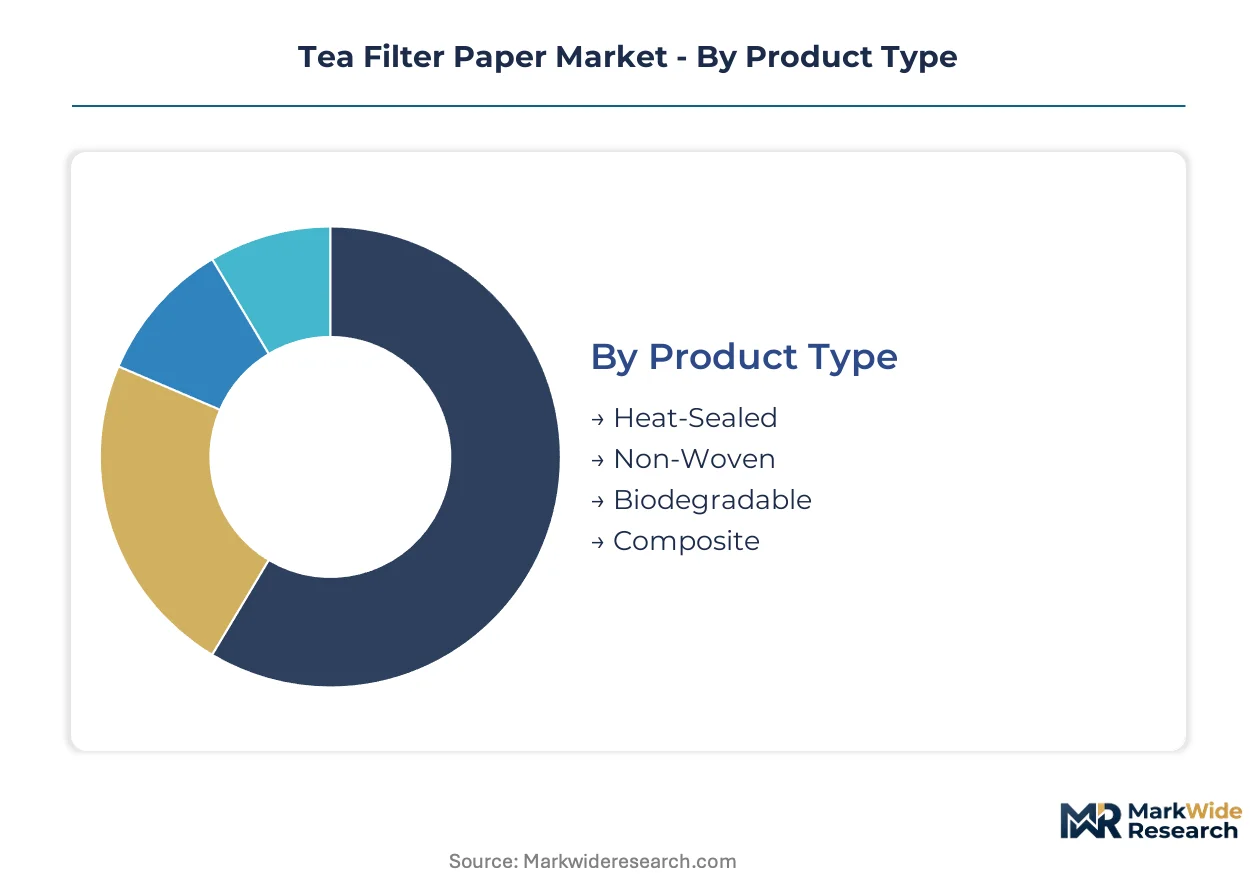
Tea filter paper procurement splits sharply between commodity-grade synthetics for high-volume production and certified biodegradable substrates for premium positioning. Regulatory pressure on plastic content is compressing the middle tier, forcing packers to choose sides. Each segmentation dimension reveals a different axis of competition: technical performance, channel access, material provenance, or sustainability signaling.
Product Type:
Volume leadership sits with synthetic non-wovens, while premium positioning concentrates in heat-sealed and biodegradable formats responding to EU Single-Use Plastics Directive enforcement.
- Heat-Sealed:Cellulose-based seal layers bond through thermal compression without adhesive additives, meeting plastic-free claims required by German and Dutch private-label manufacturers. Burst strength limitations constrain line speeds at high-capacity filling equipment in Japanese machinery corridors.
- Biodegradable:Abaca and wood pulp compositions achieve BPI and TÜV Austria compostability certification, commanding supplier qualification status at North American retail chains. Certification queues extending 8-14 months create launch delays for reformulated grades.
- Non-Woven:Polypropylene and polyethylene blends retain cost-sensitive bulk procurement specifications where regulatory pressure remains muted.
- Composite:Modular multi-layer structures separate infusion-control and structural functions for 400+ bags-per-minute Japanese high-speed lines.
Today's leader: Heat-Sealed. Tomorrow's challenger: Biodegradable.
End User:
Channel access determines specification complexity, with food service and retail chains driving standardization while specialty tea manufacturers demand customization.
- Tea Manufacturers:Private-label packers in Germany's manufacturing corridor and China's processing clusters dominate procurement volume, specifying 12-25 gsm basis weights calibrated to filling equipment.
- Food Service:Las Vegas and Macau hospitality chains bundle filter supply with brewing equipment leases, consolidating purchasing into beverage-system contracts rather than standalone tenders.
- Retailers:Compostability certification from BPI and TÜV Austria has become mandatory entry criteria for supplier qualification programs across North American retail chains.
- Home Users:Specialty loose-leaf and premium bagged tea brands in China and Japan are scaling procurement for pyramid and round bag formats targeting gift-channel distribution.
Tea Manufacturers capture current volume concentration. Food Service channels are gaining share fastest through subscription replenishment models.
Material:
Raw material sourcing geography creates supply vulnerability, with Philippine abaca cultivation zones supplying over 80% of specialty pulp for high-wet-strength grades.
- Pulp:Abaca and wood fiber compositions enable biodegradable positioning, with Ahlstrom-Munksjö leveraging European pulp networks for cost-competitive grades.
- Polypropylene:Historical volume leader facing compression as EU Single-Use Plastics Directive enforcement hardens procurement specifications across Northern European tea packers.
- Polyethylene:Cost-optimized synthetic blends retain dominance in price-sensitive bulk segments where regulatory pressure remains limited.
- Nylon:Technical precision in composite structures for high-speed filling equipment, with Mitsubishi Paper Mills competing on specification tightness.
Pulp is climbing the fastest on regulatory tailwinds. Polypropylene is defending residual volume in lagging jurisdictions.
Packaging Type:
Format choice signals channel strategy, with bulk packaging serving manufacturing scale and retail packs carrying sustainability certification burden.
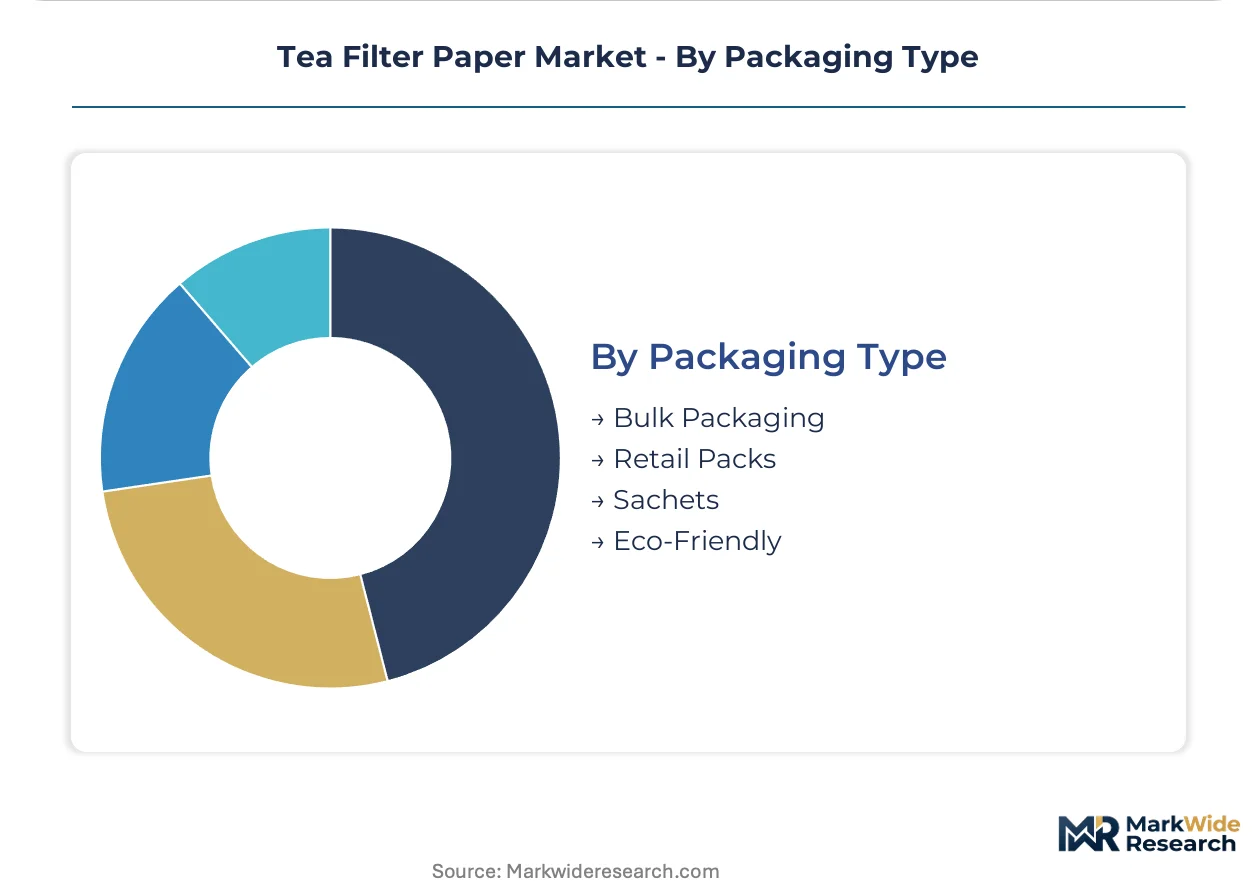
- Bulk Packaging:Roll stock and master cases serve high-volume tea manufacturers in Germany and China, optimizing logistics for continuous production.
- Retail Packs:Consumer-facing formats require compostability labeling and certification documentation for North American and European retail placement.
- Sachets:Individual-portion formats concentrate in food service and hospitality channels where operational simplicity outweighs unit cost optimization.
- Eco-Friendly:Plastic-free and biodegradable positioning commands premium shelf placement at specialty retailers, with Purico Group anchoring supply through heat-sealed format specialization for Asian manufacturers.
Bulk Packaging holds current volume leadership. Eco-Friendly formats represent the steepest expansion trajectory on sustainability procurement hardening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's private-label manufacturing corridor and China's modernizing tea processing clusters demonstrate divergent procurement patterns, with European buyers prioritizing compostability certification while Asian manufacturers optimize for heat-seal performance on high-speed equipment.
Germany
Private-label tea packers in the Lower Saxony and Bavaria corridors drive heat-sealed paper format adoption as EU Single-Use Plastics Directive enforcement hardens procurement specifications. ECHA substance candidate list updates are eliminating specific wet-strength resin chemistries previously standard in food-contact papers. The Hamburg-Bremen logistics cluster hosts converting operations serving Dutch and Scandinavian retail chains.
China
Specialty loose-leaf tea brands in Fujian and Zhejiang provinces are scaling filter paper procurement for pyramid and round bag formats targeting gift-channel distribution. SAMR enforces national food safety standards for paper products contacting beverages, creating compliance thresholds for imported filter substrates. The Yangtze River Delta processing cluster is modernizing with lightweight 15-18 gsm grades calibrated to orthodox leaf formats.
United States
Food service chains and office beverage programs are adopting subscription-based filter replenishment models, bypassing traditional bulk tender processes. FDA food-contact substance notifications govern cellulose-based filter materials entering US distribution channels. Las Vegas hospitality chains bundle filter supply with brewing equipment leases, consolidating purchasing into beverage-system contracts.
Japan
High-speed bagging equipment manufacturers are adopting multi-layer composite structures for 400+ bags-per-minute production lines. METI industrial standards shape fiber sourcing decisions through chemical restriction cascades. The Nagoya machinery corridor concentrates converting equipment operators with cellulose-based adhesive calibration expertise.
Philippines
Abaca cultivation zones supply over 80% of specialty pulp for high-wet-strength grades, creating geographic single-point vulnerability for biodegradable substrate supply chains. The country's national agricultural regulator monitors fiber harvests facing competing industrial demand from non-tea applications. Davao and Bicol growing regions face tightening supply networks as global demand for plastic-free alternatives accelerates.
Tea Filter Paper Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium biodegradable grades concentrating among pulp-network integrated players while commodity synthetics fragment across regional converters. The vendor base organizes around three strategic archetypes: European pulp-integrated specialists, Asian heat-seal format experts, and synthetic non-woven volume producers. Competitive moves center on compostability certification pre-positioning ahead of regulatory deadlines and retrofitting sealing stations to handle biodegradable substrates on shared production lines.
Among European pulp-integrated specialists, Ahlstrom-Munksjö and Mondi Group represent the biodegradable-grade tier, leveraging continental fiber supply networks to sustain cost-competitive positioning as REACH chemical restrictions cascade through bleaching sequences. Mitsubishi Paper Mills occupies a position within the precision-engineered composite segment, while Purico Group anchors the heat-seal specialization archetype serving Asian tea manufacturers. These three exemplify how supplier relationships are modularizing as converters specify layer compositions rather than purchasing monolithic substrate rolls.
| Leading Market Players |
|---|
| Glatfelter Corporation |
| Ahlstrom-Munksjö |
| Purico Group |
| Twin Rivers Paper Company |
| Terranova Papers |
| Mondi Group |
| Neenah Paper |
| Mitsubishi Paper Mills |
| Hebei Amusen Filter Paper |
| Others |
Value Network & Pricing Analysis
Abaca fiber harvests from Philippine cultivation zones flow through heat-sealed and biodegradable pricing tiers, with EU Single-Use Plastics Directive enforcement compressing polypropylene's residual cost advantage across Northern European buyer pools.
Pricing Analysis
Capacity additions in Nordic pulp networks are reshaping price floors for compostable grades as Ahlstrom-Munksjö leverages continental fiber supply to sustain cost-competitive positioning. Three-tier pricing structure across premium, standard, and economy levels separates BPI-certified biodegradable substrates from heat-sealed cellulose and commodity polypropylene blends. Cost compression in synthetic non-wovens is intensifying because REACH chemical restrictions are eliminating wet-strength resin chemistries previously standard in food-contact papers. Volume-tier packers in Germany's private-label corridor exhibit highest price sensitivity, while Las Vegas hospitality chains bundling filter supply with equipment leases show lowest.
Supply Chain Analysis
Regional distribution centers in Hamburg-Bremen and the Yangtze River Delta anchor hub-and-spoke patterns serving German and Chinese tea processing clusters. Raw material sourcing draws from Philippine abaca cultivation zones, European wood pulp networks, and Middle Eastern polypropylene resin production. Single-source vulnerability concentrates in specialty pulp supply, with over 80% of high-wet-strength grades tethered to Davao and Bicol growing regions. Distribution runs through converting operations co-located with high-speed bagging equipment manufacturers in Japan's Nagoya machinery corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable substrate migration creates margin-expansion opportunity as certification premiums offset abaca fiber cost volatility across premium buyer segments.
For Market Incumbents: Deploy compostability certification pre-positioning to capture EU Single-Use Plastics Directive enforcement tailwinds before formal restriction deadlines. Anchor heat-seal format specialization through deep technical partnerships with Japanese high-speed equipment manufacturers. Defend against Purico Group's Asian market concentration by qualifying alternative fiber treatments ahead of ECHA substance candidate list updates. For New Entrants and Emerging Players: Food service subscription replenishment programs represent the most penetrable buyer archetype, bypassing traditional bulk tender processes dominated by established pulp-integrated specialists. Target India's Darjeeling and Assam estate modernization for lightweight 15-18 gsm grades calibrated to orthodox leaf formats. Enter through SAMR compliance services, creating paid-certification revenue streams for testing laboratories serving import-dependent substrate suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where heat-seal technician scarcity concentrates operational capability in Japanese and German machinery corridors. Five-to-ten year viability favors pulp-network integrated players with backward fiber supply control over synthetic non-woven converters facing regulatory compression. Monitor BPI and TÜV Austria certification queue lengths as inflection indicator for biodegradable grade launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | BPI and TÜV Austria standards are becoming mandatory entry criteria for North American retail chain supplier qualification programs. |
| Backward Integration into Abaca Supply | Philippine fiber harvest concentration creates geographic single-point vulnerability requiring upstream control for biodegradable substrate security. |
| Heat-Seal Equipment Retrofit Partnerships | Japanese high-speed bagging manufacturers are adopting multi-layer composite structures for 400+ bags-per-minute production lines. |
| Subscription Replenishment Channel Launch | Food service chains and office beverage programs are adopting scheduled filter paper restocking models bypassing traditional bulk tenders. |
| SAMR Compliance Service Expansion | China's national food safety standards for paper products contacting beverages create paid-certification revenue streams for testing laboratories. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tea manufacturer procurement directors, converting equipment operators, food service chain beverage program managers, and compostability certification laboratory technical leads with secondary validation from FDA food-contact substance notifications, EU REACH substance candidate list updates, SAMR national food safety standards, and customs trade data for abaca pulp imports. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions across the analysis window.
Segment-weighting approaches calibrated product type splits between heat-sealed, biodegradable, non-woven, and composite structures, end user channel concentrations across tea manufacturers, food service, retail chains, and home users, material sourcing patterns for pulp, polypropylene, polyethylene, and nylon, and packaging format distributions through bulk, retail, sachet, and eco-friendly categories. CAGRs were derived from fitted growth curves incorporating EU Single-Use Plastics Directive enforcement timelines, specialty loose-leaf tea brand expansion trajectories in China and Japan, and compostability certification adoption rates across North American retail chains.
Underlying measurement precision varies by segment; heat-sealed and biodegradable categories carry tighter precision than synthetic non-wovens given clearer regulatory enforcement timelines and certification documentation trails. Forecasts reflect assumptions around abaca fiber supply stability, REACH chemical restriction implementation schedules, and food service subscription model adoption velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market