
 Paperboard Clamshell Boxes Market | 2026-2036
Paperboard Clamshell Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Paperboard Clamshell Boxes Market Outlook
Quick-service restaurant chains is recalibrating the Paperboard Clamshell Boxes market as operators replace expanded polystyrene with fiber-based alternatives. WestRock anchors North American supply through integrated pulp-to-boxboard operations across the southeastern United States. Huhtamaki competes in European foodservice channels with specialized barrier-coated clamshell designs for hot-fill applications. International Paper Company dominates corrugated and paperboard substrate supply, extending its reach into molded fiber clamshell adjacent categories.
Paperboard clamshell boxes are hinged, single-piece containers formed from SBS, CUK, or recycled paperboard grades, typically ranging from 12 to 24 points in caliper, designed to protect, display, and secure consumer goods through retail and foodservice distribution. The primary commercial purpose centers on providing rigid, printable protection with tamper-evident closure for perishables and fragile merchandise. Eco-Friendly variants are capturing disproportionate margin pools as brand owners commit to post-consumer recycled content minimums and compostability certifications. Custom Clamshell formats sustain premium pricing in Cosmetics and Electronics end uses where die-cut windows and embossed branding justify unit cost premiums over Standard Clamshell configurations.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications jointly shape material selection, with the former mandating recyclability-by-design and the latter governing fluorochemical barrier coatings in direct food applications. BIS certification requirements in India restrict uncoated paperboard imports for food contact, creating localized supply chain constraints for multinational converters. Stakeholders must monitor evolving extended producer responsibility fee structures and barrier coating chemistries to preserve market access across jurisdictions with diverging material approval timelines.
Market Dynamics
Quick-service restaurant chains and meal-kit services are dismantling polystyrene clamshell demand, redirecting capital toward fiber-based forming lines and barrier-coated paperboard substrates.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability-by-design requirements are forcing converters toward mono-material paperboard constructions and post-consumer recycled content minimums.
- Hot-fill barrier coatings:Advanced fluorochemical-free formulations now withstand temperatures above 85°C, unlocking ready-meal and soup applications previously reserved for plastic.
- Germany:Centralized retail distribution networks and strict environmental compliance standards favor standardized clamshell formats with verified compostability certifications.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft pulp prices swing with energy and freight costs, compressing converter margins on fixed-price foodservice contracts.
- Barrier coating regulatory friction:FDA food contact substance notification timelines for novel fluorochemical alternatives stretch 18-24 months, delaying product launches.
- Molded fiber substitution:Bagasse and wheat straw molded fiber clamshells compete on cost in ambient-temperature applications, limiting paperboard expansion in produce packaging.
Strategic Opportunities
- India:BIS certification requirements restrict uncoated paperboard imports for food contact, creating localized supply chain gaps for converters with domestic forming capacity.
- Cosmetics premium formats:Die-cut windows and embossed branding on custom clamshells command 40-60% unit premiums over standard configurations in skincare and electronics unboxing.
- Extended producer responsibility tailwinds:Fee structures favoring recyclable and compostable materials are redirecting brand owner procurement budgets toward certified paperboard suppliers.
Industry Challenges
- Barrier coating formulation expertise:Shortage of chemists skilled in balancing grease resistance, heat tolerance, and repulpability is constraining R&D throughput at mid-tier converters.
- Capex intensity for forming lines:Automated clamshell presses with inline coating stations require capital commitments that strain balance sheets amid interest rate volatility.
- Compostability certification timelines:TÜV Austria and BPI verification processes for industrial and home compostability add 6-12 months to new product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paperboard Clamshell Boxes Market |
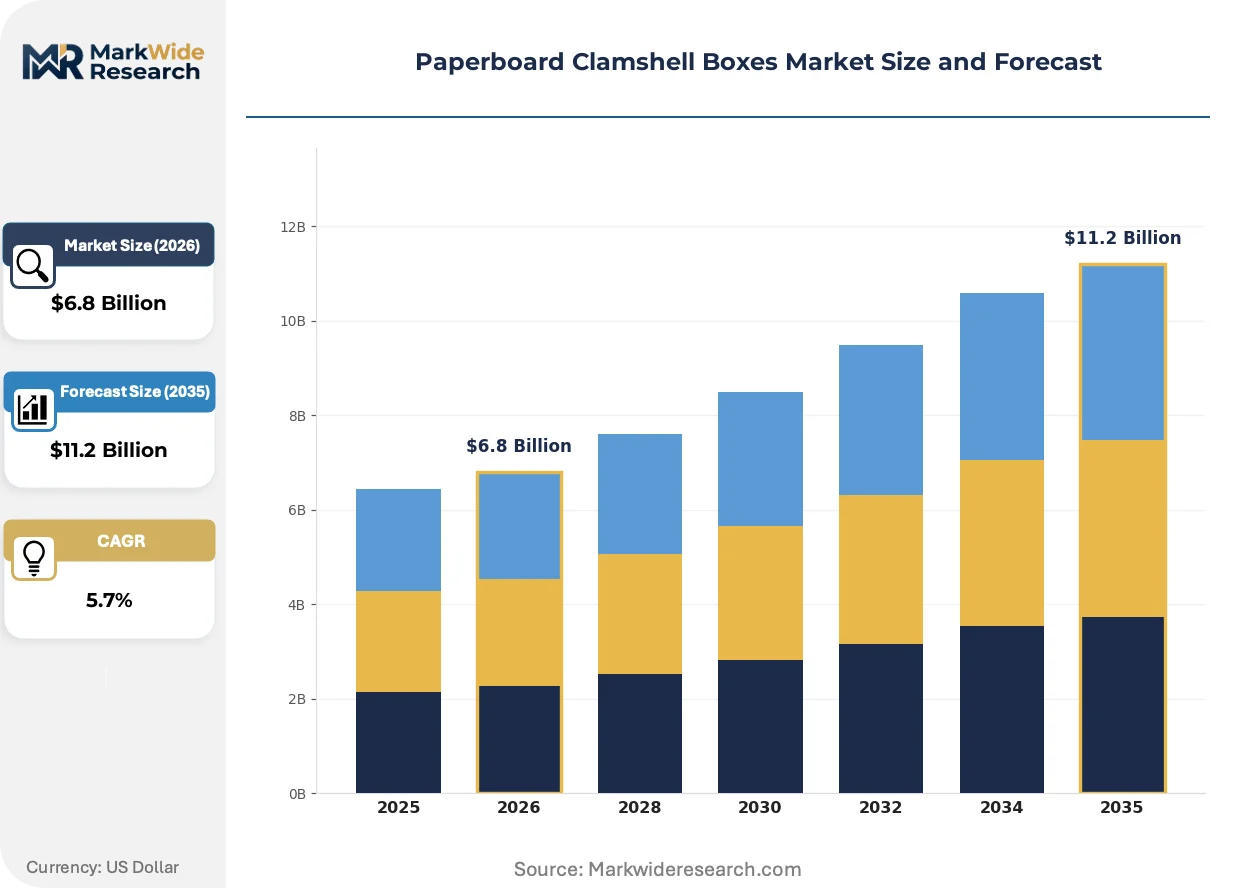
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Clamshell, Custom Clamshell, Eco-Friendly, Dual Compartment End User: Food Industry, Electronics, Cosmetics, Retail Packaging Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales Thickness: Lightweight, Medium, Heavy, Extra Heavy |
| Companies Covered | WestRock, International Paper Company, Packaging Corporation of America, Graphic Packaging International, Sonoco Products Company, Georgia-Pacific, Huhtamaki, Amcor, Pactiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paperboard Clamshell Boxes Market Strategic Shifts
Barrier-coated paperboard formulations and automated forming technologies are compressing the cost gap with plastic clamshells while regulatory mandates accelerate material substitution timelines.
Water-based and bio-based barrier coatings are consolidating market share in hot-fill and greasy food applications. Quick-service restaurant procurement teams specify these formulations for fry and burger clamshells. The technology is consolidating supplier bases around converters with captive coating capabilities, squeezing toll-coating dependent competitors.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant coatings across European foodservice channels. Industrial consequences include accelerated validation of cellulose-based and silicate barrier alternatives. German and French quick-service operators are responding with supplier qualification programs that prioritize fluorine-free certifications.
Direct sourcing from converters is displacing distributor intermediaries in large quick-service and meal-kit accounts. Procurement teams at major restaurant chains now negotiate volume commitments directly with integrated paperboard manufacturers. This pattern is most visible in the United States, where southeastern pulp-to-boxboard operations offer transparent cost structures and shorter lead times than Asian imports.
Paperboard Clamshell Boxes Market Segmentation
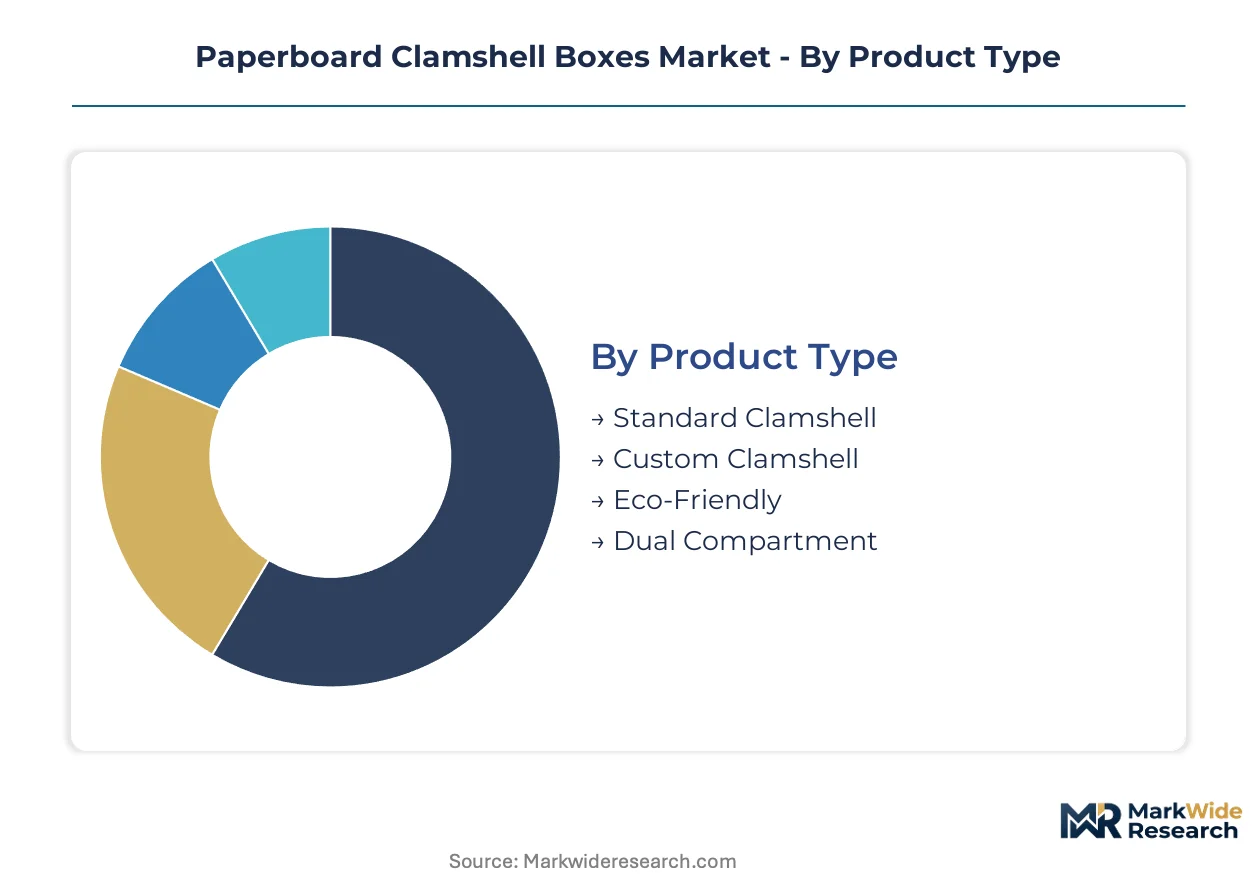
Paperboard clamshell boxes segment across four functional dimensions that determine material specification, barrier performance requirements, and channel economics. Product type and end-use classifications drive the steepest pricing differentiation, while thickness and distribution channel selections govern logistics cost structures and regional competitive positioning.
Product Type:
Converter investment cycles favor equipment that can pivot between commodity and premium formats without retooling delays.
- Eco-Friendly:Post-consumer recycled content grades and compostable barrier coatings command procurement premiums from quick-service restaurant chains with verified sustainability commitments. Demand concentrates in Germany and France where ECHA REACH restrictions on fluorochemicals intersect with centralized retail distribution networks requiring TÜV Austria compostability certifications.
- Custom Clamshell:Die-cut windows, embossed branding, and specialized hinge geometries serve cosmetics and electronics unboxing experiences. Skincare brands in premium channels specify these formats for 40-60% unit cost premiums over standard configurations.
- Standard Clamshell:SBS and CUK substrates in 12-20 point calipers dominate high-volume foodservice applications with minimal print customization.
- Dual Compartment:Partitioned designs separate hot and cold components or entree and side dishes for meal-kit services and ready-meal retail.
Volume placements concentrate in Standard Clamshell; the faster expansion belongs to Eco-Friendly.
End User:
Application-specific barrier requirements force substrate and coating selections that segment converter capabilities.
- Food Industry:Hot-fill and grease-resistant formulations now withstand temperatures above 85°C, unlocking soup and ready-meal applications. Quick-service restaurant chains and meal-kit services are dismantling polystyrene demand and redirecting capital toward fiber-based forming lines.
- Cosmetics:Rigid protection with tamper-evident closure and premium print surfaces supports skincare and fragrance unboxing experiences where packaging extends brand identity.
- Electronics:Anti-static coatings and precision die-cuts protect fragile components through e-commerce distribution with drop-test certification requirements.
- Retail Packaging:General merchandise applications favor cost-optimized SBS grades with standard hinge geometries for ambient-temperature display.
Food Industry captures the largest placement volumes; Cosmetics delivers the steepest margin expansion trajectory.
Distribution Channel:
Channel selection determines lead time requirements, inventory carrying costs, and converter-customer contractual structures.
- Direct Sales:Large quick-service and meal-kit accounts negotiate volume commitments directly with integrated paperboard manufacturers, displacing distributor intermediaries. Southeast U.S. pulp-to-boxboard operations offer transparent cost structures and shorter lead times than Asian imports.
- Wholesale:Regional distributors aggregate fragmented foodservice and retail demand, requiring converters to maintain safety stock for just-in-time replenishment.
- Supermarkets:Private-label and store-brand clamshells for deli and bakery counters specify standardized formats with high print consistency.
- Online Retail:E-commerce channels for small-batch cosmetics and electronics accessories favor quick-turn digital print with minimal order minimums.
Direct Sales commands the highest volume commitments; Online Retail is climbing the fastest as digital procurement penetrates mid-tier accounts.
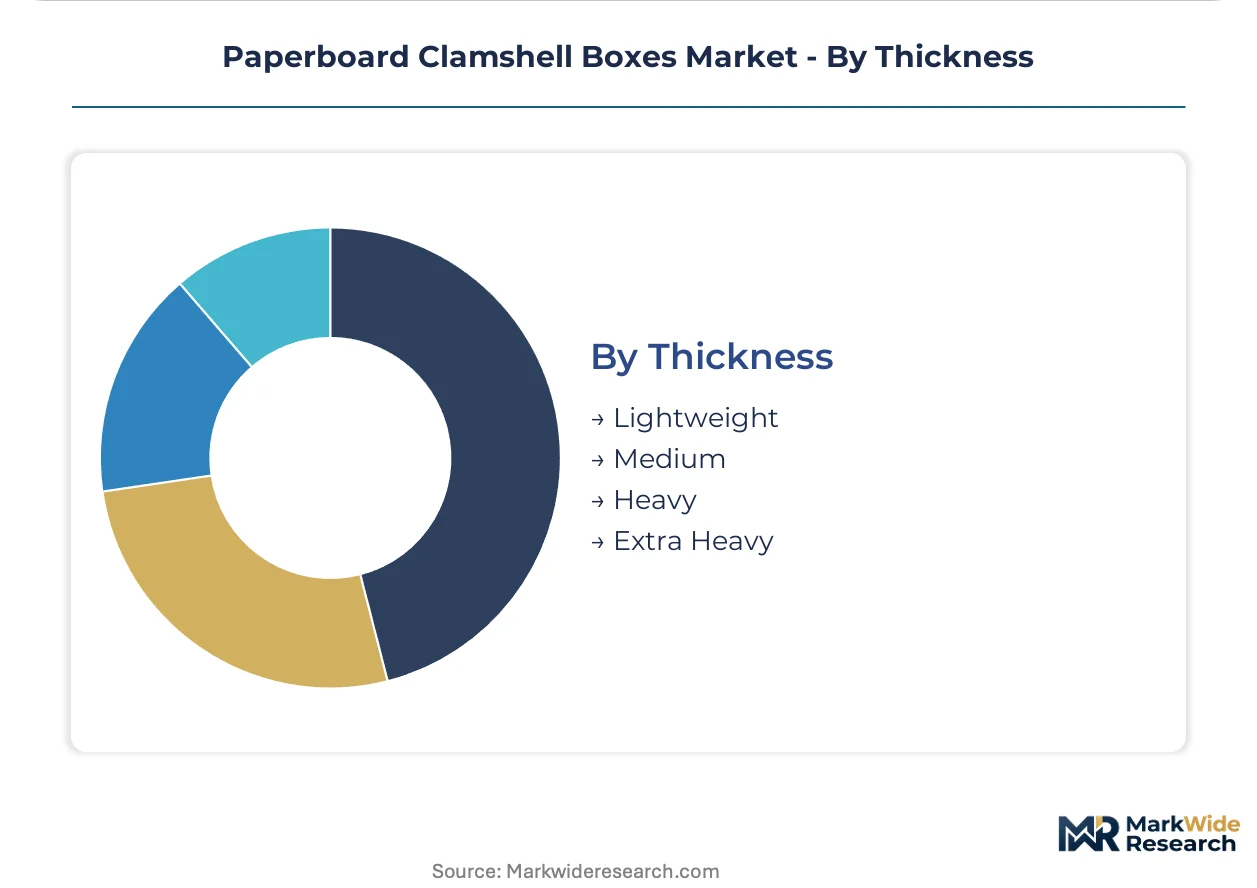
Thickness:
Caliper selection balances structural rigidity against material cost and freight cube efficiency.
- Medium:16-20 point SBS and CUK grades serve the broadest foodservice and retail applications where compression strength must survive distribution stacking without excess weight.
- Heavy:20-24 point constructions protect fragile electronics and premium cosmetics through extended supply chains with multiple handling points.
- Lightweight:12-14 point grades reduce freight costs for ambient-temperature produce and bakery items with short distribution cycles.
- Extra Heavy:Above 24 point specialized grades address industrial components and heavy merchandise requiring maximum stack strength.
Medium thickness dominates current placements; Heavy calipers are gaining share fastest in electronics and cosmetics premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-boxboard operations in the southeastern United States attract capital through state-level manufacturing tax credits and accelerated depreciation schedules for sustainable packaging equipment.
United States
Quick-service restaurant procurement teams negotiate direct volume commitments with southeastern pulp-to-boxboard manufacturers. FDA food contact substance notifications govern fluorochemical barrier coatings in direct food applications. Charlotte and Atlanta anchor forming line investments where automated presses with inline coating stations serve national foodservice distribution networks.
Germany
Centralized retail distribution networks require standardized clamshell formats with TÜV Austria compostability certifications. ECHA REACH restrictions on per- and polyfluoroalkyl substances force reformulation of grease-resistant coatings across foodservice channels. The Rhine-Ruhr industrial corridor concentrates converter capacity serving quick-service operators with fluorine-free qualification programs.
India
Meal-kit services and organized retail expansion drive demand for food-grade paperboard clamshells with BIS certification compliance. BIS requirements restrict uncoated paperboard imports for food contact, creating localized supply chain gaps. Maharashtra and Gujarat host emerging forming capacity as multinational converters establish domestic production to bypass import restrictions.
China
E-commerce penetration for cosmetics and electronics accessories accelerates small-batch digital print demand for premium unboxing formats. NMPA and GB standards govern food contact paperboard safety in parallel with export market requirements. The Yangtze River Delta clusters die-cutting and embossing specialists serving skincare brands with custom windowed clamshell designs.
France
Quick-service operators prioritize fluorine-free barrier coatings ahead of phased REACH enforcement timelines. ANSM and environmental ministry directives accelerate supplier qualification programs for compostable packaging. The Île-de-France region anchors converter R&D facilities developing cellulose-based grease resistance for hot-fill applications.
Paperboard Clamshell Boxes Market Competitive Environment
Top-tier vendors anchor integrated pulp-to-boxboard supply, while mid-tier converters compete through specialized barrier coating capabilities and regional forming capacity. The market structure favors players with captive fiber supply and inline coating infrastructure over toll-dependent competitors. Three archetypes dominate: integrated forest products conglomerates with southeastern U.S. pulp operations, European specialists in hot-fill barrier formulations, and Asia-Pacific converters leveraging proximity to e-commerce fulfillment networks. Competitive moves concentrate on backward integration into pulp supply and geographic expansion through domestic forming capacity in regulated import markets.
Among North American integrated manufacturers, WestRock and International Paper Company exemplify scale-driven archetypes with captive pulp supply and transparent cost structures for direct foodservice procurement. Huhtamaki occupies a position within the European specialist tier, representing converters with advanced barrier-coated designs for temperature-critical applications. These three anchors illustrate the geographic and capability segmentation shaping vendor selection criteria across quick-service, retail, and e-commerce channels.
| Leading Market Players |
|---|
| WestRock |
| International Paper Company |
| Packaging Corporation of America |
| Graphic Packaging International |
| Sonoco Products Company |
| Georgia-Pacific |
| Huhtamaki |
| Amcor |
| Pactiv |
| Others |
Value Chain & Pricing Dynamics
Automated clamshell presses with inline coating stations are compressing unit economics while simultaneously concentrating supply among converters with capital deployment capacity in the southeastern United States. This equipment transition rewards integrated pulp-to-boxboard operations with captive barrier formulation capabilities, squeezing toll-dependent competitors and reshaping pricing power across foodservice procurement channels.
Pricing Analysis
Short lead-time premiums of 15-25% apply to direct sales contracts with quick-service restaurant chains requiring just-in-time replenishment, while spot inventory from regional distributors trades at discounts. Contract-based long-term offtake dominates volume placements, with price differentiation resting on certification tier and vertical integration status. Cost compression in standard clamshell grades is intensifying because pulp cost volatility and energy freight surges compress converter margins on fixed-price foodservice agreements. Mid-tier foodservice operators exhibit highest price sensitivity; premium cosmetics and electronics brands show least sensitivity due to unboxing experience requirements.
Supply Chain Analysis
Workforce availability constraints in Georgia, North Carolina, and Alabama are limiting expansion of automated forming capacity despite state-level manufacturing tax credits. Supply concentrates in the United States, Germany, and China, with raw material dependencies on northern bleached softwood kraft pulp, fluorochemical-free barrier coatings, and post-consumer recycled fiber grades. Single-source vulnerability sits with specialized chemists skilled in balancing grease resistance, heat tolerance, and repulpability. Distribution runs through direct sales channels for large accounts and wholesale distributors for fragmented foodservice demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based and bio-based barrier coatings are displacing legacy fluorochemical formulations, creating a technology-transition window where coating expertise determines competitive survival. This substitution phase rewards early movers with validated compostability certifications and punishes laggards facing extended product qualification cycles.
For Market Incumbents: Cement barrier coating formulation leadership through captive R&D investment in cellulose-based and silicate alternatives, as ECHA REACH restrictions on per- and polyfluoroalkyl substances threaten existing grease-resistant product lines. Add automated forming capacity in Germany to serve centralized retail distribution networks with TÜV Austria compostability certifications, defending against molded fiber substitution in ambient-temperature applications. For New Entrants and Emerging Players: Fluorine-free hot-fill barrier technology offers a technology-first wedge into quick-service restaurant supplier qualification programs in France and Germany ahead of phased enforcement timelines. Target India's meal-kit services and organized retail expansion, where BIS certification requirements restrict uncoated paperboard imports and create localized supply chain gaps for converters with domestic forming capacity. Pursue direct sourcing relationships with multinational meal-kit operators seeking transparent cost structures. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated forest products conglomerates seeking barrier coating capabilities and geographic expansion through domestic forming capacity in regulated import markets. Five-to-ten year viability favors converters with captive pulp supply and inline coating infrastructure over toll-dependent competitors. Watch FDA food contact substance notification timelines for novel fluorochemical alternatives as inflection indicator for product launch velocity and R&D throughput.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber access insulates WestRock and International Paper from northern bleached softwood kraft price volatility. |
| Fluorine-Free Barrier Certification | TÜV Austria and BPI verification unlocks quick-service procurement in Germany and France under REACH restrictions. |
| Domestic Forming Capacity in India | Maharashtra and Gujarat facilities bypass BIS import restrictions on uncoated paperboard for food contact. |
| Direct Sales Channel Expansion | Southeastern U.S. pulp-to-boxboard operations displace distributor intermediaries with transparent cost structures. |
| Custom Clamshell Premium Formats | Die-cut windows and embossed branding command 40-60% unit premiums in cosmetics and electronics unboxing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with paperboard converter plant managers, quick-service restaurant procurement leads, barrier coating R&D directors, and meal-kit supply chain planners. FDA food contact substance notifications, ECHA REACH restriction dossiers, BIS certification requirements, and TÜV Austria compostability verification records provided regulatory validation. Bottom-up volume modeling across product types and end uses triangulated against top-down pulp consumption and forming capacity estimates.
Granularity-level modeling addressed product type, end user, distribution channel, and thickness dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by pricing tier and regional demand concentration. Forecast inputs incorporated quick-service restaurant capital expenditure cycles for fiber-based forming lines, EU Packaging and Packaging Waste Regulation material recovery target timelines, and e-commerce penetration rates for cosmetics and electronics accessories.
Several conditions sit outside the modeled scope, including abrupt pulp price spikes exceeding historical volatility bands, accelerated REACH enforcement timelines, and breakthrough molded fiber cost reductions in hot-fill applications. Forecasts reflect assumptions about regulatory approval continuity and barrier coating validation throughput. Material deviation in FDA notification timelines or fluorochemical alternative performance thresholds warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market