
 Latin America Video Surveillance Market | 2026-2036
Latin America Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Video Surveillance Market Insights
Buyer concentration across Latin American retail chains is recalibrating procurement patterns for enterprise-grade surveillance systems. Hangzhou Hikvision Digital Technology Company Limited leverages its manufacturing scale to occupy the mid-market channel across Brazilian and Mexican distributors. Zhejiang Dahua Technology Co., Ltd anchors its regional position through localized technical support centers in São Paulo and Mexico City. Motorola Solutions Inc. differentiates by integrating command-center software with its installed radio communications base across public safety agencies.
Video surveillance encompasses the capture, transmission, storage, and analysis of visual data through camera sensors operating across visible, infrared, or thermal spectra, typically encoded via H.265 or AI-enhanced compression protocols for bandwidth efficiency. The primary commercial purpose centers on real-time threat detection, forensic evidence collection, and operational intelligence for asset protection. Cameras and software together command the dominant margin pool as edge-computing capabilities shift analytics processing from centralized servers to device-level inference. IP and Cloud-Based technology segments attract accelerated deployment capital as telecommunications infrastructure modernizes across urban centers, while Analog systems sustain residual demand in cost-constrained rural municipalities and legacy industrial installations.
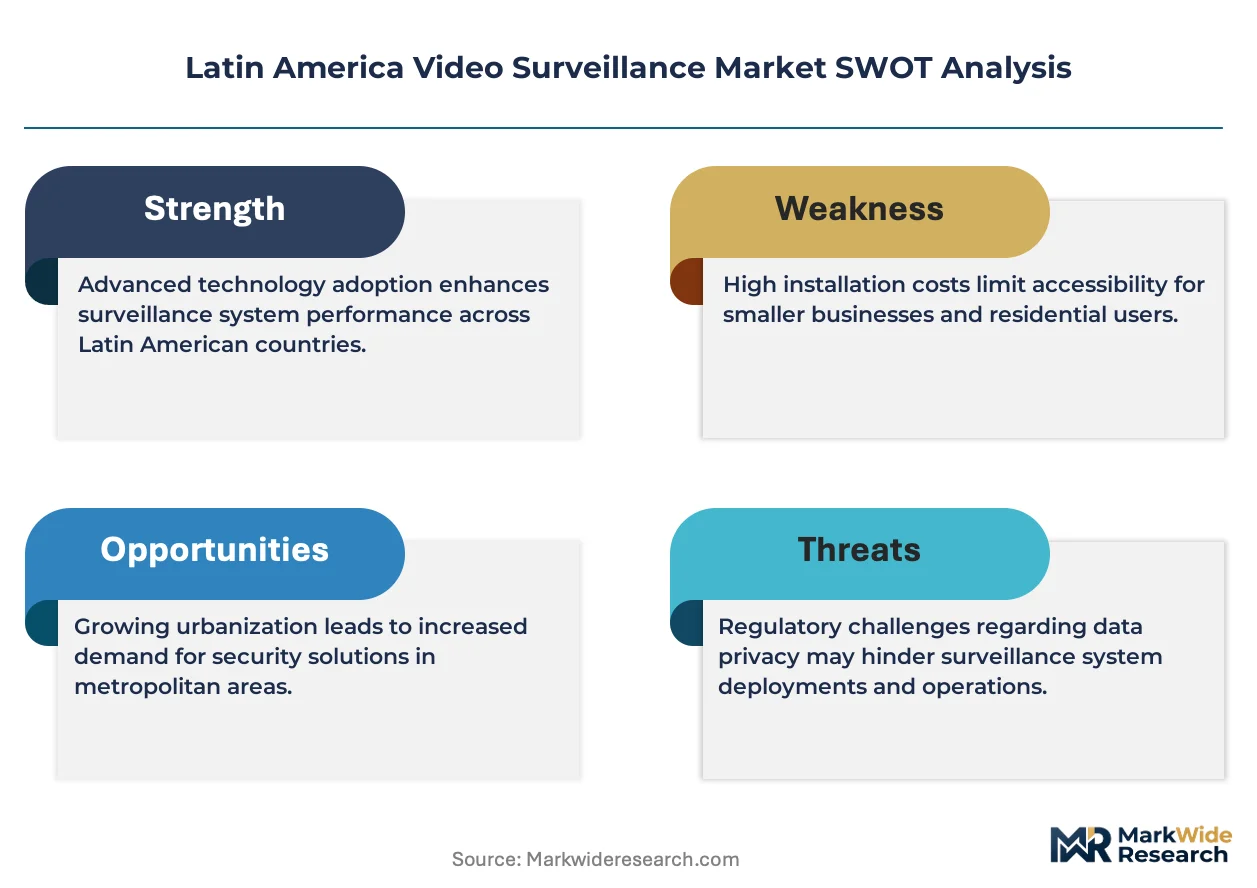
Brazil's ANATEL enforces electromagnetic compatibility and cybersecurity standards for networked surveillance hardware, effectively filtering non-compliant imports from regional distribution channels. Mexico's IFT coordinates spectrum allocation for wireless video transmission while federal security programs mandate encrypted storage protocols for government-procured systems. Argentina's CNC and Chile's SUBTEL impose analogous certification barriers that shape product roadmaps for vendors serving the Southern Cone. Stakeholders must monitor evolving data-localization requirements and cross-border cloud-access restrictions as policymakers balance security imperatives against privacy frameworks.
Market Dynamics
Edge-computing migration is compressing analytics processing from centralized servers to camera-level inference, forcing distributors to recalibrate inventory toward IP-compliant hardware as ANATEL certification requirements harden.
Growth Catalysts
- Smart city infrastructure mandates:Brazilian municipalities are expanding camera deployments for traffic management and public safety operations, creating sustained procurement pipelines for network-connected systems.
- ANATEL electromagnetic compatibility standards:Certification requirements for network-connected security devices are pushing local distributors toward IP-compliant inventory and filtering non-compliant imports.
- Northern Mexico industrial corridor concentration:Manufacturing campuses and logistics hubs require integrated perimeter monitoring systems, concentrating demand for enterprise-grade surveillance.
Market Restraints
- Semiconductor input cost volatility:Image sensor and processor pricing fluctuations compress margins for mid-market hardware vendors serving cost-constrained rural municipalities.
- Supply concentration in East Asian component sources:Dependence on specialized optics and encoding chip suppliers creates vulnerability to logistics disruptions and tariff exposure.
- Legacy analog infrastructure lock-in:Residual installed base of coaxial-cable systems in legacy industrial installations slows upgrade cycles and fragments procurement budgets.
Strategic Opportunities
- Argentina and Chile regulatory harmonization:CNC and SUBTEL certification barriers are creating first-mover advantages for vendors with pre-certified product roadmaps in the Southern Cone.
- AI-enhanced compression protocol convergence:H.265 and edge-analytics integration is opening bandwidth-efficient deployment in telecommunications-constrained secondary cities.
- Cloud-storage service bundling:Subscription-based remote monitoring models are penetrating retail chains previously served by capital-intensive on-premise installations.
Industry Challenges
- Cross-functional cybersecurity skill scarcity:Shortage of technicians capable of configuring encrypted storage protocols and network segmentation is delaying deployment timelines for federal security programs.
- Multi-jurisdiction certification complexity:Divergent data-localization requirements and cross-border cloud-access restrictions across Brazilian, Mexican, and Southern Cone regulators are lengthening product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Video Surveillance Market |
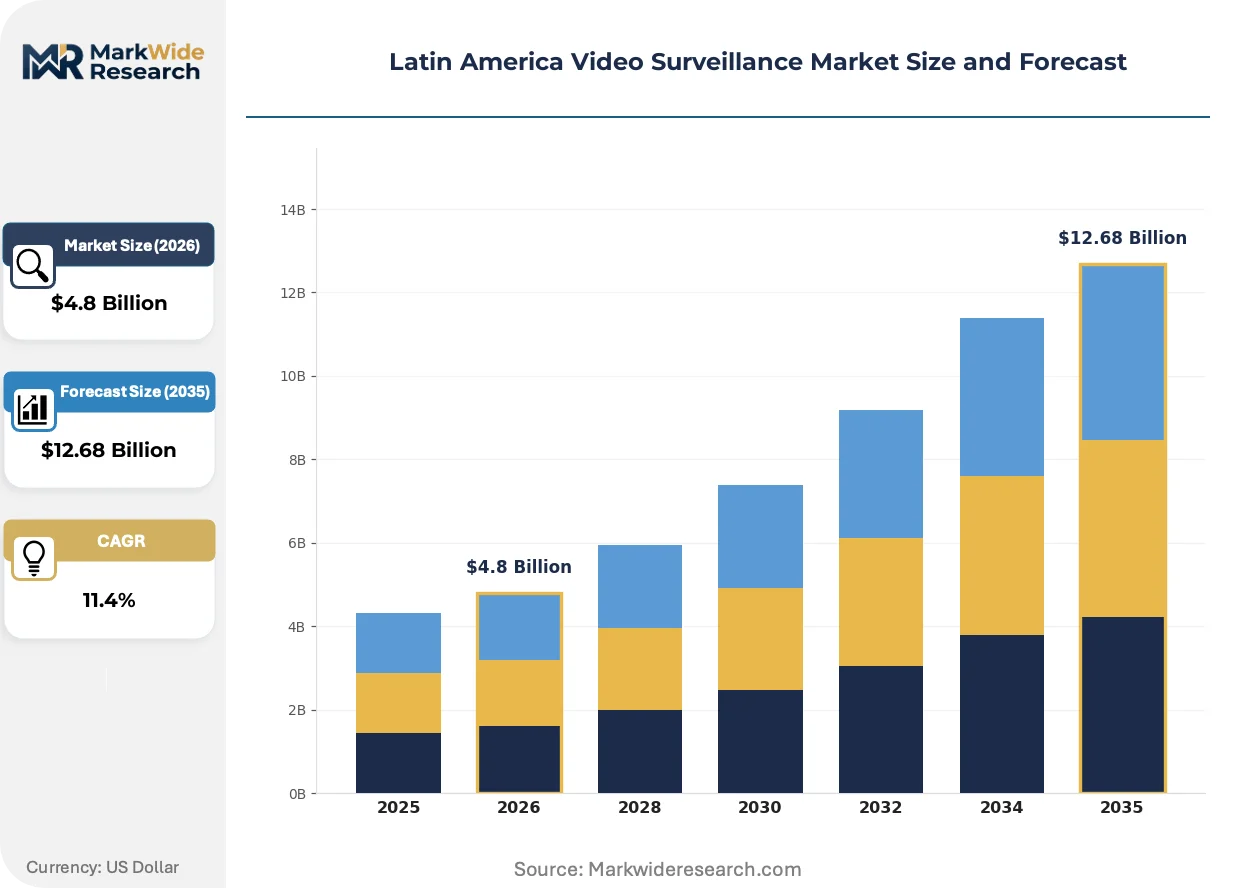
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Recorders, Monitors, Software Application: Infrastructure, Retail, Transportation, Banking Technology: Analog, IP, Wireless, Cloud-Based End User: Government, Commercial, Residential, Industrial |
| Companies Covered | Honeywell Security Group, Hangzhou Hikvision Digital Technology Company Limited, Eagle Eye Networks, Teledyne FLIR LLC, BOSCH Security Systems, Zhejiang Dahua Technology Co., Ltd, Verkada Inc, Motorola Solutions Inc., The Infinova Group, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Video Surveillance Market Trends and Innovations
Video surveillance architecture is migrating from reactive recording to predictive inference, with hardware vendors and software providers racing to capture margin pools at the network edge.
Edge-AI chipsets are integrating neural inference engines directly into camera enclosures, enabling real-time object classification without server dependency. Large retail chains and transportation authorities in São Paulo and Mexico City are piloting these units for queue management and crowd-density monitoring. The technology is integrating forensic and operational intelligence into unified workflows, compressing the traditional separation between security and business analytics functions.
IFT spectrum coordination for wireless video transmission is mandating encrypted storage protocols across government-procured systems in Mexico, with analogous frameworks emerging under Brazil's federal security programs. Hardware vendors must now engineer dual-certification compliance for electromagnetic compatibility and data protection. Public safety agencies represent the most affected segment, with procurement specifications increasingly specifying end-to-end encryption as a non-negotiable requirement.
Buyer concentration among Latin American retail chains is consolidating vendor relationships toward integrated solution providers capable of delivering hardware, software, and managed services through single contracts. Traditional distributor networks serving smaller municipal and commercial accounts face disintermediation pressure from manufacturer-direct enterprise sales teams. Brazil's southeastern manufacturing belt exhibits the most visible compression of channel layers, with multinational logistics operators bypassing regional distributors for direct OEM negotiations.
Latin America Video Surveillance Market Segmentation
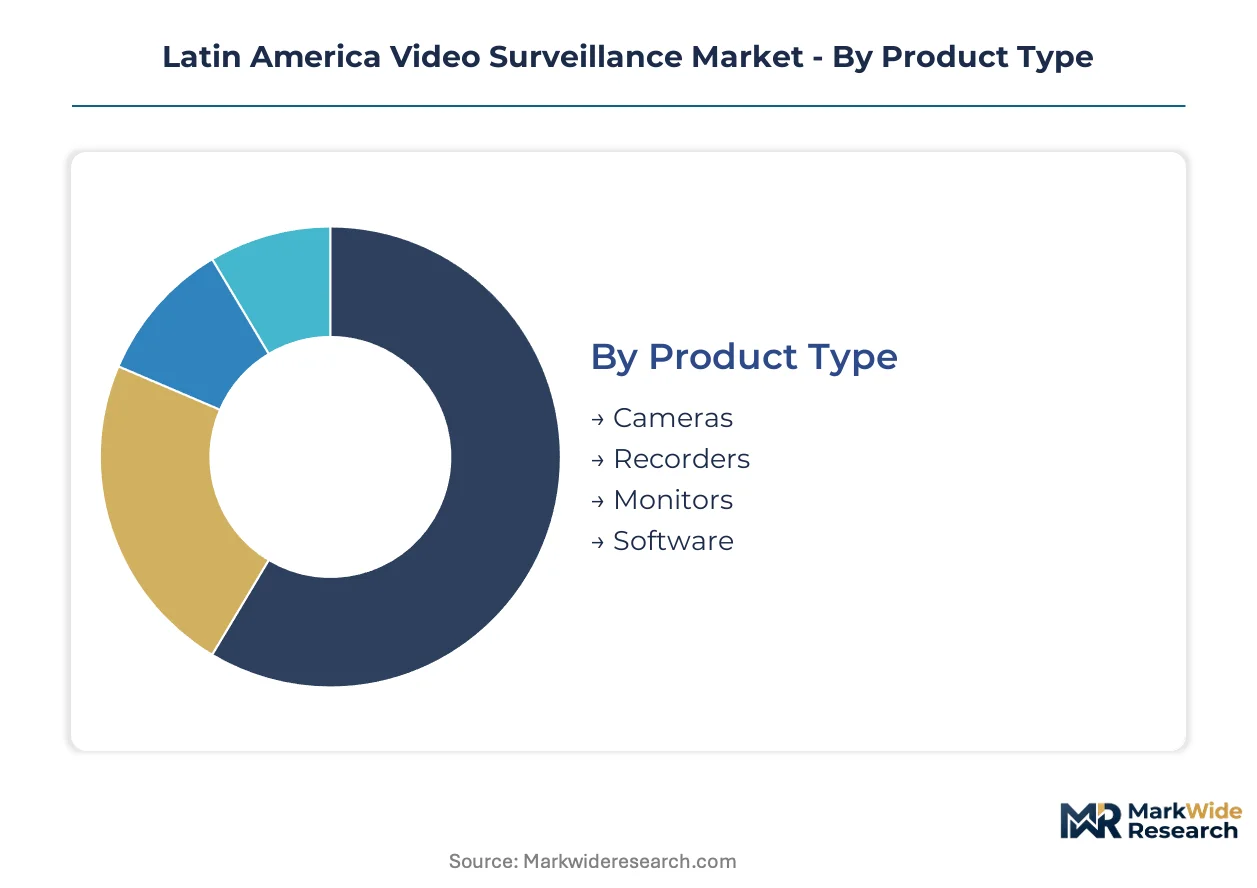
Segmentation in Latin American video surveillance reveals distinct procurement patterns across product tiers and deployment contexts. Technology migration paths and regulatory certification requirements create divergent growth trajectories within each category.
Product Type:
Standalone hardware dominates upfront capital expenditure, while embedded software components capture recurring service margins across installation lifecycles.
- Cameras:Image sensors operating across visible, infrared, and thermal spectra form the physical capture layer. Brazilian smart city initiatives and Mexican manufacturing corridors are concentrating procurement for network-connected units with edge-computing inference capabilities.
- Software:Video management systems and AI analytics platforms enable predictive threat detection and operational intelligence. Cloud-storage service bundling is penetrating Latin American retail chains previously locked into capital-intensive on-premise installations.
- Recorders:Network video recorders and digital video recorders handle compressed H.265 encoding for bandwidth efficiency.
- Monitors:Display units for control room visualization and field technician configuration.
Cameras lead volumes today; Software is gaining share fastest.
Application:
Cost tier differentiation separates federally funded security infrastructure from commercially financed retail and logistics deployments.
- Infrastructure:Traffic management systems, public safety networks, and municipal surveillance grids require encrypted storage protocols and electromagnetic compatibility certification. ANATEL standards in Brazil and IFT spectrum coordination in Mexico are shaping procurement specifications for government-procured systems.
- Retail:Large Latin American retail chains are consolidating vendor relationships toward integrated solution providers capable of delivering hardware, software, and managed services through single contracts.
- Transportation:Queue management and crowd-density monitoring for airports, ports, and mass transit authorities.
- Banking:Perimeter monitoring and facial recognition for branch security and ATM surveillance.
Infrastructure commands the largest project scale; Retail shows the steepest expansion trajectory.
Technology:
Customer type stratification separates enterprise-grade IP deployments from cost-constrained analog retention in rural municipalities.
- IP:Network-connected cameras and recorders transmit encoded visual data over Ethernet infrastructure. ANATEL certification requirements are filtering non-compliant imports and pushing Brazilian distributors toward IP-compliant inventory.
- Cloud-Based:Remote storage and analytics processing eliminate on-premise server requirements. Subscription-based monitoring models are penetrating secondary cities across the Southern Cone where telecommunications infrastructure is modernizing.
- Analog:Coaxial-cable systems sustain residual demand in legacy industrial installations and cost-constrained rural municipalities.
- Wireless:Spectrum-dependent transmission for locations lacking wired infrastructure.
IP leads volumes today; Cloud-Based is climbing the fastest.
End User:
Maturity divergence separates government security programs with mandated encryption standards from commercial buyers optimizing total cost of ownership.
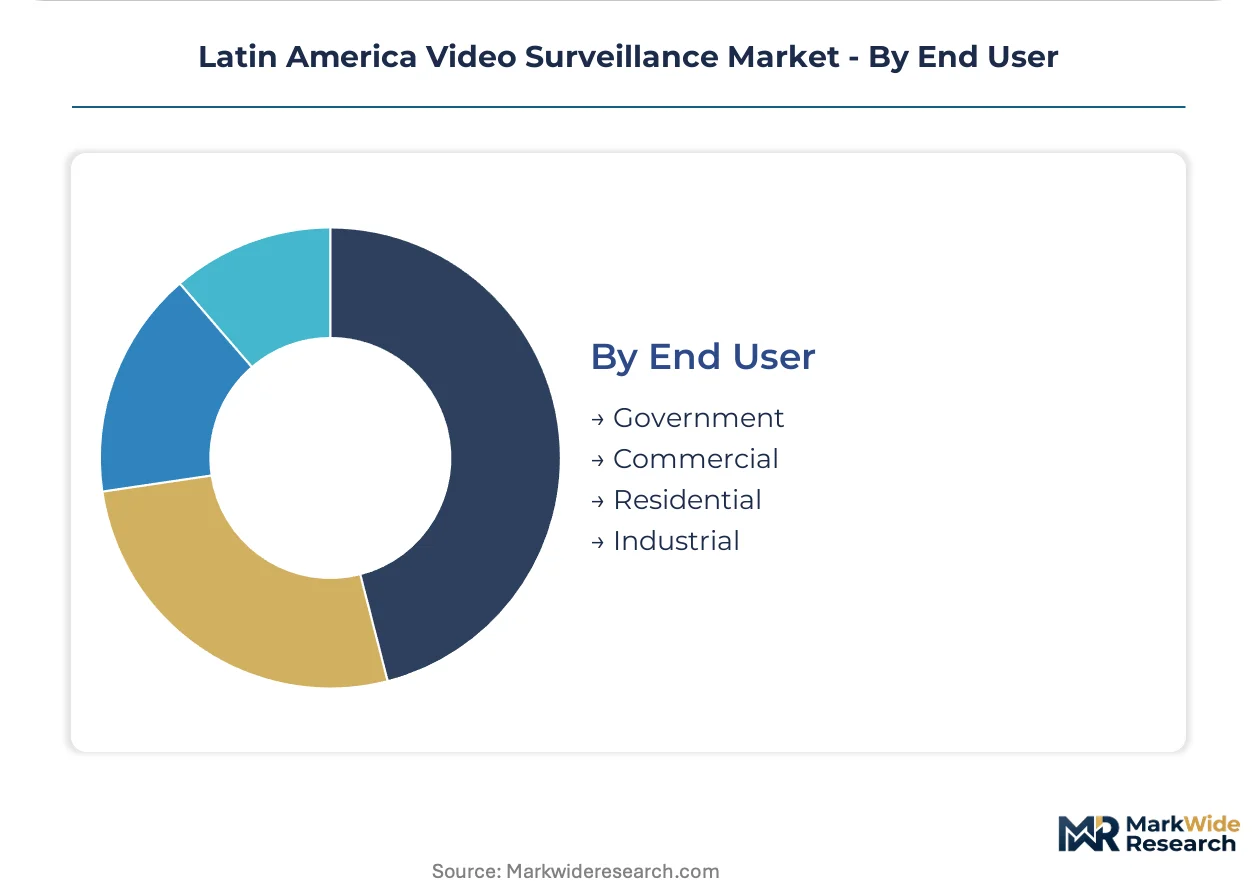
- Government:Public safety agencies and federal security programs specify end-to-end encryption and data-localization compliance. Cross-functional cybersecurity skill scarcity is delaying deployment timelines for encrypted storage protocol configuration.
- Commercial:Retail chains, logistics operators, and service sector businesses prioritize integrated perimeter monitoring with operational analytics. Buyer concentration is consolidating vendor relationships toward single-contract solution providers.
- Industrial:Manufacturing campuses and logistics hubs in Mexico's northern corridor require enterprise-grade surveillance systems.
- Residential:Single-family and multi-unit dwellings with cost-sensitive procurement patterns.
Government leads volumes today; Commercial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in São Paulo, Mexico City, and Santiago anchor Latin America's video surveillance deployment capacity, with technical certification programs expanding across Brazilian and Mexican distributor networks.
Brazil
Smart city infrastructure mandates in São Paulo and Rio de Janeiro are accelerating camera deployments for traffic management and crowd-density monitoring. ANATEL enforces electromagnetic compatibility and cybersecurity standards that filter non-compliant imports from regional distribution channels. The southeastern manufacturing belt exhibits channel compression as multinational logistics operators bypass regional distributors for direct OEM negotiations.
Mexico
Manufacturing campuses and logistics hubs in Nuevo León and the northern border states require integrated perimeter monitoring systems with encrypted storage protocols. IFT coordinates spectrum allocation for wireless video transmission while federal security programs mandate encryption for government-procured systems. Mexico City transportation authorities are piloting edge-AI chipsets for queue management and real-time crowd analytics.
Argentina
Federal security programs in Buenos Aires and Córdoba are specifying end-to-end encryption for public safety network upgrades. CNC certification barriers are creating first-mover advantages for vendors with pre-certified product roadmaps. The Pampas agricultural corridor sustains residual analog demand in cost-constrained rural municipalities with legacy coaxial infrastructure.
Chile
SUBTEL imposes certification requirements that shape vendor product roadmaps for the Southern Cone market. Santiago's retail banking sector is consolidating vendor relationships toward integrated solution providers capable of delivering hardware, software, and managed services through single contracts. The Valparaíso port complex requires enterprise-grade surveillance for cargo monitoring and perimeter security operations.
Colombia
Bogotá's public transit authorities are deploying network-connected systems with edge-computing inference capabilities for passenger safety monitoring. National telecommunications modernization is opening bandwidth-efficient deployment pathways in secondary cities previously constrained by infrastructure limitations. Medellín's urban innovation programs are integrating video analytics with existing smart city sensor networks for predictive threat detection.
Latin America Video Surveillance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's video surveillance market, with procurement patterns consolidating toward integrated solution providers capable of single-contract delivery. The vendor base stratifies across three tiers: multinational security conglomerates with command-center software integration, Chinese manufacturers leveraging scale advantages in mid-market hardware, and regional distributors adapting to ANATEL and IFT certification requirements. Dominant competitive moves include backward integration into edge-AI chipset design and geographic expansion through localized technical support centers in São Paulo and Mexico City.
Among scale-driven manufacturers, Hangzhou Hikvision Digital Technology Company Limited and Zhejiang Dahua Technology Co., Ltd occupy positions exemplifying mid-market channel penetration through Brazilian and Mexican distributor networks. Motorola Solutions Inc. represents the integrated systems archetype, anchoring its regional presence through command-center software compatibility with public safety radio communications infrastructure. These three entities collectively illustrate the competitive tension between hardware scale advantages and software integration capabilities reshaping procurement specifications across Latin American government and commercial accounts.
| Leading Market Players |
|---|
| Honeywell Security Group |
| Hangzhou Hikvision Digital Technology Company Limited |
| Eagle Eye Networks |
| Teledyne FLIR LLC |
| BOSCH Security Systems |
| Zhejiang Dahua Technology Co., Ltd |
| Verkada Inc |
| Motorola Solutions Inc. |
| The Infinova Group |
| Others |
Pricing and Supply Chain Analysis
Edge-AI chipset integration into camera enclosures is compressing server dependency costs while concentrating premium-tier margins among vendors with in-house silicon design capabilities. This technology shift simultaneously elevates hardware bill-of-materials for mid-market distributors and fragments procurement budgets across Brazilian municipalities facing ANATEL compliance deadlines.
Pricing Analysis
Bundled hardware-software-service contracts command premium positioning against transactional equipment sales in Latin American enterprise accounts. Three-tier pricing structure across certified-premium, standard-IP, and economy-analog levels separates government security programs from cost-constrained rural installations. Price differentiation hinges on ANATEL electromagnetic compatibility certification and encrypted storage protocol compliance. Pricing pressure stems from semiconductor input cost volatility compressing margins for mid-market hardware vendors. Commercial retail chains exhibit highest price sensitivity; federal security agencies demonstrate lowest sensitivity due to mandated encryption requirements.
Supply Chain Analysis
Image sensor supply rests on Taiwanese and South Korean foundry capacity, with specialized optics sourcing concentrated in Chinese and Japanese component houses. H.265 encoding processors and edge-inference chipsets draw from East Asian semiconductor fabricators. Supply chain risk centers on single-source vulnerability for AI-accelerated silicon and tariff exposure on Chinese-manufactured hardware. Distribution runs through São Paulo and Mexico City technical support centers, with Brazilian distributors adapting inventory toward IP-compliant SKUs under ANATEL filtering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in software-analytics bundling and cloud-storage subscription models, as edge-computing migration reduces server infrastructure costs for enterprise deployments.
For Market Incumbents: Extend backward integration into edge-AI chipset design to capture silicon margin pools and reduce dependency on East Asian processor suppliers. Fortify São Paulo and Mexico City technical support centers against emerging pure-play software entrants. Deepen certification investment for CNC and SUBTEL pre-approval to defend Southern Cone positioning against first-mover challengers.
For New Entrants and Emerging Players: ANATEL electromagnetic compatibility standards in Brazil open a window for certified-IP hardware specialists to displace non-compliant legacy distributors. Target Mexico's northern industrial corridor manufacturing campuses with integrated perimeter monitoring solutions. Pursue cloud-storage service bundling as the primary go-to-market angle for retail chain accounts consolidating toward single-contract providers.
For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with ANATEL and IFT certification capabilities because regulatory barriers create captive customer relationships and limit new entrant supply. Long-term viability favors platforms with software recurring revenue attachment to hardware installation bases. Acquisition target archetype: Brazilian distributors with municipal government relationships and pending IP-compliance inventory transitions. Monitor encrypted storage protocol mandate acceleration as the inflection signal for premium-tier vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chipset Integration | In-house neural inference engine design captures silicon margins from East Asian suppliers. |
| ANATEL Certification Investment | Pre-approved hardware SKUs unlock Brazilian municipal procurement pipelines. |
| Cloud-Storage Service Bundling | Subscription models displace capital-intensive on-premise installations in retail chains. |
| Technical Support Center Expansion | São Paulo and Mexico City localization anchors enterprise solution delivery. |
| CNC/SUBTEL Pre-Certification | Southern Cone regulatory alignment creates first-mover advantages in Argentina and Chile. |
Research Methodology
Coverage spans Brazil, Mexico, Argentina, Chile, and Colombia, with primary inputs from each market's distributor networks and end-user procurement committees. The analysis combines structured interviews with security systems integrators, municipal IT directors, retail loss prevention managers, and federal security program officers with secondary validation from ANATEL certification databases, IFT spectrum allocation filings, customs import records, and vendor technical documentation. Bottom-up installation volume estimates triangulate against top-down market sizing from equipment trade flows.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including technology tier, application vertical, end-user type, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, smart city infrastructure mandate timelines, and telecommunications modernization trajectories. Forecast inputs incorporate edge-AI chipset adoption curves and cloud-storage penetration rates in secondary cities.
Revisions become necessary when semiconductor supply disruptions, tariff regime shifts, or data-localization policy changes materialize across the modeled geographies. Forecasts reflect documented assumptions regarding certification timeline adherence and infrastructure investment continuity. A small set of named triggers warrants ongoing watch: ANATEL enforcement intensity, IFT encryption mandate expansion, and East Asian logistics corridor stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
India Surveillance IP Cameras Market