
 Canada Surveillance Storage Market | 2026-2036
Canada Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Surveillance Storage Market Insights
Multi-source procurement for surveillance storage hardware is recalibrating how Canadian security integrators balance cost against supply chain resilience. Seagate Technology leverages its vertically integrated disk manufacturing to anchor long-term contracts with federal correctional facilities. Western Digital competes through specialized surveillance-optimized drive portfolios designed for 24/7 write-intensive workloads. Quantum Corporation differentiates via tape-based cold storage solutions that address multi-decade retention mandates at substantially lower total cost of ownership.
Canada surveillance storage encompasses digital infrastructure purpose-built to capture, retain, and retrieve video evidence from security camera networks, typically requiring sustained write throughput of 500+ MBps per stream and operational reliability across temperature extremes from -30°C to 60°C. The primary commercial purpose centers on enabling real-time incident response while preserving legally admissible chain-of-custody records for criminal and civil proceedings. Cloud Storage deployment models are capturing accelerated adoption as hybrid architectures allow edge buffering with centralized elastic capacity for seasonal event spikes. HDD storage medium categories continue dominating unit volume despite SSD encroachment in high-frame-rate analytics applications where random read performance proves critical.
Health Canada collaborates with provincial privacy commissioners to enforce PIPEDA-aligned data sovereignty requirements that restrict cross-border video archive hosting without explicit consent protocols. The Communications Security Establishment publishes baseline cyber standards that shape encryption and access control procurement specifications for federal surveillance programs. Stakeholders must monitor evolving provincial cloud certification regimes to determine whether domestic data center investments or foreign provider partnerships deliver superior compliance economics.
Market Dynamics
Canadian municipal police departments are scaling body-worn camera deployments that demand petabyte-scale archival infrastructure, while provincial privacy statutes under the Privacy Act mandate encrypted, audit-ready storage architectures that reshape procurement specifications.
Growth Catalysts
- Smart City Transit Mandates:Ontario's Greater Toronto Area transit authorities are deploying enterprise-grade surveillance networks across critical infrastructure corridors. These deployments require sustained write throughput exceeding 500 MBps per video stream.
- Federal Correctional Video Archiving:Correctional Service Canada specifications for multi-decade retention of facility surveillance footage create recurring demand for cold storage solutions with chain-of-custody compliance.
- Hybrid Cloud Architectures:Edge buffering with centralized elastic capacity allows agencies to manage seasonal event spikes without overprovisioning on-premises infrastructure year-round.
Market Restraints
- Data Sovereignty Compliance Costs:Health Canada and provincial privacy commissioners enforce PIPEDA-aligned restrictions on cross-border video archive hosting, forcing domestic data center investments or complex consent protocols.
- Temperature-Grade Hardware Premiums:Operational reliability requirements across -30°C to 60°C temperature extremes necessitate industrial-grade storage components with substantially higher unit costs than standard enterprise equipment.
- Tape-to-Disk Migration Friction:Federal agencies with decades of legacy tape archives face technical and legal complexity migrating historical surveillance records to modern searchable formats without breaking chain-of-custody documentation.
Strategic Opportunities
- Quebec Provincial Cloud Certification:Evolving provincial certification regimes for cloud service providers create first-mover advantages for storage vendors establishing domestic data center partnerships before mandatory compliance deadlines.
- AI-Assisted Video Analytics Convergence:Machine learning-based incident detection systems require high-frame-rate storage with random read performance that SSD-optimized architectures can capture from traditional HDD-dominated deployments.
- First Nations Policing Infrastructure:Underpenetrated Indigenous police services across northern territories represent whitespace for modular, containerized surveillance storage solutions designed for remote deployment and limited technical staffing.
Industry Challenges
- Chain-of-Custody Documentation Talent:Forensic storage specialists capable of maintaining legally admissible audit trails across hybrid cloud and on-premises environments command premium compensation and remain scarce outside major metropolitan areas.
- Multi-Jurisdictional Compliance Integration:Vendors must simultaneously satisfy Communications Security Establishment cyber standards for federal programs and divergent provincial privacy statutes, fragmenting product roadmaps and certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Surveillance Storage Market |
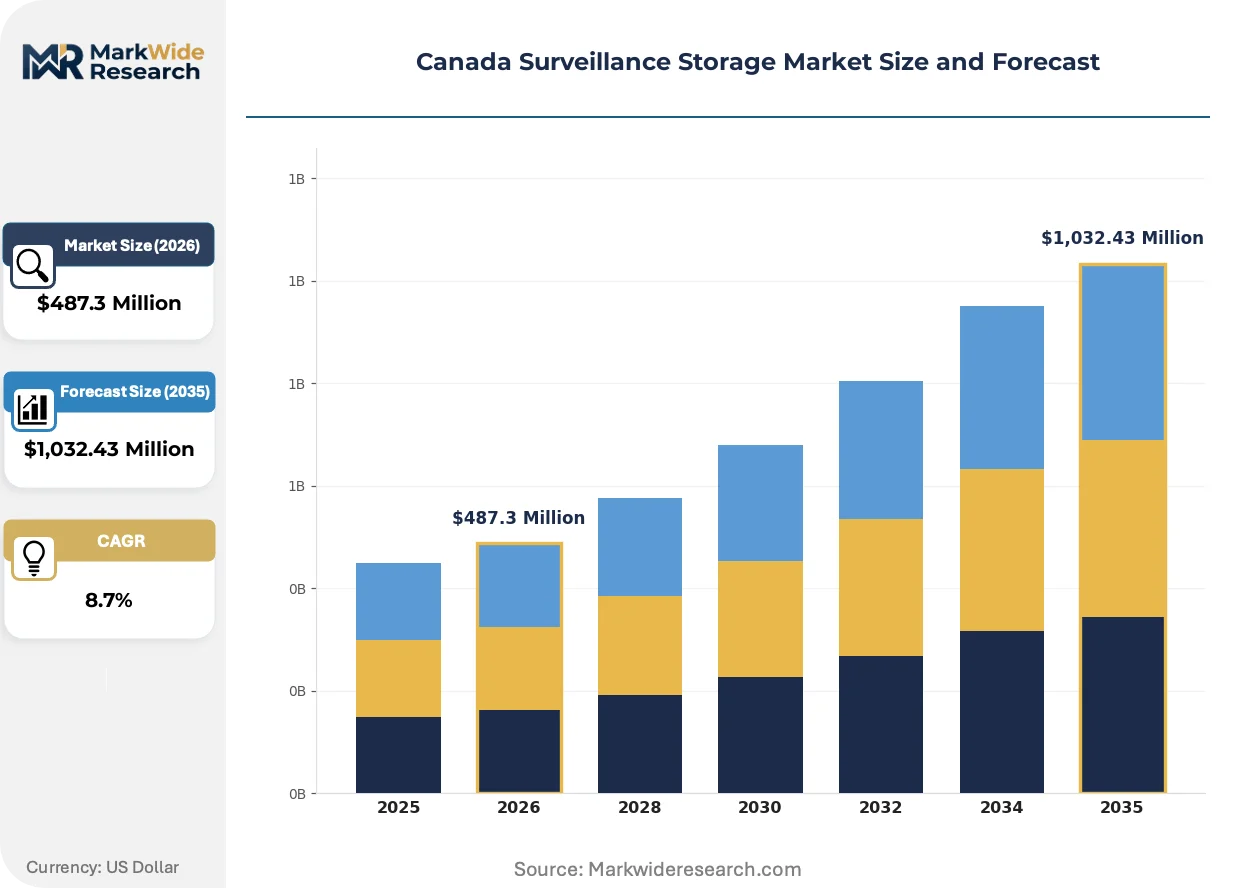
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NVR, DVR, Video Management Systems, Cloud Storage Deployment Model: On-premises, Cloud-based, Hybrid, Remote End User: Residential, Retail, Transportation, Healthcare Storage Medium: HDD, SSD, NAS, SAN |
| Companies Covered | Quantum Corporation, Hewlett Packard Enterprise, Seagate Technology, Genetec, IBM, Western Digital, Dell Technologies, Sync.com, Inc, NetApp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Surveillance Storage Market Trends and Innovations
Surveillance storage architectures are pivoting from passive archival systems toward active evidence management platforms that integrate real-time analytics, automated retention policies, and cross-agency federation capabilities.
Object storage software is expanding into Canadian law enforcement evidence management workflows. RCMP detachments and large municipal forces in Vancouver and Calgary are adopting software-defined storage platforms that unify body-worn camera, vehicle, and fixed-surveillance feeds into searchable repositories. This expansion is compressing procurement cycles as agencies abandon siloed, vendor-specific systems in favor of open-API architectures that prevent future lock-in.
The Privacy Act and provincial privacy statutes are tightening audit trail requirements for video evidence access and deletion. Storage vendors must now embed immutable logging and cryptographic verification into firmware layers rather than relying on application-level compliance. Federal surveillance programs and Ontario smart city deployments are responding by specifying FIPS 140-2 validated encryption modules as mandatory procurement criteria.
Subscription-based capacity provisioning is displacing capital-intensive storage procurement in mid-sized police departments. British Columbia and Alberta municipalities with 50-200 officer forces are adopting managed storage services that bundle hardware, software, and compliance documentation into per-camera monthly fees. This shift concentrates vendor selection authority with provincial procurement consortiums rather than individual agency IT departments.
Canada Surveillance Storage Market Segmentation
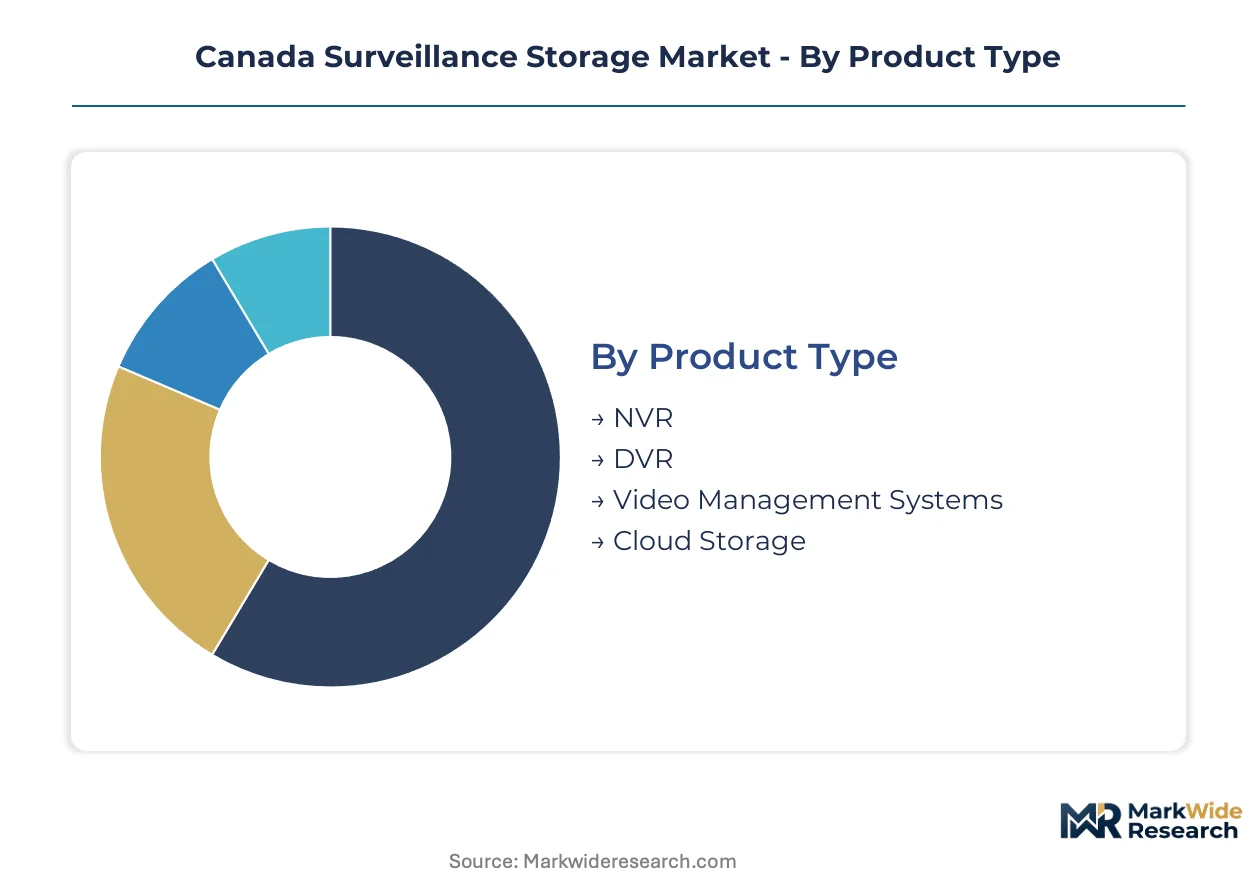
Segmentation in Canadian surveillance storage reveals how procurement specifications diverge across enforcement, transit, and commercial verticals. Each dimension carries distinct compliance burdens and performance thresholds that reshape vendor positioning.
Product Type:
Customization intensity varies sharply from plug-and-play appliances to enterprise software platforms requiring extensive systems integration.
- NVR:Network video recorders integrate embedded analytics and direct IP camera connectivity for mid-scale deployments. Ontario municipal police departments specify NVRs for station-level evidence buffering before cloud archival upload.
- DVR:Digital video recorders persist in legacy analog-to-digital conversion scenarios where coaxial infrastructure replacement remains capital-constrained. Federal correctional facilities maintain DVR fleets for compatibility with existing camera investments.
- Video Management Systems:Enterprise software platforms federate multi-site surveillance into unified command interfaces. Vancouver and Calgary RCMP detachments drive demand for open-API architectures that prevent vendor lock-in.
- Cloud Storage:Elastic capacity provisioning displaces capital-intensive on-premises procurement in mid-sized forces. British Columbia and Alberta municipalities with 50-200 officer complements adopt per-camera subscription models.
Leading the category by volume: NVR. Growing fastest: Cloud Storage.
Deployment Model:
Cost tier stratification separates budget-constrained remote installations from federally funded enterprise architectures with redundant resilience.
- On-premises:Dedicated hardware within agency-controlled facilities satisfies PIPEDA-aligned data sovereignty mandates. Health Canada and provincial privacy commissioners restrict cross-border hosting without explicit consent protocols.
- Cloud-based:Centralized elastic capacity manages seasonal event spikes without year-round overprovisioning. Quebec's evolving provincial cloud certification regimes create first-mover advantages for vendors establishing domestic data center partnerships.
- Hybrid:Edge buffering with centralized archival balances real-time responsiveness against long-term retention economics. Greater Toronto Area transit authorities deploy hybrid architectures across critical infrastructure corridors.
- Remote:Containerized modular systems address underpenetrated First Nations policing infrastructure across northern territories with limited technical staffing.
Commanding highest margins: Hybrid. Expanding most quickly: Cloud-based.
End User:
Application maturity spans from commoditized residential monitoring to emerging healthcare compliance with distinct chain-of-custody requirements.
- Residential:Consumer-grade cloud cameras with basic motion detection and smartphone alerts. Volume concentrates in urban centers with higher property crime rates.
- Retail:Loss prevention systems with POS integration and facial recognition analytics. Demand clusters in Ontario and British Columbia metropolitan commercial districts.
- Transportation:Smart city transit mandates in the Greater Toronto Area require sustained write throughput exceeding 500 MBps per video stream. Provincial infrastructure investments drive enterprise-grade procurement.
- Healthcare:Patient privacy compliance under provincial health information statutes creates emerging demand for encrypted, audit-ready archival with strict access logging.
Generating largest revenue pool: Transportation. Gaining share fastest: Healthcare.
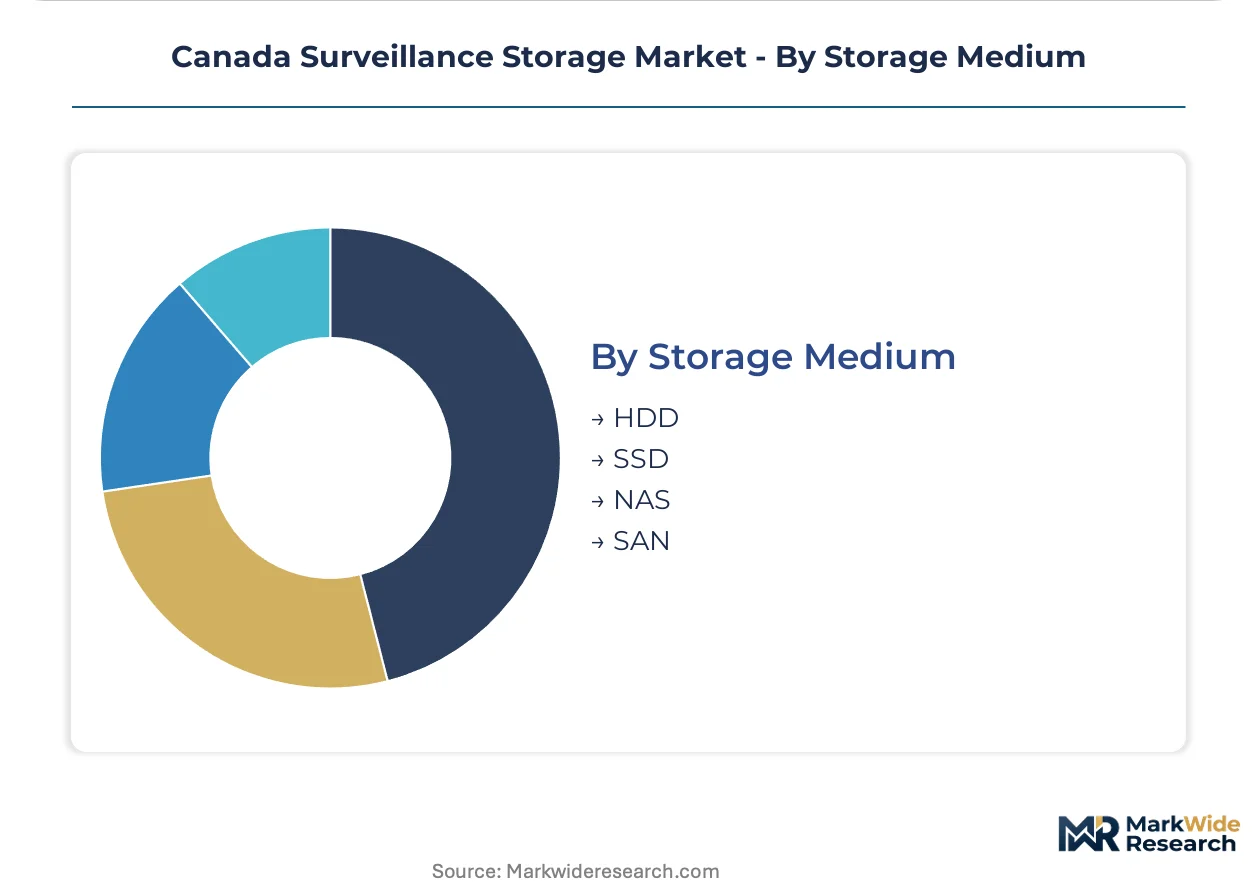
Storage Medium:
Technology maturity curves separate established rotating media from solid-state encroachment in performance-critical analytics workloads.
- HDD:Surveillance-optimized drives designed for 24/7 write-intensive workloads dominate unit volume. Western Digital competes through specialized portfolios addressing multi-petabyte archival scale.
- SSD:Solid-state storage captures high-frame-rate analytics applications where random read performance proves critical. Machine learning-based incident detection systems in advanced municipal deployments specify SSD tiers.
- NAS:Network-attached storage consolidates multi-camera feeds for mid-sized agency evidence management. Software-defined platforms unify body-worn camera, vehicle, and fixed-surveillance repositories.
- SAN:Storage area networks serve federal programs with multi-decade retention mandates requiring cold storage tiering and chain-of-custody compliance documentation.
Highest shipment volumes: HDD. Steepest expansion trajectory: SSD.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication facilities in Ontario anchor Canadian surveillance storage hardware supply chains. Provincial data sovereignty mandates concentrate demand within domestic cloud infrastructure zones.
Ontario
Greater Toronto Area transit authorities deploy enterprise-grade surveillance networks requiring sustained write throughput exceeding 500 MBps per stream. Health Canada collaborates with provincial privacy commissioners to enforce PIPEDA-aligned data sovereignty requirements. Smart city infrastructure investments in Toronto and Ottawa drive petabyte-scale storage procurement for critical corridor monitoring.
Quebec
Montreal municipal police departments expand body-worn camera programs demanding encrypted, audit-ready archival architectures. Evolving provincial cloud certification regimes create compliance deadlines for domestic data center partnerships. Video management system deployments concentrate in Montreal's public transit and correctional facility networks.
British Columbia
Vancouver RCMP detachments adopt software-defined storage platforms federating multi-site surveillance into unified command interfaces. Provincial privacy statutes mandate strict data retention controls for cross-agency evidence sharing. Mid-sized municipalities with 50-200 officer complements shift toward per-camera subscription storage models.
Alberta
Calgary law enforcement agencies specify open-API architectures preventing vendor lock-in across evidence management workflows. The Communications Security Establishment publishes baseline cyber standards shaping federal surveillance program encryption specifications. Energy sector critical infrastructure operators in Edmonton deploy industrial-grade storage components rated for temperature extremes.
Atlantic Canada
Federal correctional facilities in New Brunswick and Nova Scotia maintain multi-decade retention mandates for facility surveillance footage. Correctional Service Canada specifications create recurring demand for cold storage solutions with chain-of-custody compliance. Underpenetrated First Nations policing infrastructure across northern territories represents whitespace for modular, containerized deployment systems.
Canada Surveillance Storage Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors establish domestic data center alliances before mandatory provincial compliance deadlines. The vendor base stratifies across three tiers: vertically integrated disk manufacturers, specialized surveillance-optimized drive portfolios, and tape-based cold storage specialists. Two strategic archetypes anchor competitive positioning: hardware-centric manufacturers leveraging captive production assets, and software-defined platform providers enabling hybrid cloud federation. Portfolio diversification and geographic expansion through domestic partnership structures represent the dominant competitive vectors.
Within the hardware-centric tier, Seagate Technology and Western Digital exemplify vertically integrated manufacturing archetypes, while Quantum Corporation occupies a specialized position in tape-based archival systems. These three companies anchor the competitive structure through distinct technical approaches to petabyte-scale retention mandates. Seagate leverages disk manufacturing integration for federal correctional facility contracts. Western Digital competes through surveillance-optimized drive portfolios. Quantum differentiates via substantially lower total cost of ownership for multi-decade cold storage requirements.
| Leading Market Players |
|---|
| Quantum Corporation |
| Hewlett Packard Enterprise |
| Seagate Technology |
| Genetec |
| IBM |
| Western Digital |
| Dell Technologies |
| Sync.com, Inc |
| NetApp |
| Others |
Pricing and Supply Chain Analysis
Federal correctional facility procurement programs concentrate buyer power through multi-year storage infrastructure contracts, anchoring a subscription-dominant pricing model that bundles hardware refresh cycles with compliance documentation services. This procurement structure compresses margins for vendors lacking domestic data center partnerships while rewarding integrated service providers with recurring revenue visibility.
Pricing Analysis
Warranty and service bundling separates enterprise-grade surveillance storage offerings from commodity hardware transactions, with federal agencies mandating multi-year on-site support and chain-of-custody audit documentation as non-negotiable inclusions. Three-tier pricing structure across premium, standard, and economy levels stratifies by encryption certification grade and temperature-grade component specifications, with industrial-rated hardware commanding substantial premiums over standard enterprise equipment. Cost compression in mid-sized municipal deployments is intensifying because provincial procurement consortiums are consolidating vendor selection authority and standardizing per-camera subscription terms. First Nations policing infrastructure represents the most price-sensitive segment due to limited capital allocation and remote deployment logistics, while federal correctional programs exhibit lowest sensitivity given multi-decade retention mandates and compliance-driven procurement.
Supply Chain Analysis
Silicon wafer and precision magnetic component supply rests on Taiwanese semiconductor foundries, Japanese specialty materials producers, and Chinese rare earth processing facilities for high-performance storage media substrates. Canadian surveillance storage manufacturing draws from Thailand and Malaysia for disk drive assembly operations, with firmware development concentrated in California and Israel. Single-source vulnerability in FIPS 140-2 validated encryption module supply creates procurement bottlenecks for federal surveillance programs requiring certified components. Distribution runs through security integrator channels that combine hardware procurement with systems integration and compliance certification services for end-user agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada surveillance storage market is becoming a vertical-integration race as vendors pursue captive control over encryption module validation and domestic data center infrastructure to satisfy provincial cloud certification mandates.
For Market Incumbents: Anchor market position through backward integration into FIPS-validated encryption firmware development and exclusive domestic data center partnerships in Quebec and Ontario before mandatory provincial compliance deadlines crystallize. Deepen relationships with Correctional Service Canada through multi-decade cold storage service contracts that embed quantum-safe archival migration pathways. Seagate Technology and Western Digital must defend against tape-based cost advantages by emphasizing searchable format accessibility and reduced chain-of-custody documentation friction. For New Entrants and Emerging Players: First Nations policing services across northern territories represent the most penetrable whitespace, with modular containerized storage solutions addressing limited technical staffing and extreme temperature operational requirements. Quebec's evolving provincial cloud certification regimes create entry opportunity for software-defined platform providers establishing domestic data center alliances before mandatory deadlines. Target mid-sized British Columbia and Alberta municipalities with per-camera subscription models that bundle hardware, software, and compliance documentation into predictable operational expenditures. For Investors and Strategic Acquirers: The window for entry favors software-defined storage platform providers with established open-API architectures and hybrid cloud federation capabilities. Long-term viability across the projection horizon depends on capturing provincial procurement consortium relationships and encryption certification expertise that federal agencies mandate. Watch for Communications Security Establishment baseline cyber standard revisions as the primary inflection indicator for encryption module procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Partnership | Quebec provincial cloud certification deadlines favor vendors with established Canadian infrastructure zones. |
| Encryption Module Validation | FIPS 140-2 certification becomes mandatory procurement criterion for federal surveillance programs. |
| Software-Defined Platform Launch | Open-API architectures prevent vendor lock-in and compress procurement cycles for RCMP detachments. |
| Containerized Remote Deployment | Modular systems address First Nations policing infrastructure gaps across temperature-extreme northern territories. |
| Managed Storage Service Expansion | Per-camera subscription models capture mid-sized municipal forces shifting from capital-intensive procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across surveillance storage procurement managers at federal correctional facilities, provincial privacy commissioner offices, municipal police IT directors, security integrator technical leads, and cloud service provider compliance officers. Health Canada enforcement guidelines, Communications Security Establishment cyber standards documentation, PIPEDA regulatory interpretations, and provincial cloud certification regime filings provided foundational regulatory context. Bottom-up demand modeling from individual agency procurement disclosures triangulated against top-down market sizing from hardware shipment customs records and security integrator revenue disclosures.
Segmentation granularity modeled deployment models at the individual agency level, storage medium categories at the petabyte-scale archival tier, and end-user verticals distinguishing federal correctional mandates from municipal policing and smart city transit requirements. Product type differentiation captured NVR, DVR, video management system, and cloud storage provisioning splits. CAGR derivation incorporated historical procurement cycle analysis, body-worn camera deployment scaling trajectories, and provincial infrastructure investment commitments across the analysis window. Forecast inputs included Correctional Service Canada multi-decade retention mandate specifications and Ontario Greater Toronto Area transit authority enterprise-grade surveillance network expansion plans.
Revisions become necessary when provincial privacy statute amendments, federal cyber standard updates, or domestic data center certification regime changes materialize. Forecasts reflect assumptions regarding continued PIPEDA-aligned data sovereignty enforcement and sustained municipal police body-worn camera program scaling. A small set of named triggers warrants ongoing watch: Quebec cloud certification deadline acceleration, Communications Security Establishment encryption module specification revisions, and First Nations policing infrastructure funding allocation shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
France Surveillance Camera Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market