
 Vortexers Market | 2026-2036
Vortexers Market Size, Share, and Industry Trends Forecast 2026-2036
Vortexers Market Outlook
Modular platform configurations with interchangeable tube racks and programmable speed profiles is repositioning buyer expectations away from single-purpose benchtop units. Thermo Fisher Scientific leverages its global service infrastructure to bundle vortexers with centrifuge and thermal cycler contracts. Eppendorf AG anchors its position through ergonomic industrial design and calibrated precision for pharmaceutical quality control departments. Benchmark Scientific competes on accessible price points for academic institutions with lighter throughput demands.
A vortexer is an electromechanical laboratory instrument that generates orbital shaking motion through a rubber-capped drive shaft to suspend, mix, or homogenize liquid samples in tubes, flasks, or microplates. Operating speeds typically span 200 to 3,200 rpm with orbit diameters of 3–7 mm, serving essential functions in cell lysis, reagent preparation, and bead-based extraction protocols across life sciences workflows. Multi-tube vortexers dominate installed base volumes due to parallel processing capacity in high-throughput pharmaceutical research environments. Mini vortexers represent the fastest-expanding configuration as point-of-use mixing proliferates in clinical diagnostics and decentralized testing sites. Analog vortexers retain residual demand in cost-constrained academic settings where digital programmability offers limited marginal utility.
FDA quality system regulations and EMA in-vitro diagnostic device standards shape validation documentation requirements for vortexers deployed in regulated pharmaceutical and clinical workflows. ISO 13485 medical device quality management frameworks extend compliance burdens to manufacturers supplying diagnostic instrument OEMs. REACH substance restrictions and RoHS electrical equipment directives in Europe constrain motor component and housing material selections for vendors accessing EU research laboratories. Stakeholders must monitor evolving sustainability disclosure rules under the EU Green Deal and CSRD as procurement departments embed lifecycle carbon metrics into capital equipment decisions.
Market Dynamics
Modular vortexer platforms with programmable speed profiles and interchangeable tube racks are compressing demand for single-purpose benchtop units, forcing vendors to bundle calibration services and extended warranties to defend margin positions.
Growth Catalysts
- EMA diagnostic reproducibility standards:Tightened validation protocols for mixing equipment in pharmaceutical quality control departments are mandating calibrated precision instruments with documented traceability.
- Decentralized clinical testing expansion:Point-of-care diagnostics in community health centers and mobile laboratories are proliferating mini vortexer deployments for rapid sample preparation.
- Bead-based extraction protocol standardization:Automated nucleic acid purification workflows in genomics research facilities require orbital shaking consistency across high-throughput plate formats.
Market Restraints
- Brushless DC motor supply concentration:Precision motor manufacturing clusters in East Asia create single-source vulnerability for vendors requiring sub-1% speed tolerance.
- ISO 13485 certification timeline friction:Medical device quality management documentation extends product launch cycles by 12-18 months for diagnostic instrument OEM partnerships.
- Magnetic stirrer substitution in aqueous applications:Low-viscosity reagent preparation workflows increasingly favor magnetic mixing for energy efficiency and reduced mechanical wear.
Strategic Opportunities
- India PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of laboratory equipment reduce import duty exposure for multinational vendors establishing local assembly.
- Cloud-connected instrument telemetry:Integration of usage analytics and predictive maintenance alerts into vortexer firmware creates recurring service revenue streams.
- Cell therapy manufacturing scale-up:GMP-grade vortexers for cell suspension and cryoprotectant mixing address emerging demand from contract development organizations.
Industry Challenges
- Electronics technician scarcity:Servicing variable-frequency drive circuits and Hall-effect sensors in field repair environments requires specialized training programs that vendor service networks struggle to staff.
- Legacy analog inventory rationalization:Academic procurement departments with fixed capital budgets resist digital upgrade cycles, forcing manufacturers to maintain dual product lines with incompatible component supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vortexers Market |
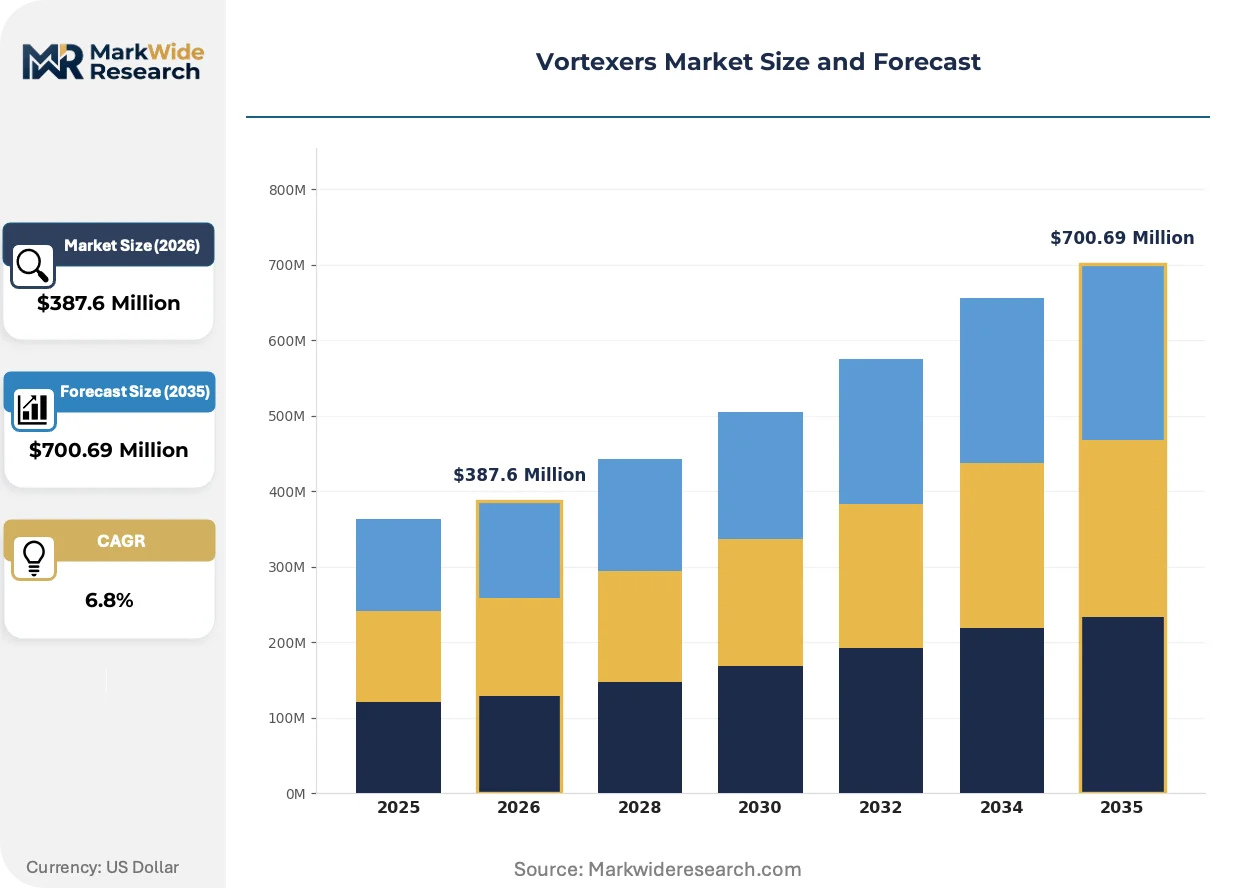
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Tube Vortexers, Mini Vortexers, High-Throughput Vortexers, Analog Vortexers Application: Biotechnology, Pharmaceutical Research, Clinical Diagnostics, Environmental Testing End User: Research Laboratories, Academic Institutions, Pharmaceutical Companies, Quality Control Departments Distribution Channel: Direct Sales, Online Retailers, Distributors, Specialty Stores |
| Companies Covered | Thermo Fisher Scientific, Eppendorf AG, IKA Works, Scientific Industries Inc., Bio-Rad Laboratories Inc., Benchmark Scientific, VWR International, Corning Incorporated, Heidolph Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vortexers Market Strategic Shifts
Programmable microprocessor control is displacing analog potentiometer interfaces across all price tiers, embedding calibration memory and multi-step protocol storage as baseline expectations rather than premium features.
Brushless DC motor technology is consolidating orbital shaking precision in mid-tier and premium vortexer segments. Pharmaceutical quality control departments in Germany and Switzerland are adopting these systems for validated dissolution testing workflows. The shift is compressing demand for brushed motor platforms and forcing incumbent vendors to redesign chassis architectures around integrated drive electronics.
EU CSRD sustainability disclosure requirements are reshaping procurement documentation for capital equipment in European research institutions. Vendors must now provide lifecycle carbon metrics and circularity assessments alongside technical specifications. Diagnostic instrument OEMs in France and the Netherlands are embedding these requirements into supplier qualification questionnaires, favoring manufacturers with EU-based assembly operations.
Instrument service contract unbundling is fragmenting traditional bundled sales models in North American academic markets. Core facility managers at research universities in Massachusetts and California are negotiating separate calibration and maintenance agreements, comparing third-party metrology providers against manufacturer service plans. This behavior is compressing attach rates for extended warranties and forcing vendors to compete on transparent hourly service pricing.
Vortexers Market Segmentation
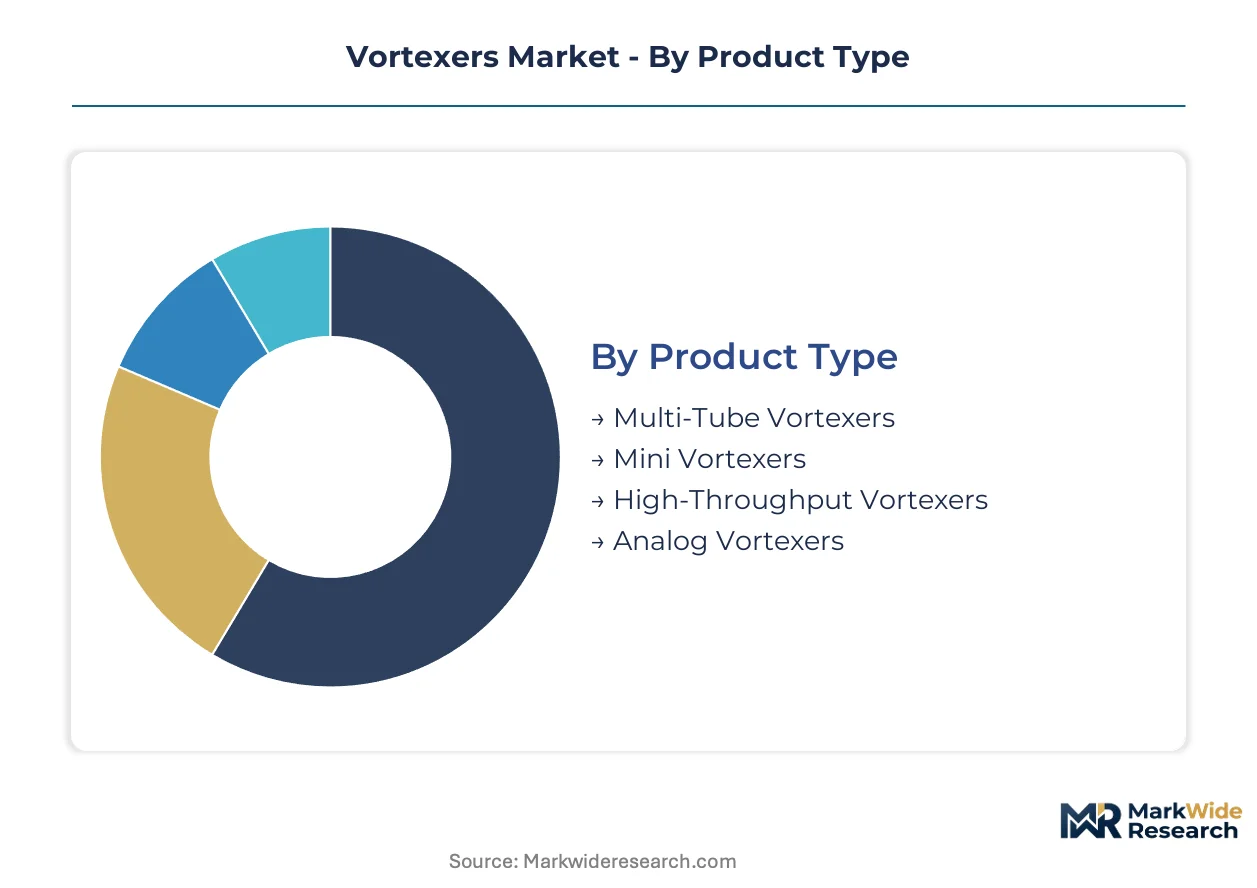
Vortexer procurement decisions split across technical specifications, workflow throughput, and compliance requirements. Buyers in regulated pharmaceutical environments prioritize validated precision, while academic purchasers weight capital efficiency against functional adequacy.
Product Type:
Orbital shaking mechanics and motor architecture define performance boundaries across laboratory workflows.
- Multi-Tube Vortexers:Parallel processing racks accommodate 24-96 tubes simultaneously with programmable speed ramping. Pharmaceutical quality control departments in Germany and Switzerland deploy these for dissolution testing workflows requiring documented traceability under EMA standards.
- Mini Vortexers:Compact single-tube units operate at 200-3,200 rpm with 4 mm orbit diameter. Point-of-care diagnostics in community health centers and mobile laboratories are expanding deployments for rapid sample preparation at decentralized testing sites.
- High-Throughput Vortexers:Microplate-compatible platforms process 384-well formats for automated nucleic acid purification protocols.
- Analog Vortexers:Potentiometer-controlled brushed motor units serve cost-constrained academic settings where digital programmability offers limited marginal utility.
Multi-Tube Vortexers lead on scale; Mini Vortexers lead on momentum.
Application:
End-use workflow characteristics determine precision requirements and validation burden intensity.
- Biotechnology:Cell lysis and reagent suspension protocols demand orbital consistency for reproducible protein extraction. Genomics research facilities in Massachusetts and California are standardizing bead-based extraction workflows requiring sub-1% speed tolerance.
- Pharmaceutical Research:GMP-grade mixing for cell therapy manufacturing and cryoprotectant suspension is emerging from contract development organizations scaling autologous cell production.
- Clinical Diagnostics:FDA-regulated workflows mandate calibrated instruments with ISO 13485 documentation for diagnostic instrument OEM partnerships.
- Environmental Testing:Soil and water sample homogenization for contaminant analysis employs robust sealed housing designs.
Pharmaceutical Research commands premium pricing; Clinical Diagnostics is gaining share fastest.
End User:
Capital allocation authority and compliance exposure shape purchasing behavior across institutional categories.
- Research Laboratories:Core facility managers negotiate unbundled service contracts comparing third-party metrology against manufacturer plans. Massachusetts and California research universities are fragmenting traditional bundled sales models.
- Pharmaceutical Companies:Quality control departments require brushless DC motor precision with calibration memory and multi-step protocol storage as baseline specifications.
- Academic Institutions:Fixed capital budgets resist digital upgrade cycles, forcing manufacturers to maintain dual analog-digital product lines.
- Quality Control Departments:Validated dissolution testing workflows in Germany anchor demand for programmable speed profiles with documented traceability.
Pharmaceutical Companies concentrate revenue; Research Laboratories show steepest contract restructuring.
Distribution Channel:
Procurement route selection reflects order scale, technical support requirements, and geographic market maturity.
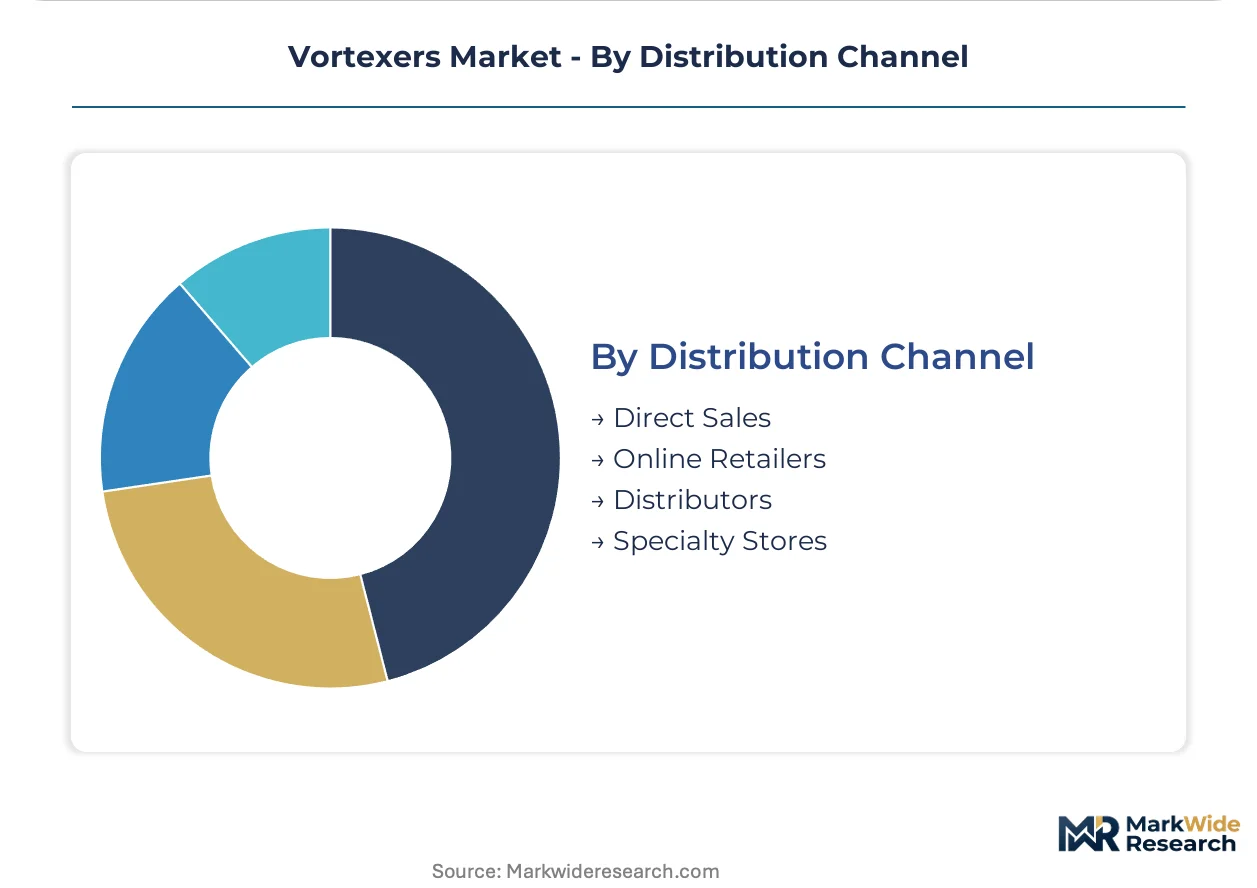
- Direct Sales:Multinational vendors leverage global service infrastructure to bundle vortexers with centrifuge and thermal cycler contracts for high-volume pharmaceutical accounts.
- Distributors:Regional inventory positioning reduces lead times for European research institutions requiring EU-based assembly operations under CSRD sustainability disclosure rules.
- Online Retailers:Academic purchasers with lighter throughput demands compare accessible price points across standard configurations.
- Specialty Stores:Local laboratory supply operations serve decentralized clinical testing sites with immediate availability requirements.
Direct Sales dominates contract value; Online Retailers show most rapid channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering traditions established vortexer manufacturing standards in the 1960s, with orbital shaking technology migrating to pharmaceutical quality control workflows across Western Europe before consolidating in North American biotechnology clusters.
Germany
Pharmaceutical quality control departments in Baden-Württemberg and North Rhine-Westphalia drive demand for calibrated precision instruments with documented traceability. EMA diagnostic reproducibility standards mandate validation protocols that favor brushless DC motor platforms with ISO 13485 certification. IKA Works in Staufen anchors a precision engineering cluster serving dissolution testing workflows across Swiss and German pharmaceutical facilities.
United States
Genomics research facilities in Massachusetts and California standardize bead-based extraction protocols requiring sub-1% speed tolerance for reproducible nucleic acid purification. FDA quality system regulations shape validation documentation requirements for diagnostic instrument OEM partnerships. Core facility managers at Boston and San Francisco research universities fragment traditional bundled sales models through unbundled service contract negotiations.
Switzerland
Contract development organizations scaling autologous cell production generate emerging demand for GMP-grade mixing equipment in cryoprotectant suspension workflows. Swissmedic medical device standards extend compliance burdens to manufacturers supplying diagnostic instrument partnerships. Basel and Zurich pharmaceutical manufacturing corridors concentrate procurement authority for validated dissolution testing systems.
India
Domestic laboratory equipment manufacturing expands under the PLI scheme production-linked incentives, reducing import duty exposure for multinational vendors establishing local assembly. CDSCO medical device regulations tighten quality management documentation requirements for diagnostic workflows. Maharashtra and Karnataka biotechnology corridors concentrate emerging demand from contract research organizations scaling sample preparation throughput.
China
NMPA medical device registration requirements extend product launch timelines for diagnostic instrument OEM partnerships seeking orbital shaking consistency. Dual carbon goals under national climate commitments reshape procurement documentation for capital equipment in research institutions. Yangtze River Delta pharmaceutical manufacturing clusters concentrate demand for high-throughput microplate-compatible platforms.
Vortexers Market Competitive Environment
The competitive structure tilts toward diversified laboratory equipment conglomerates with global service infrastructure. Tiered specialization separates precision calibration specialists from volume-oriented academic suppliers. Three archetypes dominate: precision engineering specialists with pharmaceutical validation expertise, diversified life science conglomerates bundling multi-instrument contracts, and accessible price-point competitors serving cost-constrained research institutions. M&A activity concentrates diagnostic instrument OEM partnerships, while geographic expansion targets India PLI scheme manufacturing incentives.
Among diversified life science conglomerates, Thermo Fisher Scientific leverages global service infrastructure to anchor multi-instrument contract positions. Eppendorf AG exemplifies precision engineering specialization through ergonomic industrial design and calibrated precision archetypes. Benchmark Scientific occupies the accessible price-point tier for academic institutions with lighter throughput demands. IKA Works represents German precision engineering heritage in orbital shaking technology development.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf AG |
| IKA Works |
| Scientific Industries Inc. |
| Bio-Rad Laboratories Inc. |
| Benchmark Scientific |
| VWR International |
| Corning Incorporated |
| Heidolph Instruments |
| Others |
Value Chain & Pricing Dynamics
Brushless DC motor engineering talent concentration in Baden-Württemberg and Shenzhen feeds labor-cost differentials that widen pricing-tier spreads between precision-calibrated pharmaceutical units and basic academic models. German technicians command premiums that inflate premium-tier instrument pricing, while Chinese assembly labor enables economy-tier cost structures for emerging market distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade brushless motor platforms from brushed-mid-tier units and analog academic models. Price differentiation hinges on ISO 13485 certification grade and after-sales calibration bundling. Cost compression in the economy tier is intensifying because Indian PLI scheme domestic manufacturing erodes import markup structures. Academic institutions in fixed-budget environments exhibit highest price sensitivity; pharmaceutical quality control departments in Germany and Switzerland demonstrate lowest sensitivity due to validation compliance requirements.
Supply Chain Analysis
Brushless DC motor production rests on precision manufacturing clusters in China, Japan, and Germany. Rare-earth magnet sourcing from Chinese processors, Hall-effect sensor fabrication in Japanese facilities, and precision bearing production in German engineering corridors constitute critical input dependencies. Single-source vulnerability concentrates in East Asian motor controller semiconductor supply. Distribution runs through direct sales for pharmaceutical accounts, regional distributors for European research institutions, and online retailers for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
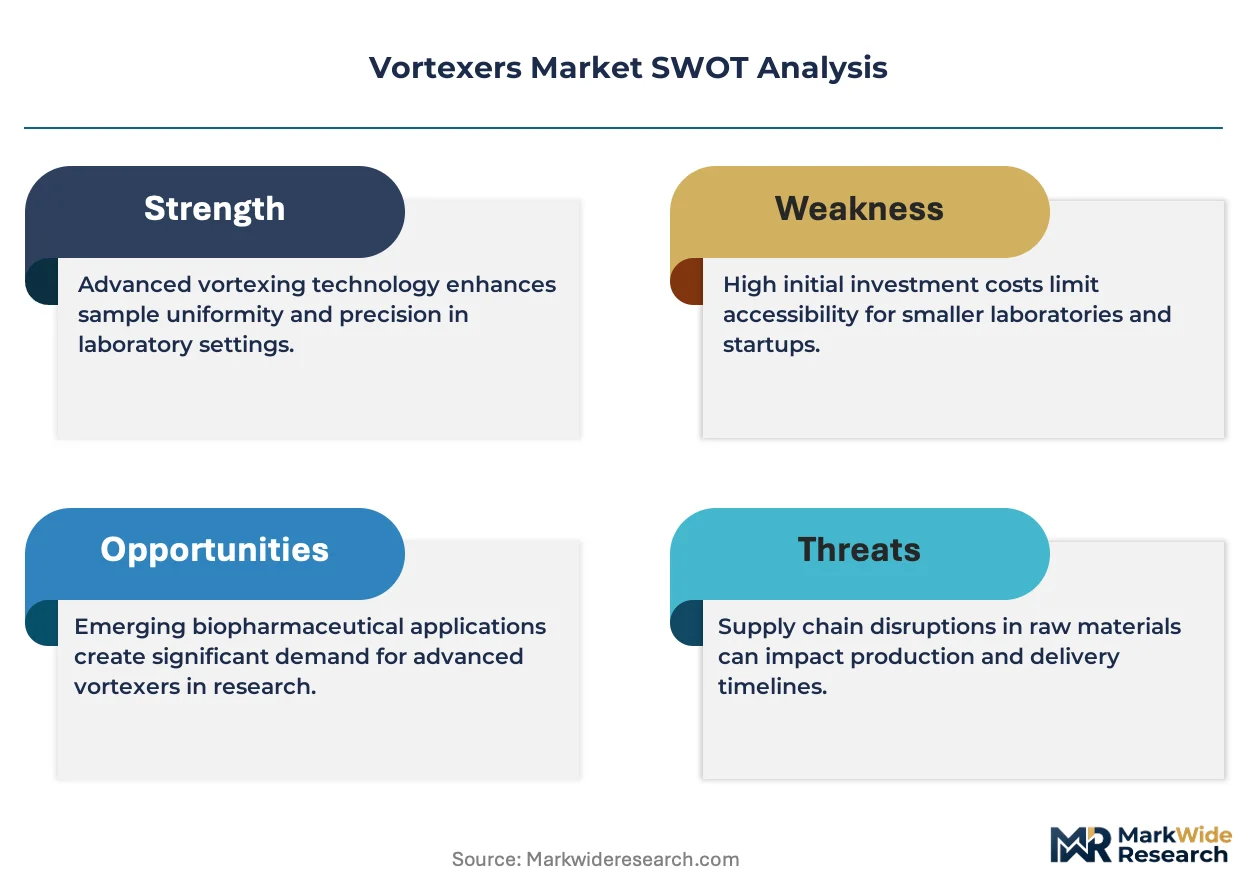
This market functions as a geographic-arbitrage play between German precision engineering premiums and Indian PLI scheme manufacturing cost advantages. CDSCO regulatory alignment costs in India run substantially below EMA validation burdens in Europe.
For Market Incumbents: To counter magnetic stirrer substitution in aqueous reagent preparation workflows, vendors should deepen backward integration into brushless DC motor production and anchor channel control through bundled centrifuge-thermal cycler service contracts. Calibration certification investment in ISO 13485 documentation defends pharmaceutical account retention against emerging Asian competitors. For New Entrants and Emerging Players: Capture contract research organization procurement in Maharashtra and Karnataka biotechnology corridors where throughput scaling demands outpace established vendor service reach. Underpenetrated mini vortexer deployments at Indian decentralized clinical testing sites offer the most penetrable entry vector. A go-to-market angle emphasizing CDSCO-compliant documentation with sub-European price positioning accelerates initial traction. For Investors and Strategic Acquirers: Diagnostic instrument OEMs are the most active acquirer in this space, seeking captive mixing module supply for automated nucleic acid purification platforms. Long-term viability over the next decade hinges on cloud-connected telemetry integration and GMP-grade cell therapy manufacturing positioning. Watch NMPA registration timeline acceleration in China as an inflection indicator for competitive manufacturing cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Backward Integration | Captive precision motor production insulates IKA Works and Eppendorf AG from East Asian supply disruption. |
| Cloud-Connected Telemetry Platform Launch | Predictive maintenance firmware creates recurring revenue streams for Thermo Fisher Scientific service contracts. |
| India PLI Scheme Manufacturing Footprint | Local assembly reduces import duty exposure and aligns with CDSCO quality documentation requirements. |
| GMP-Grade Cell Therapy Product Line Extension | Cryoprotectant mixing modules address emerging demand from Swiss contract development organizations. |
| Third-Party Metrology Partnership | Unbundled calibration agreements respond to Massachusetts and California university core facility procurement restructuring. |
Study Parameters
Multiple input streams — laboratory equipment procurement managers, pharmaceutical quality control directors, diagnostic instrument OEM engineers, and academic core facility administrators — were reconciled against FDA 510(k) filings, EMA medical device registration databases, CDSCO import records, and ISO 13485 certification registries. Bottom-up installation base estimates triangulated with top-down capital expenditure projections from research institution budget disclosures.
Historical shipment patterns cross-referenced against expert panel inputs on brushless DC motor adoption curves and EMA validation protocol evolution. Segmentation modeling incorporated product type, application workflow, end-user institution category, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from instrument replacement cycle analysis and genomics research facility expansion trajectories, with bead-based extraction protocol standardization treated as a demand elasticity input.
Brushless motor supply disruption, EMA diagnostic reproducibility standard revision, and PLI scheme incentive modification are the dominant revision risks. Forecasts embed assumptions on certification timeline stability and academic budget elasticity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Tanned Fish Skin Leather Market
Others
Operator Training Simulator Market
Others
Inflight Entertainment Solutions Market
Others
Pickup Truck Market
Others
Europe Postal Services Market
Others
Turkey Health and Medical Insurance Market
Others
Banknote Printing Machine Market
Others
Performance Testing Tools Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Traditional PC Market
Others
South Asia Geosynthetics Market
Others
North America Thermoformed Plastics Market
Others
Education and Learning Analytics Market
Others
Roasted Wheat Market
Others
France Location-Based Services Market
Others
Inorganic Tin Chemicals Market