
 Middle-East and Africa Syngas Market | 2026-2036
Middle-East and Africa Syngas Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Syngas Market Foresight
Specialized gasification engineering talent is rotating toward Middle Eastern energy corridors as project complexity rises. TechnipFMC anchors large-scale reactor deployment across Gulf states through its process licensing and EPC capabilities. Air Products and Chemicals extends its position via on-site syngas supply contracts tied to refinery and chemical park expansions. Linde competes through cryogenic separation and gas handling systems integrated with reforming units.
Syngas denotes a combustible mixture of hydrogen, carbon monoxide, and varying carbon dioxide content produced through partial oxidation or steam reforming of carbonaceous feedstocks, typically operating at temperatures exceeding 1,200°C and pressures from 20 to 70 bar for industrial gasification configurations. Its primary purpose centers on serving as an intermediate platform chemical for hydrogen generation, Fischer-Tropsch liquids, ammonia synthesis, and substitute natural gas production. Ammonia commands the dominant share of Middle Eastern offtake due to fertilizer export economics and existing Haber-Bosch infrastructure along the Gulf coast. Biomass feedstock adoption is accelerating in East Africa and South Africa where agricultural residue availability and carbon accounting requirements create structural incentives for alternative gasification routes.
Saudi Arabia's SFDA and the UAE's MOHAP enforce industrial emissions protocols that shape syngas plant permitting and carbon intensity benchmarks for chemical sector operators. South Africa's carbon tax administered by the National Treasury and Egypt's environmental impact assessment requirements administered by the Egyptian Environmental Affairs Agency further constrain coal-based gasification while favoring natural gas and renewable feedstock pathways. Stakeholders must monitor feedstock cost divergence between stranded natural gas assets and emerging biomass collection networks to align capital deployment with regulatory trajectory.
Market Dynamics
Fertilizer export economics along the Gulf coast are concentrating syngas demand in integrated ammonia-urea corridors, while South Africa's carbon tax framework redirects capital toward biomass gasification pilots and away from coal-based routes.
Growth Catalysts
- Jubail Industrial City concentration:SABIC and feedstock partners operate integrated gasification complexes serving petrochemical and power export markets, creating clustered demand pull.
- SFDA emissions protocols:Saudi Arabia's industrial emissions benchmarks shape syngas plant permitting and carbon intensity standards for chemical sector operators.
- Haber-Bosch infrastructure:Existing ammonia synthesis capacity along the Gulf coast locks in syngas offtake for fertilizer derivatives.
Market Restraints
- Biomass feedstock cost volatility:Agricultural residue collection networks in East Africa lack pricing transparency and seasonal supply consistency.
- Natural gas price divergence:Stranded gas asset economics in the Gulf states contrast with import-dependent pricing in Egypt and Morocco.
- Gasification reactor supply concentration:Specialized engineering talent and equipment fabrication capacity clusters in Western European and East Asian supplier bases.
Strategic Opportunities
- UAE renewable energy procurement rules:MOHAP-aligned sustainability mandates create structural incentives for blue and green hydrogen-derived syngas pathways.
- Ethiopian agricultural residue networks:Underdeveloped biomass collection infrastructure offers first-mover positioning for alternative gasification feedstock security.
- Fischer-Tropsch liquids integration:Convergence of syngas-to-liquids technology with existing refinery complexes enables synthetic fuel export positioning.
Industry Challenges
- High-temperature reactor engineering scarcity:Gasification specialists capable of 1,200°C+ partial oxidation system design command premium compensation and rotation premiums.
- Cryogenic separation integration complexity:Linde- and Air Products-class gas handling systems require precise thermal coupling with reforming units.
- Egyptian Environmental Affairs Agency permitting timelines:Environmental impact assessment procedures for coal-to-syngas projects extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Syngas Market |
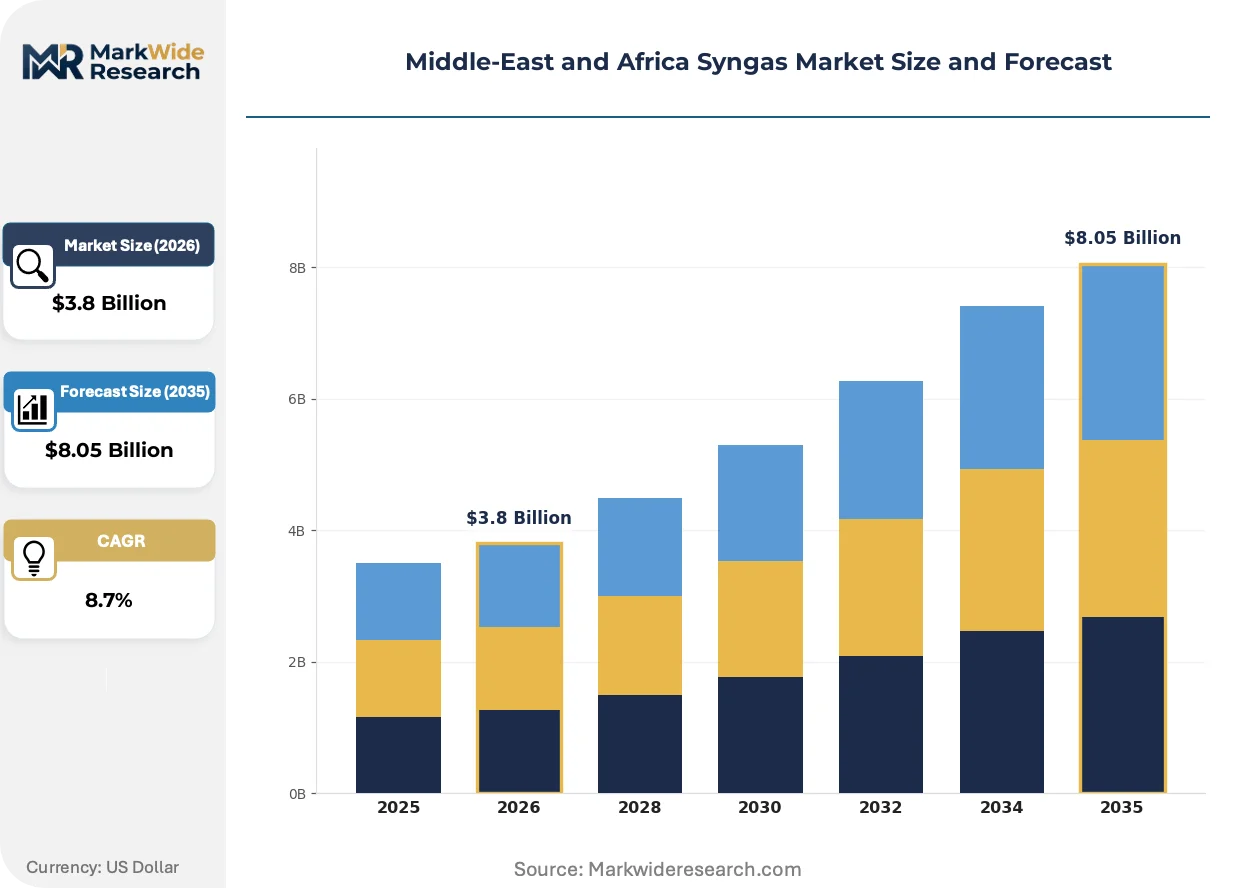
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methanol, Hydrogen, Ammonia, Synthetic Natural Gas Feedstock: Natural Gas, Coal, Biomass, Petroleum Coke Technology: Gasification, Reforming, Catalytic Conversion, Pyrolysis End User: Energy, Chemicals, Fertilizers, Power Generation |
| Companies Covered | TechnipFMC PLC, General Electric, Air Products and Chemicals Inc, Royal Dutch Shell plc, KBR Inc, BASF SE, Linde plc, Air Liquide, SABIC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Syngas Market Shifts & Advancements
Steam methane reforming configurations are yielding to alternative feedstock pathways as carbon accounting tightens across Middle Eastern chemical corridors and African carbon tax jurisdictions.
Entrained-flow biomass gasification is supplanting fixed-bed coal gasification in South African pilot deployments. Sasol and independent project developers are adopting 1,400°C slagging gasifiers for agricultural residue processing. This technology shift is compressing the capital efficiency gap between fossil and renewable syngas routes.
REACH-aligned carbon border adjustment mechanisms are reshaping export-oriented fertilizer economics. Gulf-based ammonia producers face embedded emissions scrutiny in European offtake contracts. South African operators are responding with biomass co-feeding certificates to preserve market access.
Long-term offtake contracting is displacing spot hydrogen sales in Jubail and Yanbu chemical parks. Refinery and petrochemical buyers are locking in fifteen-year syngas supply agreements with TechnipFMC-licensed reactor operators. This pattern concentrates most visibly in Saudi Arabia's integrated energy-to-chemicals complexes.
Middle-East and Africa Syngas Market Segmentation
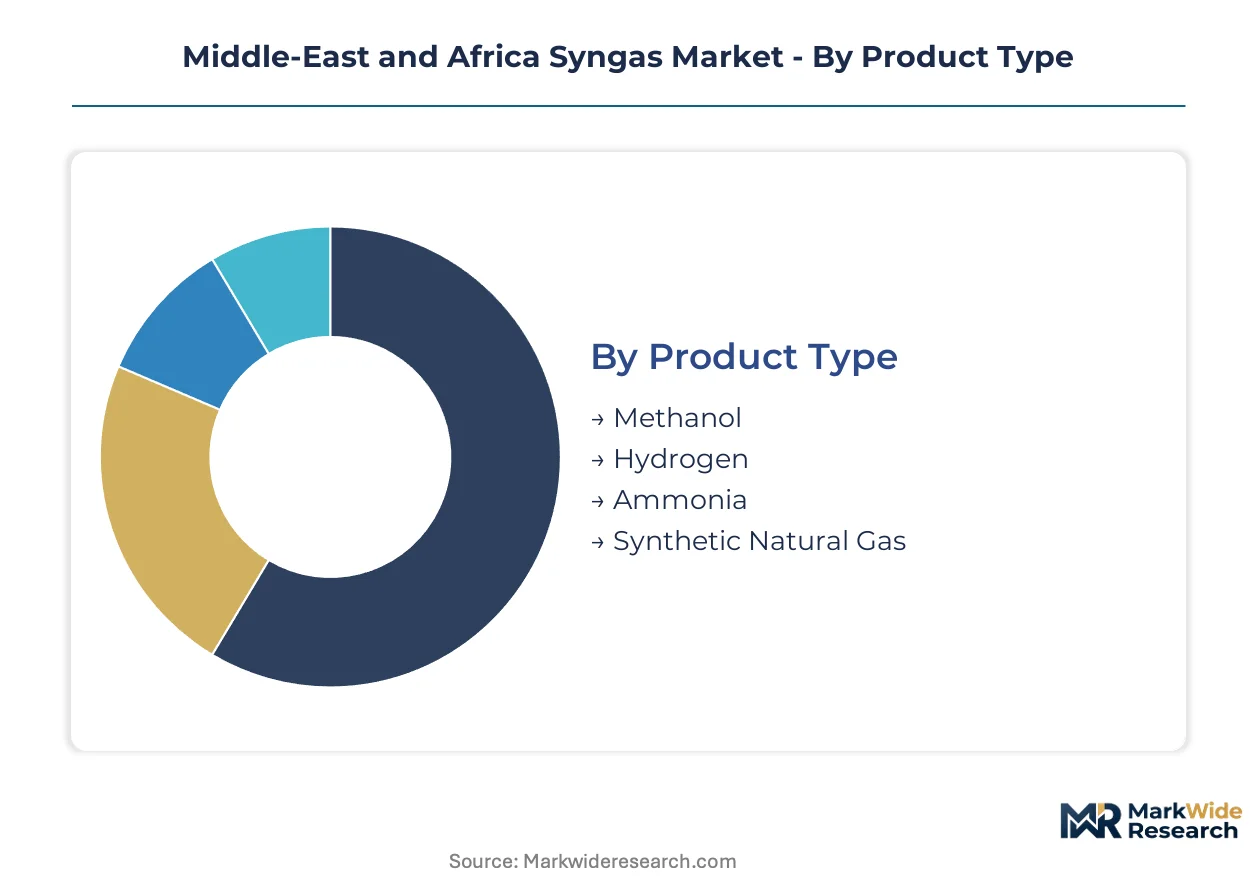
Syngas market segmentation reveals how feedstock economics, technology licensing costs, and end-use contracting structures concentrate margin capture across Middle Eastern and African corridors. Distinct value pools attach to ammonia synthesis versus Fischer-Tropsch liquids, to stranded gas assets versus biomass collection networks.
Product Type:
Margin pools concentrate in ammonia derivatives where Haber-Bosch infrastructure amortization and Gulf coast export economics create structural cost advantages over European and Asian producers.
- Ammonia:Dominates Middle Eastern offtake through urea and fertilizer derivative production. Jubail Industrial City complexes lock in syngas demand via integrated gasification corridors serving SABIC and feedstock partners for petrochemical and power export markets.
- Hydrogen:Emerging as a high-purity product stream for refinery desulfurization and emerging mobility applications. South Africa's carbon tax framework administered by the National Treasury redirects capital toward biomass-to-syngas pilot projects with hydrogen co-production.
- Methanol:Serves formaldehyde and acetic acid feedstock demand across Egyptian and Moroccan chemical parks.
- Synthetic Natural Gas:Substitute natural gas production targets pipeline injection specifications in UAE and Saudi distribution networks.
The dominant share belongs to Ammonia, while Hydrogen is closing the gap fastest.
Feedstock:
Cost tier stratification separates Gulf states with stranded natural gas assets from import-dependent North African markets and agricultural residue-rich East African corridors.
- Natural Gas:Steam methane reforming configurations yield the lowest carbon intensity syngas for ammonia synthesis. Saudi Arabia's SFDA emissions protocols shape plant permitting benchmarks that favor gas-based routes over coal alternatives.
- Biomass:Agricultural residue gasification is accelerating in South Africa and Ethiopia where carbon accounting requirements create structural incentives. Sasol and independent developers deploy 1,400°C slagging gasifiers for residue processing.
- Coal:South African operators face constraints from carbon tax exposure; Egyptian Environmental Affairs Agency permitting timelines extend development cycles for coal-to-syngas projects.
- Petroleum Coke:Refinery byproduct integration targets high-sulfur feedstock flexibility in integrated energy-to-chemicals complexes.
Natural Gas retains volume leadership, though Biomass is expanding most quickly in jurisdictions with carbon pricing mechanisms.
Technology:
Application requirements dictate technology selection—partial oxidation for heavy feedstocks, steam reforming for light hydrocarbons, with catalytic routes emerging for smaller-scale distributed production.
- Gasification:Partial oxidation systems operating above 1,200°C and 20-70 bar serve coal, petroleum coke, and biomass feedstocks. TechnipFMC anchors large-scale reactor deployment across Gulf states through process licensing and EPC capabilities.
- Reforming:Steam methane reforming yields hydrogen-rich syngas for ammonia and methanol synthesis. Linde competes through cryogenic separation and gas handling systems integrated with reforming units.
- Catalytic Conversion:Emerging for smaller-scale syngas production with lower capital intensity.
- Pyrolysis:Thermal decomposition routes target biomass and waste feedstocks in pilot deployments.
Gasification commands the installed base, while Reforming maintains lowest-cost position for natural gas corridors.
End User:
Customer type segmentation separates export-oriented commodity producers from domestic power and mobility applications, with contract duration and pricing mechanisms varying sharply across these poles.
- Fertilizers:Ammonia-urea derivatives dominate Gulf coast offtake through existing Haber-Bosch infrastructure. Fertilizer export economics concentrate syngas demand in integrated corridors serving European and Asian agricultural markets.
- Chemicals:Methanol-to-olefins and Fischer-Tropsch liquids integration targets synthetic fuel and petrochemical feedstock positioning. Refinery and petrochemical buyers in Jubail and Yanbu chemical parks lock in fifteen-year syngas supply agreements.
- Energy:Hydrogen and synthetic fuel applications are emerging under UAE renewable energy procurement rules aligned with MOHAP sustainability mandates.
- Power Generation:Integrated gasification combined cycle configurations serve industrial captive power and grid export markets.
Fertilizers hold the dominant share, though Chemicals is gaining share fastest through Fischer-Tropsch liquids integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Middle-East and Africa syngas corridor. Gulf states channel syngas predominantly into ammonia-urea export complexes, while South Africa and East African markets prioritize biomass-to-hydrogen pilots under carbon pricing regimes.
Saudi Arabia
Jubail Industrial City anchors the kingdom's syngas demand through SABIC-operated integrated gasification complexes. The Saudi Food and Drug Authority enforces industrial emissions protocols that shape plant permitting benchmarks and carbon intensity standards. These integrated corridors simultaneously serve petrochemical derivative production and power export markets.
United Arab Emirates
Refinery and chemical park expansions in Ruwais and Jebel Ali drive hydrogen-rich syngas offtake for desulfurization and synthetic fuel applications. The Ministry of Health and Prevention aligns sustainability mandates with renewable energy procurement rules, creating structural incentives for blue hydrogen pathways. Long-term supply contracting now displaces spot hydrogen sales across these integrated complexes.
South Africa
Sasol and independent developers deploy entrained-flow biomass gasification pilots for agricultural residue processing under carbon tax exposure. The National Treasury-administered carbon tax framework redirects capital away from coal-based routes toward renewable feedstock alternatives. High-temperature slagging gasifiers operating at 1,400°C are compressing the capital efficiency gap between fossil and biomass syngas production.
Egypt
Methanol-to-olefins demand in Alexandria and Suez Canal chemical parks sustains natural gas reforming capacity despite import-dependent pricing. The Egyptian Environmental Affairs Agency extends environmental impact assessment timelines for coal-to-syngas projects, effectively constraining that feedstock pathway. Stranded gas economics in the Gulf states contrast sharply with Egyptian import pricing, fragmenting regional feedstock cost structures.
Ethiopia
Agricultural residue availability in the Oromia and Amhara highlands creates structural incentives for alternative gasification feedstock security. Underdeveloped biomass collection networks offer first-mover positioning for developers establishing residue supply chains. Pilot projects targeting fertilizer and power applications are emerging where carbon accounting requirements meet feedstock cost advantages.
Middle-East and Africa Syngas Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle-East and Africa syngas market. Process licensors and industrial gas majors capture margin through technology deployment and long-term offtake contracting, while engineering specialists compete on reactor design and EPC execution. The competitive landscape stratifies into three archetypes: integrated technology licensors with captive EPC capabilities, industrial gas suppliers with on-site production expertise, and diversified chemical operators with backward-integrated feedstock positions. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with fifteen-year supply agreements locking in demand visibility.
Among technology licensors, TechnipFMC anchors large-scale reactor deployment across Gulf states through process licensing capabilities. Air Products and Chemicals extends its position via on-site syngas supply contracts tied to refinery and chemical park expansions. Linde occupies a position within the industrial gas tier, competing through cryogenic separation and gas handling systems integrated with reforming units. These three exemplify how competitive positioning concentrates around feedstock access, technology control, and contracting duration rather than manufacturing scale alone.
| Leading Market Players |
|---|
| TechnipFMC PLC |
| General Electric |
| Air Products and Chemicals Inc |
| Royal Dutch Shell plc |
| KBR Inc |
| BASF SE |
| Linde plc |
| Air Liquide |
| SABIC |
| Others |
Supply & Pricing Matrix
SFDA emissions protocols gate both supplier qualification and price differentiation in Saudi Arabia's syngas corridors, as carbon intensity benchmarks separate certified low-emission producers from conventional operators while embedding compliance costs into long-term offtake premiums.
Pricing Analysis
Long-term offtake contracts dominate pricing structures across Jubail and Yanbu chemical parks, with fifteen-year supply agreements locking in hydrogen-rich syngas streams for refinery desulfurization and ammonia synthesis. Price differentiation rests on carbon intensity certification tiers and feedstock flexibility guarantees, with biomass-co-fed certificates commanding premiums from European fertilizer offtakers. Cost compression in natural gas-based tiers is intensifying because stranded asset economics in the Gulf states contrast with import-dependent pricing in Egypt and Morocco. Chemical sector buyers exhibit lowest price sensitivity due to integrated energy-to-chemicals positioning, while independent power developers face acute margin pressure.
Supply Chain Analysis
Germany, Japan, and South Korea anchor high-temperature reactor fabrication and specialized gasification engineering talent pools serving Middle Eastern and African project demand. Supply chains draw from nickel alloy forgings, refractory ceramics, and cryogenic separation membranes as critical component inputs. Single-source vulnerability concentrates in Western European equipment licensing, where TechnipFMC-class process know-how lacks immediate substitution. Distribution runs through EPC contractor networks and on-site industrial gas supply models rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition opportunities as carbon accounting requirements splinter demand across fossil, blue, and biomass syngas pathways, generating distinct buyer archetypes with incompatible procurement criteria.
For Market Incumbents: Fortify position through backward integration into stranded natural gas feedstock positions in Saudi Arabia and the UAE, while securing biomass collection network partnerships in South Africa and Ethiopia to preempt emerging competitors. The priority lever is locking in fifteen-year offtake visibility before carbon border adjustments reshape European fertilizer import economics.
For New Entrants and Emerging Players: Anchor in Ethiopian agricultural residue supply chains and South African carbon tax-advantaged biomass pilots, where first-mover positioning in underdeveloped collection networks offers structural feedstock security. The penetrable segment is distributed syngas-to-fertilizer plants serving domestic East African agricultural markets, with go-to-market execution through development finance institution co-investment structures.
For Investors and Strategic Acquirers: South Africa's National Treasury carbon tax escalation reshapes the acquisition landscape toward biomass gasification specialists with proven 1,400°C slagging reactor deployments. Long-term viability favors technology licensors with captive EPC capabilities and regional feedstock partnerships over pure equipment suppliers. The signal to watch is REACH-aligned carbon border adjustment implementation tightening in European ammonia offtake contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Feedstock Security Partnerships | Locks in agricultural residue supply chains across Ethiopia and South Africa ahead of competitor entry. |
| Long-term Syngas Supply Agreements | Fifteen-year offtake contracts with SABIC-class operators secure demand visibility through carbon policy transitions. |
| High-temperature Reactor Technology Licensing | TechnipFMC-class process control enables premium positioning in Gulf state integrated gasification complexes. |
| Carbon Intensity Certification Investment | SFDA-aligned emissions benchmarking qualifies producers for European fertilizer export premiums. |
| Cryogenic Separation System Integration | Linde-class gas handling capabilities capture margin in hydrogen purification and synthetic fuel applications. |
Research Methodology
Initial hypotheses were tested against primary input from gasification plant managers, EPC procurement leads, downstream fertilizer offtake directors, and National Treasury carbon policy officials, then refined through secondary validation against SEC filings from industrial gas majors, IEA hydrogen project databases, Egyptian Environmental Affairs Agency permitting records, and trade flow data from Middle Eastern chemical export corridors. Bottom-up capacity buildout estimates triangulated with top-down demand projections from Haber-Bosch infrastructure utilization rates.
Variance decomposition across feedstock cost trajectories, technology licensing fees, and carbon pricing implementation schedules shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, feedstock category, gasification technology tier, and end-use industry concentration. CAGRs were derived from installed capacity expansion timelines correlated with regulatory milestone probability weightings, incorporating reactor fabrication lead times and biomass collection network development cycles as industry-specific inputs.
Material uncertainties — feedstock cost divergence between stranded gas assets and agricultural residue networks, carbon border adjustment enforcement timing, and high-temperature engineering talent availability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory trajectory continuity and EPC contractor capacity expansion. Recalibration cycles align with material shifts in SFDA emissions protocol stringency and European REACH implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
High Purity Gas Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Oxygen Market
Industrial Gases
Helium Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Metal Cutting Gas Market