
 Compressor Valves Market | 2026-2036
Compressor Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Compressor Valves Market Analysis
Petrochemical expansion is realigning compressor valve procurement priorities across energy transition corridors. Emerson Electric Co. leverages its digital valve monitoring portfolio to anchor positions in LNG export terminal projects. Burckhardt Compression AG sustains technology leadership through specialized high-pressure sealing architectures for hydrogen service. Hoerbiger Holding AG dominates aftermarket valve retrofit programs across North American pipeline infrastructure.
Compressor valves are precision-engineered flow control devices manufactured from stainless steel, brass, or carbon steel alloys, designed to regulate gas discharge and suction cycles in reciprocating and rotary compression systems operating at pressures from 50 to 10,000 psi. Their primary industrial purpose is maintaining compression efficiency while preventing backflow and minimizing fugitive emissions in continuous-duty process environments. Check valves command the largest product category share due to universal deployment across all compressor architectures, while solenoid valves represent the fastest-expanding segment driven by electrification of valve actuation in smart compressor systems. Stainless steel materials capture premium margin pools in corrosive service applications, particularly hydrogen and sour gas compression where material integrity standards are most stringent.
The EPA enforces methane emission thresholds under NSPS OOOOa that mandate low-leakage valve designs in US compressor stations, while ISO 13631 establishes international equipment standards for offshore compression packages. The EU F-Gas Regulation restricts fluorinated refrigerant leakage rates, directly shaping valve sealing specifications for European industrial refrigeration compressors. Stakeholders must monitor evolving hydrogen purity standards and their implications for valve metallurgy selection in emerging clean fuel compression chains.
Market Dynamics
EPA methane emission standards under NSPS OOOOa are forcing compressor station operators across the United States to accelerate replacement cycles for legacy high-leakage valve designs, redirecting capital toward low-emission sealing architectures and digital monitoring systems.
Growth Catalysts
- LNG Infrastructure Buildout:Gulf Coast export terminal expansions require specialized high-pressure valve configurations for cryogenic service. Terminal developers specify API 6D-compliant designs for reliability in continuous-duty liquefaction trains.
- Hydrogen Compression Standards:Emerging purity specifications for clean fuel transport are mandating stainless steel metallurgy and specialized sealing materials. Equipment fabricators face new material qualification protocols for hydrogen embrittlement resistance.
- Digital Valve Monitoring:Smart actuator integration enables predictive maintenance and emission quantification. Pipeline operators deploy sensor-embedded valves to satisfy EPA reporting requirements while reducing unplanned downtime.
Market Restraints
- Specialized Alloy Costs:Nickel-based superalloys for hydrogen and sour gas service command 3-4x carbon steel pricing. Material availability constraints from limited specialty steel mill capacity extend lead times for critical components.
- Supply Concentration:Precision forging and machining capacity for high-pressure valve bodies concentrates in Germany, Japan, and select US industrial corridors. Geographic clustering creates vulnerability to regional logistics disruptions.
- Technical Sealing Limitations:Polymer seal materials face temperature and pressure boundaries in next-generation hydrogen compression. Current elastomer formulations degrade under high-purity hydrogen cycling at elevated pressures.
Strategic Opportunities
- Aftermarket Retrofit Services:North American pipeline infrastructure contains thousands of legacy compressor stations requiring emission-compliant valve upgrades. Service providers can capture recurring revenue through scheduled replacement programs.
- Modular Valve Skids:Pre-assembled and factory-tested compressor valve packages reduce field installation time and commissioning risk. EPC contractors favor skid-mounted solutions for remote location deployments.
- EU Green Deal Alignment:Carbon border adjustment mechanisms and F-Gas Regulation amendments create demand for low-leakage designs in European industrial refrigeration and process gas applications.
Industry Challenges
- Specialized Welding Certification:Hydrogen service valve fabrication requires ASME Section IX-qualified welders with exotic alloy experience. Workforce shortages in this certification category constrain production scaling.
- Legacy System Integration:Digital valve monitoring retrofits must interface with existing SCADA architectures dating to 1990s-era installations. Protocol compatibility and cybersecurity hardening add engineering complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressor Valves Market |
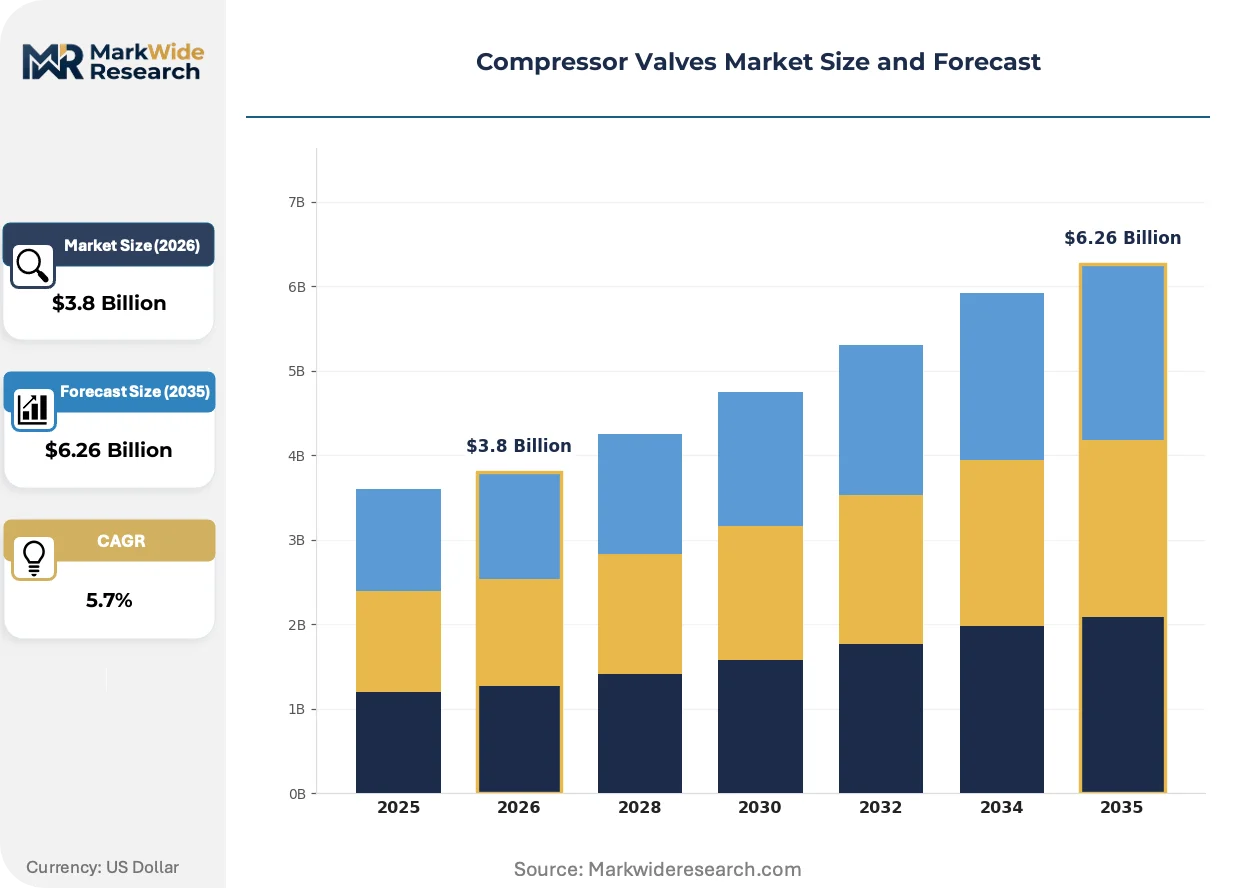
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Check Valves, Solenoid Valves, Ball Valves, Gate Valves Material: Stainless Steel, Brass, Plastic, Carbon Steel Application: Petrochemical, Industrial Refrigeration, Air Conditioning, Water Treatment End User: Manufacturing, Oil & Gas, HVAC, Power Generation |
| Companies Covered | Emerson Electric Co., Cook Compression, Burckhardt Compression AG, KB Delta, Compressor Products International, Hoerbiger Holding AG, Parker-Hannifin Corporation, H&S Valve Co., Ltd., Dresser-Rand Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressor Valves Market Emerging Trajectories
Material science advances and regulatory digitization mandates are converging to redefine compressor valve performance benchmarks. Equipment specifications now integrate real-time emission quantification alongside traditional pressure and flow metrics.
Additive manufacturing is absorbing prototyping and low-volume production of complex valve geometries previously machined from solid forgings. Specialized compressor OEMs adopt metal 3D printing for rapid iteration of flow-optimized seat designs. The technology is absorbing development timelines that previously spanned 18-24 months into 6-8 week cycles for qualified components.
EPA's updated methane performance standards now require quantified emission monitoring at individual valve locations rather than facility-level estimates. Compressor station operators must install calibrated measurement devices and report leakage rates through centralized databases. This regulatory architecture most severely affects legacy reciprocating compressor fleets in the Permian Basin and Appalachian production regions, where operators are bundling valve replacements with comprehensive station upgrades.
Asset ownership models are fragmenting as midstream operators unbundle valve maintenance from original equipment supply agreements. Third-party service specialists now capture aftermarket work previously retained by compressor packagers. This behavioral shift concentrates most visibly in the US Gulf Coast petrochemical corridor, where ethylene cracker operators prioritize localized service response over single-source OEM dependencies.
Compressor Valves Market Segmentation
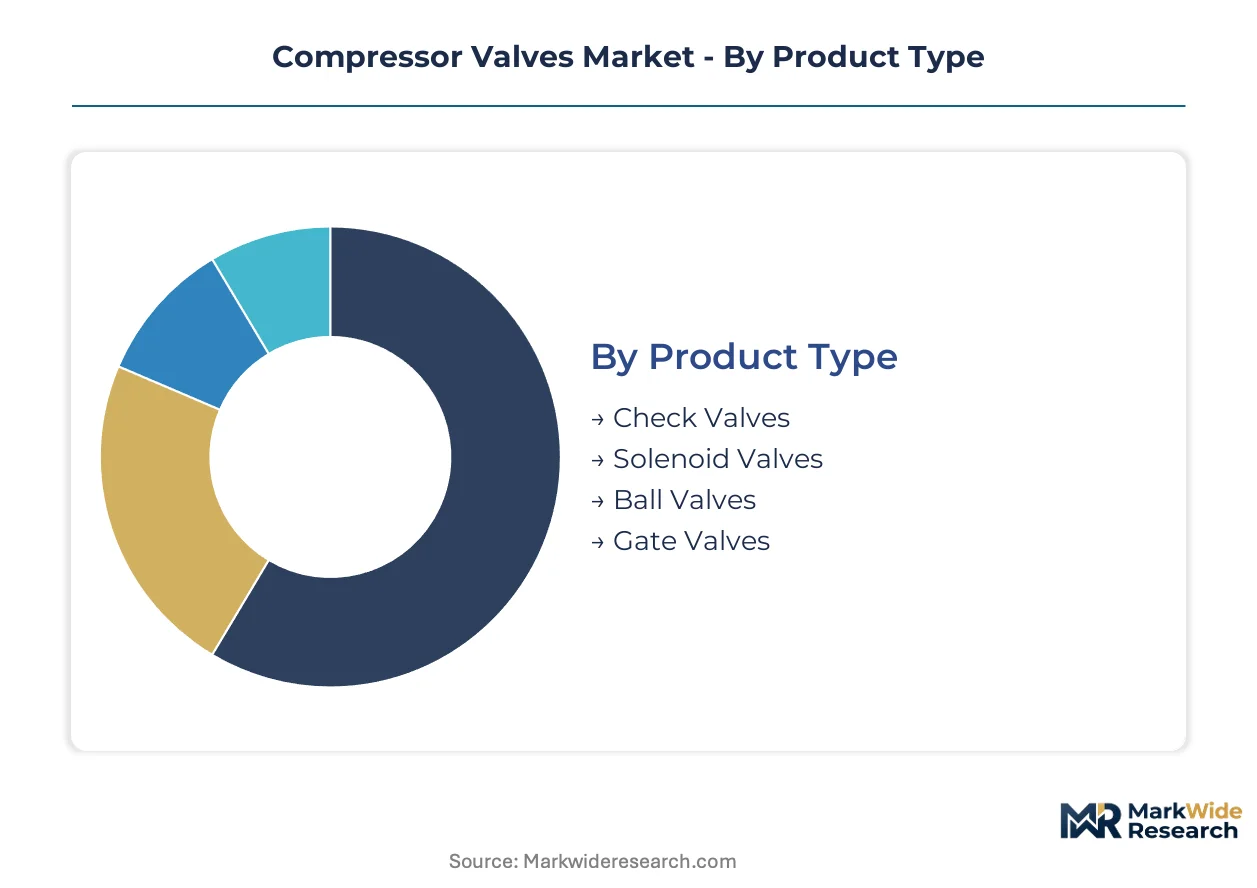
Compressor valve procurement patterns diverge sharply between standalone replacement markets and embedded OEM supply chains. Understanding these integration pathways reveals where margin pools concentrate and which specifications dominate engineering conversations.
Product Type:
Check valves operate as standalone components in field retrofit programs, while solenoid valves embed deeply into smart compressor architectures requiring factory calibration.
- Check Valves:Spring-loaded or swing-type designs manufactured from hardened stainless steel alloys regulate unidirectional flow in reciprocating compressor suction and discharge cycles. Demand concentrates in Permian Basin compressor station rebuilds where EPA methane rules force replacement of legacy high-leakage configurations.
- Solenoid Valves:Electromechanically actuated devices enable precise digital control of refrigerant and process gas flows through programmable logic interfaces. Gulf Coast LNG terminal developers specify these for liquefaction train automation, integrating them with centralized SCADA monitoring to satisfy emission quantification mandates.
- Ball Valves:Quarter-turn rotational designs provide tight shutoff in high-pressure hydrogen compression skids.
- Gate Valves:Linear-motion multi-turn configurations serve isolation duty in water treatment and low-pressure industrial refrigeration.
Volume placements concentrate in Check Valves; the faster expansion belongs to Solenoid Valves.
Material:
Cost tiers separate commodity carbon steel from premium nickel-based superalloys, with hydrogen service specifications driving metallurgy selection.
- Stainless Steel:Austenitic and duplex grades resist hydrogen embrittlement and sour gas corrosion in high-purity compression service. German specialty steel mills supply forgings for European hydrogen pipeline projects facing strict embrittlement resistance protocols.
- Carbon Steel:Standard grades dominate air compression and non-corrosive industrial refrigeration where material costs constrain project economics. Appalachian gas gathering operators specify these for dry gas compression stations with moderate pressure cycling.
- Brass:Lead-free formulations serve potable water and low-pressure HVAC applications with moderate temperature exposure.
- Plastic:Polymer composites enable corrosion resistance in chemical processing and select water treatment environments.
Carbon Steel commands the highest shipment volumes; Stainless Steel claims the steepest expansion trajectory as hydrogen infrastructure scales.
Application:
Customer maturity varies from specification-driven petrochemical engineering to price-sensitive commercial HVAC procurement.
- Petrochemical:Ethylene cracker and derivatives units require API-compliant high-pressure valve trains with documented material traceability. US Gulf Coast operators prioritize localized service response over single-source OEM dependencies for turnaround maintenance.
- Industrial Refrigeration:Ammonia and CO2 systems demand specialized sealing materials compatible with natural refrigerants. EU F-Gas Regulation amendments are accelerating low-leakage valve adoption across German and French food processing installations.
- Air Conditioning:Commercial and residential HVAC systems utilize standardized valve configurations with commodity pricing.
- Water Treatment:Municipal and industrial filtration systems specify corrosion-resistant designs for continuous-duty pump stations.
Petrochemical applications absorb the largest capital allocation; Industrial Refrigeration is gaining share fastest on regulatory tightening.
End User:
Procurement authority fragments between integrated oil and gas operators with centralized engineering standards and distributed HVAC contractors with localized purchasing.
- Oil & Gas:Midstream pipeline and upstream production operators manage valve replacement programs across thousands of compressor stations. FERC-regulated interstate pipelines in Texas and Louisiana bundle valve upgrades with comprehensive station automation retrofits.
- Power Generation:Combined cycle and peaking plants require rapid-response valve configurations for turbine protection systems.
- Manufacturing:General industrial facilities specify standard-duty valves for compressed air and process gas utility systems.
- HVAC:Mechanical contractors procure commodity valves through distribution channels with limited technical specification involvement.
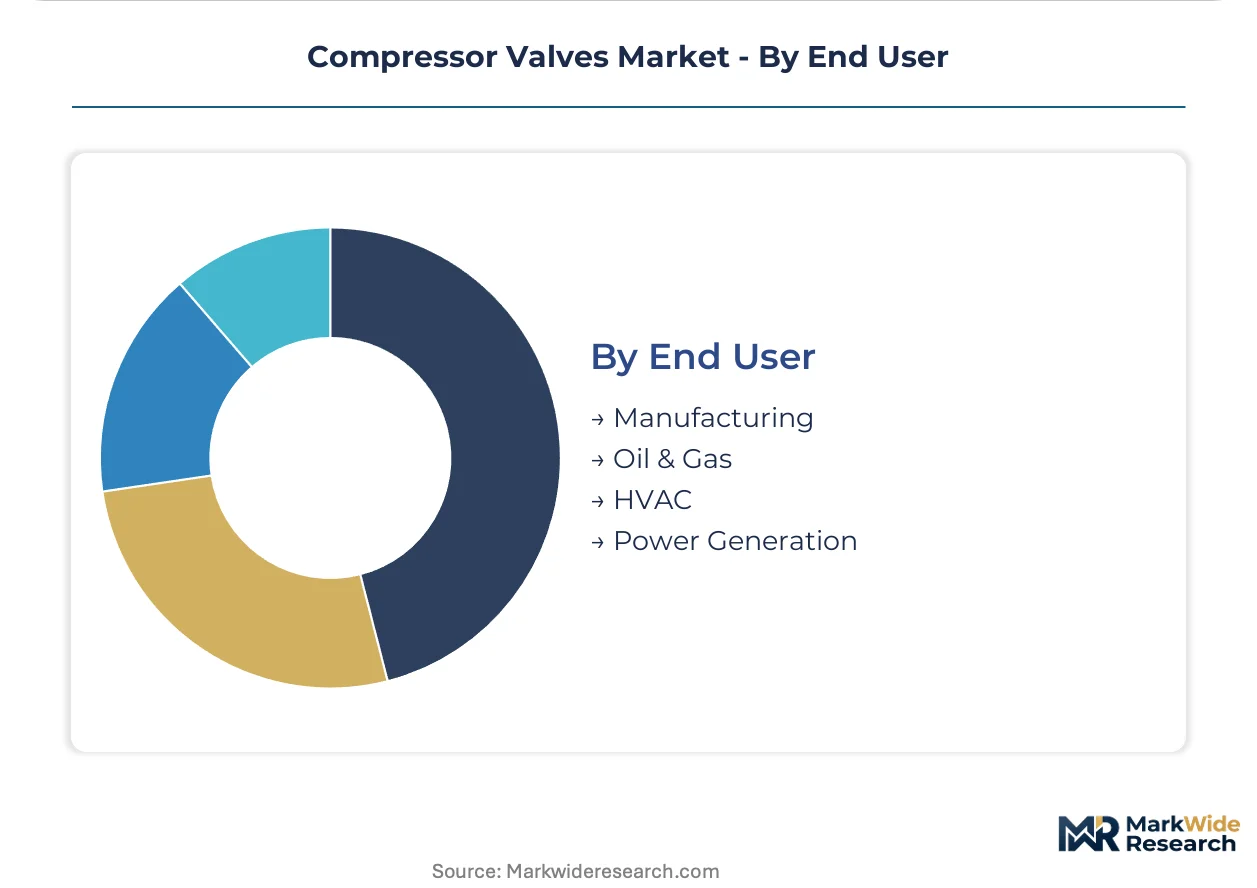
Oil & Gas maintains the dominant installed base; Power Generation is expanding most quickly on grid reliability investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor functions as the dominant demand concentration zone, with special economic incentives for ethylene cracker investments redirecting procurement volumes toward high-pressure valve configurations.
United States
Permian Basin compressor station operators face accelerated replacement cycles under EPA NSPS OOOOa methane standards. FERC-regulated interstate pipelines in Texas bundle valve upgrades with automation retrofits. Houston anchors the largest concentration of aftermarket service specialists serving Gulf Coast LNG terminal expansions.
Germany
European hydrogen pipeline projects require specialized stainless steel forgings with strict embrittlement resistance protocols. The EU F-Gas Regulation amendments tighten leakage specifications for industrial refrigeration valve sealing. Ruhr Valley specialty steel mills supply precision-forged components for clean fuel compression infrastructure.
China
Dual carbon goals under MEE directives accelerate demand for low-emission compression equipment in petrochemical clusters. GB standards for hydrogen purity reshape material qualification requirements for valve fabricators. Yangtze River Delta refineries deploy smart valve monitoring to satisfy emission quantification mandates.
Japan
METI hydrogen roadmap specifications drive investment in high-pressure sealing architectures for clean fuel transport. JIS standards for process gas equipment influence procurement criteria across Asian LNG import terminals. Chubu region industrial gas producers qualify specialized alloys for hydrogen embrittlement resistance.
India
PLI scheme incentives for petrochemical capacity expansion redirect valve procurement toward API-compliant high-pressure configurations. CEA regulations for grid reliability shape specification standards for power generation turbine protection systems. Gujarat refineries concentrate demand for corrosion-resistant valve materials in sour gas service.
Compressor Valves Market Vendor Landscape
Top-tier vendors anchor the premium sealing technology segment, while mid-scale fabricators compete on lead time and localized service response. The vendor base stratifies across three tiers: integrated industrial conglomerates with digital monitoring portfolios, specialized compression OEMs with proprietary high-pressure architectures, and regional aftermarket service specialists. Two dominant competitive moves define current positioning: backward integration into specialty alloy forging capacity and technology licensing agreements for hydrogen service material qualification.
Within the integrated technology tier, Emerson Electric Co. and Parker-Hannifin Corporation exemplify diversified industrial conglomerates with valve portfolios embedded in broader automation ecosystems. Burckhardt Compression AG occupies a specialist position among European compression OEMs with concentrated expertise in reciprocating machinery sealing systems. These three entities represent distinct strategic archetypes: platform diversification, vertical specialization, and regional service density.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Cook Compression |
| Burckhardt Compression AG |
| KB Delta |
| Compressor Products International |
| Hoerbiger Holding AG |
| Parker-Hannifin Corporation |
| H&S Valve Co., Ltd. |
| Dresser-Rand Group Inc. |
| Others |
Supply Flow & Price Mechanics
Additive manufacturing adoption in compressor valve prototyping is compressing development timelines from 18-24 months to 6-8 weeks while simultaneously fragmenting supply concentration away from traditional German and Japanese precision forging centers toward distributed metal 3D printing facilities.
Pricing Analysis
Lead-time premiums dominate compressor valve pricing, with emergency replacement orders commanding substantial markups over scheduled procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates API-certified stainless steel hydrogen service valves from carbon steel standard-duty configurations and spot-market commodity inventory. Price differentiation hinges on ASME Section IX welding certification tier and volume scale, with Gulf Coast petrochemical operators least sensitive due to turnaround-critical timelines and Appalachian gas gathering contractors most price-sensitive given lean operating budgets. Cost compression in carbon steel tiers is intensifying because specialty alloy shortages force buyers toward lower-specification alternatives.
Supply Chain Analysis
Freight costs for precision-forged valve bodies from Ruhr Valley mills to US Gulf Coast terminals add 12-18% landed cost premiums versus regional sourcing, reshaping procurement geography for time-sensitive projects. Supply concentrates in Germany, Japan, and select US industrial corridors for high-pressure forging capacity, while raw material sourcing draws from Australian nickel mines, Chilean copper deposits, and domestic scrap steel processors. Single-source vulnerability concentrates in specialty alloy qualification protocols, where hydrogen embrittlement testing certification rests on limited third-party laboratory capacity. Distribution runs through OEM-authorized service networks for warranty-critical applications and independent aftermarket specialists for legacy station retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compressor valves market functions as a cost-of-compliance arena where EPA NSPS OOOOa methane standards erect regulatory moats favoring incumbents with certified low-leakage architectures and quantified emission monitoring capabilities.
For Market Incumbents: Deepen backward integration into specialty alloy forging capacity to secure hydrogen service material supply against German and Japanese mill bottlenecks. Anchor positions in Gulf Coast LNG terminal service contracts before third-party specialists capture aftermarket fragmentation. Prioritize ASME Section IX welding certification pipeline investments to constrain production scaling by uncertified competitors facing workforce shortages. For New Entrants and Emerging Players: Aftermarket service specialists represent the most penetrable channel partner type for bypassing OEM-dominated new equipment supply chains. Target Permian Basin compressor station operators with bundled valve replacement and digital monitoring retrofit packages. Pursue white-space positioning in modular valve skid pre-assembly for remote location deployments where EPC contractors prioritize installation speed over single-source branding. For Investors and Strategic Acquirers: Re-rating potential sits with hydrogen-qualified specialty fabricators given METI and EU purity specification convergence accelerating stainless steel valve demand. Long-term viability favors targets with captive forging relationships and established material qualification protocols rather than assembly-only operators. Watch FERC interstate pipeline automation retrofit announcement velocity as the inflection signal for aftermarket service demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Forging | Captive nickel-based superalloy supply secures hydrogen service production against German mill capacity constraints. |
| Digital Valve Monitoring Platform Launch | Sensor-embedded architectures satisfy EPA quantified emission reporting mandates while reducing unplanned downtime. |
| Hydrogen Service Material Qualification Partnership | Technology licensing agreements with METI-certified laboratories accelerate JIS-compliant clean fuel compression entry. |
| Aftermarket Retrofit Service Network Expansion | Localized valve replacement programs capture recurring revenue from thousands of legacy North American compressor stations. |
| Modular Valve Skid Manufacturing Scale-Up | Factory-tested packages reduce field installation time for remote Gulf Coast LNG terminal and hydrogen hub deployments. |
Methodological Framework
Trade publications, customs databases, and SEC equipment supplier filings formed the secondary backbone, cross-referenced against primary interviews with compressor OEM procurement directors, EPA compliance officers at midstream operators, specialty steel mill sales executives, and aftermarket service network managers. Bottom-up unit economics triangulated against top-down infrastructure investment tracking across the analysis window.
Historical capital deployment patterns in LNG export terminals, hydrogen pipeline projects, and compressor station automation retrofits established baseline demand trajectories. Segmentation modeling incorporated product type, material grade, application severity, and end-user procurement authority dimensions. CAGRs were derived from facility-level equipment specification trends and regulatory compliance deadline clustering.
Caveats apply where EPA methane standard enforcement intensity, specialty alloy availability disruptions, or hydrogen purity specification revisions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Stainless Steel Valve Tag Market
Valves
Gate Impellers Market
Valves
Safety Valve Market
Valves
Global Valves Market
Valves
Valve Interlocks Market
Valves
Global Valves in Chemical Market
Valves
Mobile Hydraulic Valves Market
Valves
Industrial Vacuum Valves Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Instrumentation Valves and Fittings Market
Valves
Pneumatic Slide Gates Market
Valves
Diaphragm Valve Market
Valves
Isolator Valves Market
Valves
Flanges Market
Valves
Steam Trap Valve Market
Valves
Axial and Radial Seals Market