
 Bus Compressor Market | 2026-2036
Bus Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Compressor Market Outlook
Aftermarket distribution for bus compressors is fragmenting as digital procurement platforms and regional service networks displace traditional tiered supply arrangements. Denso Corporation leverages its integrated thermal systems portfolio to anchor long-term contracts with Japanese and European OEMs. Valeo SA competes through geographic dominance in European bus retrofit channels, while MAHLE GmbH specializes in scroll compressor architectures for electric bus platforms.
A bus compressor is a mechanical device that pressurizes refrigerant vapor within closed-loop HVAC or refrigeration circuits, typically operating at discharge pressures between 15 and 35 bar depending on refrigerant type and ambient conditions. Its primary purpose is to enable heat transfer for passenger cabin climate control and, in refrigerated transit applications, to maintain cargo temperatures within specified bands. Scroll compressors occupy the premium tier in electric bus deployments due to their quieter operation and higher efficiency at partial loads, while reciprocating units retain cost advantages in conventional diesel fleet retrofits. Screw technology leads in high-capacity cooling systems for articulated buses and coach segments where continuous duty cycles dominate operational profiles.
The EPA enforces refrigerant containment and leakage standards that shape compressor sealing specifications for buses operating in US interstate corridors. EMA and REACH collectively govern chemical composition limits and material disclosure requirements affecting European compressor supply chains. China's GB standards and MIIT energy-efficiency directives dictate minimum performance thresholds for domestically manufactured units. Stakeholders must monitor how refrigerant phase-down schedules intersect with electric bus platform development timelines to align product roadmaps with compliance windows.
Market Dynamics
Electric bus platform proliferation is compressing development cycles for HVAC thermal systems, forcing compressor architectures to evolve faster than conventional diesel retrofit timelines permit.
Growth Catalysts
- EU F-Gas Regulation:Mandatory hydrofluorocarbon phase-down schedules are pulling OEMs toward low-GWP refrigerant-compatible compressor designs, expanding addressable market for compliant suppliers.
- Urban transit fleet electrification:Municipal operators in China are retrofitting existing depots with electric HVAC infrastructure, creating sustained demand for scroll compressor volumes.
- Shanghai-Changsha manufacturing clusters:Domestic production scale-up is reducing unit costs for export-grade compressors, enabling price-competitive penetration into Southeast Asian and Latin American bus markets.
Market Restraints
- Copper and rare-earth magnet cost volatility:Permanent magnet motor materials for high-efficiency scroll compressors face input price swings that compress OEM margin structures.
- Sealing technology bottlenecks:Low-GWP refrigerants require tighter shaft seal tolerances than legacy R-134a systems, limiting qualified supplier pools to specialized precision manufacturers.
- Articulated bus screw compressor duopoly:High-capacity continuous-duty systems concentrate among two European suppliers, creating procurement risk for fleet operators dependent on single-source availability.
Strategic Opportunities
- India BIS energy-efficiency mandates:Upcoming compressor performance standards for urban bus fleets create first-mover advantage for suppliers with pre-certified scroll platforms.
- Digital procurement platforms:B2B marketplaces for aftermarket compressor parts are disintermediating traditional tiered distribution, enabling direct manufacturer-to-fleet relationships.
- Refrigerant-cooling convergence:Integration of battery thermal management with cabin HVAC is collapsing separate compressor architectures into unified variable-speed systems.
Industry Challenges
- Scroll compressor rotor machining expertise:Precision orbital scroll manufacturing requires specialized CNC programming skills that remain concentrated among Japanese and German equipment suppliers.
- Dual refrigerant certification timelines:Compressor platforms must simultaneously validate R-513A and R-1234yf compatibility, stretching engineering resources across parallel test protocols.
- Legacy fleet interoperability:Electric bus HVAC retrofits demand mechanical interface adapters for existing ductwork, adding integration complexity to deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Compressor Market |
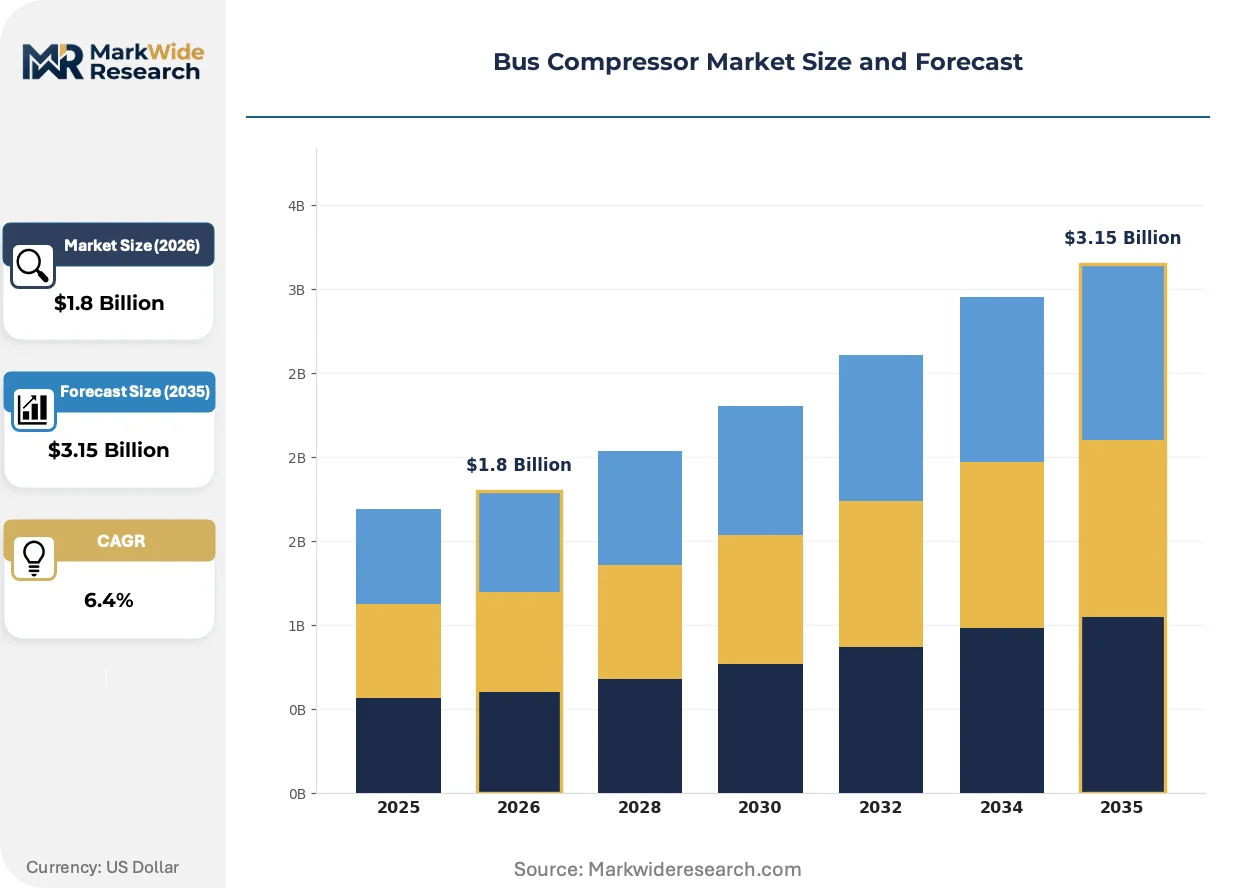
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scroll, Reciprocating, Screw, Rotatory End User: Public Transport, Private Operators, Fleet Management, OEMs Application: Air Conditioning, Refrigeration, Power Generation, Cooling Systems Technology: Electric, Hybrid, Solar, Conventional |
| Companies Covered | BorgWarner Inc., Denso Corporation, Hanon Systems, HELLA GmbH & Co. KGaA, MAHLE GmbH, Mitsubishi Electric Corporation, Sanden Corporation, Toyota Industries Corporation, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Compressor Market Strategic Shifts
Thermal system integration is collapsing discrete component boundaries, while regulatory chemistry mandates and procurement digitization are rewriting how compressors are specified, sourced, and serviced.
Variable-speed scroll compressor technology is collapsing the operational gap between partial-load efficiency and full-capacity performance. Electric bus fleet operators in China are specifying these units for routes with frequent stop-start cycles. The technology is collapsing demand for dual-compressor redundancy in mid-size articulated buses.
EPA refrigerant containment standards are tightening leakage-rate thresholds for interstate bus operators. Compressor sealing specifications now require magnetic shaft seals or hermetic designs previously reserved for rail applications. US-based coach manufacturers are responding by pre-qualifying European sealing suppliers for domestic assembly lines.
Fleet procurement departments are consolidating HVAC compressor specifications across mixed diesel-electric fleets. Traditional tiered aftermarket distribution is losing volume to direct-service contracts with compressor OEMs. This consolidation is most visible in German municipal operators bundling 10-year thermal system lifecycle agreements.
Bus Compressor Market Segmentation
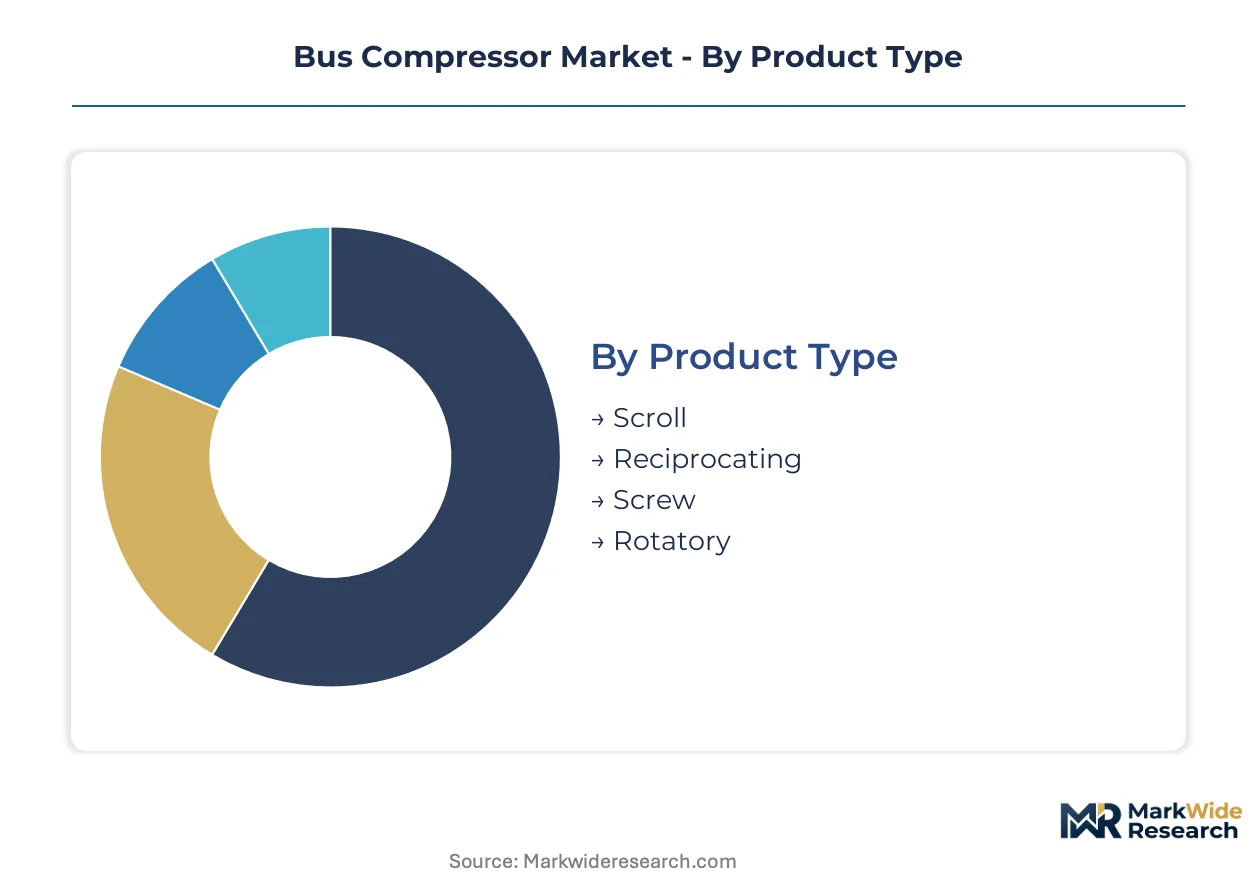
Bus compressor segmentation reflects divergent thermal system requirements across electrification trajectories. Product architecture, end-user procurement power, and refrigerant chemistry mandates create distinct commercial pockets with incompatible specification standards.
Product Type:
Mature reciprocating platforms coexist with emerging scroll architectures as fleet operators navigate diesel-to-electric transition timelines.
- Scroll:Orbital compression mechanisms deliver 15-20% efficiency gains at partial loads critical for electric bus stop-start duty cycles. Chinese municipal operators in Shanghai and Shenzhen are specifying these units for new electric fleet deployments under MIIT energy-efficiency directives.
- Reciprocating:Piston-driven compression remains cost-dominant for legacy diesel bus HVAC retrofits where capital constraints outweigh efficiency premiums. Indian state transport undertakings continue procurement of these units for conventional fleet maintenance.
- Screw:Continuous-duty rotary designs serve articulated bus and coach segments requiring sustained cooling capacity across interstate corridors.
- Rotatory:Vane-based compression occupies niche applications in compact shuttle buses where space constraints override efficiency optimization.
Scroll retains volume leadership in new electric platform procurement; screw holds the steepest expansion curve in high-capacity coach segments.
End User:
Procurement consolidation varies sharply between fragmented private operators and concentrated municipal purchasing authorities.
- Public Transport:Municipal authorities in China and Europe bundle decade-long thermal service contracts, compressing supplier margins through volume aggregation. These entities dominate scroll compressor procurement for electric fleet standardization.
- Private Operators:Fragmented ownership across Latin American and Southeast Asian markets sustains price-sensitive reciprocating demand through spot aftermarket purchases.
- Fleet Management:Third-party vehicle lifecycle managers are consolidating HVAC specifications across mixed diesel-electric assets to simplify maintenance protocols.
- OEMs:Bus manufacturers in Germany and Japan pre-qualify compressor suppliers during platform development, locking in scroll architectures for next-generation electric chassis.
Public transport commands procurement volume concentration; fleet management is expanding most quickly as outsourcing penetrates municipal operations.
Application:
Climate control duty cycles diverge substantially between passenger comfort and cargo preservation requirements.
- Air Conditioning:Cabin cooling systems operate under variable load profiles tied to door-opening frequency and occupancy fluctuations. EPA refrigerant containment standards are mandating magnetic shaft seals for interstate coach operators.
- Refrigeration:Temperature-controlled transit for pharmaceutical and food cargo demands precise setpoint maintenance, favoring variable-speed scroll modulation over on-off reciprocating cycles.
- Power Generation:Auxiliary compressor systems in hybrid bus platforms support electrical subsystem cooling during regenerative braking thermal spikes.
- Cooling Systems:Battery thermal management integration is collapsing discrete HVAC and powertrain cooling circuits into unified refrigerant architectures.
Air conditioning maintains installed base dominance; battery cooling integration is climbing the fastest as electric platforms proliferate.
Technology:
Power source segmentation tracks the divergence between grid-dependent electric systems and transitional hybrid architectures.
- Electric:Battery-powered scroll compressors with permanent magnet motors achieve coefficient of performance ratings exceeding conventional alternatives. China's dual carbon goals are accelerating domestic manufacturing scale-up in Changsha production clusters.
- Hybrid:Dual-source systems combine engine-driven and electric compressor modes to bridge diesel-electric fleet transition periods.
- Solar:Photovoltaic-assisted cooling remains experimental in desert-climate test fleets where roof panel integration offsets auxiliary load.
- Conventional:Belt-driven reciprocating compressors tethered to internal combustion engines face phase-out pressure under EU F-Gas Regulation compliance timelines.
Electric technology holds procurement priority in new platform development; hybrid sustains interim demand during fleet transition windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing leverage through Shanghai-Changsha production clusters, while European sealing specialists extract premiums for low-GWP refrigerant compatibility. This asymmetry shapes procurement patterns across electrified transit corridors.
China
Municipal electrification programs in Shanghai and Shenzhen drive scroll compressor volumes for electric bus fleets. MIIT energy-efficiency directives mandate minimum performance thresholds for domestically manufactured units. Changsha manufacturing clusters scale output for export supply into Southeast Asian and Latin American markets.
Germany
Coach manufacturers pre-qualify European sealing suppliers for domestic assembly lines under EPA-influenced containment standards. EU F-Gas Regulation phase-down schedules pull OEMs toward low-GWP refrigerant-compatible designs. Bavaria-based thermal system integrators anchor decade-long service contracts with municipal operators.
United States
Interstate bus operators face EPA refrigerant containment standards tightening leakage-rate thresholds for HVAC systems. Magnetic shaft seals or hermetic designs migrate from rail applications into coach specifications. Southwest depot retrofits concentrate demand for electric HVAC infrastructure.
Japan
Integrated thermal systems portfolios anchor long-term contracts with domestic and European OEMs. METI efficiency guidelines shape scroll compressor development for hybrid platforms. Kanto-region precision machining expertise supports orbital scroll manufacturing requirements.
India
State transport undertakings maintain reciprocating compressor procurement for conventional fleet maintenance amid capital constraints. Upcoming BIS energy-efficiency mandates for urban bus fleets create certification windows for pre-qualified scroll platforms. Maharashtra depot electrification pilots test variable-speed integration.
Bus Compressor Market Competitive Environment
Vertically integrated thermal specialists and precision component fabricators split the market between system-level contracts and specialized sub-tier supply. The vendor base concentrates among Japanese, German, and Korean conglomerates with captive HVAC divisions, alongside Chinese scale manufacturers. Two archetypes dominate: integrated automotive suppliers bundling compressor outputs with full thermal management stacks, and dedicated climate-component specialists focusing on refrigerant-specific sealing and modulation technologies. Competitive moves center on geographic expansion into electrifying transit corridors and technology licensing for low-GWP refrigerant compatibility.
Within the integrated supplier tier, Denso Corporation and Valeo SA exemplify full-stack thermal system providers, while MAHLE GmbH occupies a position among dedicated component specialists. Denso leverages its Kanto-region engineering base to anchor multi-year platform contracts. Valeo SA sits within the European retrofit channel dominance archetype. MAHLE GmbH represents the precision-scroll specialization vector for electric bus architectures.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Denso Corporation |
| Hanon Systems |
| HELLA GmbH & Co. KGaA |
| MAHLE GmbH |
| Mitsubishi Electric Corporation |
| Sanden Corporation |
| Toyota Industries Corporation |
| Valeo SA |
| Others |
Value Chain & Pricing Dynamics
Changsha manufacturing clusters anchor global scroll compressor output, concentrating precision machining expertise and permanent magnet motor supply in a single geography that captures margin pools downstream in European and North American retrofit channels. This upstream density shapes how OEMs negotiate long-term offtake terms and where fleet operators face procurement bottlenecks.
Pricing Analysis
Configured-to-order scroll compressors for electric bus platforms command 25-40% premiums over standard reciprocating units for diesel retrofits. Three-tier pricing structure across premium, standard, and economy levels stratifies by refrigerant compatibility grade and MIIT energy-efficiency certification tier. Cost compression in the standard tier is intensifying because Shanghai-Changsha scale manufacturers are exporting surplus volumes into Southeast Asian spot markets. Private operators in Latin America exhibit highest price sensitivity, while German municipal authorities bundling decade-long thermal service contracts show lowest sensitivity due to lifecycle cost optimization mandates.
Supply Chain Analysis
Export control regimes limiting rare-earth magnet flows from China constrain permanent magnet motor availability for high-efficiency scroll compressors. Supply concentrates in China, Germany, and Japan, with Changsha and Kanto-region production clusters feeding global demand. The chain draws from copper winding stock, neodymium-iron-boron magnets, and precision aluminum castings. Single-source vulnerability concentrates in European sealing specialists qualified for low-GWP refrigerant shaft tolerances. Distribution runs through direct-service contracts with compressor OEMs that are displacing traditional tiered aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bus compressor procurement is shifting toward platform-economics logic as battery thermal management and cabin HVAC collapse into unified refrigerant architectures, creating winner-take-most dynamics for suppliers controlling system-level integration protocols.
For Market Incumbents: Build switching-cost moats through pre-qualified sealing technology locked into OEM platform development timelines. Deepen backward integration into permanent magnet motor supply to buffer rare-earth price volatility. Denso Corporation's Kanto-region captive production of orbital scroll machining equipment exemplifies this defensive posture against emerging Chinese scale manufacturers. For New Entrants and Emerging Players: Establish a beachhead in India's state transport undertaking reciprocating replacement market ahead of BIS energy-efficiency mandate enforcement. Target Maharashtra depot electrification pilots with variable-speed scroll platforms pre-certified for R-513A compatibility. A direct-to-fleet digital procurement play bypasses entrenched tiered distribution networks that Valeo SA dominates in European retrofit channels. For Investors and Strategic Acquirers: Capital is best deployed toward precision component specialists with orbital scroll CNC programming expertise concentrated among Japanese and German equipment suppliers. The long-term viability window favors suppliers bridging low-GWP refrigerant certification gaps before EU F-Gas Regulation phase-down deadlines compress qualified supplier pools. Watch for MIIT efficiency directive tightening as the inflection signal triggering consolidation among Changsha scale manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Low-GWP Refrigerant Platform Certification | EU F-Gas Regulation phase-down deadlines compress qualified supplier pools to specialized precision manufacturers. |
| Permanent Magnet Motor Backward Integration | Captive neodymium-iron-boron supply buffers OEM margin structures against rare-earth price volatility from Chinese export quotas. |
| Direct-to-Fleet Digital Procurement Launch | B2B marketplace disintermediation collapses traditional tiered distribution margins held by European retrofit channel incumbents. |
| Orbital Scroll CNC Equipment Acquisition | Precision machining expertise concentration in Kanto-region Japanese suppliers creates scarcity value for electric bus platform contracts. |
| Battery Thermal Management Integration | Unified variable-speed refrigerant architectures collapse discrete HVAC and powertrain cooling compressor demand into single-source procurement. |
Study Parameters
Initial hypotheses were tested against primary input from HVAC system procurement managers at municipal transit authorities, compressor OEM platform engineers, aftermarket service network directors, and rare-earth magnet supply specialists, then refined against secondary validation from MIIT energy-efficiency directive filings, EU F-Gas Regulation implementation reports, EPA refrigerant containment enforcement data, and customs trade records for compressor component flows. Bottom-up fleet deployment tracking and top-down manufacturing capacity estimates were triangulated to anchor volume assumptions.
Demand-supply balance modeling across the projection horizon segmented by compressor architecture type, end-user procurement authority concentration, refrigerant chemistry compatibility tier, and regional electrification policy intensity. CAGRs were derived from installed base turnover rates and new platform penetration curves. Key inputs included municipal bus fleet electrification timelines in Shanghai and Shenzhen, and articulated bus screw compressor utilization rates across interstate coach corridors.
Macroeconomic conditions sit as an overlay; deviation in copper and rare-earth magnet price trajectories would shift the trajectory of cost-competitive scroll compressor adoption in price-sensitive markets. Forecasts reflect assumptions about EU F-Gas Regulation enforcement consistency and MIIT directive implementation pacing. Material shifts in low-GWP refrigerant sealing technology qualification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Process Gas Compressors Market
Compressors
USA Scroll Compressor Market
Compressors
Regenerative Blowers Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Gas Compressors Market
Compressors
Hydrogen Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Rotary Lobe Compressor Market
Compressors
Booster Compressor Market
Compressors
Compressor Rental Market
Compressors
Compressor Wheel Market
Compressors
North America Air Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
North America Centrifugal Compressor Market