
 Cloud Applications Market | 2026-2036
Cloud Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Applications Market Intelligence
Subscription-based software licensing is restructuring how enterprises procure and consume business applications. Salesforce leverages vertical specialization across CRM workflows to sustain premium positioning. Microsoft Azure anchors enterprise productivity suites through deep integration with identity and collaboration infrastructure. Amazon Web Services competes on compute elasticity that underpins third-party SaaS delivery at scale.
Cloud applications denote software programs hosted on remote server infrastructure and delivered to users via internet protocols, typically operating through multi-tenant architectures with API-driven interoperability as a core functional parameter. Their primary commercial purpose is to replace on-premises software ownership with metered service consumption that shifts capital expenditure to operational expenditure. SaaS solutions within the use case dimension command the largest revenue pool as enterprises standardize on pre-configured workflows for customer relationship management and enterprise resource planning. Hybrid cloud deployment is gaining fastest traction among regulated industries seeking to partition sensitive workloads between private infrastructure and public elasticity.
FDA guidelines on software as a medical device intersect with HIPAA privacy mandates to create dual compliance obligations for healthcare cloud deployments in the United States. The EU AI Act imposes risk-classification requirements on automated decision systems that European cloud providers must architect into their service stacks. GDPR data-localization provisions continue shaping where cloud infrastructure gets provisioned and how cross-border data flows get engineered. Stakeholders must monitor how divergent regulatory timelines between American sectoral rules and European horizontal frameworks affect product roadmaps and geographic rollout sequencing.
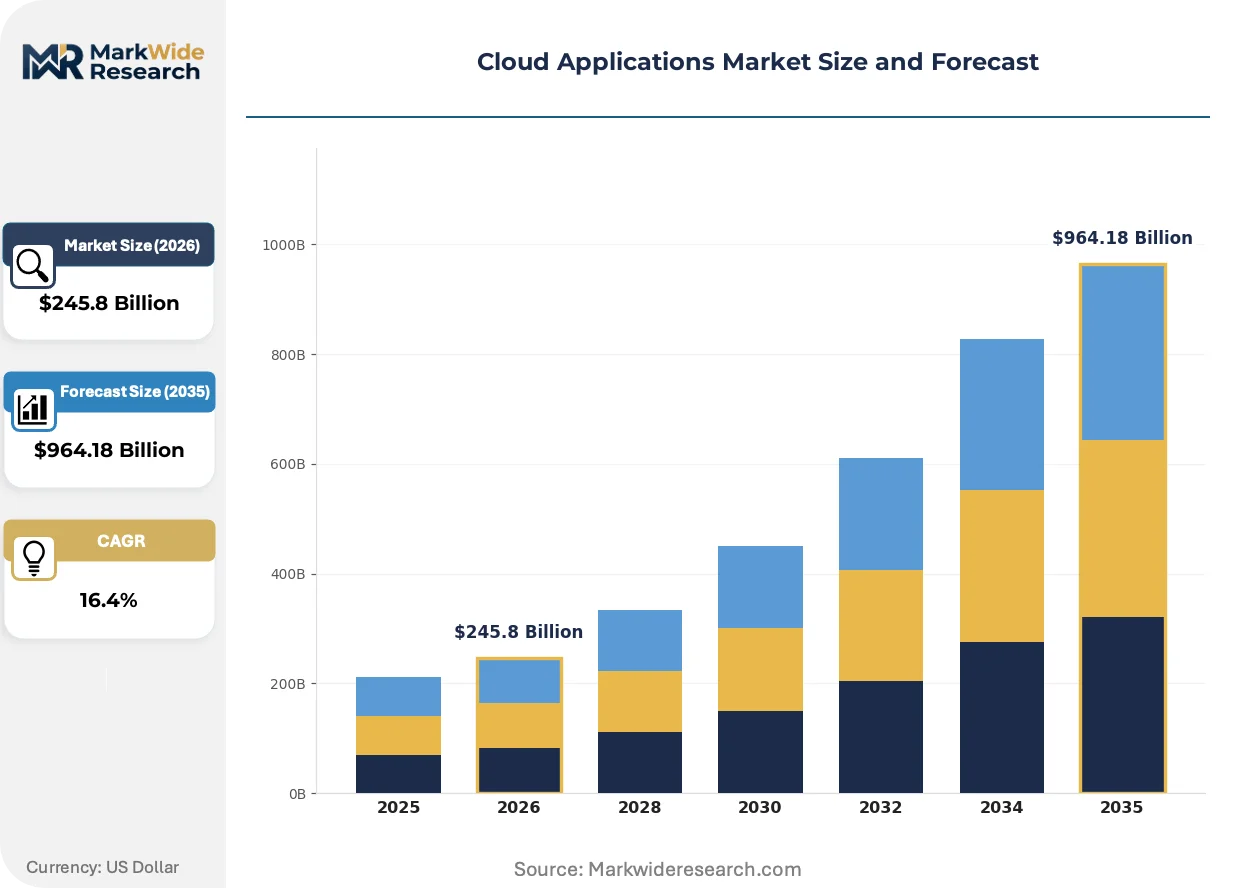
Market Dynamics
Enterprise workload migration to SaaS architectures is compressing traditional software licensing cycles and forcing infrastructure providers to absorb compliance complexity as a bundled service cost.
Growth Catalysts
- EU AI Act risk-classification mandates:European enterprises must rebuild algorithmic workflows on compliant cloud stacks, expanding demand for certified infrastructure providers.
- Healthcare digitization:HIPAA-covered entities in the United States are replacing on-premises EHR systems with cloud-native platforms to streamline clinical data interoperability.
- Financial services core banking migration:US banks are offloading legacy mainframe operations to multi-tenant SaaS environments to reduce fixed IT overhead.
Market Restraints
- Cross-border data friction:GDPR localization requirements force redundant infrastructure provisioning, raising operational costs for pan-European deployments.
- Concentrated hyperscaler dependency:Three providers control the majority of elastic compute capacity, creating single-point-of-failure exposure for downstream SaaS vendors.
- Latency constraints at the edge:Real-time manufacturing control systems cannot tolerate round-trip delays to centralized cloud regions, limiting addressable use cases.
Strategic Opportunities
- India's data center expansion:Local cloud regions under RBI guidelines offer captive demand from fintechs requiring domestic transaction processing.
- Generative AI API convergence:Embedding large language model inference into vertical SaaS workflows creates new pricing tiers for knowledge-worker automation.
- Brazil's ANVISA digital health pathway:Streamlined software-as-medical-device approvals accelerate cloud-based diagnostic tool commercialization.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Enterprise IT teams lack staff proficient in Kubernetes-native workload portability across heterogeneous environments.
- FDA-HIPAA dual compliance timelines:Healthcare SaaS vendors face extended validation cycles when software triggers both medical device and privacy oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Applications Market |
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $964.18 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution: Software as a Service, Platform as a Service, Infrastructure as a Service, Function as a Service Use Case: Customer Relationship Management, Enterprise Resource Planning, Human Capital Management, Supply Chain Management, Content Management End User: Banking & Financial Services, Telecommunications, Government Agencies, Education, Manufacturing |
| Companies Covered | Salesforce, Microsoft Azure, Amazon Web Services, ServiceNow, Workday, Google Cloud Platform, Oracle Cloud Infrastructure, Snowflake, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Applications Market Strategic Shifts & Innovations
Containerized microservices architectures are collapsing the boundary between infrastructure and application layers, enabling new operational models that treat compliance as code.
Kubernetes-native service meshes are consolidating control plane functions for traffic management, security policy enforcement, and observability into unified layers. Financial services firms in Singapore and London are deploying these architectures for payment processing workloads. The consolidation is compressing vendor stacks and reducing integration overhead for enterprise platform teams.
CSRD sustainability reporting mandates in Europe require cloud providers to disclose Scope 3 emissions from customer workloads. This is forcing infrastructure operators to build granular carbon accounting into billing systems. German industrial SaaS buyers are now selecting providers based on verified emissions transparency.
Consumption-based pricing models are displacing committed-use contracts among mid-market enterprises. Channel partners in Australia and Canada are unbundling implementation services from software subscriptions. Healthcare providers in Ontario are piloting this structure for clinical workflow tools to align costs with patient volume fluctuations.
Cloud Applications Market Segmentation
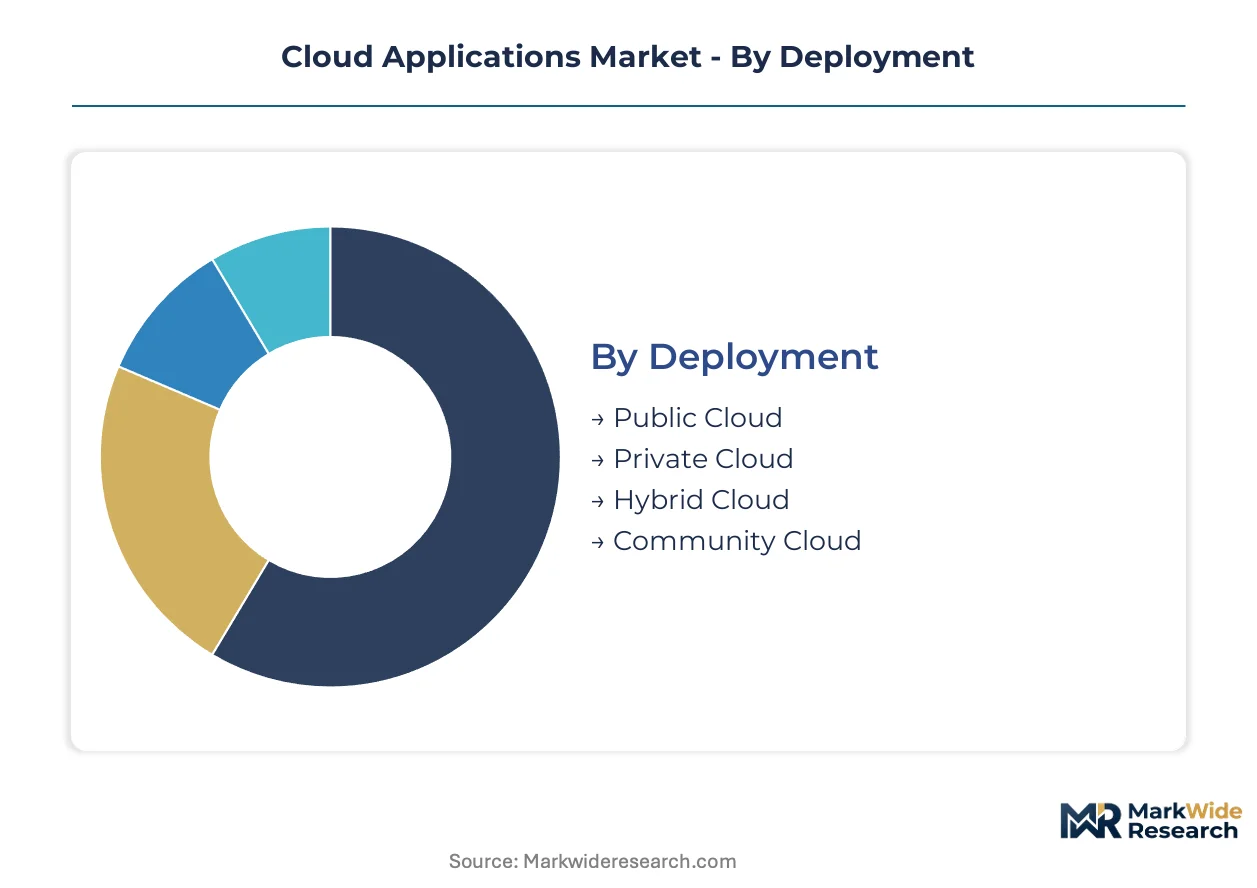
Cloud applications segmentation reveals how compliance architecture, workload sensitivity, and buyer procurement maturity fragment demand across deployment modes and service layers. Each category carries distinct certification burdens that reshape vendor competitive positioning and customer switching costs.
Deployment:
Public cloud deployments face the lightest certification overhead, while private and hybrid configurations trigger sector-specific mandates from HIPAA, GDPR, and EU AI Act regulators.
- Public Cloud:Multi-tenant infrastructure shared across unaffiliated organizations delivers compute through standardized API contracts. Demand concentrates among US fintechs and European scale-ups prioritizing speed-to-market over data sovereignty, though GDPR Article 44 cross-border transfer rules constrain multi-region architectures.
- Private Cloud:Dedicated single-tenant environments provisioned for exclusive customer use support customized compliance postures. German automotive suppliers and French healthcare networks deploy these to satisfy CSRD emissions traceability and ANSM data localization requirements without surrendering infrastructure control.
- Hybrid Cloud:Federated architectures partition sensitive workloads to private infrastructure while bursting elastic demand to public capacity. Manufacturing firms in Japan and regulated banks in Singapore favor this model to satisfy METI operational technology isolation mandates alongside cloud-native analytics.
- Community Cloud:Shared infrastructure restricted to organizations with common compliance obligations or industry membership. Australian healthcare consortia and Canadian provincial government clusters deploy these to amortize TGA and Health Canada validation costs across multiple entities.
Leading the category by volume: Public Cloud. Growing fastest: Hybrid Cloud.
Solution:
Service abstraction layers stratify by customer technical sophistication, with higher-stack services commanding premium pricing but requiring deeper integration labor.
- Software as a Service:Fully managed applications delivering complete business functionality through web interfaces. US financial services firms and European retail chains standardize on pre-configured CRM and ERP workflows to compress implementation timelines and shift capital expenditure to operational models.
- Infrastructure as a Service:Raw compute, storage, and networking resources exposed through programmatic interfaces. Indian fintechs under RBI data localization guidelines and Brazilian e-commerce platforms provision domestic IaaS regions to satisfy transaction sovereignty requirements.
- Platform as a Service:Managed runtime environments abstracting infrastructure operations from application development. UK government digital services and South Korean gaming studios leverage these to accelerate deployment velocity without maintaining container orchestration expertise.
- Function as a Service:Event-driven compute executing discrete code fragments in response to triggers. IoT device fleets in Germany and real-time payment processors in the UAE deploy serverless architectures to eliminate idle capacity costs during demand troughs.
Dominating revenue concentration: Software as a Service. Expanding most quickly: Function as a Service.
Use Case:
Functional application categories map directly to buyer departmental budgets and replacement cycle timing, with compliance-critical systems commanding longer sales cycles.
- Customer Relationship Management:Systems managing prospect engagement, sales pipeline, and post-transaction service interactions. US insurance carriers and European telecommunications operators migrate from on-premises Siebel deployments to cloud-native alternatives, triggered by sunsetting support for legacy versions.
- Enterprise Resource Planning:Integrated suites coordinating finance, procurement, and operations across organizational boundaries. German industrial conglomerates and Japanese automotive suppliers pursue SAP S/4HANA cloud transitions to consolidate decades of acquired system fragmentation.
- Human Capital Management:Workforce administration spanning recruitment, compensation, and talent development. Professional services firms in Canada and Australian healthcare networks standardize on these platforms to support hybrid work arrangements and distributed hiring.
- Supply Chain Management:Multi-enterprise coordination of procurement, logistics, and inventory positioning. Retailers in Brazil and pharmaceutical distributors in Switzerland deploy these to satisfy ANVISA and Swissmedic serialization mandates while optimizing working capital.
- Content Management:Repository and workflow systems governing document lifecycle and collaborative authoring. Government agencies in France and educational publishers in the UK select these to meet CNIL archival requirements and accessibility standards.
Capturing largest installed base: Enterprise Resource Planning. Gaining share fastest: Supply Chain Management.
End User:
Vertical industry selection determines regulatory exposure, with financial services and healthcare facing the densest overlapping compliance obligations.
- Banking & Financial Services:Institutions accepting deposits, extending credit, and executing payments under prudential supervision. US regional banks and EU investment firms migrate core banking platforms to SaaS to escape mainframe maintenance burdens while satisfying SEC and EBA operational resilience requirements.
- Telecommunications:Network operators delivering voice, data, and media services under universal service obligations. Operators in India under TRAI guidelines and carriers in Japan modernize billing and customer care systems through cloud transformation programs.
- Government Agencies:Public sector entities procuring under competitive bidding and domestic preference rules. Federal agencies in the US and ministries in Saudi Arabia deploy FedRAMP and SDAIA-compliant cloud environments for citizen service delivery.
- Education:Institutions delivering instruction and research with heterogeneous user populations and seasonal demand patterns. Universities in Ontario and vocational colleges in Australia select consumption-priced collaboration tools to align costs with enrollment fluctuations.
- Manufacturing:Industrial enterprises integrating operational technology with enterprise IT. German machinery builders and South Korean electronics assemblers deploy edge-connected cloud platforms to satisfy METI and KOSHA safety monitoring mandates.
Generating highest absolute spend: Banking & Financial Services. Climbing fastest: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces the dominant share of cloud infrastructure capacity while European and Asian markets absorb specialized compliance-driven deployments. Consumption patterns diverge sharply between financial services migration in North America and healthcare digitization in Western Europe.
United States
Financial services firms in New York and Chicago are offloading legacy mainframe operations to multi-tenant SaaS environments. SEC operational resilience requirements and HIPAA privacy mandates create dual compliance obligations for healthcare cloud deployments. The Boston corridor hosts concentrated demand from biotechnology firms replacing on-premises electronic health record systems.
Germany
Automotive suppliers in Stuttgart and Munich deploy private cloud environments to satisfy CSRD emissions traceability requirements. The EU AI Act imposes risk-classification mandates that force enterprises to rebuild algorithmic workflows on certified infrastructure stacks. Industrial machinery builders in Baden-Württemberg favor hybrid architectures to satisfy operational technology isolation requirements.
United Kingdom
Government digital services in London leverage managed runtime environments to accelerate deployment velocity without maintaining container orchestration expertise. GDPR data-localization provisions shape where infrastructure gets provisioned and how cross-border data flows get engineered. Fintech clusters in Manchester and Edinburgh pilot consumption-based pricing models to align costs with transaction volume fluctuations.
India
Fintechs in Mumbai and Bangalore require domestic transaction processing under RBI data localization guidelines. Local cloud regions under central bank supervision offer captive demand from payment processors and digital lending platforms. The Hyderabad technology corridor expands data center capacity to serve enterprise workload migration from on-premises enterprise resource planning systems.
Japan
Manufacturing firms in Nagoya and Osaka deploy edge-connected cloud platforms to satisfy METI safety monitoring mandates for operational technology integration. Electronics assemblers in the Kansai region favor hybrid cloud deployment to partition sensitive workloads between private infrastructure and public elasticity. Tokyo-based telecommunications operators modernize billing systems through cloud transformation programs.
Cloud Applications Market Key Industry Players
Capital-heavy infrastructure providers compete with asset-light application specialists for enterprise wallet share. Three hyperscalers control the majority of elastic compute capacity, creating tiered dependency structures for downstream software vendors. Strategic archetypes separate into vertical workflow specialists, horizontal platform aggregators, and infrastructure primitives suppliers. Competitive moves concentrate on API ecosystem expansion and consumption-based pricing unbundling.
Within the vertical workflow tier, Salesforce and ServiceNow exemplify specialization strategies that sustain premium positioning through industry-specific compliance architectures. Microsoft Azure and Amazon Web Services anchor the infrastructure primitives segment, with Google Cloud Platform occupying a position focused on data analytics and machine learning workloads. Oracle Cloud Infrastructure represents the enterprise database incumbent archetype, bridging legacy system migration paths to cloud-native deployments.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Azure |
| Amazon Web Services |
| ServiceNow |
| Workday |
| Google Cloud Platform |
| Oracle Cloud Infrastructure |
| Snowflake |
| Databricks |
| Others |
Cost & Logistics Intelligence
Energy costs for hyperscale data centers in Northern Virginia and Frankfurt feed directly into compute pricing tiers, with power purchase agreements for renewable capacity separating premium-certified infrastructure from standard multi-tenant offerings. Cloud buyers in regulated industries absorb these pass-through costs through longer contract terms that lock in capacity allocation.
Pricing Analysis
Margin tightening in standard public cloud tiers reflects hyperscaler competition for enterprise workload retention, while private cloud deployments command sustained premiums through HIPAA and EU AI Act compliance bundling. Consumption-based SaaS licensing stratifies across premium, standard, and economy levels based on API call volume and support response SLAs. Pricing pressure intensifies in mid-market CRM and ERP segments as Workday and Salesforce introduce modular unbundling. Financial services buyers demonstrate lowest price sensitivity due to operational resilience mandates, while education and nonprofit segments negotiate steepest discounts.
Supply Chain Analysis
Specialized cloud engineering talent scarcity in Bangalore and Dublin constrains delivery capacity for customized hybrid deployments, forcing vendors to redistribute implementation workloads across lower-cost Polish and Portuguese delivery centers. Semiconductor supply for AI training clusters draws from Taiwan and South Korea, with memory module sourcing anchored in Chinese packaging facilities. Single-source vulnerability in GPU accelerator supply creates allocation bottlenecks for generative AI inference workloads. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and hyperscaler marketplaces for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compliance engineering capacity acts as the binding constraint propping pricing power for infrastructure providers, with EU AI Act implementation timelines outstripping available architect supply.
For Market Incumbents: Anticipate margin compression in undifferentiated compute tiers as Google Cloud Platform and Oracle Cloud Infrastructure compete on price for workload retention. Defend positioning through vertical specialization in healthcare and financial services workflows where FDA and EBA certification requirements create switching costs. Prioritize backward integration into sovereign cloud regions under RBI and METI localization mandates to preempt regulatory displacement. For New Entrants and Emerging Players: Cloud-native security tooling delivered through hyperscaler marketplaces offers the most penetrable entry vector, with mid-market enterprises seeking alternatives to native IAM and observability stacks. Target Brazilian fintechs and Indian NBFCs requiring ANVISA and RBI-compliant infrastructure without legacy mainframe migration complexity. Lead with consumption-priced serverless architectures that eliminate minimum commitment friction for seasonal workload patterns. For Investors and Strategic Acquirers: EU AI Act risk-classification deadline acceleration is the leading indicator that compliance-automation tooling valuations will detach from underlying infrastructure multiples. Position for five-to-ten year holding periods around vertical SaaS vendors with embedded regulatory workflow logic. Monitor FDA software-as-medical-device submission volumes as the signal for healthcare cloud infrastructure demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical SaaS Specialization | Healthcare and financial services compliance architectures sustain premium positioning against horizontal competitors. |
| Sovereign Cloud Region Expansion | RBI and METI data localization requirements create captive demand for domestic infrastructure provisioning. |
| Generative AI API Integration | Embedding LLM inference into CRM and ERP workflows unlocks new pricing tiers for knowledge-worker automation. |
| Kubernetes-Native Service Mesh Deployment | Singapore and London financial services firms consolidate control plane functions for payment processing workloads. |
| Consumption-Based Pricing Unbundling | Ontario healthcare providers align clinical workflow costs with patient volume fluctuations through variable structures. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with cloud platform engineers, enterprise IT procurement officers, compliance architects, and channel integration specialists. SEC 10-K infrastructure capex disclosures, hyperscaler earnings call transcripts, EU AI Act implementation guidance, and hospital GPO contract databases provided demand-side validation. Bottom-up workload migration estimates triangulated against top-down cloud spending surveys across the analysis window.
Data-stream reconciliation between deployment model adoption curves and end-user vertical spending patterns shaped the analytical framework, with segmentation modeled across public, private, hybrid, and community cloud architectures by solution layer and geographic regulatory cluster. CAGRs derived from elasticity-adjusted capacity expansion rates and pricing trajectory assumptions, incorporating AI inference demand inflections and sustainability reporting mandate compliance costs as industry-specific inputs throughout the forecast period.
The model holds under stable regulatory implementation timelines; deviation in EU AI Act enforcement intensity or FDA software-as-medical-device pathway acceleration would shift workload migration velocity assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Telecom Cloud Market