
 India Alcohol E-Commerce Market | 2026-2036
India Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
India Alcohol E-Commerce Market Insights
Market Context
Maharashtra's distillery licensing reform is restructuring how alcohol flows into digital channels across western India. Diageo plc leverages its premium spirits portfolio to dominate tier-one city deliveries, while Pernod Ricard SA anchors its position through controlled distribution partnerships with licensed retailers. Uber Technologies Inc. competes aggressively by integrating alcohol delivery into its existing mobility infrastructure, reducing customer acquisition costs.
Technical Definition and Segment Structure
India Alcohol E-Commerce denotes the digital sale and fulfillment of alcoholic beverages through web platforms and mobile applications, requiring real-time age verification, excise stamp tracking, and temperature-controlled last-mile logistics to comply with state-specific prohibition and taxation regimes. The distribution channel dimension reveals structural tension: online retailers and mobile apps capture volume leadership in metro markets, while direct-to-consumer models concentrate margin pools in premium wine and craft spirits where subscription services lock in repeat purchase behavior. Spirits leads product type demand due to higher per-unit economics and established brand recognition, though beer shows faster velocity in on-demand delivery modes during sports and entertainment occasions.
Regulatory Framework and Outlook
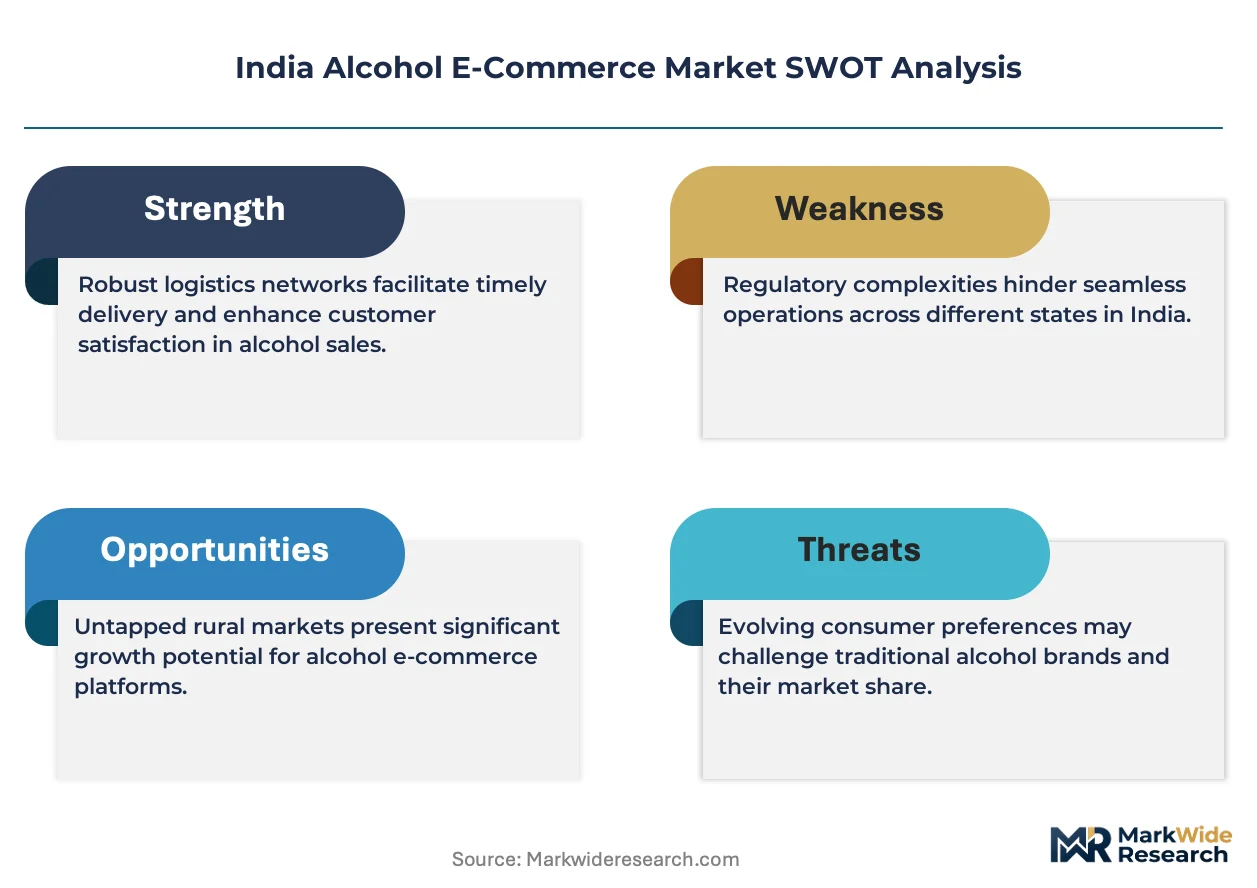
FSSAI labeling mandates, state excise departments in Maharashtra and Karnataka, and BIS packaging standards collectively determine market access granularity, with each state enforcing distinct delivery time windows, dry-day prohibitions, and permit requirements that fragment operational scalability. CDSCO oversight intersects where alcohol-adjacent wellness or medicated products enter digital channels. Stakeholders must monitor pending state excise digitization proposals and emerging judicial interpretations of inter-state alcohol commerce to anticipate where platform economics will next unlock.
Market Dynamics
State excise digitization in Maharashtra and Karnataka is dismantling the fragmented permit system that historically constrained platform scale, forcing operators to rebuild logistics around real-time excise stamp verification and geo-fenced delivery zones.
Growth Catalysts
- FSSAI Digital Compliance:Centralized labeling and traceability mandates are reducing state-by-state operational friction for multi-state platforms.
- Urban Millennial Concentration:Bengaluru, Mumbai, and Delhi generate disproportionate order velocity through mobile-first purchasing behavior.
- On-Demand Infrastructure:Temperature-controlled last-mile networks originally built for food delivery are repurposing capacity for alcohol fulfillment.
Market Restraints
- State-Level Excise Fragmentation:Maharashtra, Karnataka, and Telangana enforce incompatible delivery time windows and dry-day calendars that prevent standardized national operations.
- Permit Capital Intensity:State-specific retailer licensing requirements tie up working capital in inventory held across dozens of jurisdictional pools.
- Inter-State Commerce Prohibition:Judicial interpretations of alcohol as a state subject under the Constitution block centralized warehousing economics.
Strategic Opportunities
- Tier-Two City Expansion:Hyderabad and Pune present underpenetrated demand pools where premium spirits subscription models can establish first-mover positioning.
- Craft Spirits Curation:Direct-to-consumer channels bypass retailer markup constraints for small-batch producers seeking margin recovery.
- PLI-Aligned Logistics Investment:Domestic cold-chain incentives support capex deployment for compliant storage infrastructure.
Industry Challenges
- Age Verification Engineering:Real-time identity authentication at scale requires integration with state electoral databases that lack API standardization.
- Excise Stamp Reconciliation:Physical tax stamp tracking across thousands of daily transactions creates audit trail complexity.
Report Scope
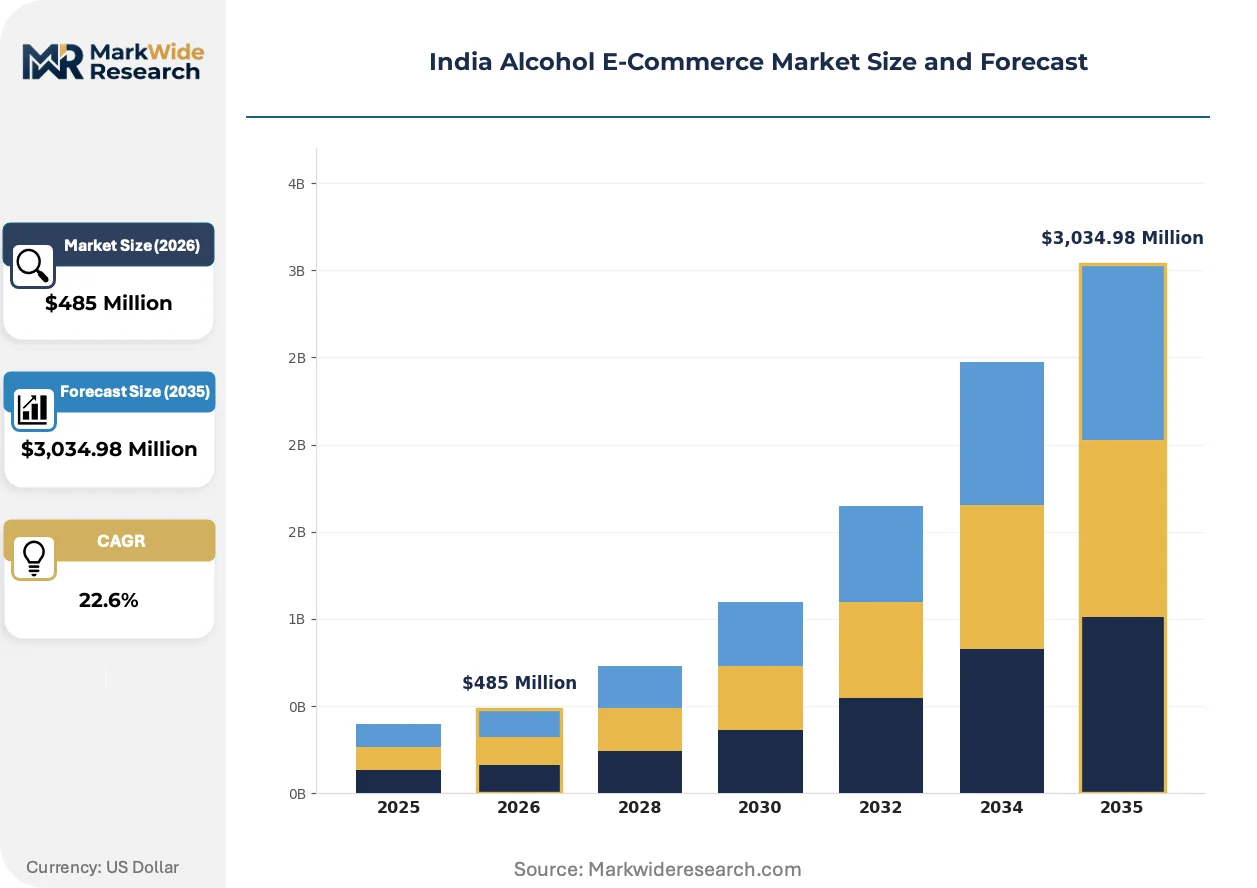
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Alcohol E-Commerce Market |
| Market Size in 2026 | $485 Million |
| Market Size in 2035 | $3,034.98 Million |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Distribution Channel: Online Retailers, Mobile Apps, Direct-to-Consumer, Delivery Services Customer Type: Millennials, Gen Z, Professionals, Casual Consumers Delivery Mode: Scheduled Delivery, On-Demand Delivery, Subscription Services, Pickup |
| Companies Covered | Diageo plc, Costco Wholesale Corporation, Uber Technologies Inc., Total Wine and More, Drizly, Anheuser-Busch InBev SA/NV, Pernod Ricard SA, Naked Wines plc, Heineken N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Alcohol E-Commerce Market Trends and Innovations
Platform operators are racing to embed regulatory compliance into core infrastructure rather than treating it as a post-hoc overlay, reshaping how technology investments get prioritized and measured.
Blockchain-based excise stamp tracking is consolidating supply chain transparency into immutable ledgers accessible to state excise departments in Maharashtra and Karnataka. Diageo and Pernod Ricard are piloting integrated verification systems that reduce manual reconciliation overhead. This consolidation is compressing the compliance cost gap between national platforms and regional specialists.
FSSAI's digital labeling mandate is forcing reformulation of packaging workflows to accommodate QR-code traceability and multilingual ingredient disclosure. Smaller craft producers face disproportionate adaptation costs relative to volume. Premium wine imports are experiencing the steepest compliance timeline extensions as BIS packaging standards intersect with FSSAI requirements.
Subscription-based replenishment is displacing occasion-driven purchasing in metropolitan markets, locking in predictable demand patterns that optimize inventory positioning. Tier-one city consumers are migrating from on-demand impulse buying to curated monthly deliveries. Bengaluru exhibits the fastest adoption velocity for spirits subscription services among Indian metros.
India Alcohol E-Commerce Market Segmentation
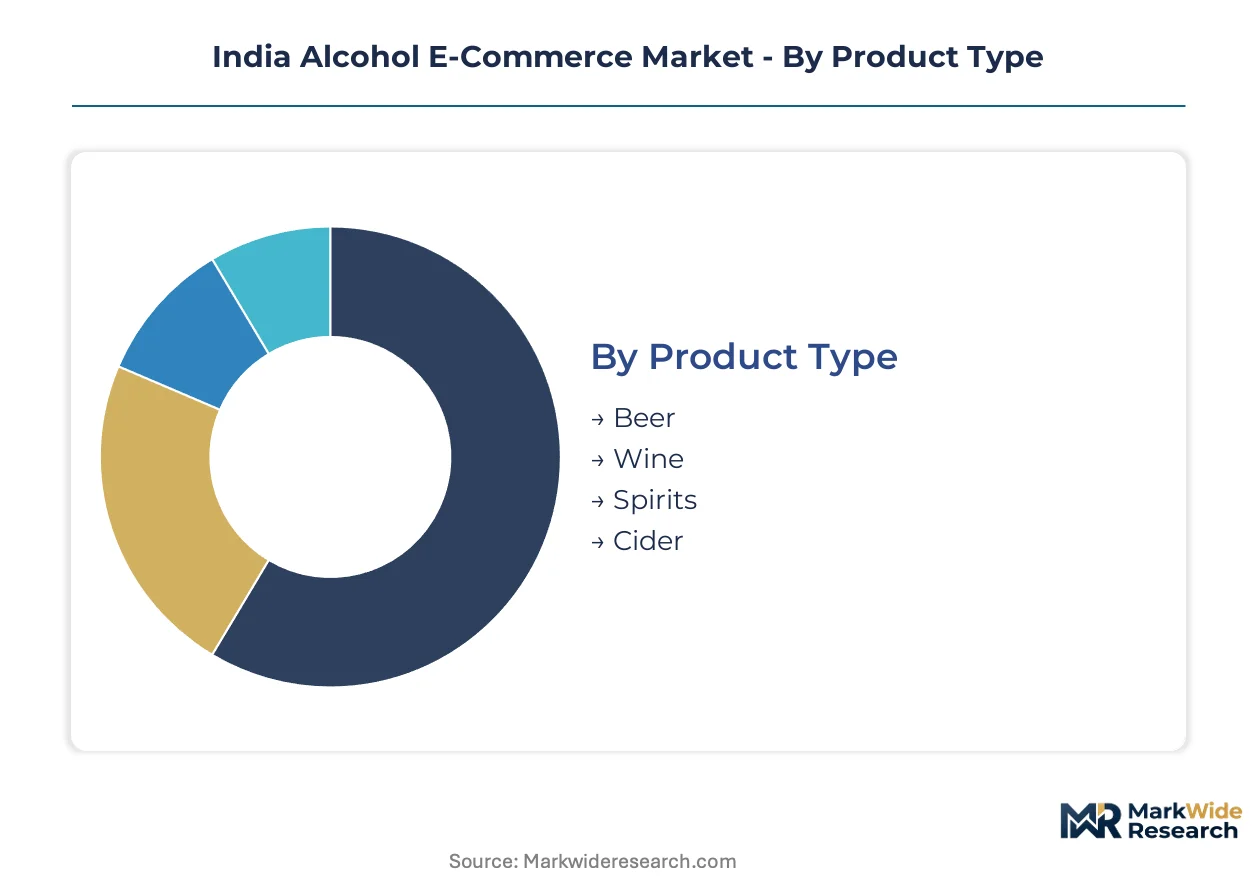
Segmentation in India's alcohol e-commerce market exposes how regulatory fragmentation and urban consumption patterns create divergent growth trajectories across product, channel, and customer dimensions. State-level excise variations force platforms to architect entirely separate operational stacks for each geography, making segment-specific strategy execution critical to capital deployment efficiency.
Product Type:
Standardization dominates mass-market beer and spirits, while wine and craft offerings demand curated sourcing and temperature-controlled handling that fragments fulfillment economics.
- Beer:High-velocity, low-margin SKUs drive on-demand delivery volume in Mumbai and Bengaluru during sports and entertainment occasions. Maharashtra's excise digitization enables real-time inventory tracking that reduces stockout rates for mainstream lager brands.
- Spirits:Premium whiskey and vodka generate disproportionate revenue per transaction through mobile app channels. Delhi's affluent consumer base concentrates demand for imported labels requiring FSSAI-compliant labeling and BIS packaging adherence.
- Wine:Temperature-sensitive fulfillment necessitates dedicated cold-chain infrastructure that elevates per-unit logistics costs.
- Cider:Emerging category with limited domestic production, dependent on import licensing through DGFT channels.
Leading the category by volume: Beer. Expanding most quickly: Wine through subscription curation models.
Distribution Channel:
Channel selection determines capital intensity, with asset-light marketplace models competing against inventory-heavy direct ownership structures for margin capture.
- Online Retailers:Aggregator platforms aggregate licensed retailer inventory into unified catalogs, earning commission on transactions without excise stamp liability. Karnataka's retailer density supports this model in Bengaluru, though dry-day synchronization across jurisdictions creates operational complexity.
- Mobile Apps:Uber and specialized alcohol delivery apps dominate order velocity through push notification-driven impulse purchasing. Real-time age verification integration with state electoral databases remains the primary technical barrier to scale.
- Direct-to-Consumer:Craft spirits producers bypass retailer markups through owned channels, capturing margin recovery at the cost of customer acquisition spend.
- Delivery Services:Third-party logistics providers repurpose food delivery infrastructure for alcohol fulfillment, leveraging existing temperature-controlled fleets.
Dominant by transaction volume: Mobile Apps. Steepest expansion trajectory: Direct-to-Consumer for premium craft segments.
Customer Type:
Generational and occupational segments exhibit divergent platform loyalty, with subscription stickiness concentrated among time-constrained professional cohorts.
- Millennials:Bengaluru's tech workforce drives subscription service adoption for curated monthly spirits deliveries, prioritizing convenience over price sensitivity.
- Gen Z:Mobile-native purchasing behavior favors on-demand delivery apps with gamified loyalty programs and social sharing features.
- Professionals:Hyderabad's corporate clusters generate predictable weekday evening order patterns that optimize inventory positioning for scheduled delivery slots.
- Casual Consumers:Occasion-driven purchasing concentrates around festivals and sporting events, creating demand spikes that strain last-mile capacity.
Highest lifetime value concentration: Professionals. Gaining share fastest: Gen Z through influencer-driven app downloads.
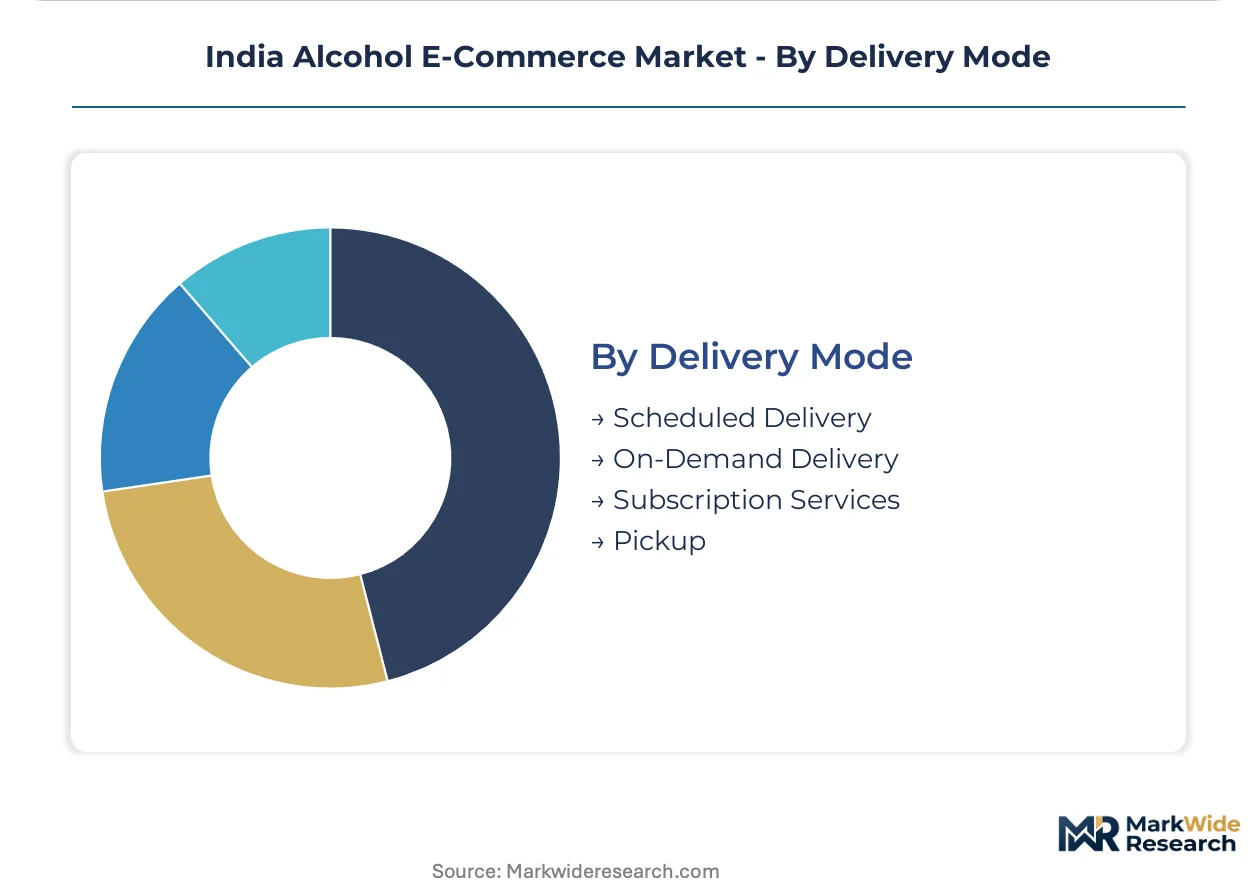
Delivery Mode:
Fulfillment timing preferences segment customers by planning horizon, with subscription models capturing predictable demand that reduces working capital volatility.
- Scheduled Delivery:Pre-booked slots enable route optimization and inventory pre-positioning that compresses per-delivery logistics costs.
- On-Demand Delivery:Mumbai's dense urban core supports sub-30-minute fulfillment through dark store networks, though Telangana's restricted delivery windows constrain operational hours.
- Subscription Services:Monthly replenishment locks in recurring revenue that justifies customer acquisition investment for premium spirits platforms.
- Pickup:Licensed retailer counter collection appeals to price-sensitive segments avoiding delivery fees, particularly in Pune's suburban markets.
Capturing majority volume: On-Demand Delivery. Climbing the fastest: Subscription Services in tier-one metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's distillery licensing reform anchors western India's alcohol digitization, while Karnataka's excise modernization and Telangana's delivery window restrictions create divergent operational templates across the peninsula.
Maharashtra
Mumbai's affluent consumer base drives premium spirits demand through mobile app channels with sub-30-minute fulfillment expectations. The state's excise digitization dismantles fragmented permit systems, enabling real-time stamp verification. Pune's suburban markets sustain pickup-oriented purchasing patterns that reduce last-mile logistics costs for price-sensitive segments.
Karnataka
Bengaluru's tech workforce concentrates subscription service adoption for curated monthly spirits deliveries, generating predictable demand patterns. FSSAI digital compliance frameworks reduce operational friction for multi-state platforms operating across jurisdictional boundaries. The city's retailer density supports aggregator marketplace models, though dry-day synchronization creates inventory planning complexity.
Telangana
Hyderabad's corporate clusters generate weekday evening order velocity that optimizes scheduled delivery slot utilization. Restricted delivery windows constrain on-demand operational hours, forcing platforms to concentrate fulfillment capacity into narrower time bands. The state's excise department enforces geo-fenced delivery zones that fragment route optimization algorithms.
Delhi-NCR
The National Capital Territory's affluent residential pockets concentrate imported label demand requiring BIS packaging adherence and FSSAI-compliant multilingual labeling. Delhi's excise framework permits controlled retail partnerships that limit direct platform ownership structures. Gurgaon's dense commercial corridors sustain corporate gifting segments with higher per-transaction values.
Tamil Nadu
Chennai's emerging urban millennial cohort exhibits accelerating mobile-first purchasing behavior for beer and mainstream spirits categories. State-level prohibition enforcement creates intermittent supply disruptions that strain inventory positioning strategies. The region's underpenetrated subscription service penetration presents first-mover positioning opportunities for curated craft spirits platforms.
India Alcohol E-Commerce Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure, with premium spirits conglomerates leveraging brand portfolios against technology platforms repurposing mobility networks. The market structure exhibits tiered consolidation: multinational beverage houses anchor premium-tier supply, specialized delivery apps capture on-demand volume, and licensed retailer aggregators aggregate fragmented inventory pools. Three archetypes dominate: brand-owning multinationals, technology-integrated logistics platforms, and curated direct-to-consumer specialists. Competitive moves concentrate on strategic partnerships with state-licensed retailers and portfolio diversification into craft and import categories.
Within the multinational beverage tier, Diageo plc and Pernod Ricard SA exemplify brand-architecture dominance through controlled distribution partnerships. Uber Technologies Inc. occupies a distinct position, integrating alcohol delivery into existing mobility infrastructure to compress customer acquisition economics. These three entities represent contrasting strategic anchors: heritage brand equity, technology-platform leverage, and hybrid operational scale.
| Leading Market Players |
|---|
| Diageo plc |
| Costco Wholesale Corporation |
| Uber Technologies Inc. |
| Total Wine and More |
| Drizly |
| Anheuser-Busch InBev SA/NV |
| Pernod Ricard SA |
| Naked Wines plc |
| Heineken N.V. |
| Others |
Pricing and Supply Chain Analysis
Premium-spirits-versus-mass-beer bifurcation drives divergent margin structures across India's alcohol e-commerce landscape, with subscription bundling and per-unit transactional models reflecting fundamentally different supply chain configurations. FSSAI digital compliance costs concentrate in premium tiers where BIS packaging standards and multilingual labeling requirements elevate per-SKU handling expenses, while mass-market beer flows through repurposed food-delivery infrastructure with minimal value-added services.
Pricing Analysis
Warranty and service bundling separates subscription-based premium spirits from unbundled on-demand beer transactions, with monthly replenishment models incorporating curated selection and temperature-controlled handling into fixed fees. Three-tier pricing structure across premium, standard, and economy levels reflects brand equity, import licensing costs, and delivery speed guarantees. Cost compression in mass-market beer is intensifying because aggregator platforms compete for volume share through subsidized delivery. Casual consumers in suburban Pune exhibit highest price sensitivity, while Bengaluru tech professionals demonstrate lowest elasticity for subscription services.
Supply Chain Analysis
FSSAI certification and state excise licensing gate market access, forcing platforms to maintain parallel inventory pools across Maharashtra, Karnataka, and Telangana with distinct compliance documentation. Geographic supply concentration centers on domestic distillery clusters in Maharashtra and Punjab, supplemented by import channels through Mumbai and Chennai ports. Raw material dependencies include glass packaging from Gujarat, excise stamps from state security printers, and cold-chain equipment from domestic PLI-aligned manufacturers. Single-source vulnerability runs through state excise department stamp issuance systems. Distribution runs through licensed retailer aggregators in metro markets and direct-to-consumer channels for craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's alcohol e-commerce market functions as a cost-of-compliance story where FSSAI digital labeling mandates and state excise stamp verification systems create barrier-to-entry moats favoring capitalized national platforms over regional specialists.
For Market Incumbents: Cement market position by deepening controlled distribution partnerships with licensed retailers in Maharashtra and Karnataka, while investing in blockchain-based excise stamp reconciliation systems that reduce audit overhead. Threat from Uber's mobility-integrated delivery model demands response through exclusive inventory agreements with premium spirits portfolios. Vertical integration into temperature-controlled dark store networks in Mumbai and Bengaluru represents the critical capacity lever for sub-30-minute fulfillment guarantees. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Chennai's underpenetrated urban millennial cohort, where subscription service adoption lags Bengaluru by significant margin. White-space opportunity concentrates in craft spirits curation for Hyderabad's corporate professionals seeking differentiated monthly offerings. Go-to-market angle should emphasize FSSAI-compliant import curation for wine categories where compliance timeline extensions disadvantage established mass-market platforms. For Investors and Strategic Acquirers: Re-rating potential sits with aggregator platforms possessing multi-state license coverage given pending excise digitization proposals in additional states. Long-term viability over the next decade hinges on regulatory adaptation capacity rather than pure technology scale. Acquisition target archetype: regional specialists with deep state-level retailer relationships in tier-two markets. Signal to watch is judicial interpretation momentum on inter-state alcohol commerce under Article 301 of the Constitution.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Excise Stamp Integration | Immutable ledger verification reduces Maharashtra and Karnataka excise department reconciliation overhead for national platforms. |
| Tier-Two City Dark Store Network | Hyderabad and Pune fulfillment infrastructure captures underpenetrated demand pools ahead of competitor saturation. |
| Craft Spirits Subscription Curation | Direct-to-consumer margin recovery bypasses retailer markup constraints for small-batch producers in Bengaluru. |
| State Excise API Standardization | Real-time age verification integration with electoral databases unlocks scalable mobile app deployment across jurisdictions. |
| Temperature-Controlled Fleet Expansion | PLI-aligned logistics investment supports compliant storage infrastructure for wine and premium spirits categories. |
Research Methodology
Multi-period observation of state excise digitization milestones, FSSAI compliance timeline extensions, and mobile app download velocity anchored the trend analysis, supplemented by interviews with platform operations executives, state excise department officials, licensed retailer consortium representatives, and cold-chain logistics providers. Secondary validation drew from FSSAI regulatory filings, state excise department policy circulars, BIS packaging standard updates, and PLI scheme disbursement records. Bottom-up transaction volume modeling and top-down addressable market sizing were triangulated against primary field observations.
Segment-weighting across product type, distribution channel, customer archetype, and delivery mode dimensions informed value allocation throughout the forecast period. Spirits, beer, wine, and cider categories were modeled separately given divergent fulfillment economics. CAGR derivation incorporated state-level adoption curve differential, excise liberalization probability assessment, and infrastructure investment lag effects. Forecast inputs included mobile penetration rates in tier-one and tier-two urban clusters and subscription service churn benchmarks from comparable emerging markets.
State excise policy reversals, judicial blockage of inter-state commerce liberalization, and cold-chain infrastructure cost inflation are the dominant revision risks warranting model sensitivity testing. A model refresh is warranted upon material change in FSSAI digital labeling mandate enforcement timelines or substantial state excise department API standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce in Nigeria Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market