
 Scientific Data Management System Market | 2026-2036
Scientific Data Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Scientific Data Management System Market Intelligence
Revenue from cloud-based subscription services is reshaping competitive positioning among vendors. Thermo Fisher Scientific leverages its extensive installed base in life sciences laboratories to drive system adoption. TIBCO Software specializes in data integration and analytics, offering powerful tools for complex research datasets. LabVantage Solutions differentiates with purpose-built laboratory informatics solutions designed specifically for regulated industries.
A scientific data management system is a software platform designed to handle large, heterogeneous datasets generated during research and development. These systems ensure data integrity and provenance by tracking every modification from acquisition to archival. Cloud-based deployment models are outpacing on-premises solutions due to scalability and accessibility for collaborative projects. Within solution types, data analysis and visualization tools command higher value, particularly in the life sciences application area where complex biological data requires sophisticated interpretation.
Regulatory frameworks are a primary driver of system design and feature sets. The FDA's 21 CFR Part 11 in the United States and the EU's GDPR mandate stringent controls on electronic records, data security, and audit trails. Compliance with these standards is a non-negotiable requirement for systems used in regulated GxP environments. Vendors must now focus on building platforms that are not only compliant but also interoperable with emerging AI-driven analytical tools.
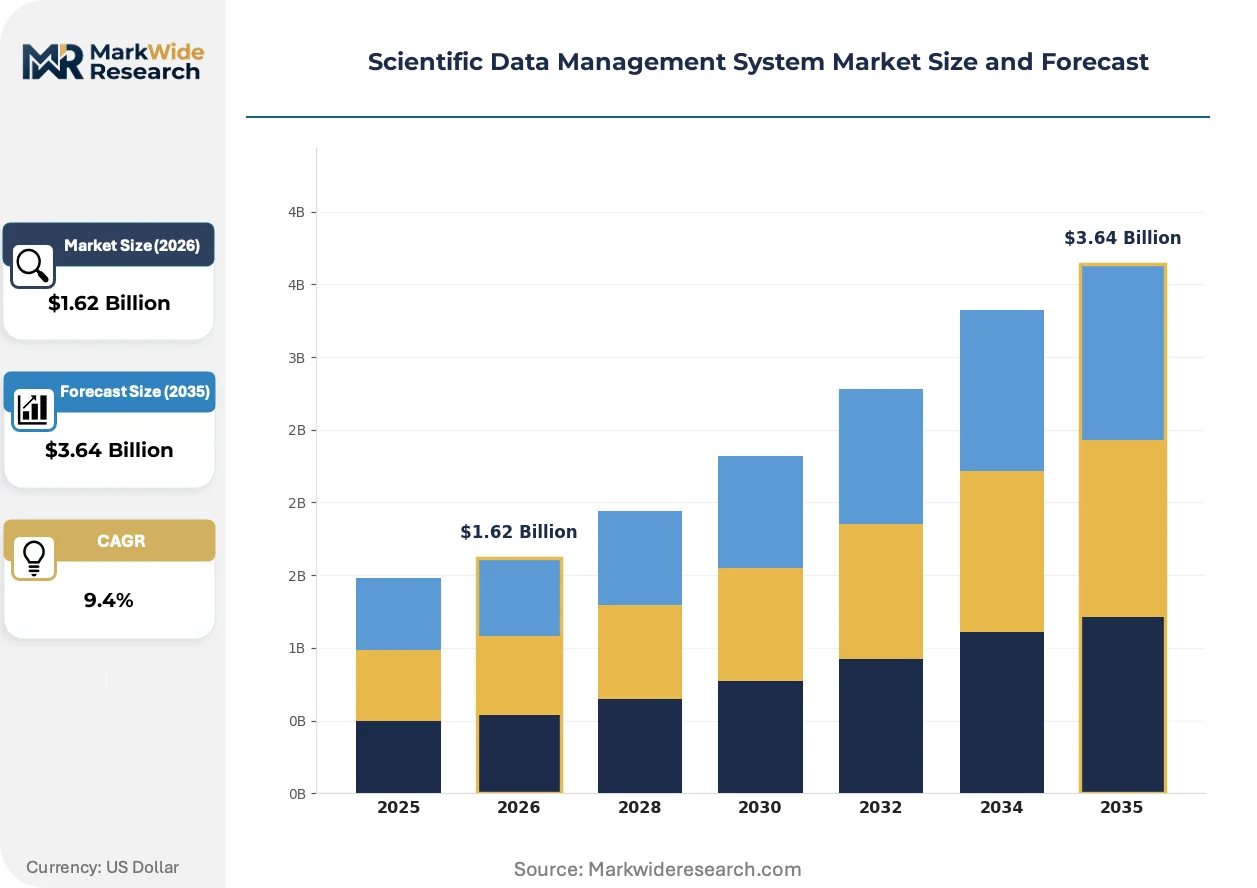
Market Dynamics
The convergence of massive data generation in life sciences with stringent global data integrity mandates, such as the FDA's 21 CFR Part 11 and Europe's GDPR, represents the central force defining the market, pushing organizations toward specialized management platforms.
Growth Catalysts
- Regulatory Compliance:Mandates like the FDA's 21 CFR Part 11 require pharmaceutical companies to maintain secure, time-stamped audit trails for all electronic records, making compliant scientific data management systems an essential investment for clinical trial data integrity and drug approval submissions.
- AI and Machine Learning Adoption:The integration of artificial intelligence into drug discovery and materials science research requires vast quantities of high-quality, structured, and annotated data, compelling research organizations to adopt sophisticated systems that can prepare datasets for algorithmic analysis.
- Genomics and Proteomics Expansion:Rapid advancements in high-throughput sequencing and mass spectrometry generate petabyte-scale datasets that are impossible to manage with traditional file systems, creating specific demand from genomics and proteomics laboratories for scalable, specialized data management solutions.
Market Restraints
- High Implementation Cost:The significant upfront investment required for software licensing, hardware infrastructure, system validation, and personnel training for a GxP-compliant system presents a substantial barrier for smaller academic institutions, startups, and laboratories in emerging economies.
- Data Format Heterogeneity:Scientific instruments from different manufacturers often produce data in proprietary and disparate formats, creating immense technical challenges and costs associated with integrating these diverse data streams into a single, unified management platform. * Legacy System Inertia: Many established laboratories have deeply entrenched, decades-old data management practices and legacy systems, such as paper notebooks or basic LIMS, creating significant organizational resistance and migration complexity that slows the adoption of modern platforms.
Strategic Opportunities
- Emerging Biotech Hubs:Underpenetrated markets in countries like India and Brazil are building out their biotechnology and pharmaceutical research infrastructure, creating new growth opportunities for vendors offering scalable, cost-effective cloud-based solutions tailored to the needs of these developing research ecosystems.
- Expansion into Adjacent Verticals:Data-intensive research in adjacent fields, such as agricultural science for crop development, food and beverage for quality control, and materials science for new polymer discovery, presents a significant opportunity for vendors to adapt their platforms for these applications.
- IoT-Enabled Lab Automation:The convergence of SDMS with Internet of Things sensors on laboratory equipment enables fully automated data capture, real-time monitoring of experiments, and predictive maintenance alerts, offering a new value proposition centered on laboratory efficiency and data quality.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals with hybrid expertise in a specific scientific domain, data science, and IT systems administration creates a bottleneck for implementing, managing, and extracting value from advanced scientific data management platforms.
- Interoperability with LIMS and ELN:Ensuring seamless, bidirectional data flow between a new scientific data management system and a laboratory's existing information management systems (LIMS) and electronic lab notebooks (ELN) is a complex and resource-intensive integration challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scientific Data Management System Market |
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Type: Data Storage, Data Integration, Data Analysis, Visualization, Metadata Management Application Area: Life Sciences, Environmental Studies, Astronomy, Social Sciences, Material Research End User Segment: Research Institutes, Educational Organizations, Government Agencies, Pharmaceutical Corporations, Tech Innovators |
| Companies Covered | Thermo Fisher Scientific, Abbott Laboratories, TIBCO Software, LabVantage Solutions, Merck KGaA, Shimadzu Corporation, Accelerated Technology Laboratories, SciCord, Scispot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scientific Data Management System Market Strategic Shifts & Innovations
Automation of data pipelines and the push for AI-readiness are transforming scientific data management from a passive archival function into an active component of the research and development value chain. This evolution prioritizes data interoperability and accessibility for advanced analytics.
FAIR data principles architecturally embed findability, accessibility, interoperability, and reusability into modern platforms. Pharmaceutical and biotechnology firms are the primary adopters, seeking to accelerate drug discovery timelines and improve research reproducibility. This focus is hybridizing the role of data management, blending its traditional archival function with active, analysis-ready data preparation capabilities required for machine learning applications.
The European Union's General Data Protection Regulation (GDPR) imposes strict controls on personal data within research, including clinical trial information. This regulation forces platform vendors to engineer privacy-by-design features like advanced anonymization and granular access controls. The life sciences sector is most affected, now demanding GDPR-compliant solutions even for research conducted outside the EU to ensure global data portability.
A decisive shift away from perpetual software licenses toward cloud-based subscription services is altering vendor revenue models. This subscription approach displaces the traditional on-premises deployment, which required large upfront capital expenditure and dedicated IT resources. This trend is most visible in academic research and startup biotech firms in the United States and Europe, which prefer the operational expenditure model.
Scientific Data Management System Market Segmentation
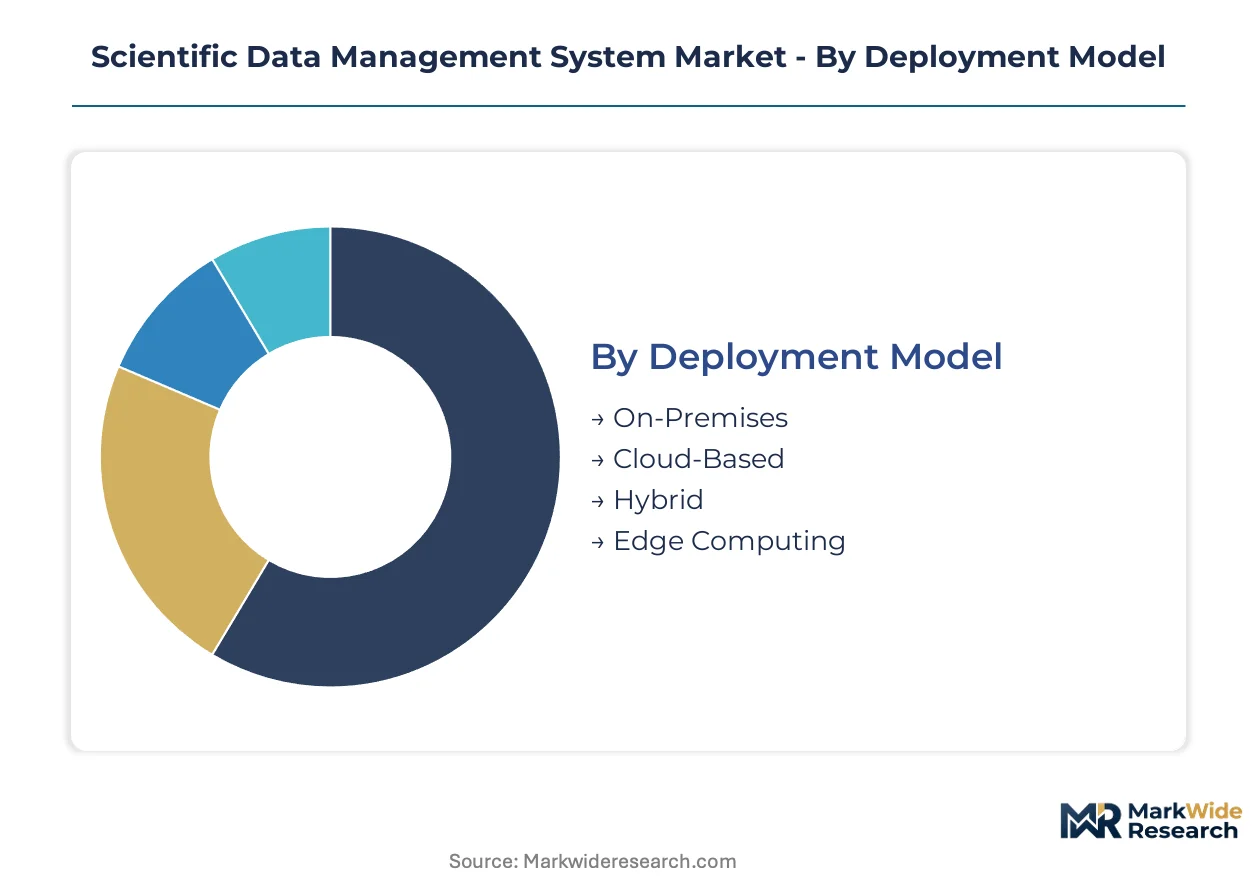
Understanding the segmentation within the scientific data management system market is critical for identifying distinct user requirements, technological preferences, and regulatory compliance needs. Each segment represents unique challenges and opportunities for vendors aiming to deliver specialized solutions across the research and development landscape.
Deployment Model:
The deployment model for scientific data management systems significantly influences the long-term service and support requirements, with cloud-based solutions often requiring less direct client-side IT maintenance.
- On-Premises:Software and hardware are installed and managed within the user's own data center, providing full control over data security and customization. Pharmaceutical corporations in Germany and Japan often prefer this model for highly sensitive GxP-regulated data.
- Cloud-Based:These systems leverage remote servers and internet delivery, offering scalability and accessibility without local infrastructure. Demand is concentrating in academic research and biotech startups in the United States and Europe, driven by operational expenditure preferences.
- Hybrid:This model combines elements of both on-premises and cloud deployments, allowing organizations to maintain sensitive data locally while leveraging cloud flexibility for other workloads.
- Edge Computing:Data processing occurs closer to the data source, such as laboratory instruments, reducing latency and bandwidth usage for real-time scientific data capture.
On-Premises holds the largest share; momentum sits with Cloud-Based.
Solution Type:
The specific solution type reflects the primary functional objective within the scientific data lifecycle, ranging from raw data capture to advanced analytical insights.
- Data Analysis:These tools provide capabilities for statistical processing, pattern recognition, and quantitative interpretation of complex scientific datasets. Life sciences applications in countries like the United States and Switzerland value sophisticated analysis for drug discovery.
- Visualization:This involves graphical representation of data, enabling researchers to identify trends, outliers, and relationships more intuitively. Genomics and proteomics laboratories in the UK and Canada rely on advanced visualization for interpreting high-throughput sequencing results.
- Data Storage:Platforms designed for secure, scalable, and long-term archival of heterogeneous scientific data, ensuring data integrity and provenance.
- Data Integration:Solutions focused on connecting disparate data sources and formats, enabling a unified view and seamless data flow across laboratory systems.
- Metadata Management:Tools for defining, capturing, and managing descriptive information about scientific data, crucial for findability and reusability under FAIR principles.
Data Analysis and Visualization tools collectively offer the highest value proposition due to their direct impact on research outcomes.
Application Area:
Each application area requires tailored scientific data management functionalities, reflecting the unique data types and regulatory landscapes prevalent in that field.
- Life Sciences:This area encompasses pharmaceutical development, biotechnology, and clinical research, generating vast and complex biological data. Stricter data integrity requirements from the FDA and EMA drive demand for compliant systems in this sector.
- Material Research:Focuses on the discovery and characterization of new materials, involving diverse data from spectroscopy, microscopy, and simulations. Researchers in Germany and South Korea increasingly adopt SDMS for managing complex experimental data in this field.
- Environmental Studies:Involves collecting and analyzing data related to ecological systems, climate, and pollution, often requiring robust spatial and temporal data handling.
- Astronomy:Deals with petabyte-scale datasets from telescopes and observatories, necessitating highly scalable storage and analysis capabilities for cosmic phenomena.
- Social Sciences:Manages qualitative and quantitative data from surveys, experiments, and observations, requiring secure handling of sensitive personal information.
Life Sciences currently dominates demand, while Material Research shows significant growth potential as an adjacent vertical.
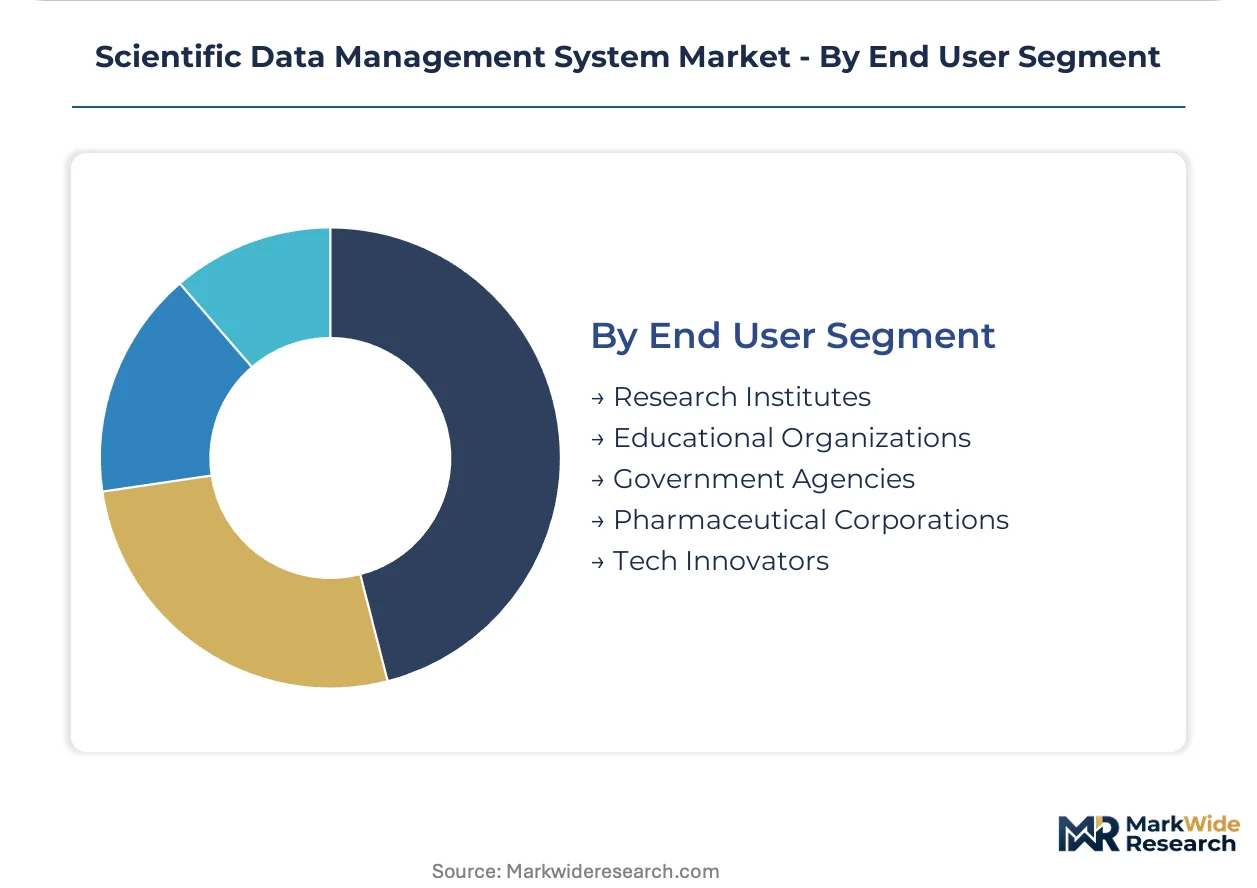
End User Segment:
The end-user segment often dictates the scale of investment and the specific compliance needs for scientific data management systems.
- Pharmaceutical Corporations:These entities require highly regulated and validated systems to manage clinical trial data, R&D results, and comply with standards like FDA 21 CFR Part 11. Demand from major pharmaceutical companies in the United States and Switzerland accelerates market expansion.
- Research Institutes:Academic and private research organizations generate diverse scientific data across multiple disciplines, seeking flexible and scalable solutions for collaborative projects. Institutions in the UK and Canada are significant adopters.
- Educational Organizations:Universities and colleges utilize SDMS for teaching and academic research, often prioritizing cost-effectiveness and ease of use for student access.
- Government Agencies:Public sector bodies involved in scientific research, public health, or environmental monitoring require secure and auditable data management platforms.
- Tech Innovators:Emerging technology companies, particularly in biotech and AI, adopt advanced SDMS for managing proprietary research data and integrating with novel analytical tools.
Pharmaceutical Corporations exert the strongest influence on system design due to their stringent regulatory requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for scientific data management systems vary significantly across geographies, with some regions prioritizing on-premises control while others embrace cloud-based flexibility. Research-intensive economies in North America and Europe drive demand for sophisticated analytical tools, while emerging markets focus on scalable, cost-effective solutions. This divergence shapes vendor strategies for localized product offerings and deployment models.
United States
Pharmaceutical corporations and biotech startups in the United States require robust systems for managing extensive clinical trial data. The FDA's 21 CFR Part 11 mandates stringent electronic record-keeping, making compliant SDMS an essential investment. Major research hubs like Boston and San Francisco actively adopt advanced data analysis and visualization tools for drug discovery.
Germany
German pharmaceutical corporations and material research institutions often prefer on-premises scientific data management systems for highly sensitive GxP-regulated data. Strict adherence to data privacy regulations, including GDPR, influences system design and data handling protocols. The Fraunhofer-Gesellschaft institutes and major automotive R&D centers in Bavaria utilize these platforms for complex experimental data.
India
India's emerging biotechnology and pharmaceutical research infrastructure generates demand for scalable, cost-effective cloud-based scientific data management solutions. The country's national pharmaceutical regulator, CDSCO, increasingly emphasizes data integrity in drug development. Research parks in Hyderabad and Bengaluru are becoming significant adopters of these modern platforms.
United Kingdom
Academic research institutes and genomics laboratories in the United Kingdom demand flexible and scalable scientific data management systems for collaborative projects. Compliance with the UK's data protection regulations, mirroring GDPR, influences procurement decisions for sensitive biological data. The Cambridge Biomedical Campus and Oxford University are centers for advanced genomics and proteomics research.
Switzerland
Swiss pharmaceutical corporations and life sciences companies prioritize highly regulated and validated scientific data management systems. Swissmedic, the national regulatory authority, enforces strict standards for clinical trial data and R&D results. The Basel life sciences cluster is a major center for pharmaceutical innovation, driving demand for compliant SDMS.
Scientific Data Management System Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered competitive structure within the scientific data management system market. The landscape features established enterprise software providers alongside specialized laboratory informatics vendors. Companies often compete through strategic partnerships for integration and continuous portfolio diversification to meet evolving research demands.
Specialized laboratory informatics providers, such as LabVantage Solutions, differentiate with purpose-built solutions designed for regulated industries. Thermo Fisher Scientific leverages its extensive installed base in life sciences laboratories, driving system adoption through its broad product portfolio. TIBCO Software, on the other hand, exemplifies a software company specializing in data integration and analytics, offering powerful tools for complex research datasets across various scientific disciplines.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott Laboratories |
| TIBCO Software |
| LabVantage Solutions |
| Merck KGaA |
| Shimadzu Corporation |
| Accelerated Technology Laboratories |
| SciCord |
| Scispot |
| Others |
Cost & Logistics Intelligence
Scarcity of specialized scientific data management talent, particularly in research-intensive economies, concentrates margin pools within highly compliant software vendors. This expertise directly influences system development costs and subsequent licensing fees.
Pricing Analysis
Long-term subscription agreements dominate pricing for scientific data management systems, reflecting the ongoing service and support requirements. Price differentiation stems from the level of regulatory compliance, such as FDA 21 CFR Part 11 validation, and the sophistication of integrated data analysis and visualization tools. Pricing softness emerges from emerging biotech hubs and academic institutions seeking cost-effective cloud-based solutions. Pharmaceutical corporations exhibit lower price sensitivity due to the critical nature of data integrity and regulatory adherence.
Supply Chain Analysis
Extended payment terms often characterize procurement for large-scale scientific data management system deployments, particularly with pharmaceutical corporations. Supply concentration for core software development talent resides in research-intensive economies like the United States and parts of Europe, drawing from a global pool of specialized developers. Key dependencies include cloud infrastructure services and highly skilled data integration engineers. The scarcity of professionals with hybrid scientific and IT expertise presents a structural risk, while distribution runs through direct sales channels for enterprise clients and cloud marketplaces for agile firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scientific data management system market is experiencing a cyclical recovery, driven by renewed investment in R&D infrastructure following increased regulatory mandates. This resurgence emphasizes compliant and interoperable platforms for advanced research.
For Market Incumbents: Pre-empt the erosion of market share from agile cloud-native entrants by accelerating investment in AI-driven analytical tools and interoperability features. Incumbents should leverage their extensive installed bases in life sciences laboratories to cross-sell advanced data analysis and visualization modules. Reinforce compliance with evolving regulatory frameworks like GDPR and FDA 21 CFR Part 11 to maintain trust. Deepen integration with existing LIMS and ELN systems to counter legacy system inertia.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated emerging biotech hubs, such as those in India and Brazil, with scalable, cost-effective cloud-based solutions. Focus on developing platforms that natively support emerging AI/Machine Learning workflows, providing a distinct advantage over legacy systems. Target academic research and startup biotech firms by offering flexible subscription models and simplified integration. Address specific data format heterogeneity challenges through robust data integration capabilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized laboratory informatics providers that have successfully navigated initial GxP compliance and established a strong customer base. The market offers long-term viability over the next decade due to persistent regulatory mandates and the exponential growth of scientific data. Identify acquisition targets with deep expertise in AI-driven analytical tools or robust interoperability solutions. The signal to watch is the accelerated adoption of FAIR data principles across major pharmaceutical R&D pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with LIMS/ELN | Ensures seamless data flow and reduces manual effort across laboratory information systems. |
| AI-Driven Analytics Development | Accelerates drug discovery and materials science research through sophisticated data interpretation. |
| Cloud Infrastructure Expansion | Supports the growing preference for scalable, accessible, and collaborative research environments. |
| Regulatory Compliance Enhancement | Maintains market access and trust by meeting stringent data integrity standards like FDA 21 CFR Part 11. |
| Adjacent Vertical Adaptation | Unlocks new revenue streams by customizing solutions for fields such as agricultural science. |
Research Approach
A spread of perspectives from pharmaceutical R&D leads, laboratory directors, IT procurement officers, and regulatory compliance specialists converged on the working assumptions for this analysis. Primary interviews were triangulated with extensive secondary validation from sources including FDA 21 CFR Part 11 guidance, GDPR reports, and scientific journal databases. This approach ensured a robust bottom-up and top-down understanding of market dynamics.
The demand-supply-balance model underpinned the quantitative framework, projecting market evolution across the analysis window. Segmentation dimensions included deployment model, solution type, application area, end-user segment, and regulatory compliance level. Compound annual growth rates were derived through a combination of historical trend analysis and expert consensus. Key forecast inputs included global pharmaceutical R&D spending and regulatory enforcement intensity.
Stress conditions across R&D investment fluctuations and major regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding the pace of AI integration and global research funding. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Canada Data Center Server Market