
 Data Center Substation Market | 2026-2036
Data Center Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Substation Market Intelligence
India's massive data center build-out is rewriting power infrastructure requirements across the subcontinent. Hitachi Energy Ltd. anchors this expansion through its high-voltage transformer installations near Mumbai and Chennai. Schneider Electric leverages integrated microgrid controllers to capture modular substation contracts. Siemens competes on gas-insulated switchgear tailored for tropical humidity conditions.
A data center substation is an electrical facility that steps down transmission-level voltage to distribution levels suitable for server racks, typically operating at 34.5 kV to 480 V with redundancy configurations exceeding N+1 standards. Its primary purpose is to ensure uninterrupted power quality for compute-intensive operations while managing harmonic loads from variable frequency drives and UPS systems. Transformers dominate equipment procurement budgets due to copper and core steel cost exposure, while switchgears attract margin focus as gas-insulated designs displace air-insulated alternatives in dense urban deployments. Medium voltage installations lead volume but ultra high voltage segments capture premium pricing for hyperscale campuses exceeding 100 MW.
The U.S. EPA and India's CEA both impose efficiency mandates on transformer losses and power factor correction that directly shape procurement specifications. IEEE 3004.8 and IEC 62271-200 define arc-flash containment and internal fault withstand criteria that gate market access for Asian manufacturers. Stakeholders must monitor interconnection queue reform proceedings at FERC and state utility commissions, as queue delays now determine project viability more than equipment availability.
Market Dynamics
Utility interconnection queues stretching multiple years in Northern Virginia have transformed substation procurement from a capital decision into a project viability gate, forcing developers to secure electrical infrastructure before site selection.
Growth Catalysts
- AI Training Clusters:Cloud service providers are commissioning substations exceeding 100 MW to power GPU-intensive facilities, with specifications demanding N+2 redundancy and harmonic filtering for variable frequency drive loads.
- EPA Efficiency Standards:The U.S. Environmental Protection Agency's emerging grid-interactive data center rules are mandating transformer loss reductions and power factor correction that accelerate equipment replacement cycles.
- Copper and Core Steel Sourcing:Raw material cost volatility is concentrating transformer procurement among vertically integrated manufacturers with captive steel production and long-term copper hedging programs.
Market Restraints
- Interconnection Queue Paralysis:Federal Energy Regulatory Commission proceedings on queue reform remain unresolved, leaving projects stranded for 36-48 months in jurisdictions like PJM Interconnection territory.
- Gas-Insulated Switchgear Concentration:Production of sulfur hexafluoride-dependent switchgear concentrates among German and Japanese suppliers, exposing procurement timelines to single-source vulnerabilities.
- Skewed Voltage Demand:Hyperscale campuses are bypassing traditional medium voltage distribution for ultra high voltage direct connections, compressing addressable market for conventional 34.5 kV substation designs.
Strategic Opportunities
- India's Subcontinent Build-Out:The Central Electricity Authority's renewable integration mandates for data centers are creating demand for microgrid-ready substations with integrated battery energy storage interfaces near Mumbai and Chennai.
- IEC 62271-200 Certification Arbitrage:Asian manufacturers achieving arc-flash containment certification are penetrating European markets previously dominated by regional incumbents, exploiting test facility bottlenecks in Germany.
- Digital Twin Convergence:Real-time thermal monitoring fused with predictive maintenance algorithms is enabling performance-based service contracts that capture recurring revenue from uptime guarantees.
Industry Challenges
- Commissioning Engineer Scarcity:Arc-flash study specialists and relay protection technicians with IEEE 3004.8 expertise command premiums exceeding 40% above standard electrical engineering rates, constraining project velocity.
- Legacy UPS Harmonic Integration:Variable frequency drives from prior-generation data centers generate harmonic distortion that conflicts with modern transformer impedance specifications, requiring custom filter design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Substation Market |
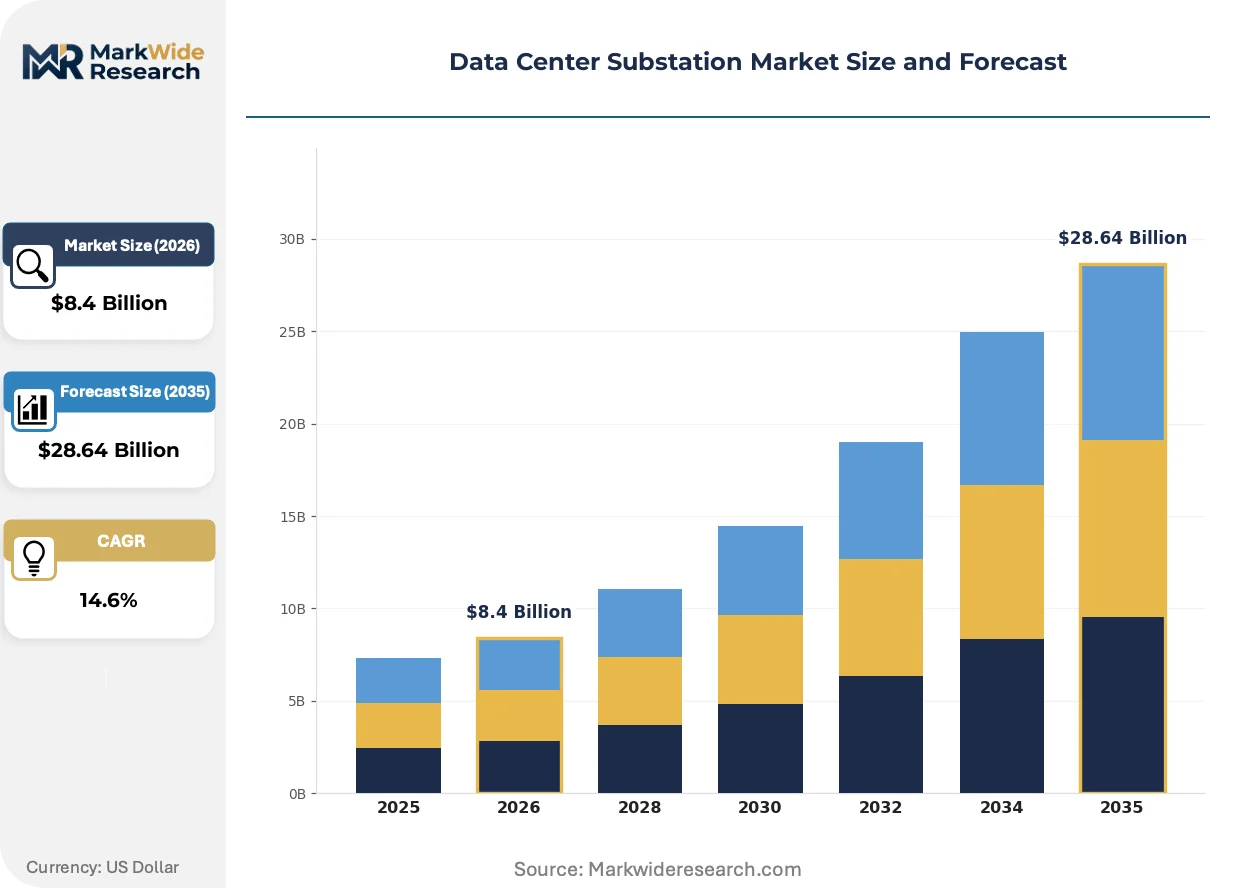
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Transformers, Switchgears, Circuit Breakers, Racks Power Capacity: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage End User: Cloud Service Providers, Telecom Operators, Enterprises, Colocation Installation Type: On-premises, Modular, Containerized, Hybrid |
| Companies Covered | Vertiv Group Corp., Hitachi Energy Ltd., Schneider Electric, Hyosung Heavy Industries, Siemens, ABB, GE Grid Solutions, Toshiba Corporation, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Substation Market Strategic Shifts & Innovations
Substation architecture is converging with IT infrastructure management, blurring operational technology boundaries and forcing vendors to embed software competencies alongside hardware manufacturing.
Digital substation protection relays with IEC 61850 protocol compatibility are digitizing fault detection and isolation sequences, reducing outage duration from cycles to milliseconds. Hyperscale operators in Northern Virginia and Frankfurt are mandating these intelligent electronic devices in all new 115 kV interconnections. The technology is digitizing maintenance scheduling by shifting from calendar-based inspections to condition-based interventions triggered by dissolved gas analysis thresholds.
The European Union's F-Gas Regulation is phasing down sulfur hexafluoride emissions from switchgear, compelling manufacturers to accelerate vacuum interrupter and clean air insulation development. Industrial consequence includes redesign of 145 kV gas-insulated switchgear footprints to accommodate larger physical clearances required by alternative dielectrics. German utilities and data center developers are most affected, responding with pilot installations of fluoronitrile-based mixtures in Frankfurt and Berlin campus expansions.
Utility-scale data center developers are unbundling engineering-procurement-construction contracts into separate substation and campus infrastructure awards, compressing vendor accountability and shifting integration risk to owners. General contractors with transmission-scale experience are displacing traditional data center EPCs in electrical infrastructure packages. This pattern is most visible in Texas and Arizona markets where merchant transmission developers intersect with hyperscale land banking strategies.
Data Center Substation Market Segmentation
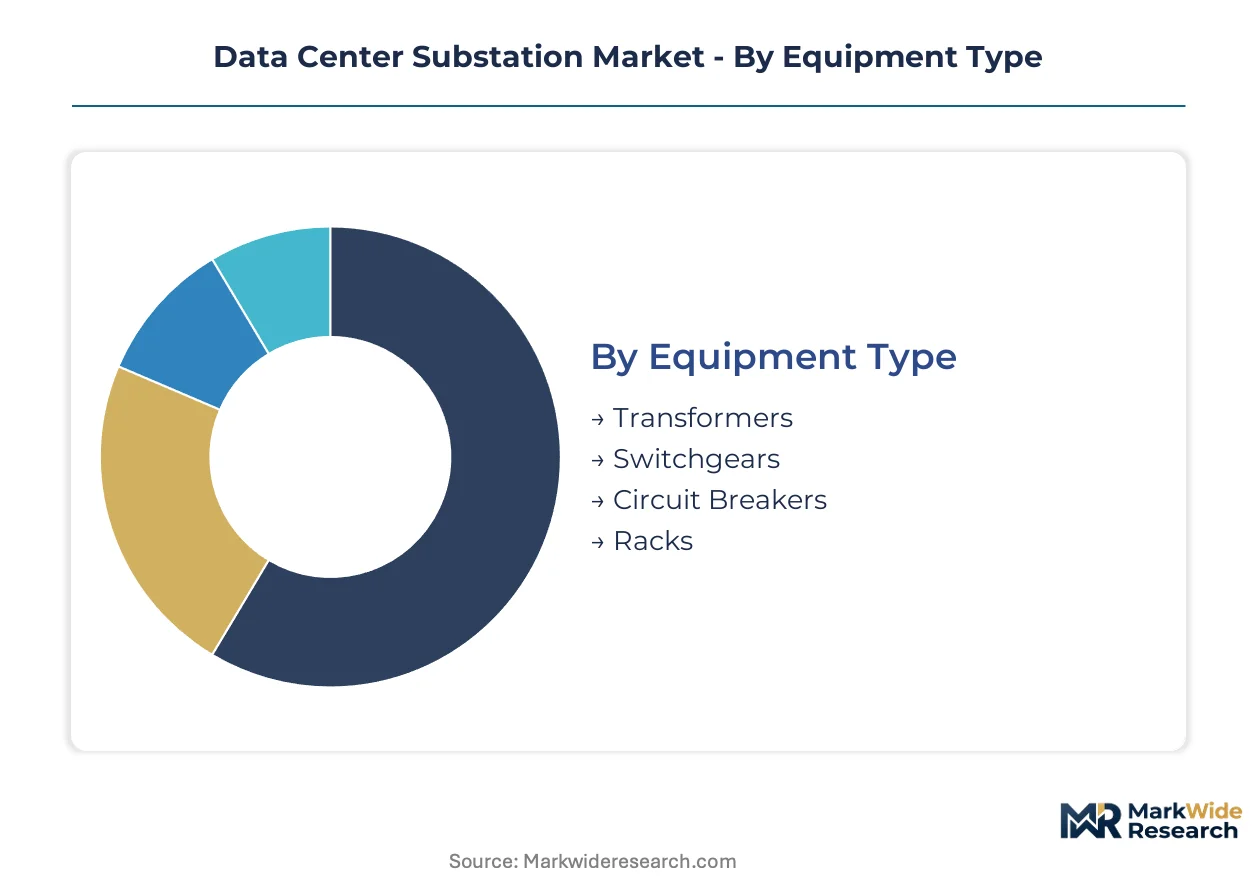
Data center substation procurement varies sharply by deployment scale and operational model. Equipment specifications, voltage tiers, and installation approaches segment vendor opportunities and margin structures across hyperscale, enterprise, and colocation verticals.
Equipment Type:
Use-case spectrum spans bulk power transformation through precision distribution, with each equipment category serving distinct reliability and space constraints.
- Transformers:Core and winding assemblies step transmission voltage to distribution levels, with copper and grain-oriented electrical steel comprising 60-70% of unit cost. Procurement concentrates among hyperscale campuses in Northern Virginia and Texas, where N+2 redundancy mandates and EPA efficiency standards accelerate replacement cycles for legacy designs.
- Switchgears:Gas-insulated and air-insulated assemblies manage fault isolation and load switching, with sulfur hexafluoride-based designs dominating dense urban deployments despite EU F-Gas Regulation phase-down pressures. Demand clusters in Frankfurt and Singapore, where land scarcity forces compact 145 kV GIS footprints.
- Circuit Breakers:Vacuum and SF6 interruption mechanisms protect downstream equipment from fault currents, with medium voltage units seeing volume concentration in Indian metro expansions near Mumbai.
- Racks:Busway and panelboard assemblies distribute 480 V power to server rows, with prefabricated skids gaining traction in modular data center deployments across Phoenix and Dallas markets.
Established volume favors transformers; emerging adoption favors switchgear alternatives with reduced fluorinated gas content.
Power Capacity:
Cost tier segmentation separates commodity distribution infrastructure from premium interconnection assets commanding engineering premiums.
- Low Voltage:480 V and below distribution serves edge computing and enterprise server rooms, with standardization compressing margins and favoring high-volume manufacturers with automated winding operations.
- Medium Voltage:34.5 kV class installations dominate traditional data center substations, though hyperscale bypass trends are constraining addressable market expansion in established markets.
- High Voltage:115 kV interconnections serve regional cloud campuses, with procurement timelines stretching 24-36 months due to utility coordination requirements in PJM and ERCOT territories.
- Ultra High Voltage:Direct 230 kV and 345 kV connections for 100 MW+ AI training clusters command premium engineering and custom transformer specifications, with demand concentrating in Northern Virginia's Data Center Alley where queue delays now determine project sequencing.
Medium voltage retains deployment volume leadership; ultra high voltage captures the steepest expansion trajectory from AI infrastructure investment.
End User:
Customer type dictates redundancy specifications, procurement centralization, and service contract structures.
- Cloud Service Providers:Hyperscale operators with standardized designs and global vendor qualification programs, driving consolidation toward integrated transformer-switchgear packages with digital twin interfaces.
- Telecom Operators:5G edge and central office facilities with mixed legacy-modern infrastructure, creating harmonic filtering challenges when integrating variable frequency drives from prior-generation UPS systems.
- Enterprises:Financial services and healthcare verticals with internal IT infrastructure, where N+1 redundancy suffices and procurement remains decentralized across facility management teams.
- Colocation:Multi-tenant operators balancing tenant-specific SLAs with shared infrastructure economics, favoring modular substation designs with segmented metering and rapid scalability.
Cloud service providers dominate capital deployment; colocation operators represent the most price-sensitive procurement segment with highest vendor switching incidence.
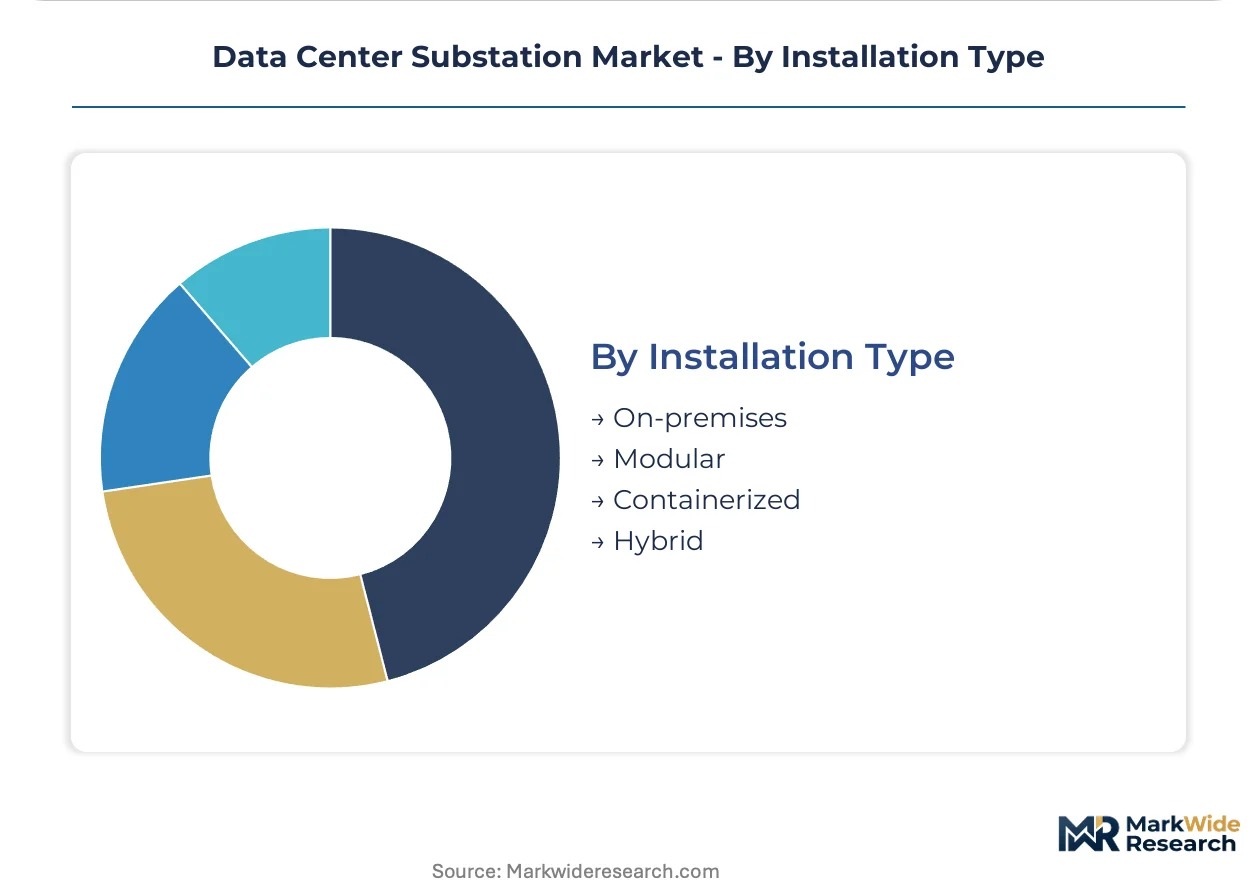
Installation Type:
Maturity gradient separates established permanent construction from emerging prefabricated approaches reshaping project velocity.
- On-premises:Traditional brick-and-mortar substation construction with civil works and embedded equipment, retaining preference for utility-owned assets and long-tenured campus expansions.
- Modular:Factory-integrated transformer and switchgear skids with reduced field commissioning, accelerating deployment for cloud providers facing interconnection queue uncertainty in Northern Virginia.
- Containerized:ISO-standard enclosures with pre-wired protection and control systems, serving remote edge locations and rapid-deployment AI training clusters in secondary markets.
- Hybrid:Combinations of permanent medium voltage infrastructure with modular low voltage distribution, optimizing capital allocation for phased campus build-outs in Texas and Arizona.
On-premises retains share in utility-integrated projects; modular and containerized formats are gaining share fastest from developer urgency around queue delays and speed-to-market imperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC proceedings on interconnection queue reform anchor the United States market, where utility coordination delays now determine project sequencing more than equipment availability. Regulatory divergence across major economies is fragmenting procurement specifications and certification requirements.
United States
Hyperscale cloud providers are commissioning 100 MW+ substations for AI training clusters in Northern Virginia's Data Center Alley. The EPA's emerging grid-interactive efficiency standards mandate transformer loss reductions and power factor correction. PJM Interconnection territory faces 36-48 month queue delays, forcing developers to secure electrical infrastructure before site selection.
Germany
Frankfurt campus expansions drive demand for gas-insulated switchgear despite EU F-Gas Regulation phase-down pressures on sulfur hexafluoride. The country's national energy regulator enforces stringent arc-flash containment standards under IEC 62271-200. Berlin developers are piloting fluoronitrile-based insulation mixtures to accommodate larger physical clearances required by alternative dielectrics.
India
The Central Electricity Authority's renewable integration mandates create demand for microgrid-ready substations with battery energy storage interfaces. Hitachi Energy Ltd. anchors high-voltage transformer installations near Mumbai and Chennai. Maharashtra and Tamil Nadu metro expansions concentrate medium voltage circuit breaker procurement for rapidly scaling data center corridors.
Singapore
Land scarcity forces compact 145 kV GIS footprints for dense urban substation deployments. The country's national standards body enforces tropical humidity specifications that shape switchgear material selection. Limited land availability accelerates adoption of gas-insulated designs displacing air-insulated alternatives in premium downtown locations.
United Arab Emirates
Dubai and Abu Dhabi are attracting merchant transmission developers intersecting with hyperscale land banking strategies. The country's federal energy regulator imposes efficiency mandates on transformer losses for new data center interconnections. Secondary emirates are emerging as rapid-deployment locations for containerized substation formats serving edge computing nodes.
Data Center Substation Market Key Industry Players
Integrated electrical conglomerates and specialized power infrastructure providers split the market based on vertical scope and geographic coverage depth. The vendor base concentrates among European and Asian manufacturers with captive transformer steel production and long-term copper hedging programs. Three strategic archetypes dominate: full-spectrum electrical infrastructure suppliers, component-specialist switchgear manufacturers, and IT-integrated power management providers. Competitive intensity centers on M&A activity to secure arc-flash study capabilities and strategic partnerships with utility-scale EPC contractors.
Among integrated infrastructure suppliers, Hitachi Energy Ltd., Siemens, and Schneider Electric exemplify the full-spectrum archetype. Hitachi Energy Ltd. occupies a position anchored in high-voltage transformer manufacturing with geographic concentration in Asian growth markets. Siemens represents European engineering heritage applied to gas-insulated switchgear tailored for tropical and temperate conditions. Schneider Electric sits within the IT-convergence tier, leveraging integrated microgrid controllers to capture modular substation contracts. These three companies illustrate how vendor positioning stratifies across hardware manufacturing depth, software integration capability, and regional market focus.
| Leading Market Players |
|---|
| Vertiv Group Corp. |
| Hitachi Energy Ltd. |
| Schneider Electric |
| Hyosung Heavy Industries |
| Siemens |
| ABB |
| GE Grid Solutions |
| Toshiba Corporation |
| Eaton |
| Others |
Cost & Logistics Intelligence
Copper and grain-oriented electrical steel price volatility determines both transformer procurement tier spreads and supply chain configuration, compressing margins for non-integrated manufacturers while rewarding those with captive steel production and long-term commodity hedging programs.
Pricing Analysis
Geographic price spreads between Northern Virginia and Indian metro markets exceed 30% for equivalent transformer specifications due to utility coordination premiums and import duty structures. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in standard-tier equipment is intensifying because Chinese manufacturers with IEC 62271-200 certification are penetrating European markets. Colocation operators represent the most price-sensitive procurement segment, while hyperscale cloud providers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Export control regimes on sulfur hexafluoride gas recovery technology limit flows from German and Japanese suppliers to Asian manufacturing hubs. Transformer core steel production concentrates in Japan, South Korea, and Germany, while copper winding assemblies draw from Chilean and Zambian mining operations. Single-source vulnerability around gas-insulated switchgear creates procurement timeline exposure when Frankfurt or Singapore projects require simultaneous delivery. Distribution runs through utility-scale EPC contractors with transmission experience, displacing traditional data center integrators in electrical infrastructure packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as AI training cluster specifications diverge from enterprise redundancy standards, creating specialized vendor niches around harmonic filtering and ultra high voltage interconnection expertise.
For Market Incumbents: Insulate transformer market share through backward integration into grain-oriented electrical steel production and accelerated IEC 61850 digital relay certification. The threat of Asian manufacturers achieving arc-flash containment parity under IEC 62271-200 demands preemptive investment in test facility capacity and utility EPC partnership lock-ups. For New Entrants and Emerging Players: Modular substation skids for secondary U.S. markets facing PJM interconnection queue paralysis represent the most penetrable entry point. Containerized formats for remote edge deployments in Texas and Arizona offer lower certification barriers. A go-to-market angle anchored to speed-to-market guarantees rather than cost competition bypasses incumbent scale advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors arc-flash study specialists and relay protection engineering boutiques. Long-term viability across the analysis window hinges on software-integrated power management capabilities rather than pure hardware manufacturing. The signal to watch is FERC queue reform proceedings, which would reset project viability calculations and equipment demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel | Captive grain-oriented electrical steel production insulates Hitachi Energy and Siemens from commodity volatility exposure. |
| IEC 61850 Digital Relay Certification | Intelligent electronic device compatibility gates access to Northern Virginia and Frankfurt hyperscale interconnection mandates. |
| SF6 Alternative Insulation Development | Fluoronitrile-based mixtures position vendors ahead of EU F-Gas Regulation phase-down deadlines in German markets. |
| Utility EPC Partnership Lock-ups | Transmission-scale contractor relationships secure electrical infrastructure package awards ahead of traditional data center EPCs. |
| Microgrid Controller Integration | Software-embedded substation management captures recurring revenue from uptime guarantees and predictive maintenance contracts. |
Research Approach
Desk research of utility interconnection queue databases, EPA efficiency standard dockets, and FERC regulatory filings preceded structured interviews with substation engineering directors, utility planning officers, hyperscale facility procurement leads, and EPC contractor project managers. Secondary validation drew from IEC certification registries, copper and steel trade association pricing data, and equipment manufacturer technical specifications. Bottom-up project pipeline analysis triangulated against top-down utility capex disclosure aggregation.
Assumptions around interconnection queue duration, raw material cost trajectories, and regulatory implementation timelines were held fixed across baseline scenarios while AI training cluster deployment velocity and FERC reform outcomes were stress-tested. Segmentation modeling spanned equipment type, voltage tier, end-user archetype, and installation format. CAGRs were derived from unit shipment projections weighted by average selling price evolution. Forecast inputs incorporated transformer loss efficiency mandates and sulfur hexafluoride phase-down compliance costs.
Practitioners should monitor FERC queue reform rulings, EPA grid-interactive standard finalization, and EU F-Gas Regulation enforcement intensity for early signals. Forecasts reflect documented assumptions regarding commodity price stability and certification timeline continuity. Material shifts in utility interconnection policy or transformer steel trade flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
UAE Data Center Construction Market