
 Pipe Marking Tape Market | 2026-2036
Pipe Marking Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Marking Tape Market Analytics
A capital-intensity divergence between integrated manufacturers and regional converters is bifurcating competitive dynamics in the pipe marking tape sector. 3M Company leverages captive resin compounding and adhesive chemistry capabilities to sustain premium positioning across North American industrial corridors. Brady Corporation anchors its position through deep distribution into utility and municipal infrastructure channels. Kolbi Pipe Marker Co. competes on turnaround speed for custom color-code orders in the Gulf Coast petrochemical cluster.
Pipe marking tape comprises pressure-sensitive adhesive substrates engineered to withstand thermal cycling, chemical exposure, and mechanical abrasion while conveying fluid content, flow direction, and hazard classification per ANSI/ASME A13.1 standards. Vinyl formulations dominate current procurement volumes due to cost efficiency and printability, though polyester tapes command margin premiums in high-temperature process environments. The application dimension shows industrial safety absorbing the largest share of specification activity, while HVAC contractors are shifting toward pre-printed, color-coded rolls to reduce field installation labor. Permanent adhesive types lock in replacement-cycle revenue, but removable formulations are expanding in temporary construction and turnaround maintenance contexts.
OSHA mandates pipeline identification consistency across process facilities, while ANSI/ASME A13.1 governs color schemes and dimensional standards; together these frameworks compel facility managers to budget for compliant marking systems rather than discretionary safety spend. The EPA's chemical facility risk management programs indirectly amplify tape demand by requiring updated process safety information and visible hazard communication. Stakeholders must monitor how evolving building electrification codes and hydrogen infrastructure standards reshape color-code requirements before committing to long-term substrate and print technology investments.
Market Dynamics
OSHA's updated pipeline identification mandates are compressing replacement cycles across US process facilities, forcing capital allocation toward compliant marking systems rather than discretionary maintenance spend.
Growth Catalysts
- ANSI/ASME A13.1 color-code standardization:Facility managers in Texas and Louisiana petrochemical corridors are retrofitting legacy piping networks to meet revised hazard classification requirements.
- Offshore salt corrosion resistance demand:Polyester substrate specifications are accelerating in North Sea and Gulf of Mexico subsea installations where vinyl degradation rates prove unacceptable.
- Hydrogen infrastructure buildout:Emerging H2 pipeline networks require new color-code protocols, creating specification windows for tape producers ahead of finalized standards.
Market Restraints
- Petrochemical resin price volatility:Vinyl chloride monomer feedstock costs swing with ethylene cracking margins, compressing converter gross margins on fixed-price municipal contracts.
- Adhesive supply concentration:Solvent-based acrylic PSA production clusters in Germany and Japan create vulnerability for North American tape laminators.
- Digital pipe labeling substitution:RFID-enabled smart tags and permanent etched marking systems are capturing share in high-value pharmaceutical cleanroom applications.
Strategic Opportunities
- India industrial safety enforcement:BIS certification mandates for hazard communication materials in Maharashtra and Gujarat chemical zones open import substitution potential.
- Pre-printed HVAC contractor rolls:Color-coded bulk formats reduce field labor hours, creating pull-through demand from mechanical installation firms.
- CE marking harmonization:REACH-compliant adhesive formulations qualify tape producers for unified European process safety equipment procurement.
Industry Challenges
- ANSI/ASME certification timeline compression:Third-party testing backlogs at accredited laboratories delay new product launches by four to six months.
- Legacy ERP integration friction:Municipal utility procurement portals require EDI compliance that regional converters lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Marking Tape Market |
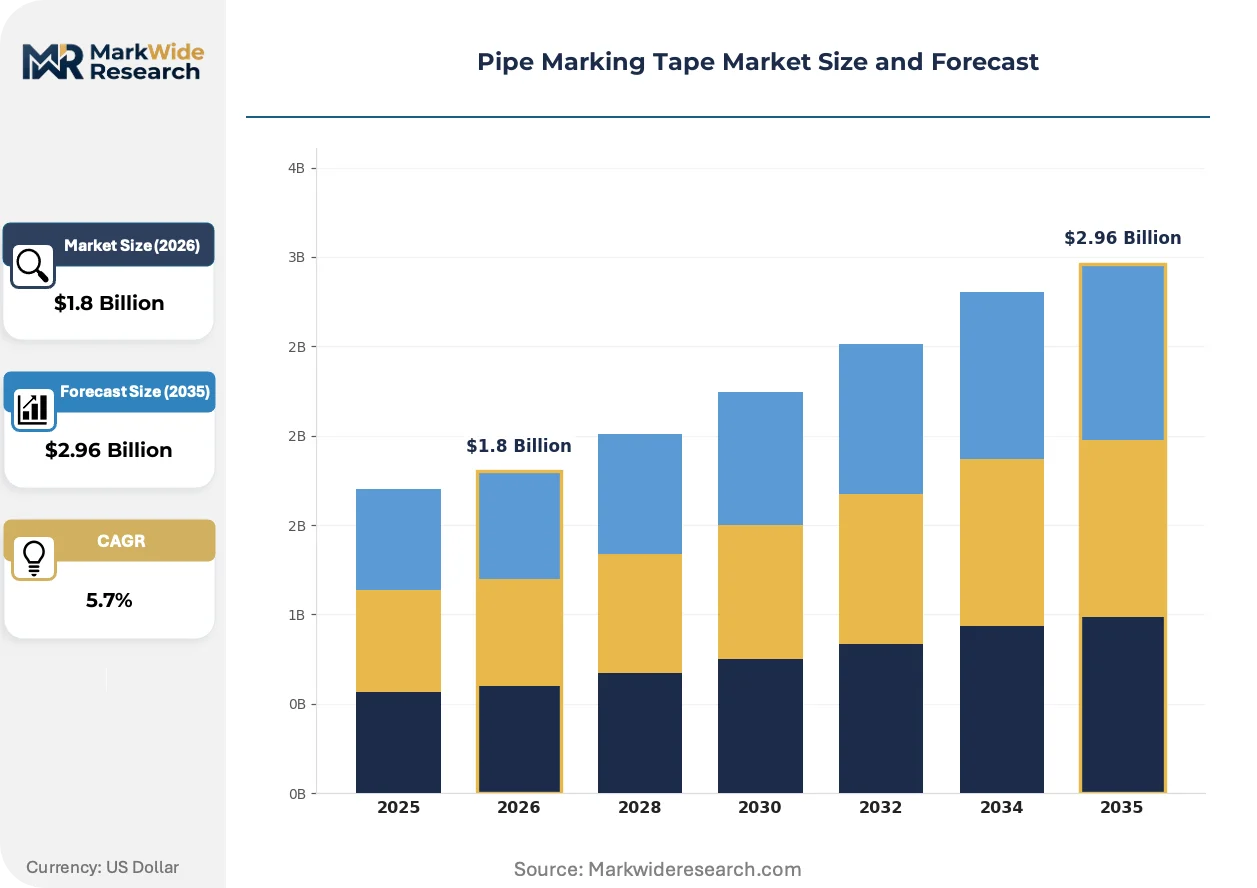
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Polyester, Polypropylene, Other Application: Industrial Safety, Plumbing, HVAC, Electrical Adhesive Type: Permanent, Removable, Low-Tack, High-Tack Color Coding: Red, Green, Yellow, Blue |
| Companies Covered | 3M Company, Brady Corporation, First Safety Signs, Acu-Tech Piping Systems, Windmill Tapes and Labels Ltd, Marking Services, Kolbi Pipe Marker Co., Craftmark Pipe Markers, INCOM Manufacturing Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Marking Tape Market Evolving Landscape
Material science advances and regulatory precision are converging to reshape substrate selection criteria, with durability specifications tightening faster than cost curves can absorb.
Photoluminescent vinyl formulations are fragmenting the emergency egress marking segment. Nuclear facilities and underground mining operations specify glow-in-the-dark substrates for blackout visibility. This capability is compressing demand for battery-backed electronic alternatives in safety-critical infrastructure.
EPA chemical facility risk management program updates are mandating visible hazard communication refresh cycles. Process safety information audits now flag faded or illegible pipe markings as violations. Petrochemical operators in Texas and Louisiana are responding with accelerated replacement schedules and higher-grade substrate specifications.
Specification authority is migrating from maintenance departments to centralized EHS compliance officers. This consolidation concentrates vendor selection power with buyers who prioritize ANSI certification documentation over unit price. The shift is most pronounced in Fortune 500 industrial conglomerates with multi-site standardization mandates.
Pipe Marking Tape Market Segmentation
Substrate chemistry and adhesive formulation choices in pipe marking tape directly determine replacement cycles, specification authority, and margin capture across industrial procurement channels. Understanding how these technical dimensions map to end-use requirements reveals where converters can defend pricing and where commoditization pressure concentrates.
Product Type:
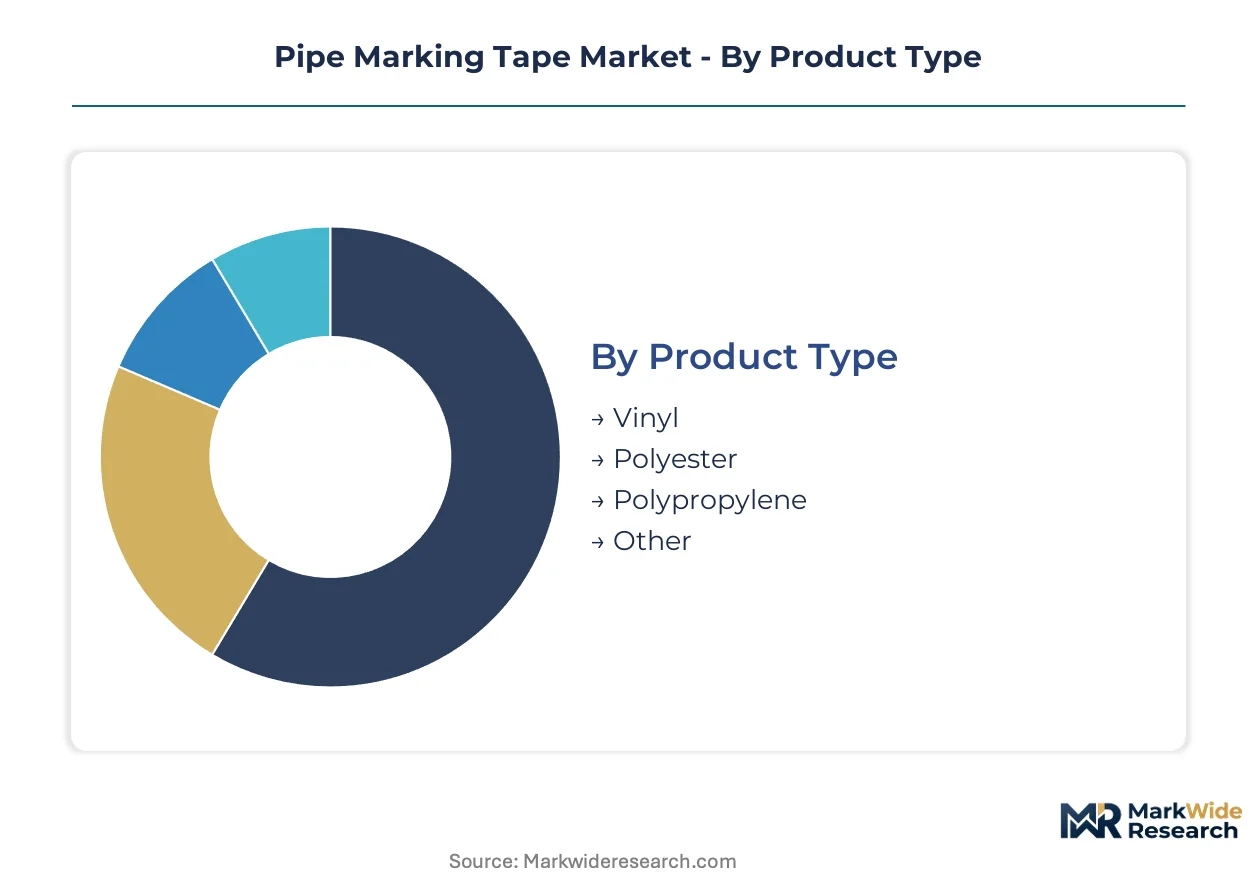
Vinyl formulations flow through municipal utility and commercial HVAC distribution, while polyester grades command specification through engineering-procurement-construction contractors in offshore and process industries.
- Vinyl:Polyvinyl chloride substrates dominate procurement volumes due to solvent-based print compatibility and cost efficiency in standard-temperature environments. Demand concentrates in Texas and Louisiana petrochemical corridors where facility managers balance OSHA compliance against maintenance budget constraints.
- Polyester:Polyethylene terephthalate films withstand thermal cycling above 150°C and salt corrosion in subsea installations. North Sea and Gulf of Mexico operators specify these grades where vinyl degradation rates prove unacceptable, accepting 40-60% unit price premiums.
- Polypropylene:Olefin-based tapes offer intermediate chemical resistance for wastewater treatment and food processing applications where moisture exposure exceeds vinyl tolerance.
- Other:Fluoropolymer and aluminum-backed specialty substrates serve nuclear containment and cryogenic LNG transfer lines with extreme temperature or radiation requirements.
By volume, Vinyl leads. By growth pace, Polyester is ahead.
Application:
Cost tier stratification separates safety-critical process industries from price-sensitive construction trades, with specification authority migrating accordingly.
- Industrial Safety:ANSI/ASME A13.1 compliance mandates absorb the largest share of specification activity in chemical processing and power generation. EPA risk management program audits now flag faded markings as violations, compressing replacement cycles.
- HVAC:Mechanical contractors are shifting toward pre-printed, color-coded bulk rolls to reduce field installation labor hours. Distribution runs through regional HVAC supply houses rather than industrial safety distributors.
- Plumbing:Municipal building codes drive specification for potable water and sanitary drain identification in commercial construction, with procurement concentrating in wholesale plumbing channels.
- Electrical:Conduit and cable tray marking requirements in data center and renewable energy installations favor photoluminescent and high-visibility formulations.
Industrial Safety captures the highest margin tier. HVAC is expanding most quickly as prefabrication trends accelerate.
Adhesive Type:
Customer type divides procurement between permanent-installation asset owners and temporary-application contractors with divergent replacement cycle economics.
- Permanent:Solvent acrylic pressure-sensitive adhesives lock in replacement-cycle revenue through 10-15 year service life in buried pipeline and subsea applications. Asset owners accept higher upfront costs to minimize intervention frequency.
- Removable:Low-residue formulations serve turnaround maintenance and temporary construction where substrate preservation matters. Refinery contractors in the Gulf Coast petrochemical cluster drive specification.
- Low-Tack:Repositionable adhesives enable precise alignment during installation for complex piping networks in pharmaceutical cleanrooms.
- High-Tack:Aggressive bonding chemistry adheres to rough or oxidized metal surfaces in legacy infrastructure retrofit applications.
Permanent adhesives dominate revenue. Removable formulations are gaining share fastest as turnaround maintenance intensity increases.
Color Coding:
Margin differentiation follows certification grade rather than pigment cost, with ANSI-compliant standard colors commanding premiums over custom matches.
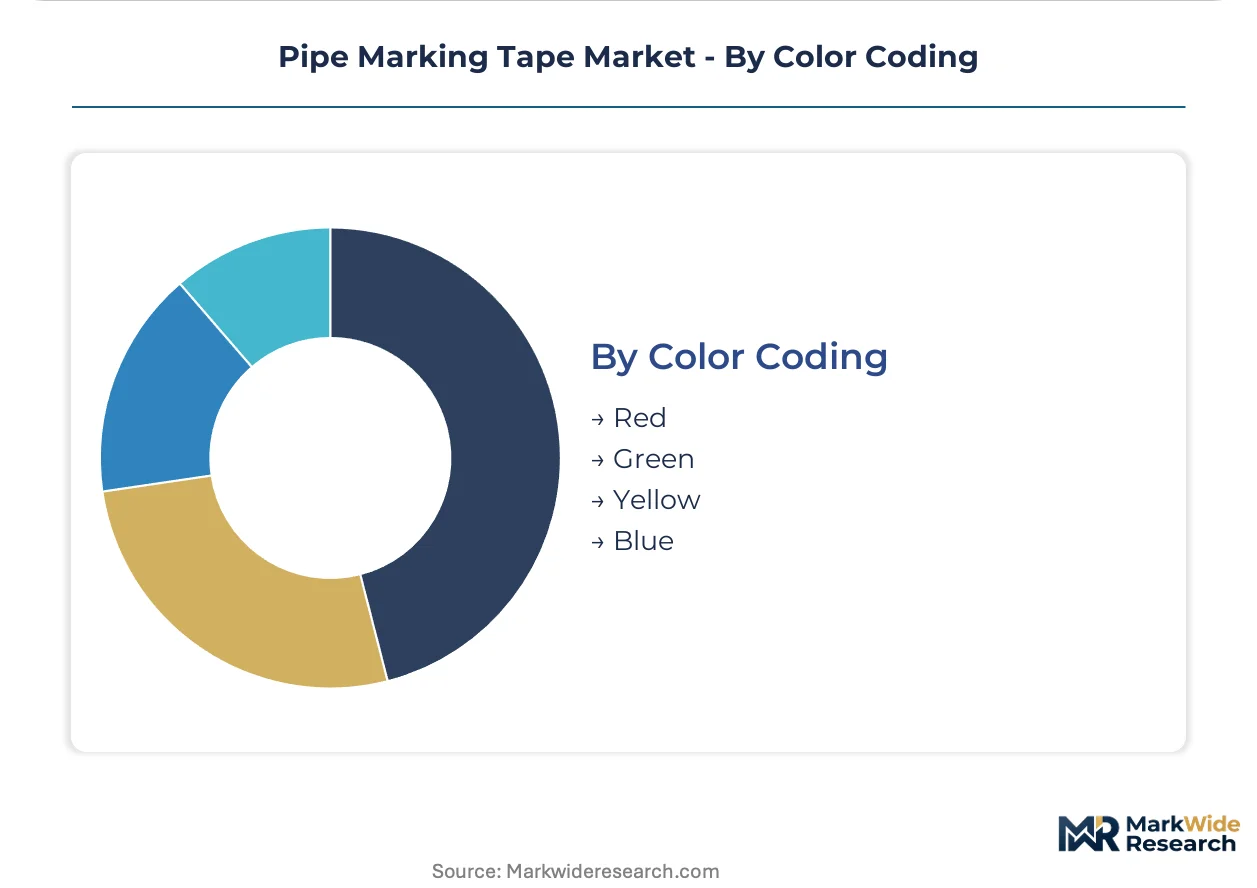
- Yellow:Flammable liquid and gas identification per ANSI/ASME A13.1 represents the highest-volume specification in petrochemical and fuel distribution facilities. OSHA inspection consistency enforces standard color procurement.
- Red:Fire suppression and emergency equipment marking concentrates in commercial building and municipal infrastructure where code compliance is non-negotiable.
- Green:Safe water and cooling return lines serve HVAC and plumbing applications with stable but lower-margin procurement patterns.
- Blue:Compressed air and potable water identification rounds out standard color demand in general industrial and food processing environments.
Yellow leads by specification frequency. Red is climbing the fastest as building electrification codes expand fire suppression system requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical corridor intensity drives divergent consumption patterns across markets. United States facilities prioritize ANSI/ASME A13.1 compliance refresh cycles, while offshore operators in the North Sea and Gulf of Mexico specify corrosion-resistant substrates. Emerging chemical manufacturing clusters in India and the Middle East are establishing first-generation marking protocols.
United States
Texas and Louisiana petrochemical operators face compressed replacement schedules under OSHA's updated pipeline identification mandates. EPA chemical facility risk management program audits now flag degraded markings as violations. The Gulf Coast petrochemical cluster is retrofitting legacy piping networks with higher-grade polyester specifications.
Germany
REACH-compliant adhesive formulations qualify domestic tape producers for unified European process safety equipment procurement. ECHA chemical safety regulations enforce hazard communication consistency across BASF and Bayer integrated sites. The Rhine-Ruhr industrial corridor maintains specification authority with centralized EHS compliance officers.
India
BIS certification mandates for hazard communication materials are opening import substitution potential in Maharashtra and Gujarat chemical zones. CDSCO-aligned industrial safety enforcement is accelerating in pharmaceutical manufacturing regions. The Gujarat Special Economic Zone is attracting tape converters to serve domestic petrochemical expansion.
United Kingdom
North Sea offshore installations specify polyester grades where vinyl degradation rates prove unacceptable. HSE offshore safety directives mandate visible pipeline identification refresh cycles. Aberdeen's subsea engineering cluster is driving specification for salt-corrosion-resistant substrates.
China
GB standards for industrial safety labeling are tightening in Yangtze River Delta chemical parks. MEE environmental compliance audits are amplifying visible hazard communication requirements. The Ningbo-Zhoushan petrochemical base is standardizing color-code protocols for hydrogen infrastructure pilot lines.
Pipe Marking Tape Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pipe marking tape supply. Captive resin compounding and adhesive chemistry capabilities separate premium-positioned manufacturers from regional converters dependent on merchant feedstock. Three archetypes dominate: integrated material science conglomerates with in-house substrate production, distribution-anchored safety equipment specialists, and turnaround-focused custom color-code shops serving Gulf Coast maintenance windows. Competitive moves concentrate on ANSI certification documentation investments and EDI compliance for municipal utility procurement portals.
Within the integrated materials tier, 3M Company exemplifies captive supply chain control over resin compounding and pressure-sensitive adhesive chemistry. Brady Corporation occupies a position anchored through deep distribution into utility and municipal infrastructure channels. Kolbi Pipe Marker Co. represents the turnaround-speed specialist archetype, competing on custom color-code velocity for Gulf Coast petrochemical maintenance cycles.
| Leading Market Players |
|---|
| 3M Company |
| Brady Corporation |
| First Safety Signs |
| Acu-Tech Piping Systems |
| Windmill Tapes and Labels Ltd |
| Marking Services |
| Kolbi Pipe Marker Co. |
| Craftmark Pipe Markers |
| INCOM Manufacturing Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Gulf Coast petrochemical operators and vinyl substrate converters lock in both resin supply security and price visibility across volatile ethylene cracking cycles. These contracts insulate integrated manufacturers from spot market swings while exposing regional converters to margin compression when fixed-price municipal utility awards collide with feedstock spikes.
Pricing Analysis
Project-based procurement dominates industrial safety applications where ANSI/ASME A13.1 certification grade and adhesive chemistry specification drive 40-60% unit price premiums for polyester over vinyl. Cost compression in standard-grade vinyl tapes is intensifying because municipal HVAC contractors prioritize volume scale over performance tier, while permanent adhesive formulations command margin defense through 10-15 year replacement cycle economics. Price-sensitive mechanical installation firms in commercial construction represent the most elastic demand segment, whereas offshore subsea operators accept premium positioning for salt-corrosion-resistant substrates.
Supply Chain Analysis
Solvent-based acrylic pressure-sensitive adhesive production clusters in Germany and Japan create a chokepoint that North American tape laminators navigate through merchant supply contracts with 90-day lead time exposure. Raw material sourcing draws from vinyl chloride monomer feedstock tied to ethylene cracking margins, polyester film biaxial orientation capacity concentrated in China and South Korea, and release liner silicone coatings anchored in Belgium and the United States. Single-source vulnerability in specialty adhesive chemistry amplifies procurement risk for converters serving OSHA-mandated replacement cycles. Distribution runs through industrial safety distributors for process industries and regional HVAC supply houses for mechanical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pipe marking tape market sits in a cyclical recovery phase as OSHA's updated pipeline identification mandates force capital allocation toward compliant marking systems rather than deferred maintenance spend.
For Market Incumbents: Secure ANSI certification documentation investments ahead of third-party testing backlogs at accredited laboratories that currently delay new product launches by four to six months. Deepen channel control through EDI compliance for municipal utility procurement portals where regional converters lack capital to implement, while building captive resin compounding capacity to defend margin position against vinyl chloride monomer price volatility.
For New Entrants and Emerging Players: ANSI certification fast-track through partnership with Gulf Coast testing laboratories opens specification windows in Texas and Louisiana petrochemical corridors where turnaround maintenance intensity is accelerating. Target India's Maharashtra and Gujarat chemical zones where BIS certification mandates for hazard communication materials are opening import substitution potential ahead of domestic converter capacity buildout. Lead with custom color-code velocity for hydrogen infrastructure pilot lines where color-code protocols remain undefined.
For Investors and Strategic Acquirers: Regional converters with established Gulf Coast maintenance relationships and turnaround-speed capabilities represent the most defensible acquisition archetype as specification authority migrates from maintenance departments to centralized EHS compliance officers. Long-term viability over the next decade hinges on substrate diversification beyond vinyl into polyester and photoluminescent formulations. Watch hydrogen infrastructure standards development as the critical inflection signal for color-code specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive vinyl chloride monomer supply insulates margin from ethylene cracking volatility in Gulf Coast corridors. |
| ANSI Certification Fast-Track Investment | Compressed testing timelines capture specification windows ahead of four-to-six month laboratory backlogs. |
| Hydrogen Infrastructure Color-Code Development | Early protocol definition secures anchor positioning before finalized H2 pipeline standards. |
| EDI Compliance for Municipal Procurement | Technical barrier to entry excludes regional converters from utility infrastructure replacement cycles. |
| Photoluminescent Substrate R&D Partnership | Glow-in-the-dark capability displaces battery-backed electronic alternatives in nuclear and mining safety. |
Research Methodology
Desk research of customs and trade flow databases, OSHA enforcement records, and ANSI/ASME standards documentation preceded structured interviews with petrochemical facility EHS compliance officers, industrial safety distributors, HVAC mechanical contractors, and adhesive chemistry specialists. Secondary validation drew from EPA chemical facility risk management program audit reports, SEC 10-K filings of integrated material science conglomerates, and regional converter capacity announcements. Bottom-up demand modeling across substrate chemistry, adhesive formulation, and end-use application segments was triangulated against top-down petrochemical capital expenditure forecasts.
Variance decomposition across the projection horizon isolates price elasticity by buyer archetype, replacement cycle compression effects from regulatory enforcement, and substrate substitution dynamics in offshore applications. Segmentation dimensions modeled include substrate chemistry tier, adhesive permanence classification, color-code certification grade, end-use industry vertical, and regional regulatory cluster. CAGRs were derived through logistic diffusion curves for emerging hydrogen infrastructure specifications and linear extrapolation for mature HVAC replacement demand. Industry-specific inputs incorporated ethylene cracking margin forecasts and third-party laboratory testing capacity constraints.
Decision-makers should treat outputs as directional under assumptions of continued OSHA enforcement intensity and stable ethylene feedstock availability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as hydrogen infrastructure color-code standards and REACH-compliant adhesive formulation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Europe Packaging Tapes Market
Tapes
Tape Backing Materials Market
Tapes
Double Coated Film Tapes Market
Tapes
India Reflective Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Sterilization Tape Market
Tapes
Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Moisture Barrier Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Global Adhesive Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Application Tapes Market
Tapes
Medical Tapes Market
Tapes
Raffia Tapes Market
Tapes
Building and Construction Tapes Market