
 Pouch Tapes Market | 2026-2036
Pouch Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Pouch Tapes Market Analytics
EU Green Deal packaging sustainability targets is expanding the addressable market for recyclable adhesive systems across European pouch tape procurement. 3M leverages its polymer science infrastructure to develop solvent-free hot-melt formulations that align with REACH compliance pathways. Irplast anchors southern European supply through its integrated film and tape production campus in Tuscany. Lynx Polythene competes on flexible minimum-order quantities that attract mid-sized UK contract packagers.
Pouch tapes are pressure-sensitive adhesive strips engineered for sealing flexible packaging substrates, typically constructed from polypropylene or polyethylene film carriers coated with acrylic or rubber-based adhesives and specified by peel adhesion values ranging from 15 to 50 ounces per inch. Their primary industrial purpose is to create tamper-evident, hermetic closures on stand-up pouches, flat bags, and sachets across automated and manual packaging lines. Transparent tapes dominate high-throughput food packaging lines where barcode scanning and optical inspection require substrate visibility, while specialty tapes capture margin pools in pharmaceutical cold-chain applications where low-temperature adhesion failure risks product spoilage. Double-sided tapes are displacing mechanical fasteners in electronics pouch assembly as device manufacturers seek thinner stack-up profiles.
FDA food-contact substance notifications govern adhesive migration limits for pouch tapes serving US food packaging, while EFSA evaluates similar safety thresholds under EU framework 10/2011 for plastic materials intended for food contact. China's SAMR enforces GB standards for packaging material composition that affect imported tape formulations. BIS certification requirements in India create non-tariff barriers for unqualified foreign suppliers. Stakeholders must monitor how divergent recyclability mandates across these jurisdictions reshape material specification roadmaps and supplier qualification timelines.
Market Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates are compressing specification timelines for adhesive formulators, forcing rapid solvent-free hot-melt qualification cycles that favor polymer science infrastructure over commodity converters.
Growth Catalysts
- Automated packaging line deployment:E-commerce fulfillment centers in Germany are scaling robotic sealing stations that demand high-tack, low-variation tape performance.
- REACH compliance pathways:Solvent-free adhesive formulations are gaining procurement preference as downstream brands pre-empt regulatory liability.
- Cold-chain pharmaceutical expansion:Temperature-stable adhesion specifications are opening specification windows for specialty tape grades in biologics distribution.
Market Restraints
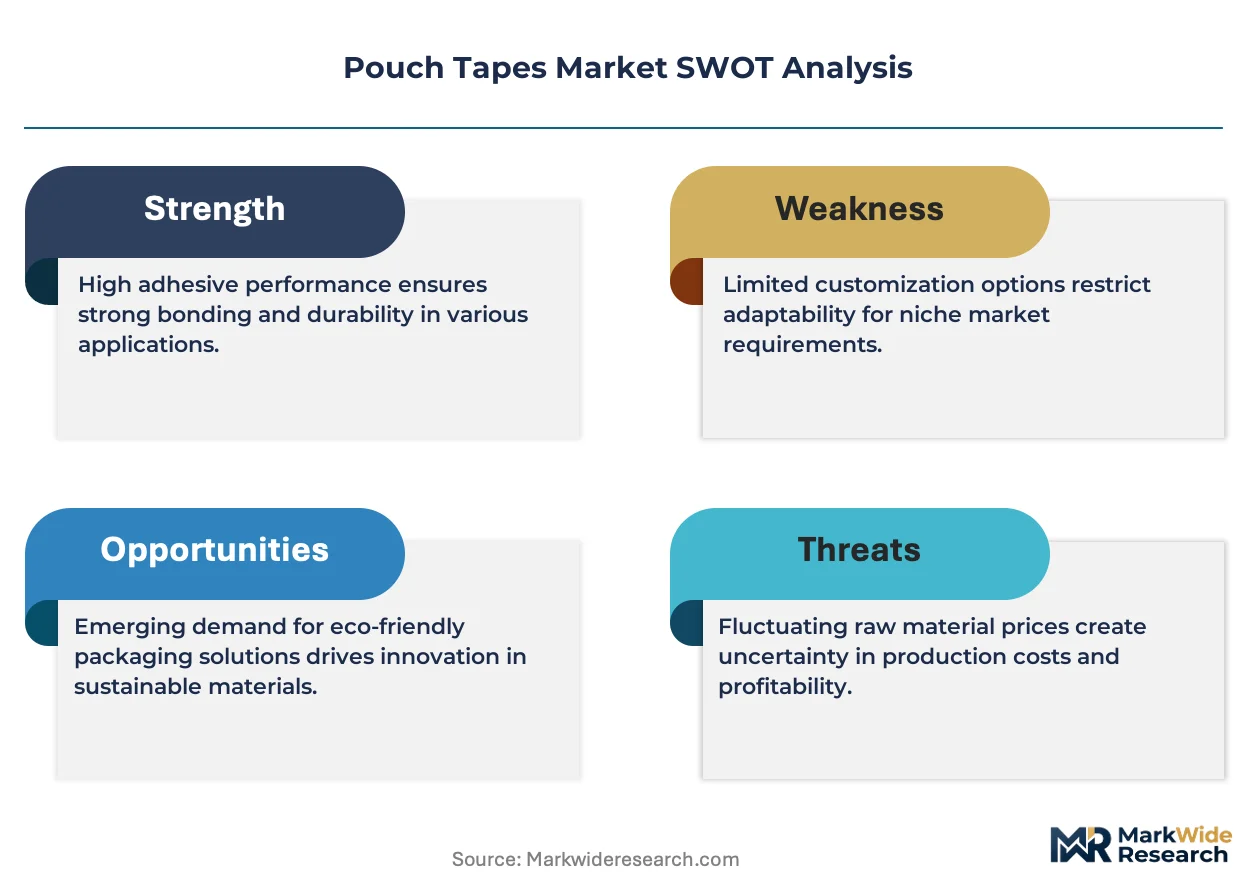
- Petrochemical feedstock volatility:Polypropylene carrier film costs fluctuate with propylene monomer pricing, squeezing converter margins.
- Southern European supply concentration:Integrated film-and-tape production clusters in Italy create geographic vulnerability to energy price shocks.
- Mechanical fastener substitution resilience:Zip-lock and heat-seal technologies retain cost advantage in low-value commodity pouch segments.
Strategic Opportunities
- India BIS certification gaps:Unqualified foreign suppliers face non-tariff barriers that create first-mover advantage for early certifiers.
- Electronics pouch assembly:Double-sided tape formats are capturing stack-up reduction mandates in smartphone and wearable device packaging.
- EU Green Deal procurement incentives:Public-sector packaging tenders are embedding recycled-content thresholds that reward circular adhesive systems.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with hot-melt rheology expertise command premium compensation in tight labor markets.
- Multi-jurisdiction certification lag:Parallel FDA food-contact substance and EFSA framework 10/2011 evaluations extend qualification timelines.
- Legacy mechanical sealing integration:Retrofitting automated lines for pressure-sensitive formats requires line-speed recalibration and operator retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pouch Tapes Market |
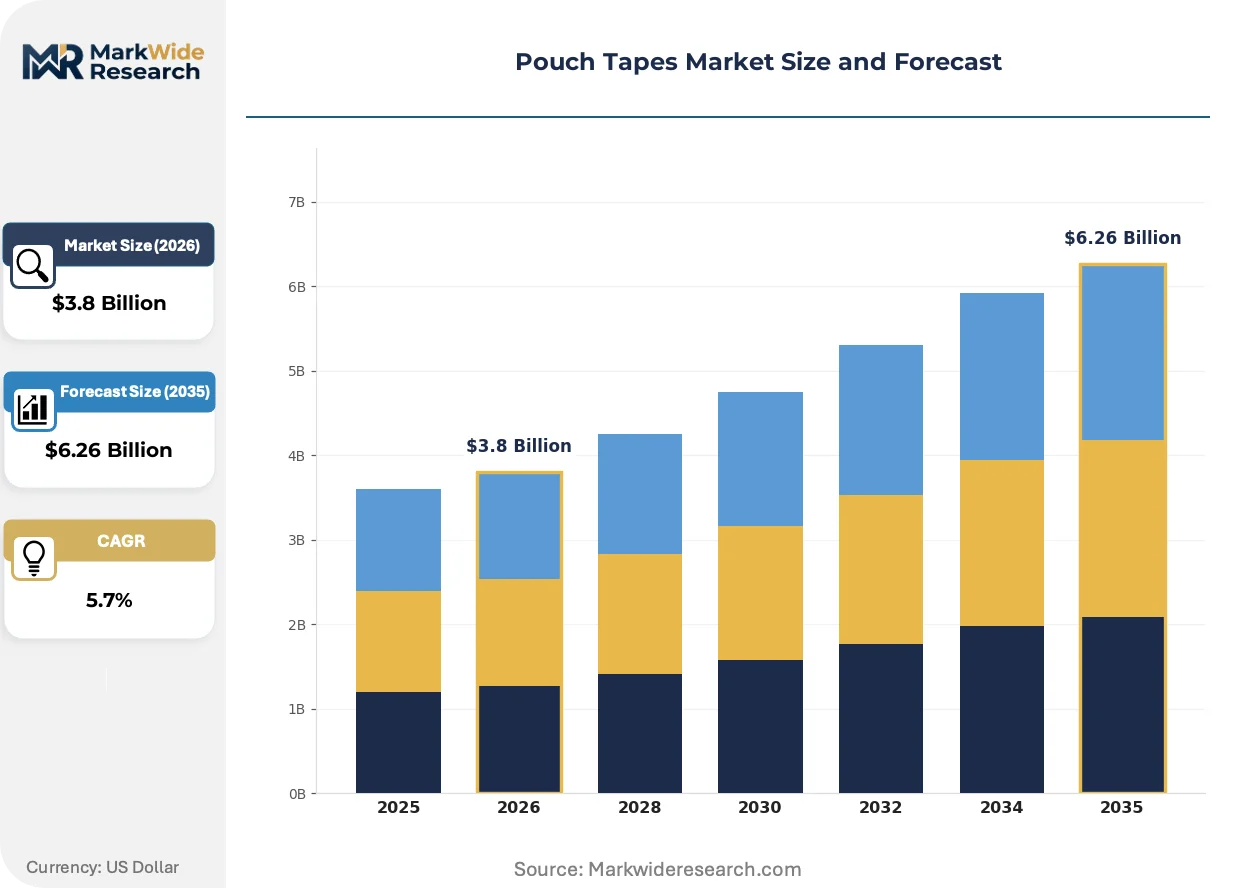
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tapes, Transparent Tapes, Masking Tapes, Specialty Tapes End User: Food Packaging, Electronics, Pharmaceuticals, Consumer Goods Material: Plastic, Paper, Foam, Cloth Application: Sealing, Bonding, Insulation, Labeling |
| Companies Covered | 3M, Irplast, Lynx Polythene, Flexopack, Raja SA, Test Valley Packaging, ULINE, BGR Packaging, Kilby Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pouch Tapes Market Evolving Landscape
Adhesive formulators are racing to align product roadmaps with divergent recyclability mandates across North America, Europe, and Asia-Pacific, compressing development cycles and favoring platforms with modular polymer architecture.
Water-based acrylic adhesive systems are integrating into high-throughput food packaging lines as converters seek to eliminate solvent handling infrastructure and reduce volatile organic compound emissions. Major European contract packagers are piloting these formats on existing polypropylene carriers without line-speed degradation. The technology is integrating sustainability reporting requirements into procurement scorecards, forcing tape suppliers to document carbon intensity per linear meter.
China's SAMR enforcement of GB standards for packaging material composition is tightening import specifications for adhesive formulations containing restricted phthalate plasticizers. Downstream brands sourcing from Yangtze River Delta contract packagers are demanding pre-certified tape stocks to avoid customs detention. Pharmaceutical cold-chain exporters are most affected, as they face dual compliance with SAMR migration limits and FDA food-contact substance notifications.
Mid-sized UK contract packagers are consolidating supplier relationships around flexible minimum-order-quantity programs that reduce working capital intensity. Direct procurement from integrated film-and-tape manufacturers is displacing distributor intermediaries in segments where technical specification support matters less than price and availability. This concentration is most visible in snack food and personal care pouch segments serving private-label retail channels.
Pouch Tapes Market Segmentation
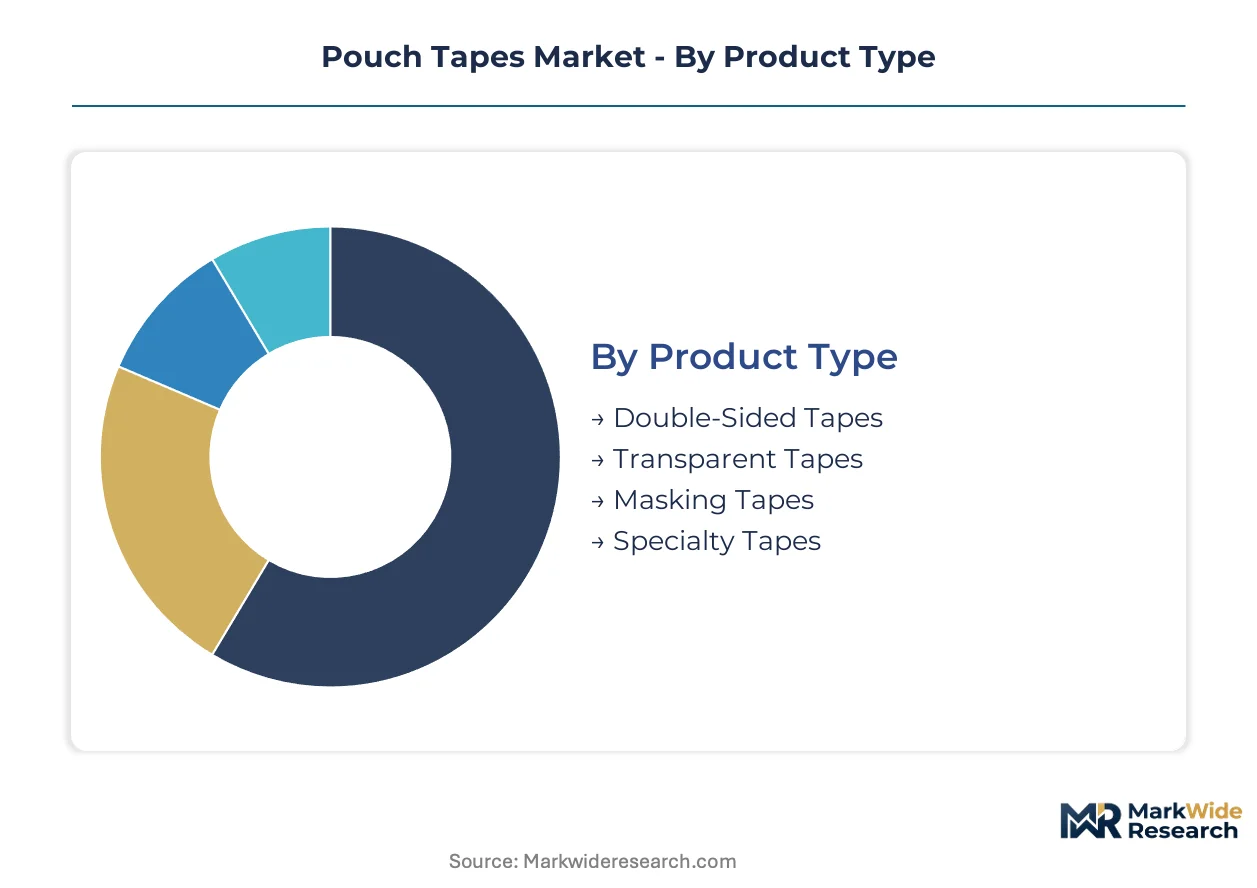
Pouch tape specification varies sharply by substrate compatibility, regulatory exposure, and line-speed requirements. Procurement teams segment primarily by adhesive chemistry and carrier material, with secondary filters for end-use certification and automated handling performance.
Product Type:
Supply concentration in solvent-free hot-melt capacity favors converters with integrated polymer science infrastructure over commodity assemblers.
- Transparent Tapes:Polypropylene film carriers with acrylic or rubber-based adhesives deliver optical clarity for barcode scanning and machine vision inspection. Food packaging lines in Germany's e-commerce fulfillment corridor specify these for high-throughput sealing where substrate visibility prevents rejection errors.
- Double-Sided Tapes:Pressure-sensitive adhesive layers on both faces of PET or tissue carriers enable stack-up reduction in electronics pouch assembly. Smartphone and wearable device manufacturers in China's Yangtze River Delta manufacturing corridor are displacing mechanical fasteners with these formats to achieve thinner device profiles.
- Masking Tapes:Crepe paper carriers with rubber adhesives serve temporary protection and paint-masking applications in consumer goods packaging workflows.
- Specialty Tapes:Low-temperature acrylic formulations maintain adhesion integrity in pharmaceutical cold-chain distribution where standard grades fail.
Today's leader: Transparent Tapes. Tomorrow's challenger: Double-Sided Tapes.
End User:
Cost tier differentiation separates premium-certified grades from commodity specifications across buyer categories.
- Food Packaging:FDA food-contact substance notifications and EFSA framework 10/2011 compliance govern adhesive migration limits for direct-contact applications. Major European contract packagers are piloting water-based acrylic systems to eliminate solvent handling infrastructure while maintaining line speeds.
- Pharmaceuticals:Temperature-stable adhesion specifications address biologics distribution risks where cold-chain failure triggers product spoilage. SAMR enforcement of GB standards in China creates dual compliance burdens for exporters.
- Electronics:Precision die-cutting and clean-room compatibility requirements favor thin-film carriers with controlled peel adhesion values.
- Consumer Goods:Flexible minimum-order-quantity programs from UK-based suppliers attract mid-sized contract packagers serving private-label retail channels.
Food Packaging commands current procurement volume. Pharmaceuticals present the steepest expansion trajectory as cold-chain infrastructure scales.
Material:
Volume concentration in polypropylene carriers reflects propylene monomer supply integration among major converters.
- Plastic:Polypropylene and polyethylene films dominate high-speed automated lines for their tensile strength and moisture resistance. EU Packaging and Packaging Waste Regulation recyclability mandates are compressing specification timelines for mono-material constructions.
- Paper:Kraft and crepe paper carriers serve masking and temporary bonding applications where biodegradability supports sustainability reporting.
- Foam:Polyethylene and polyurethane foam tapes provide gap-filling and cushioning in protective pouch designs for fragile electronics.
- Cloth:Woven fabric carriers reinforced with synthetic fibers deliver durability in heavy-duty industrial sealing applications.
Plastic retains manufacturing dominance. Paper gains share fastest as brands embed recycled-content thresholds into procurement scorecards.
Application:
Customer type segmentation separates OEM specification engineers from distributor procurement managers with varying technical support requirements.
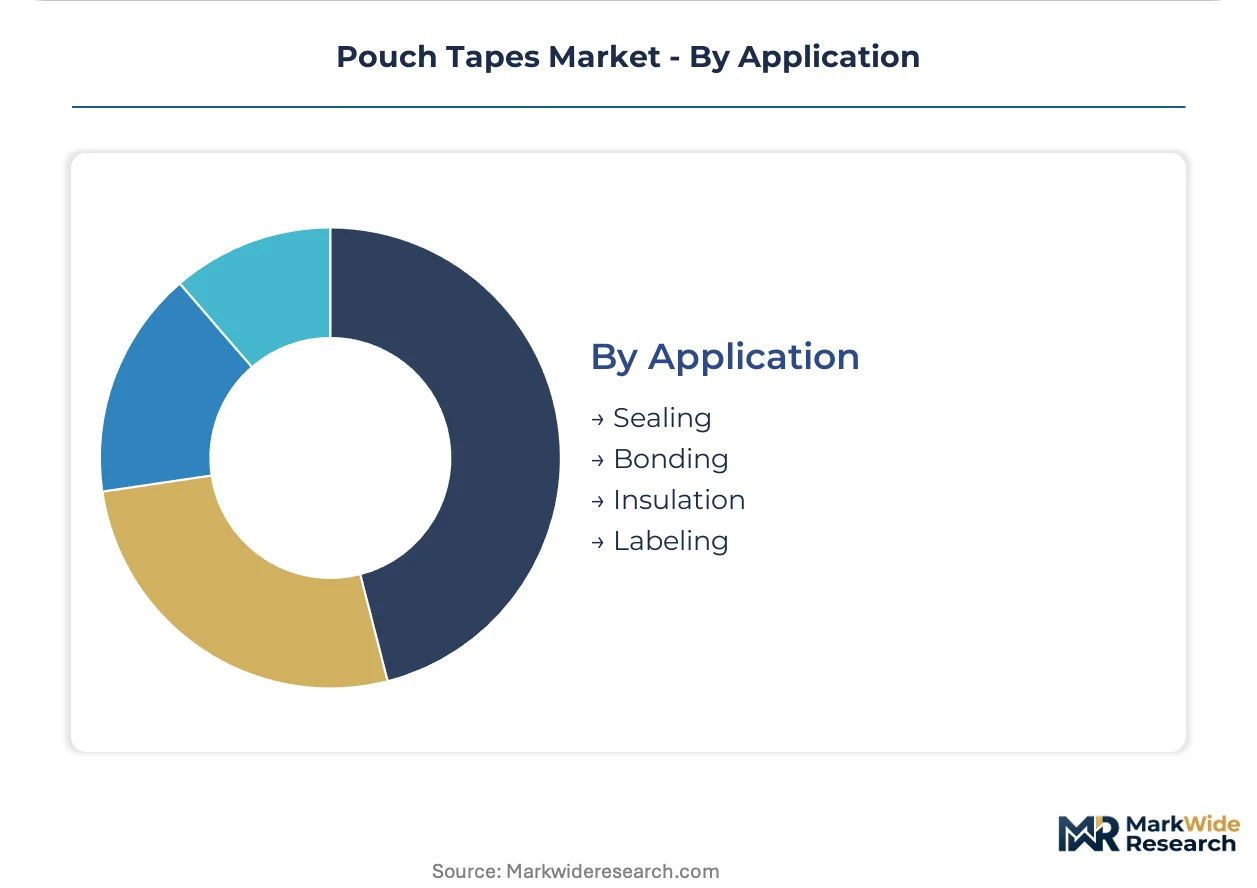
- Sealing:Tamper-evident closure creation on stand-up pouches, flat bags, and sachets represents the core industrial purpose. Automated packaging lines in Germany demand high-tack, low-variation performance from robotic sealing stations.
- Bonding:Structural adhesion in pouch assembly and lamination processes requires controlled rheology for clean bond lines without squeeze-out.
- Insulation:Thermal and electrical barrier functions in electronics packaging leverage foam and film tape dielectric properties.
- Labeling:Printable facestocks with permanent or removable adhesives integrate identification and branding functions into pouch surfaces.
Sealing anchors current demand. Bonding expands most quickly as electronics manufacturers pursue stack-up miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer scientists and adhesive formulators concentrate in industrial clusters near major contract packaging hubs, creating talent pipelines that shape regional competitive dynamics. Their expertise anchors formulation capabilities in specific geographies.
Germany
Automated packaging line deployment in e-commerce fulfillment centers drives specification demand for high-tack sealing solutions. REACH compliance pathways favor solvent-free hot-melt formulations that eliminate volatile organic compound exposure. The Rhine-Ruhr industrial corridor hosts integrated film-and-tape production facilities serving pan-European distribution networks.
China
Contract packagers in the Yangtze River Delta manufacturing corridor serve multinational consumer brands with volume-intensive procurement requirements. SAMR enforcement of GB standards for packaging material composition tightens import specifications for adhesive formulations. Shanghai and Suzhou anchor tape specification engineering for electronics pouch assembly serving smartphone manufacturers.
United States
FDA food-contact substance notifications govern adhesive migration limits for pouch tapes serving domestic food packaging lines. Cold-chain pharmaceutical expansion creates specification windows for temperature-stable specialty grades. The Midwest industrial belt concentrates converter operations near major CPG brand headquarters.
India
BIS certification requirements create non-tariff barriers that filter unqualified foreign suppliers from domestic procurement channels. Mid-sized contract packagers consolidate supplier relationships around flexible minimum-order-quantity programs. Maharashtra and Gujarat host emerging tape converting capacity serving South Asian export markets.
Italy
Integrated film-and-tape production campuses in Tuscany anchor southern European supply with captive polymer science infrastructure. EU Packaging and Packaging Waste Regulation recyclability mandates compress specification timelines for mono-material constructions. Energy price volatility in the region creates margin pressure on energy-intensive hot-melt coating operations.
Pouch Tapes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pouch tape value chain, creating tiered competitive dynamics. Integrated polymer science infrastructure separates formulation specialists from commodity converters. Three strategic archetypes dominate: multinational material science conglomerates with captive adhesive R&D, regional integrated film-and-tape manufacturers with geographic supply concentration, and flexible specialty converters serving niche certification requirements. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for solvent-free qualification cycles.
Among diversified material science conglomerates, 3M occupies a position exemplifying polymer science infrastructure leveraged for regulatory-compliant formulation development. Regional integrated manufacturers include Irplast, whose Tuscan production campus represents southern European supply concentration, and Lynx Polythene, which sits within the UK-based flexible converter tier serving mid-sized contract packagers with variable volume requirements.
| Leading Market Players |
|---|
| 3M |
| Irplast |
| Lynx Polythene |
| Flexopack |
| Raja SA |
| Test Valley Packaging |
| ULINE |
| BGR Packaging |
| Kilby Packaging |
| Others |
Value Network & Pricing Analysis
Mid-sized UK contract packagers concentrate procurement leverage through flexible minimum-order-quantity programs, anchoring pricing power in volume consolidation rather than specification premium.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cold-chain grades from food-contact certified tapes from commodity sealing products. Price differentiation hinges on REACH compliance certification and volume scale commitments. Cost compression in standard food-packaging tiers is intensifying because water-based acrylic formulations eliminate solvent handling infrastructure investments. Mid-sized contract packagers exhibit highest price sensitivity, while biologics distributors accept premium positioning for temperature-stable adhesion specifications.
Supply Chain Analysis
Single-source vulnerability sits with propylene monomer feedstock dependence tethered to petrochemical complexes in Germany, China, and the United States. Raw material procurement draws from polypropylene carrier films, acrylic and rubber-based adhesive resins, and release liner substrates. Tariff exposure on imported adhesive formulations containing restricted phthalate plasticizers threatens margin stability under China's SAMR enforcement. Distribution runs through integrated film-and-tape manufacturers displacing distributor intermediaries in segments where technical specification support carries lower priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory tightening, with EU Packaging and Packaging Waste Regulation recyclability mandates accelerating specification turnover and adhesive reformulation demand.
For Market Incumbents: Anticipate solvent-free hot-melt qualification cycles compressing development timelines by investing in captive polymer science infrastructure before commodity converters achieve REACH-compliant scale. Defend margin position through backward integration into propylene monomer supply chains in the Rhine-Ruhr corridor, neutralizing feedstock volatility that squeezes unintegrated competitors. For New Entrants and Emerging Players: Mid-sized Indian contract packagers face BIS certification barriers that filter unqualified foreign suppliers, creating first-mover windows for early certifiers with flexible volume programs. Capture specification share in electronics pouch assembly by offering precision die-cut double-sided formats with clean-room compatibility, displacing mechanical fasteners in Yangtze River Delta smartphone manufacturing. For Investors and Strategic Acquirers: Specialty chemical conglomerates with adhesive divisions are the most active acquirer in this space, targeting regional integrated film-and-tape manufacturers with Tuscan or UK geographic concentration. Long-term viability favors assets with modular polymer architecture capable of rapid solvent-free pivot. Monitor EU Green Deal public-sector tender thresholds embedding recycled-content requirements as the inflection signal for circular adhesive system premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Hot-Melt Capacity Expansion | REACH compliance pathways favor polymer science infrastructure over commodity assemblers in Germany. |
| Backward Integration into Propylene Supply | Captive feedstock sourcing neutralizes petrochemical margin volatility for Rhine-Ruhr converters. |
| BIS Certification Pre-Investment | Early qualification creates non-tariff barrier leverage in Maharashtra and Gujarat procurement channels. |
| Water-Based Acrylic Line Conversion | Eliminates solvent handling infrastructure while maintaining line speeds for European food packagers. |
| Electronics Pouch Assembly Partnership | Double-sided precision formats capture stack-up reduction mandates from Yangtze River Delta OEMs. |
Research Methodology
Direct dialogue with adhesive formulation chemists, contract packaging procurement directors, polymer science R&D heads, and regulatory affairs specialists at tape converters grounded qualitative insights. Secondary validation drew from EFSA framework submissions, REACH registration dossiers, BIS certification records, and customs trade data on polypropylene film imports. Bottom-up and top-down triangulation cross-checked volume estimates against propylene monomer consumption patterns and end-use packaging line deployment metrics.
Bottom-up modeling built from adhesive grade specifications, carrier material tonnages, and line-speed throughput assumptions across food, pharmaceutical, electronics, and consumer goods applications. Top-down verification anchored against EU packaging waste directive compliance spending and e-commerce fulfillment center automation capex trajectories. CAGRs derived from segment-level growth differentials reflecting regulatory qualification timelines and substitution elasticity between pressure-sensitive and mechanical sealing formats.
Underlying measurement precision varies by segment; transparent food-packaging tapes carry tighter precision than emerging double-sided electronics formats. Forecasts reflect assumptions on REACH enforcement intensity, SAMR import detention rates, and cold-chain pharmaceutical infrastructure buildout. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Washi Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Umbilical Tapes Market
Tapes
Correction Tapes Market
Tapes
Invisible Tapes Market
Tapes
Building and Construction Tapes Market
Tapes
Global Non Woven Tape Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Smart Card Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Dry Wall Tapes Market
Tapes
Cable Wrapping Tapes Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Raffia Tapes Market