
 Lacing Tape Market | 2026-2036
Lacing Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Lacing Tape Market Analytics
The EU Green Deal is realigning material specifications across European supply chains, compelling lacing tape producers to reformulate toward lower-carbon inputs. 3M Company leverages its polymer science portfolio to develop adhesive-backed lacing solutions for industrial harnessing. Tesa SE anchors its position through precision coating capabilities that serve automotive wire bundling applications. Saint-Gobain Performance Plastics dominates high-temperature lacing segments with silicone- and fiberglass-reinforced constructions.
Lacing tape comprises narrow-width textile strips engineered for binding, securing, and tension-management functions, typically manufactured through weaving, braiding, or knitting processes with tensile strengths ranging from 50 to 1,000 pounds depending on fiber construction and end-use requirements. Woven constructions occupy the largest share of industrial demand due to dimensional stability and abrasion resistance, while elastic variants represent the fastest-expanding category as sportswear brands integrate stretch recovery into closure systems. Polyester and nylon material grades capture the dominant margin pools because petrochemical-derived fibers offer superior strength-to-weight ratios and dye consistency compared with cotton alternatives.
FDA regulations govern lacing tapes employed in medical device strapping and patient restraint applications, while OSHA standards influence industrial-grade specifications for workplace safety equipment. REACH compliance in Europe restricts certain chemical finishes and dye carriers, elevating certification costs for suppliers serving multiple jurisdictions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across major economies, as these compound coating chemistries face phased elimination that will force reformulation investments and supply base qualification cycles.
Market Dynamics
The EU Green Deal is unifying material sourcing requirements across European supply chains, compelling lacing tape producers to reformulate toward recycled polyester and bio-based alternatives while athletic footwear brands simultaneously pursue lighter closure systems.
Growth Catalysts
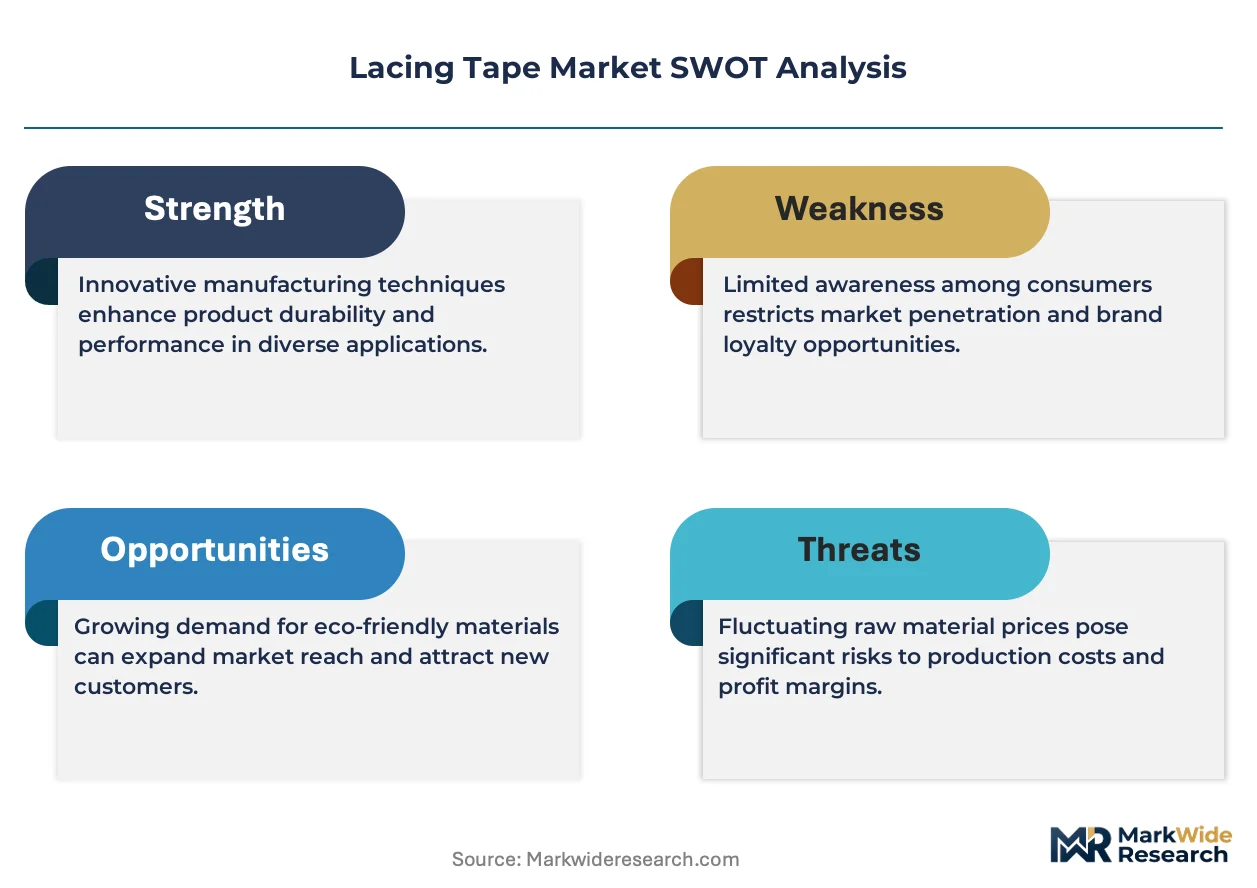
- REACH compliance evolution:Chemical finish restrictions are elevating certification barriers that favor established compounders with reformulation capabilities, consolidating margin pools among compliant suppliers.
- Athletic footwear lightweighting:Brands are integrating woven and elastic lacing tapes into performance closure systems, expanding specification volumes for tensile-optimized constructions.
- China-Vietnam production clustering:Concentrated textile manufacturing infrastructure in these markets absorbs capital investment and captures scale efficiencies in narrow-width weaving.
Market Restraints
- Petrochemical input volatility:Polyester and nylon resin prices fluctuate with crude oil derivatives, compressing margin stability for fiber-grade tape producers.
- Per- and polyfluoroalkyl substance elimination:Phased restrictions across major economies force compound coating reformulations and extended supply base qualification cycles.
- Silicone-reinforced construction concentration:High-temperature lacing capacity concentrates among specialized compounders, creating supply bottleneck risk for industrial harnessing applications.
Strategic Opportunities
- India domestic manufacturing expansion:The PLI scheme for textiles incentivizes localized narrow-width weaving capacity to serve regional automotive and medical device demand.
- Wire bundling electrification:Electric vehicle platform architectures are expanding automotive harnessing specifications for adhesive-backed lacing solutions.
- Bio-based polymer convergence:Polyhydroxyalkanoate and polylactic acid fiber developments are enabling performance parity claims in sustainable athletic footwear closures.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with adhesive-coating expertise command premium compensation, constraining R&D throughput for mid-tier producers.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and OSHA qualification requirements extend product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lacing Tape Market |
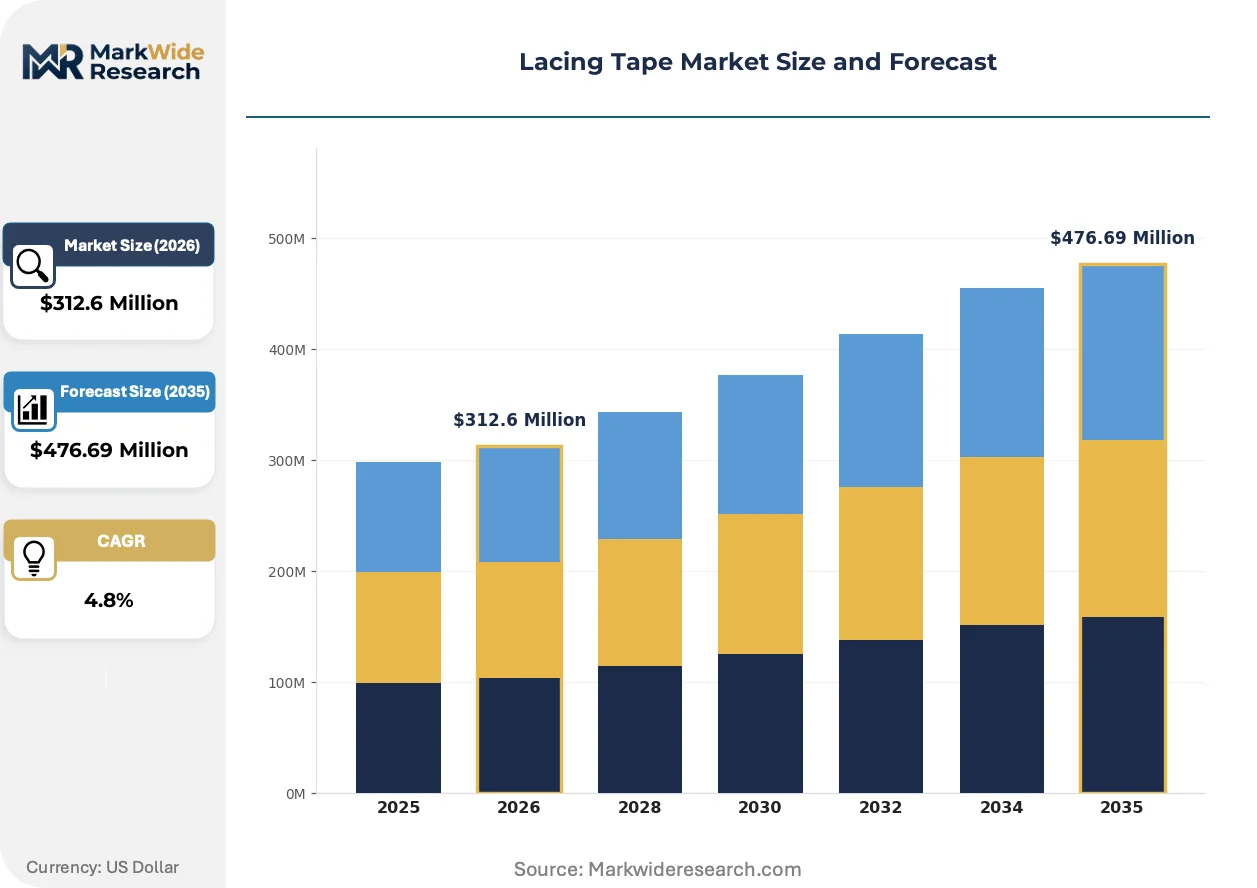
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $476.69 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven, Non-woven, Braided, Elastic Material: Cotton, Polyester, Nylon, Polypropylene Application: Footwear, Bags, Gloves, Industrial Distribution Channel: Online, Offline, Direct, Wholesalers |
| Companies Covered | 3M Company, Nitto Denko Corporation, Tesa SE, Intertape Polymer Group, Avery Dennison Corporation, Scapa Group, Lintec Corporation, Saint-Gobain Performance Plastics, Shurtape Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lacing Tape Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape fiber selection and coating formulations across industrial, medical, and consumer applications.
Elastic recovery technology is unifying stretch and stability functions previously served by separate mechanical components. Sportswear brands in Germany and the United States are specifying knitted lacing tapes with 300% elongation recovery for dynamic fit adjustment. This convergence is compressing supplier counts as compounders must master both textile engineering and polymer elasticity.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy water-repellent finishes from medical-grade lacing tapes. European medical device manufacturers face reformulation deadlines that disqualify existing supply base qualifications. The strapping and patient restraint segment is responding by accelerating bio-based coating validation programs with notified bodies.
Direct material specification by footwear brand technical teams is displacing traditional converter-mediated procurement in athletic closure systems. Design studios in Portland and Amsterdam now issue fiber denier and tensile strength requirements directly to narrow-width weavers. This pattern is most visible in performance running and basketball categories where closure system weight targets have tightened below fifteen grams per shoe.
Lacing Tape Market Segmentation
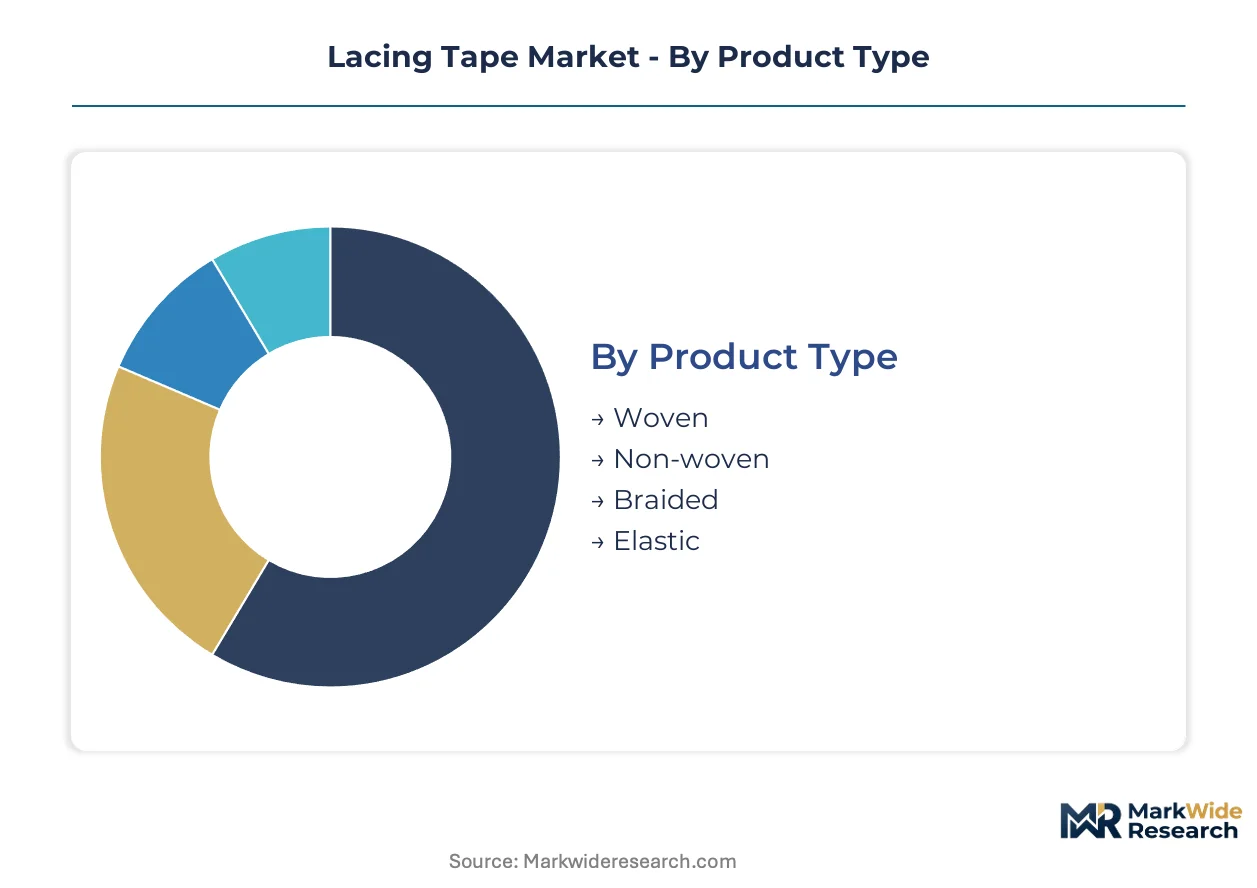
Lacing tape specifications diverge sharply across end-use requirements, with athletic footwear demanding stretch recovery and industrial harnessing prioritizing tensile strength. Material selection and weave construction determine margin profiles, while distribution channels reflect customer scale and technical support needs.
Product Type:
Customization intensity varies from engineered elastic constructions to standardized woven formats.
- Woven:Interlaced warp and weft constructions deliver dimensional stability and abrasion resistance for industrial wire bundling and safety harness applications. Automotive OEMs in Germany and Japan specify polyester and nylon woven grades for engine compartment temperature tolerance. REACH chemical finish restrictions are elevating certification costs for European suppliers of industrial-grade woven tapes.
- Elastic:Knitted constructions incorporating spandex or rubber cores enable 200-400% elongation recovery for dynamic fit adjustment in performance athletic footwear. Portland-based design studios now issue direct specifications for elastic lacing tapes with sub-fifteen-gram closure system weight targets. This segment is gaining share fastest as sportswear brands consolidate mechanical closure functions into single textile components.
- Non-woven:Bonded fiber mats provide economical binding for disposable medical strapping and temporary packaging applications.
- Braided:Tubular constructions from interlaced yarns offer uniform stress distribution for marine cordage and decorative accessories.
Leading the category by volume: Woven. Growing fastest: Elastic.
Material:
Cost tiers stratify from commodity petrochemical fibers to specialty bio-based alternatives.
- Polyester:Petrochemical-derived filament dominates industrial and footwear applications due to superior strength-to-weight ratios, dye consistency, and moisture resistance. Recycled PET feedstocks are capturing specification share as EU Green Deal compliance requirements tighten across European supply chains. Crude oil derivative price volatility compresses margin stability for virgin polyester producers.
- Nylon:Polyamide grades deliver exceptional abrasion resistance and fatigue life for high-cycle industrial harnessing and premium athletic closures. Vietnam and China concentrate nylon lacing tape weaving capacity for export to North American footwear brands. PA6 and PA66 resin price fluctuations track benzene and caprolactam markets.
- Cotton:Natural fiber constructions serve heritage footwear aesthetics and medical applications requiring skin breathability.
- Polypropylene:Lightweight olefin tapes offer chemical resistance for marine and outdoor equipment binding at lower cost points.
Polyester commands the largest volume position. Nylon exhibits the steepest expansion trajectory in high-performance segments.
Application:
Customer sophistication ranges from technical footwear engineering to commodity packaging procurement.
- Footwear:Athletic brands integrate woven and elastic lacing tapes into performance closure systems with tightening weight specifications. Direct material specification by Portland and Amsterdam design studios is displacing traditional converter-mediated procurement. FDA and OSHA qualification requirements extend product launch cycles for medical and safety footwear applications.
- Industrial:Wire bundling, safety harness, and equipment securing applications demand tensile strengths from 50 to 1,000 pounds. Electric vehicle platform architectures are expanding automotive harnessing specifications for adhesive-backed lacing solutions. Silicone-reinforced high-temperature capacity concentrates among specialized compounders.
- Bags:Closure and compression functions for luggage, backpacks, and technical equipment.
- Gloves:Wrist cinching and retention systems for protective and athletic handwear.
Industrial applications lead by volume. Footwear is climbing the fastest as lightweighting specifications proliferate.
Distribution Channel:
Supply concentration dictates channel efficiency, with scale buyers bypassing intermediaries.
- Direct:Major athletic footwear brands and automotive Tier-1 suppliers negotiate direct contracts with narrow-width weavers for volume and customization. Technical teams specify fiber denier, tensile strength, and coating chemistry without converter involvement. This channel captures the highest margin pool through specification ownership.
- Wholesalers:Regional distributors aggregate demand from smaller industrial users and specialty manufacturers requiring technical support and mixed-SKU procurement.
- Online:E-commerce platforms serve prototype developers, small-batch footwear startups, and replacement part markets with catalog-standard specifications.
- Offline:Traditional brick-and-mortar industrial supply houses serve maintenance-repair-operations procurement with immediate availability.
Direct channels dominate value capture. Online is expanding most quickly for small-scale technical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Vietnam, and India concentrate lacing tape manufacturing capacity, while the United States and Germany drive specification standards through footwear and automotive OEM procurement. This production-consumption divide shapes trade flows and regulatory compliance requirements across supplier networks.
China
Shanghai and Zhejiang Province house dense clusters of narrow-width weaving operations serving export markets. MIIT industrial standards govern textile chemical finishes for domestic medical device applications. The Yangtze River Delta absorbs capital investment in polyester filament capacity as brands demand recycled PET feedstock verification.
Vietnam
Ho Chi Minh City and Hanoi corridors host footwear-focused lacing tape operations supplying Nike and Adidas assembly plants. The country's national textile regulator enforces chemical safety protocols for export-bound medical-grade tapes. Binh Duong Province concentrates elastic construction capacity for performance athletic closure systems.
United States
Portland, Oregon and Boston, Massachusetts design studios specify fiber denier and tensile requirements directly to Asian weavers. FDA regulations govern medical strapping applications, while OSHA standards influence industrial safety harness procurement. The domestic market relies on imported narrow-width textiles with limited captive weaving capacity.
Germany
Bavaria and Baden-Württemberg anchor automotive wire bundling demand through BMW and Mercedes-Benz supply chains. REACH compliance deadlines force reformulation of water-repellent coating chemistries by European medical device manufacturers. The Stuttgart industrial cluster specifies silicone-reinforced high-temperature grades for electric vehicle harnessing.
India
Tamil Nadu and Gujarat states expand narrow-width weaving capacity under the PLI scheme for textiles. CDSCO regulations shape medical device strapping specifications for domestic hospital procurement. The Tiruppur knitwear cluster sources elastic lacing tapes for export-oriented athletic apparel manufacturers.
Lacing Tape Market Competitive Landscape
The competitive structure tilts toward diversified materials conglomerates with polymer science capabilities and precision coating expertise. Saint-Gobain Performance Plastics and 3M Company anchor high-performance segments through silicone-reinforced and adhesive-backed constructions. Three archetypes dominate: petrochemical-derived fiber specialists, precision coating compounders, and diversified industrial tape manufacturers. Capacity expansion and supply base qualification acceleration represent the dominant competitive moves as REACH and PFAS restrictions compress reformulation timelines.
Among diversified materials conglomerates, 3M Company and Saint-Gobain Performance Plastics occupy positions defined by polymer science depth and high-temperature construction expertise. Tesa SE exemplifies the precision coating archetype through adhesive-backed solutions for automotive harnessing. Japanese manufacturers including Nitto Denko Corporation and Lintec Corporation represent the Asia-Pacific production base with integrated film and tape capabilities. These anchors illustrate how competitive positioning depends on reformulation agility and multi-jurisdiction certification throughput rather than scale alone.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| Tesa SE |
| Intertape Polymer Group |
| Avery Dennison Corporation |
| Scapa Group |
| Lintec Corporation |
| Saint-Gobain Performance Plastics |
| Shurtape Technologies |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap weavers in Zhejiang Province and Tamil Nadu anchor narrow-width textile production, transmitting feedstock cost volatility directly into contract negotiations with Portland and Amsterdam footwear design studios while maintaining pricing discipline through direct specification relationships.
Pricing Analysis
Margin tightening in standard-grade polyester woven tapes reflects benzene and caprolactam resin volatility, while premium elastic constructions with spandex cores command pricing premiums based on REACH certification tiers and direct technical collaboration with athletic brand R&D teams. Three-tier pricing structure across premium silicone-reinforced, standard industrial-grade, and economy non-woven levels stratifies the market, with automotive OEM procurement showing lowest price sensitivity due to harnessing reliability requirements and small-batch footwear startups exhibiting highest elasticity.
Supply Chain Analysis
Polyester filament supply rests on petrochemical complexes in China, South Korea, and Saudi Arabia, with spandex fiber production concentrating among specialty chemical producers in Singapore and Germany. Raw material dependencies span purified terephthalic acid, caprolactam, and diphenylmethane diisocyanate for polyurethane cores. Single-source vulnerability in medical-grade coating chemistries intensifies as ECHA accelerates PFAS elimination timelines. Distribution runs through direct contracts for volume buyers and regional wholesalers serving fragmented industrial maintenance-repair-operations demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lacing tape market sits at a materials-transition inflection as bio-based polyhydroxyalkanoate fibers displace virgin polyester in EU-bound athletic footwear supply chains.
For Market Incumbents: Lock in reformulation capabilities ahead of REACH Annex XVII expansion by qualifying bio-based coating chemistries with notified bodies and securing backward integration into recycled PET feedstock streams. Saint-Gobain and 3M demonstrate how polymer science depth defends margin pools against commodity polyester competitors. For New Entrants and Emerging Players: Small-batch footwear startups in Amsterdam and Seoul represent the most penetrable buyer archetype, underserved by minimum-order-quantity barriers at established narrow-width weavers. A digital-first sampling and rapid-prototyping service model bypasses traditional converter relationships. For Investors and Strategic Acquirers: CDSCO medical device registration acceleration in India is the leading indicator that domestic elastic lacing demand will outpace supply, creating acquisition opportunities for precision coating specialists with existing BIS certification infrastructure. Target mid-cap compounders with dual automotive-footwear qualification pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | Qualification with ECHA-notified bodies secures EU medical device supply continuity. |
| Recycled PET Feedstock Integration | EU Green Deal verification requirements favor suppliers with closed-loop polyester sourcing. |
| Direct Technical Sales to Footwear Studios | Bypassing converters captures specification ownership and margin in athletic closure systems. |
| Silicone-Reinforced Capacity Expansion | Electric vehicle harnessing demand outstrips specialized high-temperature compounder supply. |
| India PLI-Backed Weaving Capacity | Domestic narrow-width production serves CDSCO-regulated medical strapping and automotive Tier-1 demand. |
Research Methodology
Document review covered customs trade databases, ECHA regulatory filings, and SEC 10-K disclosures from materials conglomerates, complemented by interviews with narrow-width weaving plant managers, athletic footwear procurement leads, automotive Tier-1 harness engineers, and medical device regulatory affairs specialists. Secondary sources included MIIT industrial standards, CDSCO device registration records, and EU Green Deal implementation guidance. Bottom-up capacity assessments and top-down demand modeling were triangulated against primary field intelligence.
Segment-level value and volume trajectories across the analysis window were derived from weave construction type, material grade tier, end-use application intensity, and regional regulatory cluster. CAGRs were computed from fitted growth curves incorporating polyester resin price elasticity coefficients, footwear brand lightweighting specification timelines, and electric vehicle platform harnessing content per vehicle estimates.
Revisions become necessary when REACH chemical restriction timelines accelerate, PFAS elimination deadlines shift, or major footwear brands consolidate supplier counts beyond modeled thresholds. A small set of named triggers—ECHA Annex XVII expansion scope, EU Green Deal recycled content mandates, and CDSCO medical device registration velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Medical Tapes Market
Tapes
Carton Sealing Tape Market
Tapes
Industrial Tapes Market
Tapes
India Masking Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Thermal Transfer Tapes Market
Tapes
Silicone Tape Market
Tapes
Tape Backing Materials Market
Tapes
Unidirectional Tapes Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Thread Seal Tape Market
Tapes
Double Coated Film Tapes Market
Tapes
Labels, Tapes and Films Market
Tapes
Seam Tapes Market
Tapes
Umbilical Tapes Market
Tapes
Pucker Free Tapes Market