
 Reflective Tape Market | 2026-2036
Reflective Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Reflective Tape Market Outlook
A capital-intensity divergence between integrated resin producers and downstream converters is redrawing competitive boundaries in reflective tape manufacturing. 3M leverages captive polymer science and optical film extrusion to sustain margin capture across engineering-grade and microprismatic lines. ORAFOL Europe GmbH anchors its position through precision-coated prismatic technologies that dominate premium conspicuity segments for commercial vehicle OEMs.
Reflective tape comprises retroreflective sheeting engineered with glass beads or microprismatic arrays bonded to polyester, PVC, or acrylic substrates, manufactured through precision coating, embossing, and metallization processes to return incident light toward its source. The material's primary commercial purpose is to enhance nighttime visibility of vehicles, road signage, and personal protective equipment under headlamp illumination. Microprismatic and high-intensity types command the strongest margin pools due to tighter optical tolerances and longer service life, while polyester-based substrates lead volume through balance of durability and cost in traffic control and work zone applications. Safety gear and emergency vehicle end users represent the fastest-expanding demand channels as occupational safety enforcement tightens across industrial jurisdictions.
The Federal Motor Carrier Safety Administration, the European Committee for Standardization through EN 12899 and EN 13356, and the Federal Highway Administration through MUTCD compliance frameworks collectively shape product certification pathways and procurement eligibility for reflective tape suppliers. REACH chemical restrictions and evolving RoHS substance limits further constrain adhesive and substrate formulations, elevating compliance costs for non-integrated converters. Stakeholders must monitor regulatory divergence between North American and European retroreflectivity test methods when configuring regional product portfolios and certification investments.
Market Dynamics
Retroreflective performance standards are tightening across major automotive and infrastructure jurisdictions, forcing converters to abandon glass-bead films for microprismatic architectures with tighter optical tolerances and longer field durability. This specification escalation compresses margins for non-integrated suppliers while rewarding captive polymer science capabilities.
Growth Catalysts
- FMCSA truck conspicuity mandates:United States DOT requirements for retroreflective striping on commercial trailers sustain replacement demand cycles and specification upgrades across the North American fleet.
- EN 12899 retroreflectivity thresholds:European road signage authorities are expanding procurement of high-visibility markings, pushing microprismatic film adoption for traffic control applications.
- Work zone safety enforcement:Occupational safety regulators in Germany and France are mandating enhanced visibility gear for highway maintenance crews, accelerating personal protective equipment channel demand.
Market Restraints
- Petrochemical input volatility:Acrylic and polyester substrate costs fluctuate with propylene and PTA feedstock pricing, compressing converter margins during supply shocks.
- Prismatic master roll concentration:Precision embossing equipment and optical-grade resin supply concentrate among integrated North American and European producers, limiting second-source options.
- REACH adhesive restrictions:ECHA substance limits on solvent-based chemistries constrain formulation flexibility and extend R&D validation timelines for European product lines.
Strategic Opportunities
- Emergency vehicle specification upgrades:Fire apparatus and ambulance OEMs in the United States are adopting multi-color prismatic configurations for enhanced nighttime recognition.
- India infrastructure build-out:National highway expansion programs create virgin demand for traffic signage sheeting as state-level procurement capacity matures.
- Digital printing compatibility:UV-curable ink adhesion advances enable short-run customization for fleet graphics, opening service bureau channels beyond traditional converter networks.
Industry Challenges
- Optical metrology talent scarcity:Precision goniophotometry and retroreflectivity testing require specialized technicians that converter operations struggle to recruit and retain.
- Multi-jurisdiction certification burden:ASTM D4956, EN 12899, and CSA D250.1 testing protocols demand parallel validation investments for suppliers serving transatlantic customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflective Tape Market |
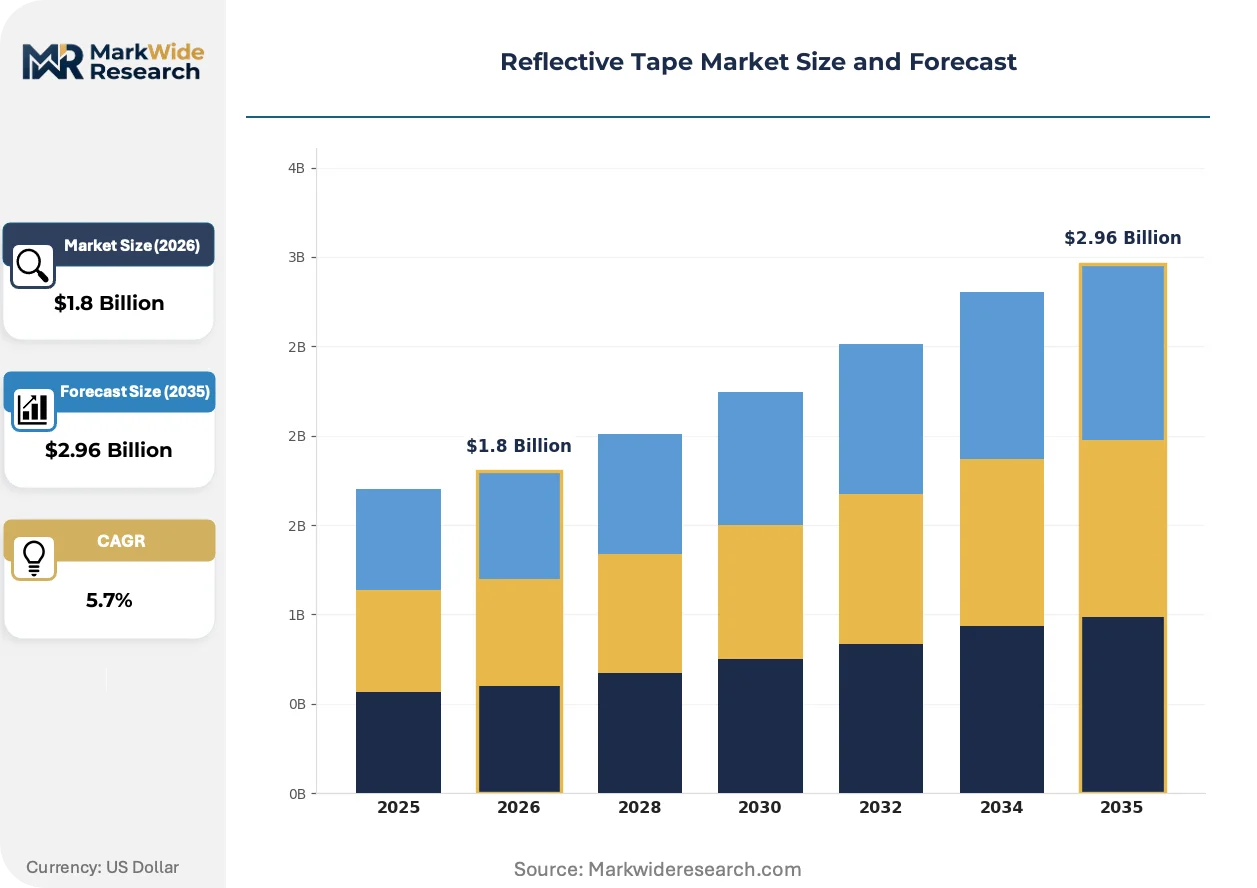
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyester, PVC, Polycarbonate, Acrylic End User: Automotive, Safety Gear, Road Signage, Apparel Application: Traffic Control, Emergency Vehicles, Work Zones, Sports Equipment Type: Engineering Grade, High-Intensity, Microprismatic, Conspicuity |
| Companies Covered | DuPont, Paiho Group, 3M, Reflomax Co., Ltd, SKC, Avery Dennison Corporation, Nitto Denko Corporation, Changzhou Hua R Sheng Reflective Material Co., Ltd., ORAFOL Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflective Tape Market Strategic Shifts
Specification convergence between automotive conspicuity and traffic signage applications is eroding traditional product category boundaries, forcing manufacturers to engineer multi-purpose film platforms. Three developments are actively restructuring competitive positioning.
Microprismatic film technology is fragmenting the historical dominance of enclosed-lens glass-bead constructions across high-performance segments. Commercial vehicle OEMs in the United States and premium signage authorities in Germany are specifying full-cube prismatic arrays for superior angularity performance. This specification migration is fragmenting converter customer bases into performance-tier segments with diverging technical service requirements.
ASTM D4956-21 retroreflectivity minimums are compressing the viable supply base for engineering-grade traffic signage sheeting. State DOT qualification programs in the United States are rejecting legacy bead-based submissions for interstate applications. Sign fabricators are responding by consolidating supplier relationships toward vertically integrated film producers with captive optical testing laboratories.
Fleet maintenance departments are unbundling retroreflective striping from body shop contracts and sourcing directly through industrial distributors with cut-to-length capabilities. This channel pivot compresses converter margins but expands addressable volume for precision-slitting operations with same-day turnaround. The behavior shift is most visible among for-hire trucking operators in the United States managing DOT audit compliance internally.
Reflective Tape Market Segmentation
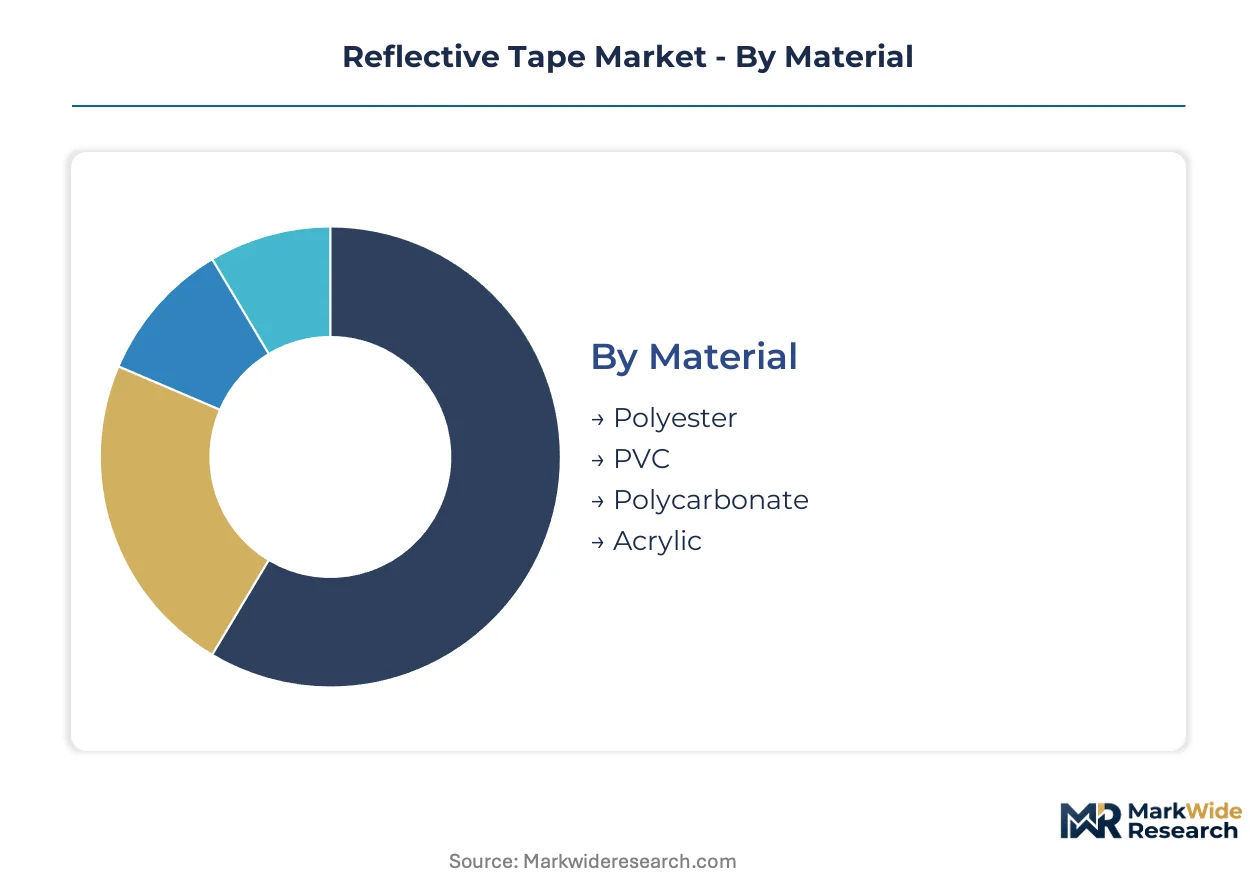
Reflective tape segmentation reveals divergent margin architectures across material chemistry and optical performance tiers. Procurement specifications from FMCSA, EN 12899, and state DOTs fragment demand into compliance-driven categories with incompatible certification pathways.
Material:
Polyester faces substitution pressure from polycarbonate in high-durability traffic signage applications where UV resistance and impact strength override cost considerations.
- Polyester:Thermoplastic polymer substrate balances tensile strength with coating adhesion for standard conspicuity striping and work zone apparel. Demand concentrates in United States fleet maintenance channels where FMCSA mandates drive replacement volume for commercial trailers.
- Acrylic:Optical-grade resin formulation delivers superior weathering resistance and prismatic embossing fidelity for premium microprismatic films. German road signage authorities specify acrylic-based sheeting for autobahn applications where EN 12899 retroreflectivity thresholds are most stringent.
- PVC:Flexible vinyl substrate serves cost-sensitive temporary traffic control devices and disposable safety gear with shorter service life requirements.
- Polycarbonate:High-impact thermoplastic penetrates emergency vehicle marking segments requiring abrasion resistance during frequent equipment washing cycles.
Polyester retains volume leadership; acrylic holds the steepest expansion curve.
End User:
Cost tier stratification separates specification-heavy automotive OEM contracts from price-elastic apparel procurement.
- Automotive:Commercial vehicle and emergency apparatus OEMs mandate certified conspicuity striping with documented retroreflectivity degradation curves. United States DOT audit compliance programs sustain replacement demand across for-hire trucking fleets.
- Safety Gear:Industrial distributors supply EN 13356-compliant personal protective equipment to German and French highway maintenance contractors under tightening occupational visibility enforcement.
- Road Signage:State and federal transportation departments procure ASTM D4956-qualified sheeting for interstate highway signage with 10-12 year durability specifications.
- Apparel:Fashion and recreational applications outside regulatory compliance frameworks compete on color range and washability rather than optical performance metrics.
Automotive commands the premium pricing tier; safety gear is expanding most quickly.
Application:
Volume concentration in traffic control contrasts with margin concentration in emergency vehicle specialization.
- Traffic Control:Permanent and temporary roadway signage consumes the largest substrate tonnage, with state DOT qualification programs consolidating supplier relationships toward integrated film producers.
- Emergency Vehicles:Fire apparatus and ambulance OEMs in the United States specify multi-color prismatic configurations with NFPA 1901 recognition requirements, opening premium configuration channels.
- Work Zones:Highway maintenance contractors in Germany and France procure high-visibility markings under occupational safety enforcement expansion.
- Sports Equipment:Cycling and running gear manufacturers specify lightweight retroreflective trims outside regulatory compliance frameworks.
Traffic control dominates procurement tonnage; emergency vehicles deliver the highest margin per square meter.
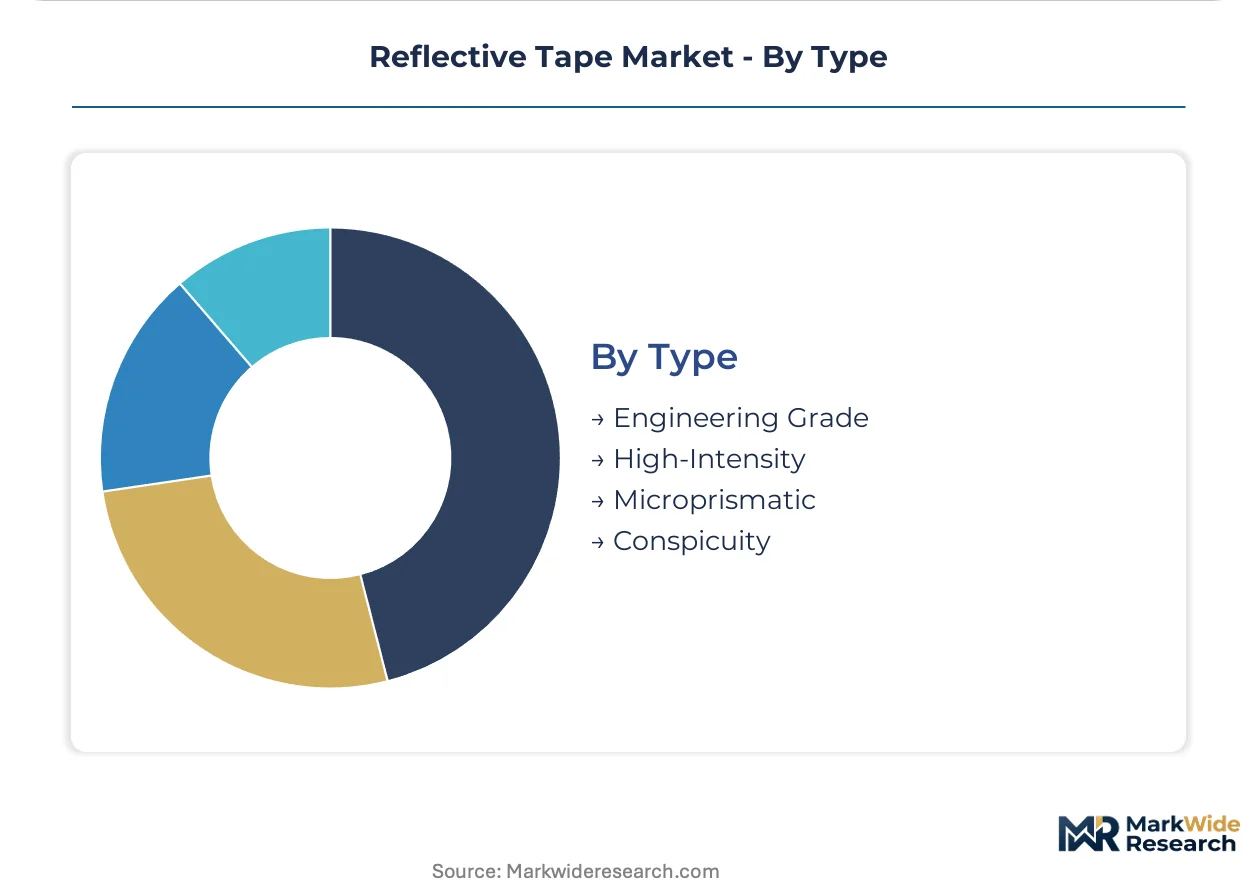
Type:
Technology migration from enclosed-lens to microprismatic architectures is compressing viable supply bases for legacy performance tiers.
- Microprismatic:Full-cube prismatic arrays deliver superior angularity performance and longer field durability, commanding specification preference from United States commercial vehicle OEMs and German premium signage authorities. EN 12899 and ASTM D4956-21 threshold tightening accelerates substitution away from bead-based alternatives.
- Engineering Grade:Glass-bead enclosed-lens construction retains position in cost-constrained applications where minimum retroreflectivity requirements have not escalated, though state DOT qualification rejections are narrowing addressable market.
- High-Intensity:Intermediate optical performance tier serves regional road networks and municipal fleets with moderate durability requirements.
- Conspicuity:Regulatory-mandated striping format for commercial vehicle sides and rear under FMCSA and ECE 104 frameworks, specified by fleet operators managing DOT audit compliance.
Engineering grade retains installed base volume; microprismatic captures the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and United States specification authorities, while converters in India and Mexico absorb margin compression from feedstock volatility and certification fragmentation.
United States
FMCSA truck conspicuity mandates sustain replacement cycles across for-hire fleets, with DOT audit compliance programs driving specification upgrades. NHTSA enforcement of retroreflective striping standards tightens procurement eligibility. Converter operations cluster in Ohio and Michigan industrial corridors where precision-slitting capabilities service direct fleet procurement channels.
Germany
EN 12899 retroreflectivity thresholds for autobahn signage accelerate microprismatic film adoption among traffic control authorities. KBA vehicle certification requirements extend to commercial fleet marking specifications. Optical-grade resin processing concentrates in Bavaria and Baden-Württemberg chemical corridors near captive polymer science operations.
China
National highway expansion programs generate virgin demand for traffic signage sheeting as provincial procurement capacity matures. MIIT standards for vehicle conspicuity markings align with ECE 104 frameworks for export-oriented commercial vehicle production. Manufacturing gravity centers on Yangtze River Delta converter operations serving domestic infrastructure build-out and Southeast Asian export channels.
India
National highway development under Bharatmala and Sagarmala programs creates specification-grade demand for retroreflective sheeting. BIS certification requirements for road signage materials constrain import eligibility and elevate local converter investment. Industrial clusters in Gujarat and Maharashtra develop precision coating capabilities to capture state-level traffic authority procurement.
Japan
JIS standards for vehicle safety markings maintain stringent optical performance requirements for domestic commercial vehicle production. METI industrial policy supports advanced materials development for next-generation prismatic architectures. Converter operations in Chubu and Kansai industrial regions supply precision-coated films for automotive OEM specification programs.
Reflective Tape Market Competitive Environment
Concentration sits with integrated polymer producers and precision-coated film specialists, compressing viable supply bases for non-captive converters. Market structure tiers between vertically integrated resin-to-film operations and downstream slitting distributors. Two strategic archetypes dominate: optical-grade resin producers with captive embossing capabilities, and regional converters with cut-to-length service models. Capacity expansion and certification portfolio diversification constitute the dominant competitive moves as specification thresholds escalate.
Among integrated material science groups, 3M and DuPont exemplify archetypes with upstream control over polymer formulations and optical film extrusion. ORAFOL Europe GmbH occupies a position within the precision-coated prismatic tier, while Changzhou Hua R Sheng Reflective Material Co., Ltd. represents Chinese converter scaling. Avery Dennison Corporation and Nitto Denko Corporation anchor diversified adhesive and film technology portfolios that span adjacent industrial tape segments.
| Leading Market Players |
|---|
| DuPont |
| Paiho Group |
| 3M |
| Reflomax Co., Ltd |
| SKC |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Changzhou Hua R Sheng Reflective Material Co., Ltd. |
| ORAFOL Europe GmbH |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety day master roll lead times from integrated optical film producers concentrate pricing power with German and United States resin-to-film operations, while downstream converters absorb margin compression through inventory carrying costs and specification-grade certification investments. This temporal asymmetry between raw material availability and finished goods qualification shapes competitive boundaries across the value chain.
Pricing Analysis
The customization-premium spread between configured-to-order microprismatic configurations and standard engineering-grade sheeting spans three performance tiers tied to ASTM D4956 and EN 12899 certification levels. Price differentiation rests on optical-grade resin sourcing and captive embossing capabilities rather than brand positioning alone. Cost compression in standard conspicuity striping intensifies as fleet maintenance departments consolidate procurement through industrial distributors with cut-to-length capabilities. Small-scale sign fabricators exhibit the highest price sensitivity, while commercial vehicle OEMs prioritize documented retroreflectivity degradation curves over unit economics.
Supply Chain Analysis
Germany and the United States anchor precision embossing equipment and optical-grade acrylic resin production, while China scales coating operations for domestic infrastructure build-out and Southeast Asian export channels. Raw material dependencies center on propylene feedstocks for acrylic formulations, polyester substrates tethered to PTA pricing, and metallized film layers for prismatic array construction. Single-source vulnerability concentrates in precision goniophotometry equipment for retroreflectivity validation. Distribution runs through converter operations with FMCSA and EN 12899 qualification credentials, bypassing traditional distributor networks for direct fleet and signage authority procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as infrastructure investment programs in India and occupational safety enforcement in Germany and France accelerate specification-grade adoption beyond replacement demand saturation. Microprismatic technology migration creates whitespace for qualified entrants while compressing legacy bead-based supplier viability.
For Market Incumbents: Secure captive polymer science capabilities through backward integration into optical-grade resin formulations, insulating margin pools from petrochemical input volatility. Consolidate certification portfolio investments across ASTM D4956-21 and EN 12899 testing protocols to defend against emerging Asian converters with lower compliance cost structures. Channel control through direct fleet procurement relationships represents the critical defensive lever against industrial distributor disintermediation. For New Entrants and Emerging Players: EN 13356 fast-track certification for personal protective equipment channels opens immediate procurement eligibility with German and French highway maintenance contractors facing tightening occupational visibility enforcement. Target temporary traffic control device segments where shorter service life requirements accommodate PVC-based cost structures and lower optical performance thresholds. Digital printing compatibility investments enable service bureau positioning for short-run fleet graphics customization beyond traditional converter networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified adhesive and film technology parents with underutilized optical coating assets and dormant certification portfolios. Long-term viability hinges on specification threshold escalation continuing to compress viable supply bases toward integrated resin-to-film operations. Signal to monitor: state DOT qualification program rejections of legacy bead-based submissions accelerating consolidation timelines toward microprismatic-dominant market structure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical-Grade Resin | Captive acrylic formulation control insulates margin pools from propylene feedstock volatility at German chemical corridor operations. |
| Multi-Jurisdiction Certification Investment | Parallel ASTM D4956 and EN 12899 validation unlocks transatlantic procurement eligibility for commercial vehicle OEM specification programs. |
| Precision-Slitting Capacity Expansion | Same-day turnaround capabilities capture fleet maintenance departments unbundling retroreflective striping from body shop contracts in Ohio and Michigan corridors. |
| Digital Printing Compatibility Development | UV-curable ink adhesion advances open service bureau channels for short-run fleet graphics customization beyond traditional converter networks. |
| Emergency Vehicle Multi-Color Configuration | NFPA 1901-compliant prismatic arrays command premium positioning with United States fire apparatus and ambulance OEMs. |
Study Parameters
Cross-validation between primary interviews with optical film plant managers, FMCSA compliance officers at for-hire trucking fleets, state DOT specification engineers, and European road signage procurement leads anchors the qualitative findings. Secondary validation draws from customs and trade data for acrylic resin and polyester substrate flows, SEC 10-K filings from integrated material science groups, and EN 12899 certification registry databases. Bottom-up triangulation across converter shipment volumes and top-down reconciliation with infrastructure investment program disclosures ensure dimensional consistency.
Sensitivity analysis around petrochemical input price bands and specification threshold escalation timelines frames projection uncertainty across the modeling period. Segmentation dimensions include material chemistry tier, optical performance grade, end-use regulatory framework, and regional procurement maturity. CAGRs derive from fitted trend extrapolation against historical replacement cycle data and infrastructure build-out pipeline disclosures. Industry-specific forecast inputs encompass FMCSA audit enforcement intensity and EN 12899 threshold revision schedules.
Decision-makers should treat outputs as directional under sustained infrastructure investment and regulatory enforcement assumptions; material deviation in petrochemical pricing or specification harmonization timelines would warrant model refresh. Recalibration cycles align with substantive shifts in DOT procurement qualification protocols and occupational safety enforcement expansion trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Pipe Marking Tape Market
Tapes
Packaging Tapes Market
Tapes
Global Construction Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Europe Packaging Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Splicing Tapes Market
Tapes
Pre-Printed Tape Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Pucker Free Tapes Market
Tapes
Paper Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Double Sided Tape Market
Tapes
Hydrocolloid Tapes Market