
 Strapping Tapes Market | 2026-2036
Strapping Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Strapping Tapes Market Outlook
High-tensile polyester specifications are reorganizing competitive dynamics in strapping tapes as warehouse automation demands stronger, more consistent load containment. 3M Company leverages its materials science portfolio to sustain premium positioning in industrial-grade applications. Tesa SE anchors European supply through specialized acrylic adhesive platforms designed for cold-chain logistics. Intertape Polymer Group competes on manufacturing scale across North American distribution networks.
Strapping tapes are pressure-sensitive or heat-activated adhesive strips, typically manufactured from oriented polypropylene or polyester film with tensile strengths ranging from 100 to 600 pounds per inch, engineered to secure palletized goods, bundle pipe and lumber, and reinforce corrugated containers during transit. Polypropylene dominates volume due to its cost-efficiency in light-duty bundling and consumer goods palletizing, while polyester commands margin pools in heavy-duty construction and steel replacement applications where elongation recovery and UV resistance prove critical. Rolls remain the standard product form for automated dispensing equipment, though custom shapes are gaining traction in automotive just-in-time sequencing operations.
FDA regulations govern direct-contact food packaging applications, requiring adhesive migration testing that shapes product development priorities for suppliers serving the sector. EPA guidelines on volatile organic compound emissions influence solvent-based adhesive formulations, particularly for manufacturers operating in the United States. OSHA workplace safety standards for manual handling drive adoption of ergonomic, high-performance tapes that reduce repetitive strain injuries in distribution centers. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions reshape material recovery obligations and adhesive chemistries.
Market Dynamics
Warehouse automation density in Germany, China, and the United States is compressing tolerance specifications for strapping tapes, forcing adhesive formulators to synchronize elongation recovery rates with robotic palletizing cycle speeds.
Growth Catalysts
- E-commerce fulfillment velocity:Third-party logistics operators in the United States are specifying polyester strapping with 400+ pound tensile ratings for high-throughput distribution centers handling electronics and consumer durables.
- REACH solvent restrictions:European manufacturers are converting acrylic adhesive platforms to water-borne chemistries ahead of 2025 compliance deadlines, opening retrofit demand from existing tape inventories.
- Cold-chain infrastructure:Pharmaceutical distributors in Germany require strapping tapes with sub-zero adhesive performance for vaccine palletizing, creating specification premiums in healthcare logistics.
Market Restraints
- Petrochemical input volatility:Oriented polypropylene resin prices track naphtha spreads, compressing margins for commodity-grade strapping tape converters without backward integration into polymer production.
- Supplier concentration in East Asia:Biaxially oriented polyester film supply concentrates among Korean and Chinese producers, exposing North American tape manufacturers to freight cost shocks and currency fluctuation.
- Steel strapping substitution ceiling:Heavy-gauge steel banding retains cost advantage in primary metals and construction verticals above 1,200-pound break strength, limiting polyester penetration in extreme-load applications.
Strategic Opportunities
- India warehouse automation:The country's PLI scheme for logistics infrastructure is attracting automated packaging line investments in Mumbai and Delhi NCR, creating virgin demand for precision-strapping equipment compatibility.
- RFID-embedded tape convergence:Combining pressure-sensitive adhesives with passive tracking tags enables real-time pallet location without secondary label application, unlocking value in pharmaceutical and aerospace supply chains.
- Extended producer responsibility frameworks:France's anti-waste law and Germany's Packaging Act are mandating recyclable adhesive systems, rewarding early movers with preferred supplier status in EU public procurement.
Industry Challenges
- Adhesive formulation talent scarcity:Solvent-to-water chemistry transitions require polymer scientists with simultaneous expertise in tackification and drying kinetics, a skillset concentrated among retiring European formulators.
- ISO 9001 certification timelines:Medical device and food-contact applications demand 18-24 month validation cycles for new adhesive platforms, delaying revenue recognition from reformulated products.
- Legacy equipment retrofit friction:Automated strapping heads designed for 1970s-era steel banding require mechanical and control system upgrades to handle polyester tape elongation characteristics without jamming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strapping Tapes Market |
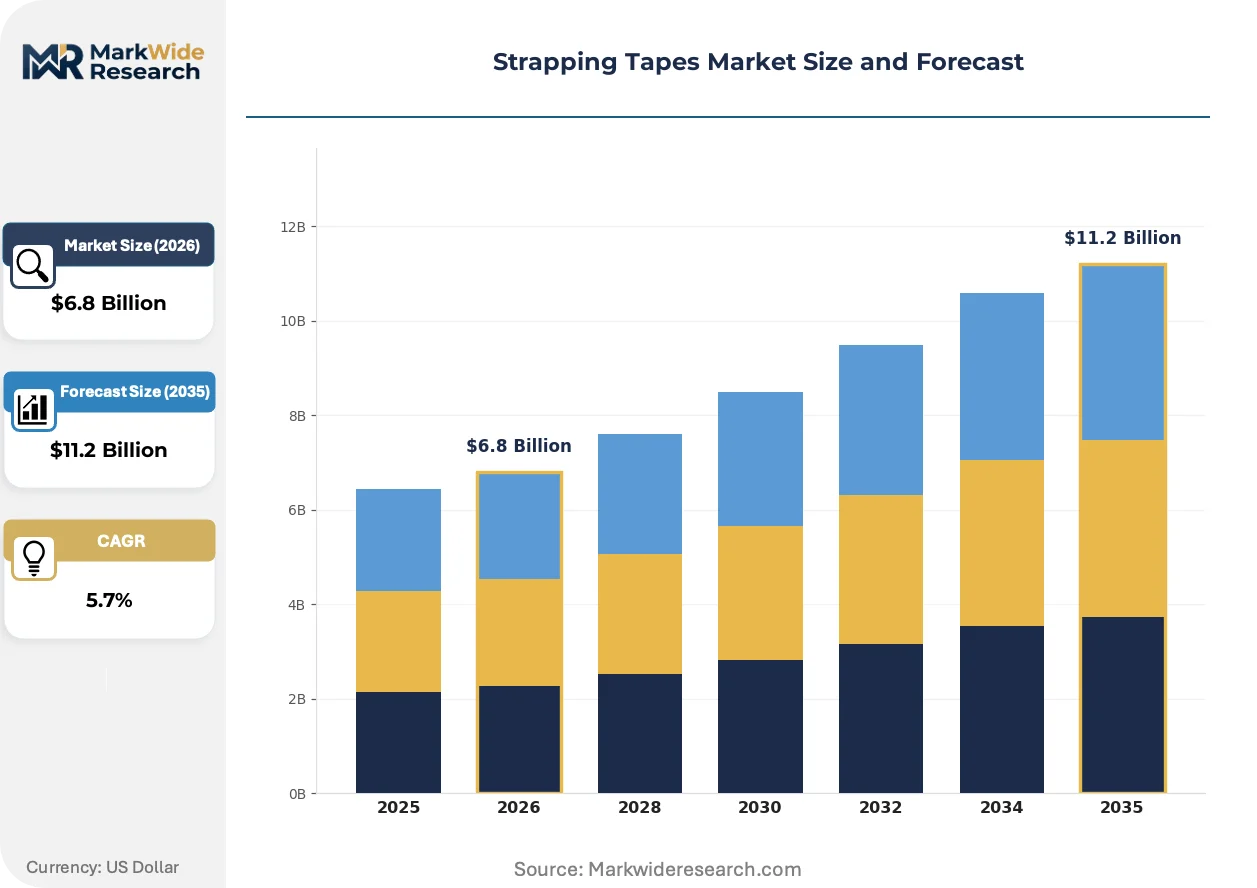
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyester, Nylon, Steel End Use Industry: Packaging, Automotive, Construction, Logistics Product Form: Rolls, Sheets, Spools, Custom Shapes Application: Heavy Duty, Light Duty, Bundling, Palletizing |
| Companies Covered | 3M Company, Tesa SE, Intertape Polymer Group, Avery Dennison Corporation, Nitto Denko Corporation, Scapa Group plc, Berry Global Inc., Shurtape Technologies LLC, Saint-Gobain Performance Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strapping Tapes Market Strategic Shifts
Strapping tape functionality is bifurcating between commodity bundling and intelligent load containment, with adhesive chemistry and embedded sensing becoming the primary vectors of differentiation rather than substrate tensile strength alone.
Biodegradable pressure-sensitive adhesives derived from rosin ester and starch derivatives are decomposing the traditional petroleum-based formulation lock-in among European food-packaging suppliers. Retail grocery distributors in France and Germany are piloting these platforms for fresh produce crate sealing ahead of 2025 single-use plastic restrictions. The structural consequence is a compression in conventional hot-melt adhesive capacity utilization as converters retool coating lines for lower-temperature bio-based processing.
EPA volatile organic compound emission limits under 40 CFR 59 are forcing solvent-based adhesive manufacturers toward thermal oxidizer investments or water-borne platform migrations. Tape converters operating in California and Texas face the most stringent state implementation plans, with Los Angeles basin facilities already reporting 30% coating speed reductions during drying phase transitions. The affected segment is industrial-grade polyester strapping for construction lumber, where water-borne alternatives struggle to match humidity resistance.
Third-party logistics buyers are consolidating supplier relationships around integrated strapping-and-dispensing system contracts rather than discrete tape procurement. Amazon and Walmart fulfillment networks in the United States are specifying equipment-agnostic tape performance guarantees, displacing brand-loyal purchasing in favor of total-cost-of-ownership metrics. This behavioral shift is most visible in the parcel sortation vertical, where downtime penalties now exceed material cost differentials in vendor selection criteria.
Strapping Tapes Market Segmentation
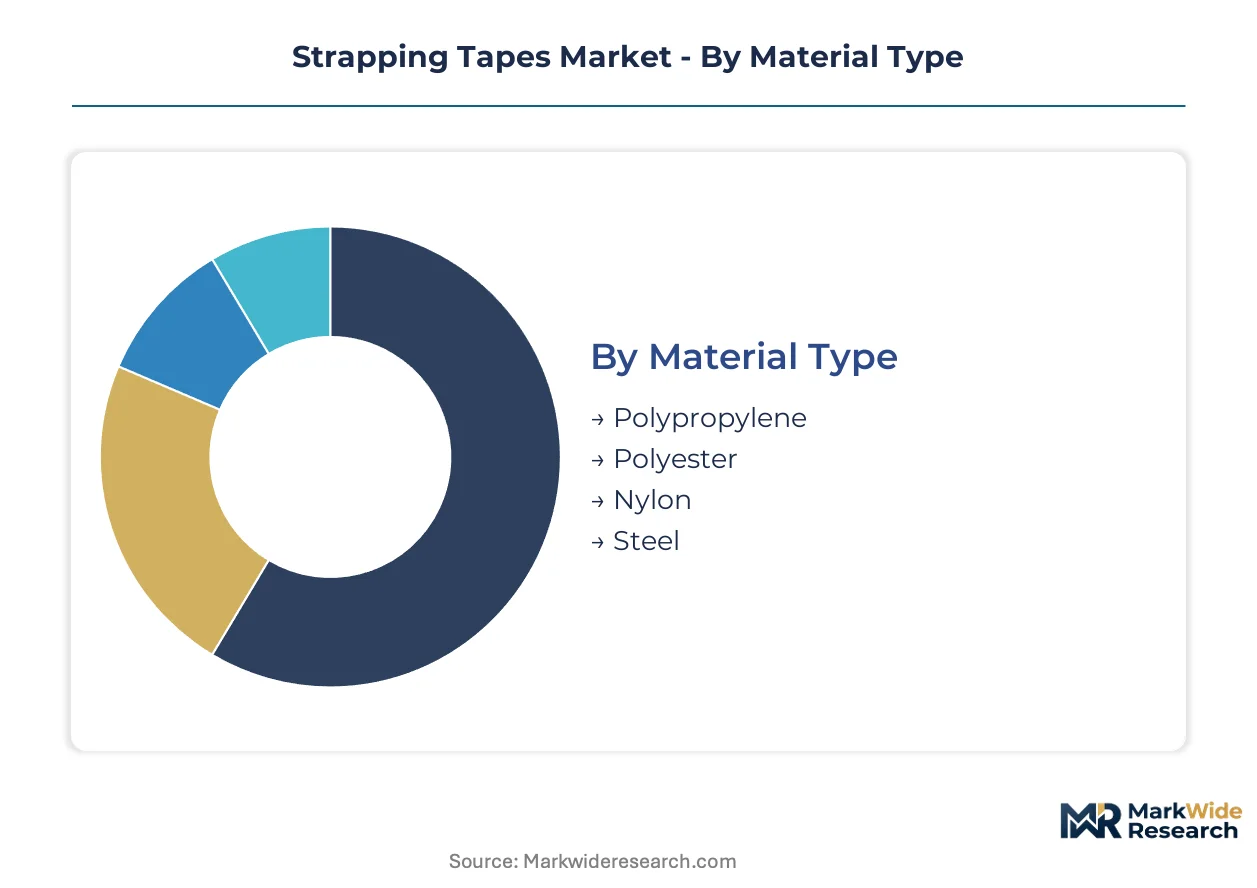
Strapping tape segmentation reveals where substitution pressures reshape supplier economics. Material chemistry, end-use specifications, and application intensity each create distinct vulnerability profiles against alternative securing technologies.
Material Type:
Steel strapping faces the most acute substitution threat as polyester formulations close the tensile strength gap at lower unit weights.
- Polypropylene:Oriented polypropylene film delivers 100-300 pound tensile ratings with minimal moisture absorption. E-commerce fulfillment centers in Germany and the United States specify this grade for consumer goods palletizing where cost-per-foot dominates procurement decisions.
- Polyester:Biaxially oriented polyester achieves 400-600 pound tensile strength with superior elongation recovery for automated tensioning systems. Heavy-duty construction applications in China and steel coil bundling operations favor this specification despite resin price volatility.
- Nylon:High-tensile nylon substrates withstand extreme temperature cycling from -40°C to 85°C, serving aerospace component securing and outdoor equipment bundling where dimensional stability under thermal stress matters.
- Steel:Cold-rolled steel banding retains dominance in primary metals shipment above 1,200-pound break thresholds, though corrosion susceptibility and worker safety liabilities erode share in construction verticals.
Polypropylene retains volume leadership; polyester holds the steepest expansion curve.
End Use Industry:
Application intensity varies sharply across verticals, with logistics operators driving specification standardization while automotive buyers demand lot-level traceability.
- Packaging:Corrugated container reinforcement and case sealing consume the highest tape footage per facility. Food-contact applications trigger FDA migration testing requirements that filter out commodity adhesive suppliers.
- Logistics:Third-party fulfillment networks specify equipment-agnostic performance guarantees across multi-site operations. Amazon and Walmart distribution centers in the United States prioritize downtime reduction over per-roll cost minimization.
- Automotive:Just-in-time sequencing operations require custom-width tapes with embedded lot codes for component tracking. OEM assembly plants in Germany specify cold-tack adhesives for winter inbound logistics.
- Construction:Lumber bundling and pipe securing expose tapes to UV degradation and mechanical abrasion. Water-borne adhesive alternatives struggle to match humidity resistance in outdoor storage applications.
Logistics commands the highest footage volume; automotive generates the strongest specification premiums.
Product Form:
Equipment compatibility constraints lock buyers into specific form factors, creating switching costs that protect incumbent suppliers.
- Rolls:Standard 3-inch and 6-inch widths feed automated dispensing heads across warehouse operations. Core diameter standardization at 3-inch or 6-inch specifications determines equipment interoperability.
- Spools:High-capacity spools reduce changeover frequency in continuous-flow packaging lines. Steel strapping exclusively ships on this form factor for heavy-gauge applications.
- Sheets:Pre-cut sheet formats serve manual bundling stations in small-scale distribution operations and field construction sites without automated equipment.
- Custom Shapes:Die-cut configurations with integrated pull-tabs address ergonomic injury reduction mandates under OSHA workplace safety standards.
Rolls dominate automated installations; custom shapes gain share in manual-handling environments.
Application:
Load characteristics and handling frequency determine whether adhesive or friction-based securing proves optimal.
- Palletizing:Unit load stabilization for forklift transport demands consistent tension maintenance through vibration and shock. Robotic palletizing cycle speeds in Chinese and German facilities compress tolerance specifications for elongation recovery rates.
- Heavy Duty:Steel replacement applications in construction and primary metals require break strengths above 400 pounds with minimal creep under sustained load.
- Bundling:Pipe, lumber, and textile coil securing favors tapes with hand-tearability and residue-free removal for downstream processing.
- Light Duty:Consumer goods and printed material bundling prioritizes printability and aesthetic finish over mechanical performance.
Palletizing absorbs the highest footage volumes; heavy duty commands the steepest price per pound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyester and polypropylene film supply concentrates among Korean and Chinese producers, exposing downstream tape manufacturers to freight cost volatility and currency fluctuation. Automated packaging line density varies sharply by country, compressing tolerance specifications where robotic palletizing operates at highest velocity.
United States
Third-party logistics operators specify polyester strapping with 400+ pound tensile ratings for electronics and consumer durables distribution. EPA guidelines on volatile organic compound emissions under 40 CFR 59 push solvent-based adhesive manufacturers toward thermal oxidizer investments or water-borne platform migrations. Amazon and Walmart fulfillment networks in California and Texas prioritize equipment-agnostic tape performance guarantees over brand-loyal purchasing.
Germany
Pharmaceutical distributors require strapping tapes with sub-zero adhesive performance for vaccine palletizing in healthcare logistics. REACH solvent restrictions compel acrylic adhesive conversions to water-borne chemistries ahead of compliance deadlines. The Rhine-Ruhr and Bavarian industrial corridors host the densest concentrations of automated packaging lines in Europe, forcing adhesive formulators to synchronize elongation recovery with robotic cycle speeds.
China
Heavy-duty construction applications and steel coil bundling operations favor biaxially oriented polyester despite resin price volatility. MIIT standards and dual carbon goals shape domestic manufacturing compliance requirements for adhesive emissions. Yangtze River Delta and Pearl River Delta clusters concentrate biaxial film production capacity, supplying both domestic converters and export markets.
India
The PLI scheme for logistics infrastructure attracts automated packaging line investments in Mumbai and Delhi NCR, creating virgin demand for precision-strapping equipment compatibility. BIS certification requirements filter out commodity adhesive suppliers from food-contact applications. Gujarat and Maharashtra industrial zones see accelerating warehouse automation adoption among third-party fulfillment operators.
Japan
Aerospace component securing and outdoor equipment bundling demand high-tensile nylon substrates with dimensional stability across extreme temperature cycling. METI industrial standards govern adhesive performance specifications for export-oriented manufacturers. Kanto and Kansai regions maintain specialized coating capacity for cold-tack adhesives serving automotive just-in-time sequencing operations.
Strapping Tapes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Materials science specialists command premium positioning through proprietary adhesive platforms, while scale-driven converters compete on manufacturing throughput across distribution networks. Three archetypes dominate: diversified industrial conglomerates with captive polymer research, regional specialists in cold-chain or automotive adhesives, and commodity converters leveraging backward integration into film extrusion. Consolidation pressures favor M&A activity among mid-cap specialists, while geographic expansion targets underpenetrated warehouse automation clusters.
Among diversified industrial conglomerates, 3M Company and Tesa SE exemplify technology-led positioning through materials science depth. Intertape Polymer Group occupies a scale-driven position across North American distribution networks. Nitto Denko Corporation and Avery Dennison Corporation anchor the Asia-Pacific and specialty adhesive vectors respectively. Saint-Gobain Performance Plastics Corporation represents European industrial heritage in performance films. Berry Global Inc. and Shurtape Technologies LLC sit within the packaging-focused converter tier, while Scapa Group plc exemplifies regional specialist positioning.
| Leading Market Players |
|---|
| 3M Company |
| Tesa SE |
| Intertape Polymer Group |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Scapa Group plc |
| Berry Global Inc. |
| Shurtape Technologies LLC |
| Saint-Gobain Performance Plastics Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between polyester film suppliers and North American tape converters lock in resin access while capping price volatility exposure for buyers serving e-commerce fulfillment networks. These arrangements concentrate procurement power among distributors with multi-site warehouse footprints, compressing spot-market liquidity for smaller converters.
Pricing Analysis
REACH and RoHS directives dictate the pricing tier structure across European supply, separating solvent-free adhesive platforms from legacy formulations facing compliance retrofit costs. Three-tier pricing structure across premium, standard, and economy levels reflects tensile strength certification, cold-chain performance validation, and volume scale commitments. Cost compression in commodity polypropylene grades is intensifying because Korean resin exporters are absorbing freight cost spikes to defend market share. Third-party logistics operators demonstrate lowest price sensitivity, prioritizing equipment compatibility and downtime guarantees over per-roll cost minimization.
Supply Chain Analysis
China and South Korea anchor biaxially oriented polyester film production, feeding both domestic converters and export markets across North America and Europe. Raw material flows draw from naphtha-derived polypropylene resin, acrylic adhesive monomers, and release liner substrates. Single-source vulnerability concentrates in East Asian film extrusion capacity, exposing downstream tape manufacturers to currency fluctuation and logistics chokepoint risk. Distribution runs through converter-owned coating facilities, third-party logistics procurement hubs, and industrial distribution networks serving construction and automotive end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-agnostic performance specifications create defensive moats through switching costs, as automated strapping head retrofits demand 18-24 month validation cycles that lock buyers into incumbent suppliers.
For Market Incumbents: Shield margin pools in cold-chain logistics by deepening captive supply of sub-zero adhesive formulations before REACH compliance deadlines filter out commodity competitors. Accelerate certification investment for FDA food-contact and ISO 9001 medical device tiers to capture specification premiums. Defend against steel strapping substitution in heavy-duty construction by demonstrating total-cost-of-ownership advantages in corrosion resistance and worker safety liability reduction. For New Entrants and Emerging Players: RFID-embedded tape convergence represents a service-layer gap where incumbents under-serve pharmaceutical and aerospace supply chains demanding real-time pallet tracking without secondary label application. Target India's warehouse automation clusters around Mumbai and Delhi NCR, where PLI scheme investments are creating virgin demand for precision-strapping equipment compatibility without entrenched supplier relationships. Lead with integrated strapping-and-dispensing system contracts rather than discrete tape procurement to bypass brand-loyal purchasing at established fulfillment networks. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with proprietary acrylic adhesive platforms serving cold-chain or automotive just-in-time sequencing operations, where specification premiums sustain margin compression resistance. Long-term viability hinges on water-borne chemistry transition completion ahead of regulatory enforcement windows. Monitor adhesive formulation talent scarcity as an inflection indicator, as retiring European polymer scientists with simultaneous tackification and drying kinetics expertise constrain new platform development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive supply of biaxially oriented polyester reduces exposure to Korean and Chinese resin price volatility. |
| Water-Borne Adhesive Platform Migration | EPA 40 CFR 59 and REACH compliance positions converters for preferred supplier status in EU public procurement. |
| RFID-Embedded Tape Development | Passive tracking tag integration unlocks pharmaceutical and aerospace supply chain value without secondary labeling. |
| India Warehouse Automation Partnership | PLI scheme logistics infrastructure investments in Mumbai and Delhi NCR create equipment-agnostic tape demand. |
| Cold-Chain Performance Certification | Sub-zero adhesive validation for vaccine palletizing captures specification premiums in German healthcare logistics. |
Study Parameters
Operator-level perspectives from plant managers at tape coating facilities, procurement leads at third-party logistics operators, and technical R&D directors at adhesive formulators anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, SEC 10-K filings of diversified industrial conglomerates, and chemical industry association reports. Bottom-up modeling of converter capacity utilization and top-down triangulation against end-use demand from e-commerce fulfillment networks and construction verticals established volume estimates.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios and regulatory compliance timeline variations over the projection horizon. Segmentation dimensions modeled include material chemistry grade, end-use industry intensity, product form factor, and application load characteristic. CAGRs were derived from trend extrapolation of automated packaging line density and robotic palletizing cycle speed requirements. Industry-specific inputs incorporated REACH solvent restriction implementation pace and EPA volatile organic compound emission limit enforcement intensity.
Forecasts assume regulatory continuity in EU REACH and RoHS regimes, US EPA 40 CFR 59 state implementation plans, and China MIIT dual carbon goal trajectories; material policy shifts would require re-modeling of adhesive chemistry transition timelines and capital expenditure assumptions. Recalibration cycles align with material shifts in warehouse automation density, resin supply concentration, and extended producer responsibility framework expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Non Woven Water Blocking Tape Market
Tapes
Duct Tapes Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Paper Gummed Tape Market
Tapes
Masking Tape Market
Tapes
Raffia Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Nylon Cable Ties Market
Tapes
Thread Seal Tape Market
Tapes
Washi Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Global Surface Protection Tapes Market