
 Global Engineering Plastic Market | 2026-2036
Global Engineering Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Engineering Plastic Market Foresight
Performance-based material subscription contracts is realigning how engineering resin suppliers monetize long-term relationships with automotive and electronics OEMs. BASF SE leverages its integrated polyamide value chain from caprolactam to compounded grades to sustain pricing power across European EV platforms. Solvay S.A. anchors its position in specialty polyphenylene sulfide and fluoropolymer segments for semiconductor fabrication equipment. SABIC competes through its global manufacturing scale in polycarbonate, particularly for consumer electronics housings and 5G infrastructure applications.
Engineering plastics comprise thermoplastic polymers engineered to withstand mechanical loads, thermal stress, and chemical exposure beyond the capabilities of commodity resins, with glass transition temperatures typically exceeding 100°C and tensile strengths above 40 MPa. These materials serve primarily as metal replacements in precision components where weight reduction, design freedom, and corrosion resistance deliver operational advantages. Polyamide dominates volume consumption in automotive and industrial applications due to its balance of toughness, oil resistance, and processability in injection molding systems. Polycarbonate leads optical and electronics segments where transparency combined with impact resistance creates differentiated value pools. Acrylonitrile Butadiene Styrene occupies mature consumer goods and appliance markets where cost-efficient extrusion and thermoforming sustain steady replacement demand.
The EPA oversees emissions and chemical safety standards affecting engineering plastic formulations in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances and mandate recyclability disclosures across the supply chain. China's SAMR enforces GB standards for flame retardancy and electrical safety that dictate material qualification for domestic appliance and automotive markets. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries will determine which compounders capture cross-border OEM supply positions.
Market Dynamics
Automotive electrification is compressing material qualification cycles as OEMs redesign battery housings and thermal management systems around polyamide and polycarbonate grades that must simultaneously satisfy flame-retardant mandates and crashworthiness standards.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon blowing agents is accelerating substitution toward halogen-free flame-retardant polyamide formulations in appliance and automotive wire harness applications.
- EV battery housing demand:Chinese, German, and US-based electric vehicle manufacturers are qualifying glass-filled polyamide grades for module enclosures and cooling line connectors at unprecedented speed.
- 5G infrastructure buildout:Polycarbonate and PPS compounds are capturing antenna housing and base station enclosure contracts as dielectric performance requirements tighten across telecommunications networks.
Market Restraints
- Caprolactam supply concentration:European and Asian polyamide producers face margin pressure from benzene derivative cost volatility and concentrated precursor supply in Northeast China.
- REACH substance restrictions:The European Chemicals Agency's expanding candidate list of SVHCs is forcing reformulation of legacy flame-retardant packages, extending qualification timelines by 12-18 months.
- Recycled content mandates:The EU's proposed Packaging and Packaging Waste Regulation is creating technical barriers for high-performance grades where mechanical property retention limits post-consumer recycled feedstock incorporation.
Strategic Opportunities
- India automotive localization:The country's Production-Linked Incentive scheme for advanced chemistry cell manufacturing is creating first-mover advantages for compounders establishing polyamide compounding capacity near Tamil Nadu and Gujarat battery plant clusters.
- Semiconductor fabrication equipment:Fluoropolymer and PPS grades are penetrating wafer handling components and chamber linings as chip fabrication node sizes shrink below 3 nanometers.
- Medical device resin qualification:US FDA and EU MDR biocompatibility pathways for long-term implantable grades represent untapped margin pools for polycarbonate and PSU compounders with sterilization validation capabilities.
Industry Challenges
- Multi-jurisdiction certification complexity:Compounders must maintain parallel UL 94, GB 4943, and EN 60695 test data sets for flame-retardant grades, fragmenting R&D resources across incompatible standard regimes.
- Compounding asset specificity:Twin-screw extrusion lines configured for high-temperature engineering resins require 24-36 month lead times and cannot be repurposed for commodity polymer production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Engineering Plastic Market |
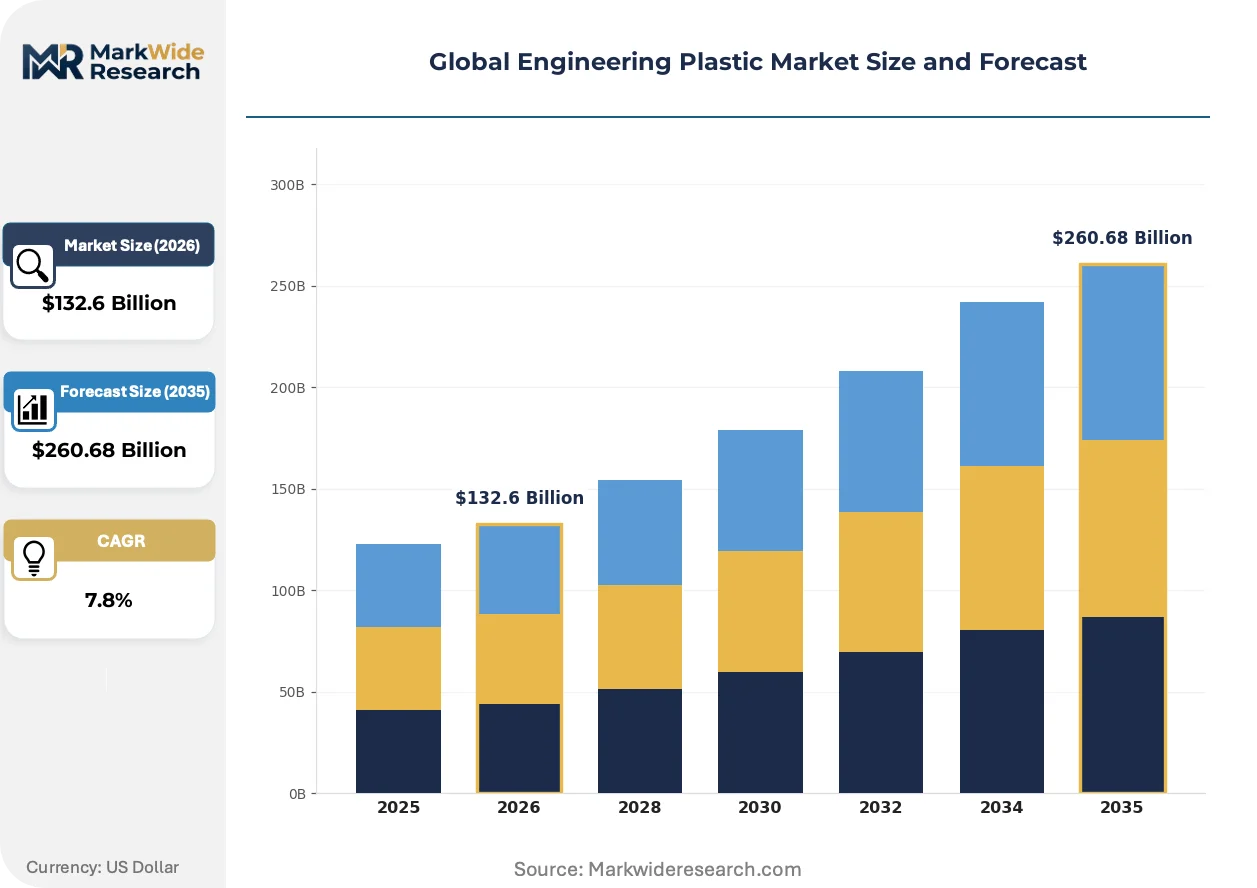
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $260.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, Polypropylene, Polyethylene, Acrylonitrile Butadiene Styrene, Polystyrene Technology: Injection Molding, Extrusion, Blow Molding, Thermoforming, Compression Molding, Rotational Molding Application: Electrical & Electronics, Consumer Goods, Packaging, Construction, Aerospace, Sports Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Industrial Manufacturers, Appliance Makers |
| Companies Covered | DuPont de Nemours, Inc., Solvay S.A., BASF SE, LANXESS AG, Evonik Industries AG, Covestro AG, Celanese Corporation, DSM Engineering Plastics, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Engineering Plastic Market Shifts & Advancements
Material science advances are converging with regulatory pressure to redefine performance thresholds across automotive, electronics, and industrial end-uses. Suppliers are repositioning around circularity credentials and thermal management capabilities rather than commodity volume.
Bio-based polyamide feedstocks derived from castor oil and other renewable sources are expanding into under-hood automotive components and sports equipment frames. Tier 1 suppliers in Germany and Japan are qualifying these grades for intake manifolds and pedal modules where heat resistance requirements previously excluded non-petroleum alternatives. The structural consequence is that bio-based suppliers are capturing sustainability-linked procurement contracts from OEMs with Science-Based Targets commitments.
REACH authorization requirements for persistent organic pollutants are forcing phaseouts of legacy brominated flame retardants in electrical enclosures and connector housings. Compounders are accelerating phosphorous-nitrogen synergist formulations and metal hydroxide packages to maintain V-0 ratings at reduced wall thicknesses. Wire and cable segments in European appliance and automotive harness applications are experiencing the most acute reformulation pressure.
Subscription-based material supply agreements are displacing transactional spot purchasing in automotive and electronics verticals. OEMs in the United States and South Korea are locking in five-year compounded resin contracts with embedded recyclability guarantees and technical service provisions. This model concentrates procurement authority with integrated compounders possessing captive recycling streams and regional technical centers.
Global Engineering Plastic Market Segmentation
Engineering plastic procurement decisions cascade through four distinct lenses: material specification, conversion process, end-use performance, and supply chain position. Each segmentation axis reveals different margin pools and qualification barriers that compounders must navigate.
Product Type:
Material selection hinges on thermal-mechanical requirements and regulatory compliance pathways rather than unit cost alone.
- Polycarbonate:Amorphous thermoplastic delivering optical clarity with impact resistance exceeding 80 kJ/m². Demand concentrates in Chinese and German automotive lighting clusters where headlamp lens specifications now mandate laser-weldable grades for seamless styling integration.
- Polyamide:Semi-crystalline resin family spanning PA6 to PA12 with continuous service temperatures from 80°C to 150°C. Automotive OEMs in the United States and China are qualifying glass-filled grades for battery module enclosures and electric motor housings where flame-retardant V-0 ratings must coexist with thermal conductivity above 0.5 W/mK.
- Polypropylene:Lightweight olefin with density below 0.91 g/cm³ and excellent chemical resistance against automotive fluids.
- Polyethylene:Versatile polyolefin offering superior stress-crack resistance and electrical insulation properties for wire and cable jacketing.
- Acrylonitrile Butadiene Styrene:Tough, processable terpolymer dominating appliance housings and consumer electronics enclosures where metallic finishes drive aesthetic differentiation.
- Polystyrene:Cost-efficient amorphous resin with exceptional dimensional stability for precision medical device components and food packaging trays.
Volume sits with polyamide; growth tilts toward polycarbonate.
Technology:
Processing method selection determines achievable part complexity, surface finish, and cycle economics.
- Injection Molding:Dominant conversion technology for complex three-dimensional geometries with wall thickness below 2mm. Tier-1 suppliers in Germany and South Korea are deploying multi-component machines to integrate soft-touch surfaces directly into polycarbonate structural housings for EV charging equipment.
- Extrusion:Continuous profile production enabling hollow chambers and integrated ribs for thermal break applications. Chinese construction material processors are scaling co-extrusion lines combining polyamide insulation cores with UV-resistant polyethylene skins for energy-efficient window systems.
- Blow Molding:Hollow part formation for fluid reservoirs and ducting components with blow ratios exceeding 3:1.
- Thermoforming:Sheet-based shaping for large-area thin-wall parts including aircraft interior panels and medical device enclosures.
- Compression Molding:High-pressure forming for fiber-reinforced composites and thick-section industrial components requiring minimal residual stress.
- Rotational Molding:Hollow part production without weld lines for chemical storage tanks and recreational equipment shells.
Injection molding commands installed capacity; extrusion is climbing the fastest as construction energy codes tighten.
Application:
End-use certification requirements fragment demand into distinct technical ecosystems with incompatible qualification protocols.
- Electrical & Electronics:Enclosure and connector applications demanding CTI ratings above 600V and relative thermal indices exceeding 130°C. 5G infrastructure buildouts in the United States and China are absorbing flame-retardant polycarbonate grades for antenna radomes where dielectric constants must remain stable across -40°C to 85°C operating windows.
- Consumer Goods:Aesthetic-driven applications prioritizing surface quality and color consistency over mechanical extremes.
- Packaging:Barrier-sensitive formats requiring multilayer coextrusion with EVOH or polyamide core layers for oxygen transmission control.
- Construction:Structural and insulation components subject to fire classification EN 13501 and long-term weathering validation.
- Aerospace:Cabin interior and structural applications requiring FAA flammability compliance and FST (fire, smoke, toxicity) certification.
- Sports Equipment:High-impact protection gear leveraging polycarbonate and ABS blends for helmet shells and protective eyewear.
Electrical & electronics holds revenue concentration; aerospace represents the steepest expansion trajectory as cabin retrofit cycles accelerate.
End User:
Supply chain position dictates contract structure, technical service intensity, and inventory liability allocation.
- OEMs:Final product manufacturers with direct material specification authority and sustainability audit requirements. German automotive OEMs are embedding post-consumer recycled content mandates into polyamide supply agreements for visible interior components.
- Tier-1 Suppliers:System integrators managing sub-assembly procurement and just-in-sequence delivery to vehicle plants.
- Aftermarket Providers:Independent distributors serving repair and replacement demand with reduced qualification overhead.
- Vehicle Assemblers:Final-stage manufacturers integrating purchased modules into finished automotive and commercial transport products.
- Industrial Manufacturers:Capital equipment producers specifying engineering plastics for machinery guards, housings, and wear components.
- Appliance Makers:White goods manufacturers balancing cost targets with energy efficiency labeling requirements and refrigerant chemical resistance.
OEMs concentrate specification power; Tier-1 suppliers are gaining share fastest through integrated module supply contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the largest engineering plastic volumes globally, yet Germany and the United States retain concentrated production of high-performance grades for automotive and semiconductor applications. This production-consumption asymmetry shapes trade flows and qualification requirements across major economies.
China
Electric vehicle battery housing and charging infrastructure manufacturing concentrates in Shanghai, Shenzhen, and Ningbo, absorbing glass-filled polyamide grades at unprecedented speed. SAMR enforces GB standards for flame retardancy and electrical safety that dictate material qualification timelines. Yangtze River Delta compounders are scaling capacity to serve BYD and CATL module enclosure contracts.
Germany
Automotive OEMs in Stuttgart and Munich are embedding post-consumer recycled content mandates into polyamide supply agreements for visible interior components. REACH and RoHS frameworks restrict hazardous substances and mandate recyclability disclosures across the supply chain. Bavarian chemical parks maintain integrated caprolactam-to-compound value chains that sustain pricing power.
United States
EPA emissions standards and chemical safety requirements affect engineering plastic formulations for under-hood automotive and appliance applications. Detroit-area OEMs are qualifying laser-weldable polycarbonate grades for headlamp lens integration. Texas and Louisiana host precursor production that feeds compounding operations serving Mexican maquiladora assembly plants.
India
The Production-Linked Incentive scheme for advanced chemistry cell manufacturing is creating first-mover advantages for compounders establishing capacity near Tamil Nadu and Gujarat battery plant clusters. BIS certification requirements for electrical safety create qualification barriers for imported grades. Mumbai-Pune industrial corridor processors are expanding twin-screw extrusion lines for automotive wire harness applications.
South Korea
Seoul Capital Area electronics OEMs are locking in five-year compounded resin contracts with embedded recyclability guarantees and technical service provisions. MFDS and KC certification requirements for flame retardancy dictate material selection for consumer electronics housings. Busan-Ulsan chemical complexes supply high-purity polycarbonate for 5G antenna radome production.
Global Engineering Plastic Market Competitive Landscape
Top-tier vendors anchor integrated value chains from monomer production to compounded grades, while mid-scale compounders compete through regional technical service and rapid qualification support. The vendor base stratifies into three tiers: petrochemical majors with captive feedstock, specialized engineering resin compounders, and regional distributors with blending capabilities. Two dominant competitive moves are reshaping positioning: backward integration into caprolactam and precursor chemicals, and subscription-based material supply agreements with embedded recyclability guarantees.
Within the integrated petrochemical tier, BASF SE and Solvay S.A. occupy positions that exemplify divergent specialization strategies. BASF represents the vertically integrated archetype with European polyamide value chain control, while Solvay anchors specialty polyphenylene sulfide and fluoropolymer segments for semiconductor fabrication equipment. SABIC sits within the scale-driven polycarbonate segment, serving consumer electronics and telecommunications infrastructure applications. These three entities illustrate how geographic production concentration and feedstock access determine competitive positioning.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Solvay S.A. |
| BASF SE |
| LANXESS AG |
| Evonik Industries AG |
| Covestro AG |
| Celanese Corporation |
| DSM Engineering Plastics |
| SABIC |
| Others |
Supply & Pricing Matrix
Benzene derivative indices and caprolactam contract pricing cascade through polyamide value chains into three distinct procurement tiers. Integrated producers in Germany and China capture margin premiums through captive precursor supply, while independent compounders face cost pass-through volatility that compresses pricing power in spot transactions.
Pricing Analysis
Margin tightening in standard-grade polyamide reflects benzene cost volatility and concentrated caprolactam supply in Northeast China. Three-tier pricing structure across premium, standard, and economy levels separates flame-retardant certified grades from general-purpose compounds and recycled-content blends. Cost-down pressure on economy tiers accelerates because Chinese construction processors are qualifying lower-specification grades for window thermal break applications. Tier-1 automotive suppliers exhibit lowest price sensitivity due to embedded technical service requirements, while appliance OEMs drive hardest bargain on volume contracts.
Supply Chain Analysis
Caprolactam supply rests on integrated chemical parks in Germany, China, and the United States that feed regional compounding networks. Precursor dependencies span benzene derivatives, adipic acid, and specialty flame-retardant packages sourced from concentrated Japanese and German additive producers. Single-source vulnerability concentrates in high-purity polycarbonate for optical grades where Korean and Saudi producers dominate export volumes. Distribution runs through integrated compounders with captive technical centers rather than commodity distributors, concentrating procurement authority with BASF, SABIC, and Solvay tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering plastic markets are becoming a vertical-integration race where control over caprolactam and precursor chemicals determines pricing power. Players are pursuing backward integration into benzene derivatives and captive recycling streams to defend margin position.
For Market Incumbents: Cement feedstock security by securing long-term benzene supply agreements with Texas and Louisiana refiners, or acquire distressed European caprolactam assets before REACH-driven consolidation accelerates. Lock in five-year subscription contracts with Korean and German automotive OEMs that embed recyclability guarantees and technical service provisions to raise switching costs against emerging Chinese compounders.
For New Entrants and Emerging Players: Launch via regional compounding partnerships near Tamil Nadu and Gujarat battery clusters where Indian PLI incentives are concentrating demand and BIS certification creates qualification barriers for imported grades. Target semiconductor fabrication equipment segments in South Korea and Japan where fluoropolymer and PPS grades face supply constraints as node sizes shrink below 3 nanometers.
For Investors and Strategic Acquirers: The window for entry favors mid-scale compounders with validated UL 94 and GB 4943 test data sets that can be leveraged across incompatible standard regimes. Watch for REACH SVHC list expansions that force 12-18 month reformulation timelines, triggering distressed valuations among legacy flame-retardant package holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive precursor supply insulates German and Chinese producers from benzene derivative volatility. |
| Subscription-Based Material Supply Agreements | Five-year contracts with Korean electronics OEMs lock in recyclability guarantees and technical service. |
| Halogen-Free Flame-Retardant Reformulation | Phosphorous-nitrogen synergist packages maintain V-0 ratings as REACH phases out brominated additives. |
| Regional Compounding Capacity Expansion | Tamil Nadu and Gujarat plants capture Indian PLI-driven battery housing demand. |
| Post-Consumer Recycled Content Integration | Recycled feedstock incorporation satisfies EU Packaging and Packaging Waste Regulation mandates. |
Research Methodology
SEC 10-K filings, Cefic industry reports, and customs trade data formed the secondary backbone for volume and value estimation. Primary interviews with polyamide plant managers, automotive Tier-1 procurement leads, and technical R&D directors at compounding operations validated cost structures and qualification timelines. Bottom-up and top-down triangulation reconciled production capacity data with end-use consumption patterns across automotive, electronics, and industrial segments.
Bottom-up modeling aggregated grade-specific consumption by end-use application, while top-down analysis cross-checked against regional production capacity and trade flow data. Segmentation dimensions spanned material type, processing technology, end-use certification tier, and regional production cluster. CAGRs were derived from trend extrapolation of electric vehicle battery housing demand and 5G infrastructure buildout schedules, with cross-validation against OEM platform launch timelines.
The model assumes a particular technology adoption path; alternative pathways for bio-based polyamide feedstocks would alter the outlook if castor oil-derived grades achieve cost parity with petroleum-based alternatives. Forecasts reflect assumptions about REACH SVHC expansion pace and EU recycled content mandate implementation. A small set of triggers—caprolactam supply disruptions, sudden REACH restriction additions, and Chinese SAMR standard revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market