
 Global Thermally Conductive Plastics Market | 2026-2036
Global Thermally Conductive Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermally Conductive Plastics Market Foresight
Specialty compounders in Japan and Germany is restructuring capacity to serve electric vehicle thermal management needs. SABIC leverages its R&D footprint in the Middle East to develop halogen-free conductive formulations. Celanese Corporation anchors North American supply through captive polyamide compounding assets. DuPont differentiates via fluoropolymer-ceramic hybrid grades targeting power electronics.
Thermally conductive plastics are polymer matrices loaded with ceramic or metallic fillers, typically achieving thermal conductivities of 1–20 W/m·K, engineered to replace metal heat sinks in weight-sensitive assemblies. Their primary purpose is to dissipate heat in electronic enclosures while enabling design freedom and corrosion resistance. Polyphenylene sulfide dominates the product landscape due to its inherent flame resistance and compatibility with lead-free solder processes. Injection molding commands the technology tier because it permits complex geometries for LED heat sinks and telecommunications housings. Electric vehicles represent the fastest-expanding application channel as battery thermal runaway protection mandates intensify.
EPA guidelines on electronic waste recyclability and REACH restrictions on halogenated flame retardants are tightening material specifications across the supply chain. The EU F-Gas Regulation directly accelerates polymer adoption by penalizing conventional refrigerant-based cooling in automotive and appliance sectors. China's GB standards on new energy vehicle safety mandate thermal barrier performance that conductive plastics increasingly satisfy. Stakeholders must monitor how battery platform standardization across OEMs reshapes volume requirements and compound specifications.
Market Dynamics
Battery thermal runaway protection mandates are compressing design cycles for polymer housings as OEMs abandon metal heat sinks in electric vehicle battery packs. This structural force concentrates procurement authority among tier-one automotive suppliers clustered around Stuttgart and Munich.
Growth Catalysts
- EU F-Gas Regulation:Penalties on conventional refrigerant-based cooling in automotive and appliance sectors are accelerating polymer adoption among German and French OEMs seeking compliant thermal management solutions.
- Power electronics miniaturization:Silicon carbide inverter deployment in electric drivetrains demands lighter, corrosion-resistant heat dissipation materials that conductive plastics provide.
- China's GB standards:New energy vehicle safety mandates on thermal barrier performance are pulling Japanese and Korean compounders into direct supply relationships with Chinese battery manufacturers.
Market Restraints
- Ceramic filler cost volatility:Boron nitride and aluminum oxide prices fluctuate with energy-intensive processing costs in China's Yangtze River industrial corridor, squeezing compounder margins.
- REACH compliance friction:ECHA restrictions on halogenated flame retardants force reformulation of established polyphenylene sulfide grades, extending qualification timelines by 12-18 months.
- Metal heat sink substitution resistance:Aerospace and defense contractors in the US and UK maintain specifications for aluminum and copper thermal solutions due to established EMI shielding performance.
Strategic Opportunities
- Data center liquid cooling integration:Immersion cooling rack architectures in hyperscale facilities are creating specifications for thermally conductive polymer cold plates and manifolds.
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are drawing compounder investment toward Gujarat and Tamil Nadu industrial zones.
- 5G base station densification:Massive MIMO antenna thermal management requirements in South Korea and Japan are opening volume contracts for injection-molded polymer heat spreaders.
Industry Challenges
- Multi-physics simulation talent scarcity:Compounders lack sufficient thermal-mechanical finite element analysis specialists to support customer co-design of complex housing geometries.
- UL 94 V-0 recertification bottlenecks:Reformulated halogen-free grades require extensive third-party flammability testing, delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermally Conductive Plastics Market |
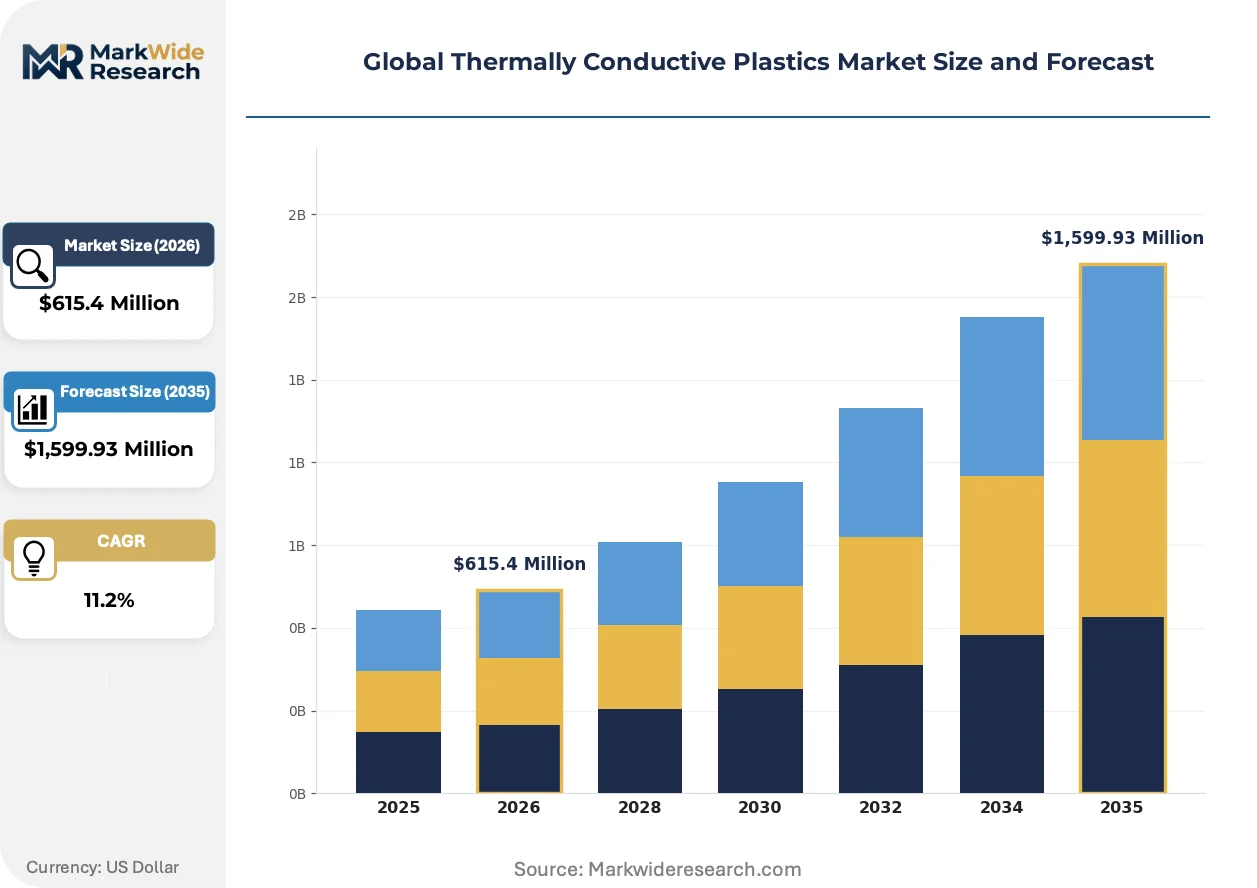
| Market Size in 2026 | $615.4 Million |
| Market Size in 2035 | $1,599.93 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide, Polycarbonate, Polyphenylene Sulfide, Thermoplastic Elastomers, Acrylics Technology: Injection Molding, Extrusion, Compression Molding, Blow Molding, 3D Printing Application: Consumer Electronics, LED Lighting, Power Modules, Telecommunications Equipment, Electric Vehicles End User Industry: Semiconductor Manufacturing, Aerospace Components, Renewable Energy Systems, Household Appliances, Networking Equipment |
| Companies Covered | Celanese Corporation, SABIC, BASF SE, DuPont, DSM, LANXESS, Mitsubishi Engineering-Plastics Corporation, TORAY INDUSTRIES, INC., KANEKA CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermally Conductive Plastics Market Shifts & Advancements
Formulation science and processing technology are converging to push thermal conductivity boundaries while maintaining injection molding flow characteristics. Three developments are restructuring competitive capabilities across the value chain.
Hybrid ceramic-fluoropolymer composites are expanding into power module substrates where polyphenylene sulfide alone fails dielectric strength requirements. Japanese automotive electronics suppliers are qualifying these grades for 800-volt inverter housings. The technology is expanding into designs previously reserved for direct-bonded copper ceramic substrates.
REACH authorization procedures for novel filler surface treatments are tightening entry barriers for European compounders. ECHA scrutiny of silane coupling agents delays new product introductions by 18-24 months. German suppliers are responding by accelerating in-house toxicology assessment capabilities to preempt regulatory objections.
Direct material specification by battery cell manufacturers is compressing traditional tiered supply chains. Contemporary Amperex Technology and LG Energy Solution now issue compound specifications directly to SABIC and Celanese, bypassing automotive tier-one intermediaries. This pattern is most visible in South Korea's Gyeonggi-do battery industrial cluster.
Global Thermally Conductive Plastics Market Segmentation
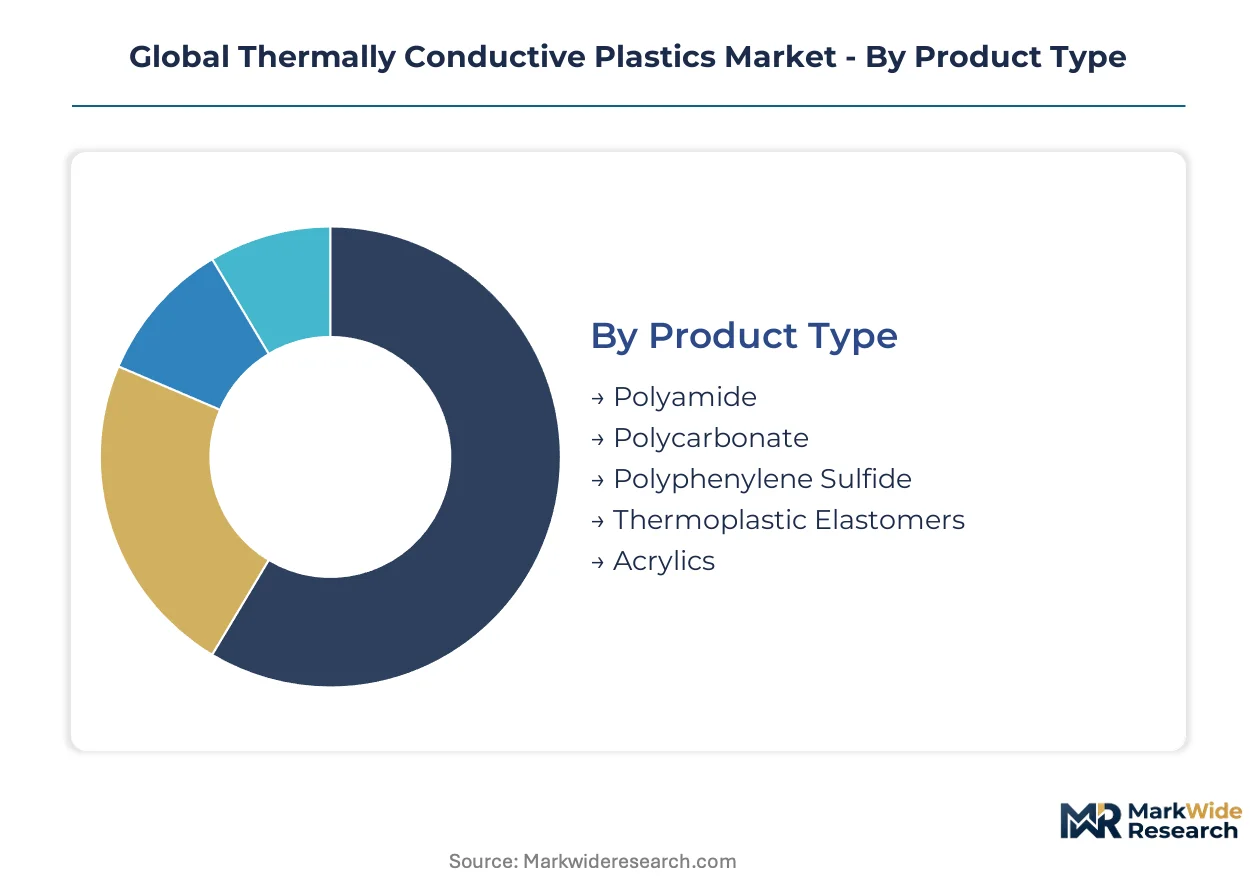
Material selection in thermally conductive plastics follows upgrade cycles tied to solder process changes, battery platform evolution, and thermal management specification tightening. Segmentation reveals where formulation investments concentrate and which processing technologies capture displacement opportunities from metal heat sinks.
Product Type:
Replacement cycles in automotive electronics and power modules are accelerating shifts between polymer chemistries as lead-free solder compatibility and thermal runaway protection requirements harden.
- Polyphenylene Sulfide:Inherently flame-resistant matrix compatible with lead-free solder reflow temperatures. Procurement concentrates among German tier-one suppliers serving Stuttgart-based OEMs, driven by EU F-Gas Regulation penalties on conventional cooling systems.
- Polyamide:Cost-optimized backbone for LED heat sinks and telecommunications housings. Celanese Corporation anchors North American supply through captive compounding assets, responding to power electronics miniaturization in silicon carbide inverter designs.
- Polycarbonate:Transparent grades enable optical-thermal integration in consumer electronics enclosures. Demand clusters in Japanese consumer electronics supply chains.
- Thermoplastic Elastomers:Soft-touch surfaces with moderate conductivity for wearable device interfaces. Korean manufacturers specify these for 5G handset thermal management.
- Acrylics:UV-stable formulations for outdoor LED luminaire applications. Chinese lighting exporters drive volume in Guangdong province.
Volume placements concentrate in Polyphenylene Sulfide; the faster expansion belongs to Polyamide.
Technology:
Processing method selection hinges on geometry complexity, filler loading limits, and cycle time economics across automotive and electronics production scales.
- Injection Molding:Dominant method for complex LED heat sink geometries and telecommunications housings. Tooling investments concentrate in Germany's industrial corridor around Munich, where battery pack housing specifications are compressing design cycles.
- Extrusion:Continuous profiles for thermal interface pads and renewable energy system gaskets. Japanese compounders serve solar inverter manufacturers with boron nitride-loaded sheet products.
- Compression Molding:Thick-section parts for power module substrates where dielectric strength requirements exceed injection molding capabilities. Korean battery cell manufacturers specify these for 800-volt inverter housings.
- Blow Molding:Hollow conformable shapes for liquid cooling manifolds in data center architectures. Hyperscale facility designers in the US are qualifying polymer cold plates.
- 3D Printing:Topology-optimized heat spreaders for aerospace component prototyping. UK defense contractors maintain specifications for EMI-shielded aluminum alternatives, limiting polymer penetration.
Injection Molding captures the largest installed base; 3D Printing is climbing the fastest as topology optimization penetrates power electronics.
Application:
Application prioritization tracks thermal dissipation wattage requirements, flammability certification needs, and weight reduction mandates across mobility and infrastructure sectors.
- Electric Vehicles:Battery thermal runaway protection housings and power electronics enclosures. China's GB standards on new energy vehicle safety mandate thermal barrier performance that conductive plastics increasingly satisfy, pulling Japanese and Korean compounders into direct supply relationships.
- Consumer Electronics:Smartphone and laptop heat spreaders where corrosion resistance enables thinner wall sections. South Korean OEMs specify injection-molded polymer solutions for 5G handset thermal management.
- LED Lighting:Heat sink housings for high-lumen outdoor luminaires. German lighting manufacturers respond to EU F-Gas Regulation by abandoning metal-and-grease thermal solutions.
- Power Modules:Inverter substrates and IGBT housings in electric drivetrains. Japanese automotive electronics suppliers qualify hybrid ceramic-fluoropolymer composites for 800-volt systems.
- Telecommunications Equipment:Base station heat spreaders and antenna thermal management. Massive MIMO densification in South Korea and Japan opens volume contracts for injection-molded polymer solutions.
Consumer Electronics maintains the deepest volume base; Electric Vehicles is gaining share fastest as battery platform standardization reshapes compound specifications.
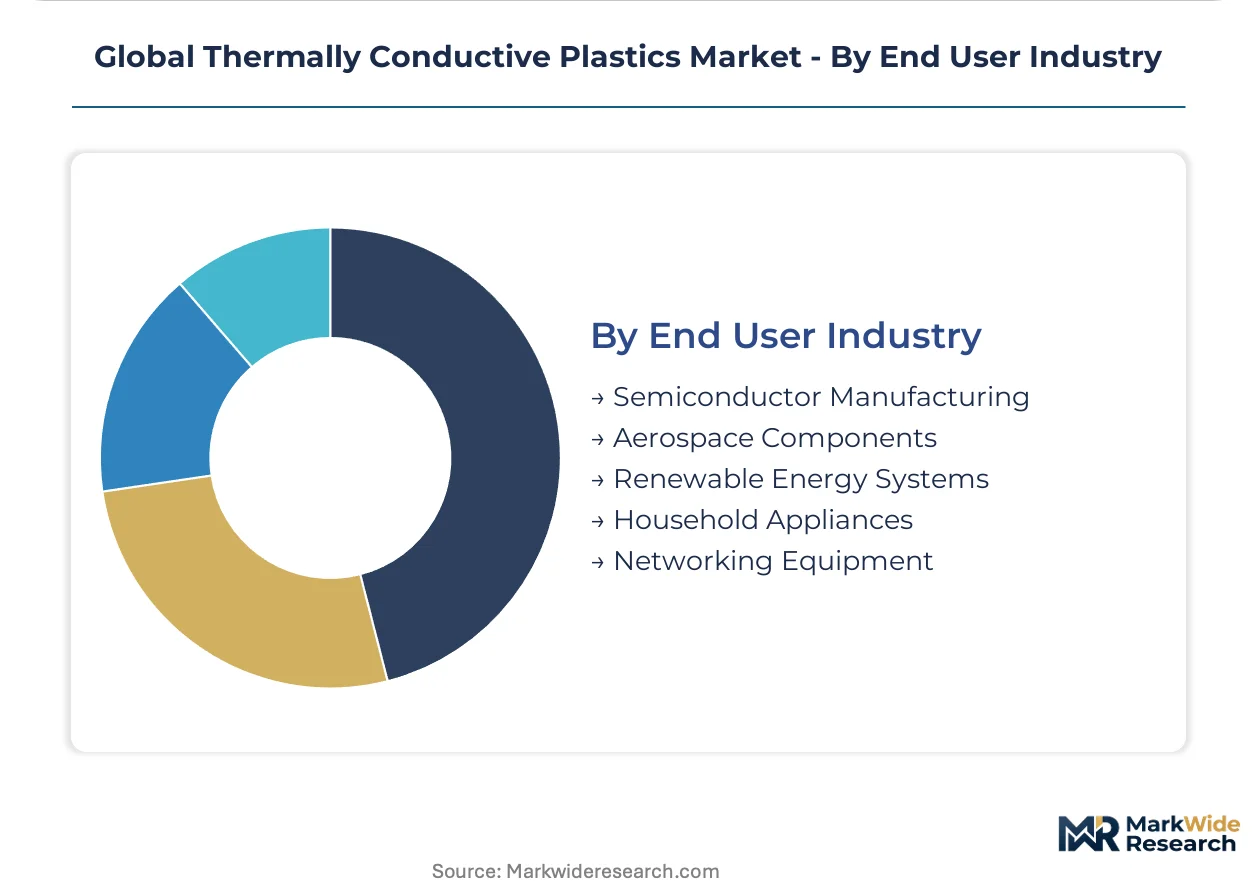
End User Industry:
Industry verticals impose distinct certification regimes, volume scales, and supply chain access requirements that filter compounder participation.
- Semiconductor Manufacturing:Process equipment thermal management and test socket housings. EPA guidelines on electronic waste recyclability tighten material specifications across US-based fabrication facilities.
- Renewable Energy Systems:Solar inverter housings and wind turbine power electronics. India's PLI scheme for advanced chemistry cell manufacturing draws compounder investment toward Gujarat industrial zones.
- Networking Equipment:Router and switch thermal management for hyperscale data centers. Immersion cooling rack architectures create specifications for thermally conductive polymer cold plates.
- Household Appliances:Refrigeration compressor housings and cooking appliance heat shields. EU F-Gas Regulation penalizes conventional refrigerant-based cooling, accelerating polymer adoption.
- Aerospace Components:Satellite and avionics thermal control surfaces. US and UK defense contractors maintain aluminum and copper specifications due to established EMI shielding performance, creating substitution resistance.
Semiconductor Manufacturing commands premium pricing; Renewable Energy Systems shows the steepest expansion trajectory as solar and wind deployments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boron nitride processing clusters in China's Yangtze River industrial corridor anchor raw material supply for conductive filler production. This concentration shapes procurement patterns across automotive and electronics manufacturing hubs in Germany, Japan, South Korea, and the United States.
Germany
Tier-one automotive suppliers around Stuttgart and Munich accelerate procurement of polymer battery housings as EU F-Gas Regulation penalties drive abandonment of metal-and-grease thermal solutions. ECHA REACH restrictions on halogenated flame retardants force reformulation of established polyphenylene sulfide grades. The Baden-Württemberg industrial corridor concentrates injection molding tooling investments for electric vehicle battery pack specifications.
China
GB standards on new energy vehicle safety mandate thermal barrier performance that conductive plastics increasingly satisfy, pulling Japanese and Korean compounders into direct supply relationships with battery manufacturers. MIIT dual carbon goals pressure domestic producers toward lighter thermal management materials. The Gyeonggi-do battery industrial cluster in neighboring South Korea extends influence into Chinese supply chains through direct material specifications.
United States
EPA guidelines on electronic waste recyclability tighten material specifications across semiconductor fabrication facilities, filtering compounder participation in process equipment thermal management. Silicon carbide inverter deployment in electric drivetrains demands lighter heat dissipation materials. The Pacific Northwest hosts hyperscale data center designers qualifying polymer cold plates for immersion cooling rack architectures.
Japan
METI industrial policy supports specialty compounders restructuring capacity to serve electric vehicle thermal management needs. Hybrid ceramic-fluoropolymer composites expand into power module substrates for 800-volt inverter housings. The Kanto region around Tokyo anchors automotive electronics supplier qualification programs for these advanced grades.
South Korea
MFDS-aligned industrial standards and battery cell manufacturer direct specifications compress traditional tiered supply chains, with LG Energy Solution issuing compound requirements directly to global suppliers. Massive MIMO antenna thermal management requirements open volume contracts for injection-molded polymer heat spreaders. The Gyeonggi-do battery industrial cluster concentrates procurement authority for conductive polymer formulations.
Global Thermally Conductive Plastics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue halogen-free and hybrid composite specializations. The market structure consolidates around integrated chemical conglomerates with captive polymerization assets, while regional compounders defend niche positions through formulation agility. Three archetypes dominate: diversified materials conglomerates with backward integration into base resins, specialty compounders focused on thermal filler optimization, and automotive-focused suppliers co-located with OEM engineering centers. Competitive intensity centers on capacity expansion in electric vehicle supply corridors and strategic partnerships bypassing traditional tier-one intermediaries.
Among diversified materials conglomerates, Celanese Corporation anchors North American supply through captive polyamide compounding assets, while SABIC leverages Middle East feedstock access to develop halogen-free conductive formulations. DuPont occupies a position within the specialty tier through fluoropolymer-ceramic hybrid grades targeting power electronics applications. These three exemplify how geographic R&D footprint and resin integration determine competitive positioning in qualification-intensive automotive and electronics channels.
| Leading Market Players |
|---|
| Celanese Corporation |
| SABIC |
| BASF SE |
| DuPont |
| DSM |
| LANXESS |
| Mitsubishi Engineering-Plastics Corporation |
| TORAY INDUSTRIES, INC. |
| KANEKA CORPORATION |
| Others |
Supply & Pricing Matrix
Captive boron nitride processing in China's Yangtze River industrial corridor anchors both raw material positioning and compounder pricing power. German tier-one suppliers around Stuttgart and Munich absorb this concentration through long-term offtake agreements, while Japanese specialty compounders hedge via dual-sourcing strategies.
Pricing Analysis
Warranty-bundled technical support and rapid formulation iteration separate premium compounder tiers from transactional spot suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks UL 94 V-0 certification status and filler loading precision. Cost compression in economy-grade polyamide runs through energy-intensive ceramic processing in China. Battery cell manufacturers exhibit lowest price sensitivity due to thermal runaway liability exposure, while LED lighting OEMs in Guangdong province drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale battery manufacturer demand, bypassing traditional automotive tier-one intermediaries. Raw material supply draws from China, Germany, and Japan for boron nitride, polyphenylene sulfide resin, and silane coupling agents respectively. Single-source vulnerability concentrates in Yangtze River energy-intensive processing nodes exposed to power rationing. Distribution runs through qualified compounder technical centers co-located with Stuttgart, Munich, and Gyeonggi-do engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty compounder capacity expansion lags electric vehicle procurement acceleration, propping pricing power for qualified suppliers. Boron nitride processing bottlenecks in China's industrial corridor sustain this supply constraint.
For Market Incumbents: To counter direct material specification by battery cell manufacturers, Celanese and SABIC should anchor channel control through captive technical service centers in Gyeonggi-do and Baden-Württemberg. Backward integration into halogen-free flame retardant chemistry defends margin position against REACH reformulation costs. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for halogen-free conductive formulation specialists. India's PLI scheme for advanced chemistry cell manufacturing presents the most penetrable geography. Target co-development partnerships with Gujarat-based battery producers seeking localized thermal management supply. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified materials conglomerates seeking electric vehicle thermal management exposure. Five-to-ten year viability favors compounders with captive resin production and qualified automotive grades. Monitor battery platform standardization announcements across OEMs as inflection signal for volume consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Boron nitride-loaded compounding lines in Gyeonggi-do serve LG Energy Solution direct specifications. |
| Backward Integration | Captive polyphenylene sulfide resin production shields Celanese from raw material volatility. |
| Long-term Supply Agreement | Multi-year offtake contracts with Stuttgart-based tier-one suppliers lock in EV battery housing volumes. |
| Joint Venture | Hybrid ceramic-fluoropolymer development partnerships accelerate 800-volt inverter qualification timelines. |
| Green Manufacturing Transition | Halogen-free formulation investments preempt ECHA REACH restrictions on flame retardant chemistry. |
Research Methodology
Trade databases, ECHA regulatory filings, and automotive production statistics formed the secondary backbone for this analysis. Primary interviews with compounder R&D directors, tier-one supplier procurement managers, and battery cell manufacturer thermal engineers validated demand assumptions. Bottom-up and top-down triangulation reconciled volume estimates across material flow analysis and end-use consumption models.
Bottom-up modeling built product-type and application-level forecasts across the analysis window, while top-down approaches cross-checked against automotive and electronics production trajectories. Segmentation dimensions included polymer chemistry, processing technology, thermal conductivity tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed capacity expansion timelines and OEM platform rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide inverter thermal management would alter the outlook. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement intensity and battery platform standardization velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Bismaleimide Monomer Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Global Bio-Based Polyethylene Market