
 Polyamide-Imide (PAI) Market | 2026-2036
Polyamide-Imide (PAI) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyamide-Imide (PAI) Market Analytics
Modular component bundling is restructuring how aerospace and automotive buyers procure PAI materials, shifting from standalone resin purchases to integrated film-coating-composite packages. Solvay SA leverages its vertical chemistry portfolio to anchor European supply chains for high-performance PAI formulations. Toyobo Co Ltd sustains dominant film production capacity in Asia through proprietary extrusion technology. Ensinger GmbH specializes in precision PAI stock shapes for semiconductor and aerospace tooling applications.
Polyamide-imide is a thermosetting polymer combining amide and imide functional groups, synthesized through the condensation of trimellitic anhydride with aromatic diamines, delivering continuous service temperatures exceeding 260°C and exceptional mechanical retention under thermal stress. PAI resins occupy the highest margin tier due to formulation complexity and captive demand from aerospace OEMs requiring FAA-certified materials. PAI coatings represent the fastest-growing product category as industrial gas turbine manufacturers seek erosion-resistant thermal barrier systems. Injection molding technology leads volume throughput for automotive electrical connectors, while 3D printing adoption accelerates in prototyping low-run aerospace brackets.
FAA airworthiness directives and EPA emissions standards jointly determine PAI qualification pathways for US aerospace and automotive suppliers. REACH registration requirements and EU Green Deal material sustainability mandates impose full-life-cycle disclosure obligations on European PAI importers and compounders. Stakeholders must monitor evolving certification harmonization between FAA and EMA frameworks, as diverging thermal testing protocols threaten to fragment cross-Atlantic component approval timelines and inflate compliance duplication costs.
Market Dynamics
Modular component bundling is restructuring PAI procurement, shifting aerospace and automotive buyers from standalone resin purchases toward integrated film-coating-composite packages that consolidate supplier relationships and compress qualification timelines.
Growth Catalysts
- FAA airworthiness directives:Certification requirements for high-temperature engine components are accelerating PAI qualification in US aerospace manufacturing.
- Industrial gas turbine erosion resistance:Thermal barrier coating demand from power generation OEMs is pulling PAI formulations into new high-margin applications.
- German automotive clusters:Stuttgart and Munich production hubs are concentrating injection-molded PAI connector demand for electric vehicle platforms.
Market Restraints
- Trimellitic anhydride feedstock volatility:Aromatic dianhydride supply concentration in Chinese chemical parks creates input cost instability for Western compounders.
- REACH registration complexity:Full-life-cycle disclosure obligations under EU Green Deal mandates are extending European importer compliance timelines by 18-24 months.
- Polyetheretherketone substitution:PEEK resins are capturing lower-temperature aerospace bracket applications where thermal performance requirements have softened.
Strategic Opportunities
- India PLI scheme for specialty chemicals:Production-linked incentives are attracting PAI compounders to establish domestic formulation capacity for aerospace MRO hubs.
- 3D printing convergence:Selective laser sintering of PAI powders is opening low-run aerospace prototyping without hard-tooling investment.
- Semiconductor tooling precision:Wafer-handling component demand from Taiwan and South Korea fabs is creating high-purity PAI stock shape pull.
Industry Challenges
- Polymer synthesis expertise scarcity:Condensation chemistry specialists capable of imide-ring closure optimization are concentrated among retiring cohorts at incumbent compounders.
- FAA-EMA thermal testing harmonization gaps:Divergent glass transition temperature protocols are forcing dual qualification runs for cross-Atlantic component approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyamide-Imide (PAI) Market |
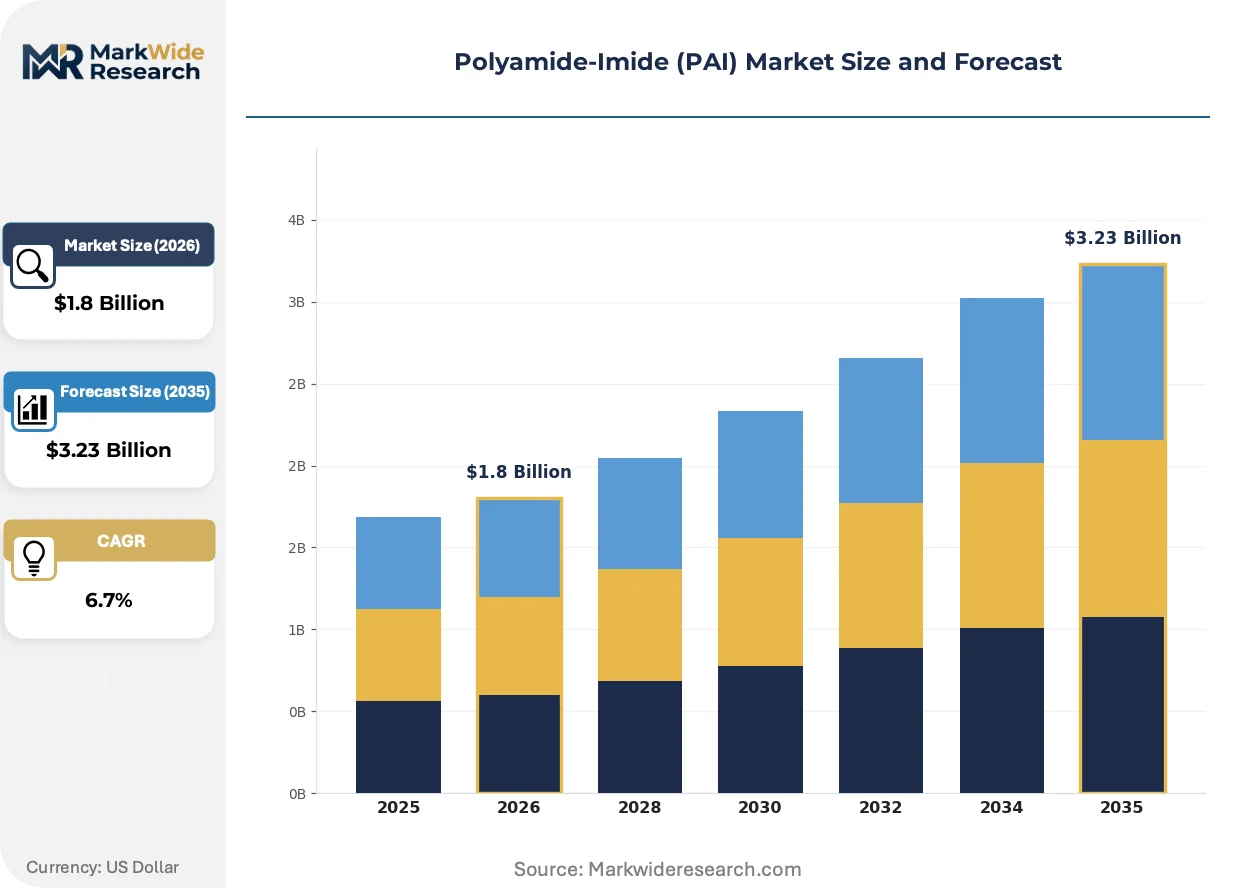
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PAI Films, PAI Coatings, PAI Composites, PAI Resins Application: Aerospace, Automotive Components, Electrical Insulation, Industrial Applications End User: Aerospace Manufacturers, Automotive OEMs, Electrical Equipment Producers, Industrial Machinery Technology: Injection Molding, Extrusion, 3D Printing, Coating Techniques |
| Companies Covered | Solvay SA, Toyobo Co Ltd, Innotek Technology Ltd, Elantas GmbH, Ensinger GmbH, Mitsubishi Chemical Corporation, Fujifilm Corporation, Kermel SA, Allnex Netherlands BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyamide-Imide (PAI) Market Evolving Landscape
Active materials science breakthroughs are compressing traditional thermal performance boundaries while regulatory disclosure mandates and procurement consolidation are rewriting how PAI flows from compounder to end-use.
Additive manufacturing of PAI structural components is converging with aerospace OEM demand for rapid prototyping of high-temperature brackets. Boeing and Airbus engineering teams are qualifying laser-sintered PAI parts for non-load-bearing engine bay applications. This convergence is collapsing traditional 18-month tooling cycles into 6-week digital production runs for low-volume aerospace programs.
REACH registration requirements under ECHA oversight are mandating polymer substance identity disclosure down to monomer residual thresholds. European compounders must now document full supply chain chemistry for PAI importers. German and French aerospace suppliers are responding by captive-sourcing certified resin batches to avoid disclosure exposure.
Integrated procurement packages are displacing standalone resin purchasing across tier-one automotive and aerospace buyers. Tier-one suppliers now specify film-coating-composite bundles rather than discrete material grades. This pattern is most pronounced in Stuttgart automotive clusters and Seattle aerospace supply chains where vendor reduction programs dominate sourcing strategy.
Polyamide-Imide (PAI) Market Segmentation
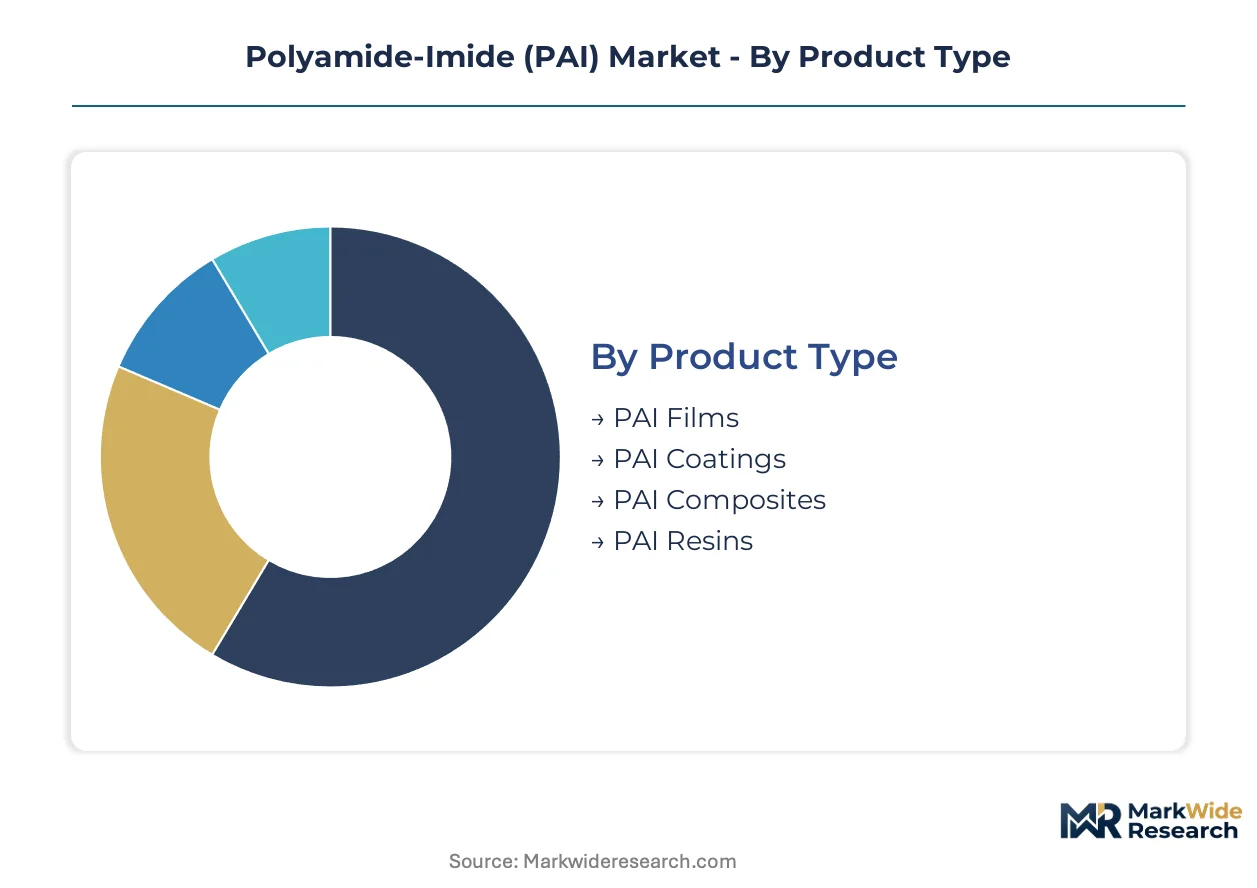
PAI market segmentation reveals distinct capital requirements and margin profiles across product forms and manufacturing technologies. Aerospace qualification timelines and automotive volume demands create divergent investment thresholds for compounders serving each tier.
Product Type:
Capital intensity varies sharply across PAI product categories, with resin synthesis requiring the heaviest upfront chemical plant investment while downstream conversion demands specialized but less capital-intensive equipment.
- PAI Resins:Base polymer formulations synthesized through trimellitic anhydride condensation with aromatic diamines demand continuous reactor systems and solvent recovery infrastructure. Boeing and Airbus OEMs in the United States and France drive specification development, with FAA-certified batches commanding formulation premiums. Captive resin production is expanding among German automotive suppliers seeking supply security.
- PAI Coatings:Solvent-borne and powder coating systems for thermal barrier applications require precision dispersion equipment and controlled atmosphere curing ovens. Industrial gas turbine manufacturers in Germany and Japan are pulling high-erosion-resistance formulations into power generation maintenance cycles. EPA emissions compliance adds capital burden for US-based coating operations.
- PAI Films:Proprietary extrusion lines with multi-layer die technology produce thin-gauge insulation for electrical applications.
- PAI Composites:Prepreg and filament winding operations integrate resin matrices with carbon or glass fiber reinforcement.
Most installed capacity flows through PAI Resins. Expansion is steepest in PAI Coatings.
Application:
Application segmentation tracks thermal performance thresholds, with each tier imposing distinct certification burdens and qualification timelines on material suppliers.
- Aerospace:Engine components, airframe brackets, and thermal protection systems operate above 260°C continuous service temperature. FAA airworthiness directives in the United States and EMA certification pathways in Europe enforce parallel qualification runs. Laser-sintered prototyping is compressing development cycles for low-volume programs at Seattle and Toulouse engineering centers.
- Automotive Components:Electrical connectors, transmission seals, and thermal management modules for electric vehicle platforms concentrate demand in Stuttgart and Munich production clusters. Injection molding at automotive scale requires resin grades with optimized melt flow indices. NHTSA material traceability rules govern US-sourced connector batches.
- Electrical Insulation:Wire enamel and slot liner applications serve motor and transformer manufacturers.
- Industrial Applications:Seals, bearings, and valve components for chemical processing equipment round out the category.
Aerospace commands the highest margin tier. Automotive Components are gaining share fastest as EV thermal management requirements intensify.
End User:
End user concentration shapes procurement leverage, with tier-one OEMs consolidating supplier relationships through integrated material-service bundles.
- Aerospace Manufacturers:Boeing, Airbus, and their tier-one subsystem suppliers specify certified resin batches with full chain-of-custody documentation. Dual sourcing mandates from FAA and EMA regulators prevent single-supplier dependencies for flight-critical components. Captive compounding partnerships are proliferating among French and German aerospace clusters.
- Automotive OEMs:Volkswagen Group, BMW, and Mercedes-Benz procurement teams in Germany negotiate multi-year resin supply agreements tied to EV platform launch schedules. REACH substance disclosure requirements impose documentation burdens on European automotive supply chains. Volume pricing structures favor suppliers with regional compounding presence.
- Electrical Equipment Producers:Motor and transformer manufacturers in Taiwan and South Korea specify high-purity film grades.
- Industrial Machinery:Pump, valve, and compressor OEMs source stock shapes and semi-finished forms.
Aerospace Manufacturers anchor premium-grade demand. Automotive OEMs are expanding specifications most aggressively.
Technology:
Technology selection determines throughput economics and geometric capability, with each process route optimized for distinct part complexity and volume requirements.
- Injection Molding:High-pressure molding systems with heated tool designs process glass-filled PAI grades for automotive connectors and industrial components. Stuttgart automotive suppliers operate the densest concentration of qualified PAI molding cells outside Asia. Tooling investments for high-temperature resins exceed standard thermoplastic setups by 40-60%.
- 3D Printing:Selective laser sintering of PAI powders enables topology-optimized brackets without hard-tooling investment. Boeing and Airbus engineering teams are qualifying laser-sintered parts for non-load-bearing engine bay applications. Build chamber size limitations currently constrain part scale.
- Extrusion:Continuous profile and film production serves electrical insulation and stock shape markets.
- Coating Techniques:Electrostatic spray and dip coating systems apply thermal barrier layers to turbine components.
Injection Molding carries the heaviest installed equipment base. 3D Printing is climbing the fastest as aerospace prototyping demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyamide-imide chemistry originated in United States aerospace laboratories during the 1960s thermal materials race, with early formulations developed for supersonic aircraft engine seals. Commercial scale followed through partnerships between chemical compounders and defense contractors, establishing production know-how that later diffused to European and Asian manufacturing clusters.
United States
Boeing and Airbus tier-one suppliers in Washington State and Kansas drive certified resin demand for engine bay brackets and thermal protection systems. FAA airworthiness directives mandate parallel qualification runs that extend supplier onboarding timelines. Seattle-Tacoma aerospace clusters concentrate injection molding capacity for flight-critical electrical connectors.
Germany
Stuttgart and Munich automotive production hubs concentrate demand for glass-filled PAI grades serving electric vehicle thermal management modules. REACH registration requirements under ECHA oversight impose full supply chain disclosure obligations on compounders. Industrial gas turbine OEMs in the Ruhr region pull high-erosion-resistance coating formulations into power generation maintenance cycles.
China
Trimellitic anhydride feedstock concentration in Jiangsu and Zhejiang chemical parks creates cost advantages for domestic resin synthesis. MIIT industrial standards govern material qualification for aerospace MRO applications. Yangtze River Delta fabrication clusters are expanding precision stock shape capacity for semiconductor tooling exports.
Japan
Toyobo's proprietary extrusion technology anchors Asia-Pacific film production for electrical insulation applications. METI technology roadmaps prioritize high-temperature polymer development for next-generation power electronics. Osaka-Kobe industrial corridors concentrate coating formulation expertise serving domestic turbine manufacturers.
India
PLI scheme production-linked incentives are attracting PAI compounders to establish domestic formulation capacity for aerospace maintenance hubs. BIS certification requirements govern material imports for defense aviation applications. Bengaluru-Hyderabad aerospace corridors are emerging as qualification centers for regional MRO operations.
Polyamide-Imide (PAI) Market Competitive Landscape
The competitive structure tilts toward vertically integrated chemical conglomerates with captive resin synthesis and downstream conversion capabilities. European and Japanese players dominate premium-grade formulation through decades of condensation chemistry expertise accumulation. Three archetypes define positioning: integrated chemical majors controlling full value chains, specialized film and coating converters with proprietary process technology, and regional compounders serving automotive tier-one contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing feedstock agreements and joint development contracts with aerospace OEMs.
Among European chemical majors, Solvay SA and Ensinger GmbH exemplify the integrated archetype through backward control over high-performance polymer supply chains. Japanese specialists Toyobo Co Ltd and Mitsubishi Chemical Corporation occupy positions emphasizing proprietary extrusion and film conversion technology. These named entities represent distinct strategic postures without implying specific market share claims or operational details beyond their evident geographic and structural positioning.
| Leading Market Players |
|---|
| Solvay SA |
| Toyobo Co Ltd |
| Innotek Technology Ltd |
| Elantas GmbH |
| Ensinger GmbH |
| Mitsubishi Chemical Corporation |
| Fujifilm Corporation |
| Kermel SA |
| Allnex Netherlands BV |
| Others |
Value Network & Pricing Analysis
EU Green Deal material sustainability mandates gate qualified supply access and premium-tier pricing power for PAI compounders serving European aerospace and automotive OEMs. REACH full-life-cycle disclosure obligations extend compliance timelines by 18-24 months, compressing margins for importers while rewarding captive-sourced resin producers with pricing premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies PAI markets by certification grade and volume scale. FAA-certified resin batches for flight-critical aerospace components command formulation premiums, while automotive-grade injection molding compounds compete on melt flow optimization and regional delivery cost. Cost compression in standard-tier automotive grades is intensifying because PEEK substitution threatens lower-temperature bracket applications. Tier-one automotive OEMs in Germany exhibit highest price sensitivity through multi-year volume negotiations, whereas Boeing and Airbus procurement teams prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for PAI resin and film distribution. Trimellitic anhydride feedstock concentration in Chinese chemical parks creates input cost instability for Western compounders drawing from Jiangsu and Zhejiang production. Aromatic diamine supply rests on petrochemical naphtha cracking capacity concentrated in South Korea and Taiwan. Single-source vulnerability around imide-ring closure chemistry expertise threatens formulation continuity as retiring cohorts exit incumbent compounders. Distribution runs through qualified compounder-to-OEM direct relationships, bypassing commodity chemical distributors for certified aerospace batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PAI functions as a regulatory compounder where FAA airworthiness directives and REACH registration requirements jointly determine qualification pathways and demand concentration among certified suppliers.
For Market Incumbents: Deepen captive resin synthesis partnerships with German and French aerospace clusters to eliminate REACH disclosure exposure for tier-one automotive suppliers. Expand backward integration into trimellitic anhydride feedstock through long-term offtake agreements with Chinese chemical park operators. PEEK substitution in lower-temperature aerospace brackets threatens margin compression in standard-grade resin tiers. For New Entrants and Emerging Players: Tier-one subsystem suppliers represent the most penetrable channel partner type for qualification-light PAI coating formulations serving industrial gas turbine maintenance cycles. Target India's PLI scheme production-linked incentives for domestic compounding capacity serving Bengaluru-Hyderabad aerospace MRO corridors. White-space exists in selective laser sintering powder grades for low-run aerospace prototyping without hard-tooling investment. For Investors and Strategic Acquirers: Roll-up economics work for specialized film and coating converters because proprietary extrusion technology creates defensible moats against commodity resin competition. Five-to-ten-year viability hinges on consolidation of European REACH-compliant formulation assets. Watch for FAA-EMA thermal testing harmonization milestones as inflection indicators for cross-Atlantic component approval timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trimellitic Anhydride | Secures feedstock cost stability for Western compounders facing Chinese supply concentration. |
| REACH-Compliant Captive Sourcing Partnerships | Eliminates disclosure exposure for German automotive suppliers under ECHA oversight. |
| Selective Laser Sintering Powder Qualification | Opens 6-week prototyping cycles for Boeing and Airbus low-volume aerospace programs. |
| India PLI Scheme Domestic Capacity | Attracts compounders to Bengaluru-Hyderabad aerospace MRO qualification centers. |
| FAA-EMA Testing Protocol Harmonization | Reduces dual qualification cost burden for cross-Atlantic component approvals. |
Research Methodology
Multiple input streams — primary interviews with resin synthesis directors, automotive procurement leads, and aerospace tier-one supplier quality managers; secondary validation through SEC 10-K filings, ECHA REACH registration databases, and MIIT industrial standard disclosures — were reconciled using bottom-up and top-down triangulation. Plant managers at German automotive clusters and coating formulation specialists in Japan's Osaka-Kobe corridor contributed operational perspective on melt flow optimization and thermal barrier application requirements.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmented modeling by product type, application tier, end-user concentration, and manufacturing technology. CAGRs were derived from production capacity expansion announcements, OEM platform launch schedules, and regulatory milestone timelines. Forecast inputs incorporated EV thermal management module adoption curves and industrial gas turbine maintenance cycle frequencies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FAA-EMA harmonization progress, trimellitic anhydride feedstock volatility, and PEEK substitution thresholds in softened thermal performance applications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
High-Density Polyethylene (HDPE) Resins Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Water-Borne Resins Market