
 High-Density Polyethylene (HDPE) Resins Market | 2026-2036
High-Density Polyethylene (HDPE) Resins Market Size, Share, and Industry Trends Forecast 2026-2036
High-Density Polyethylene (HDPE) Resins Market Intelligence
The US Gulf Coast petrochemical corridor is fragmenting as new ethane crackers diversify downstream output. Dow Inc. leverages integrated feedstock access to sustain cost leadership in injection molding grades. LyondellBasell Industries anchors North American supply through Channelview complex scale. Sinopec competes on volume in Asian pipe-grade segments.
High-Density Polyethylene (HDPE) Resins comprise linear thermoplastic polymers produced via Ziegler-Natta or metallocene catalysis, with density ranging from 0.941 to 0.965 g/cm³ and melt index values spanning 0.01 to 50 g/10 min. These specifications enable load-bearing structural applications across packaging, conduit systems, and durable goods manufacturing. Blow molding grades command premium positioning in rigid container segments where FDA and EFSA compliance differentiates food-contact supply chains. Pipe grade dominates infrastructure procurement with multi-decade service life requirements. Film grade occupies mature agricultural and retail bag segments where recycled pellet integration is accelerating.
FDA food-contact regulations, EU REACH substance restrictions, and China's GB standards for plastic recyclability collectively reshape formulation requirements and market access conditions. EPA emissions frameworks and MEE environmental enforcement in China tighten cracker-to-resin pathway compliance costs. Stakeholders must monitor regulatory divergence between jurisdictions to optimize grade portfolios and certification investments.
Market Dynamics
Feedstock volatility and cracker-to-resin pathway consolidation are compressing margin structures across HDPE value chains. Producers with captive ethane access anchor cost positions while merchant buyers face escalating basis risk.
Growth Catalysts
- EU REACH substance restrictions:Compliance mandates are accelerating formulation upgrades toward certified recyclate streams in rigid packaging applications.
- Municipal water infrastructure:Pipe-grade procurement is intensifying across India and Southeast Asia as utilities replace aging metallic conduit systems.
- Metallocene catalysis:Narrow molecular weight distribution polymers are penetrating high-clarity blow molding segments previously served by conventional Ziegler-Natta grades.
Market Restraints
- Ethane feedstock volatility:Naphtha-to-ethane spreads compress during crude price spikes, eroding cost advantage for Gulf Coast crackers.
- Supply concentration in Middle Eastern exporters:State-linked producers control discretionary export volumes, amplifying price discovery opacity.
- Polypropylene substitution:Random copolymer PP grades are displacing HDPE in thin-wall injection molding where stiffness requirements moderate.
Strategic Opportunities
- India's municipal water infrastructure:Underpenetrated district-level distribution networks require multi-decade pipe-grade commitments with localized extrusion partnerships.
- Post-consumer recyclate certification:FDA and EFSA food-contact approvals for mechanically recycled HDPE unlock premium positioning in rigid container segments.
- Digital procurement platforms:Spot-market aggregation tools are emerging in Asian trading hubs, disintermediating traditional distributor networks.
Industry Challenges
- Process engineering talent scarcity:Cracker optimization and metallocene catalyst handling require specialized skill sets concentrated among retiring technical cohorts.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and GB standard approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Density Polyethylene (HDPE) Resins Market |
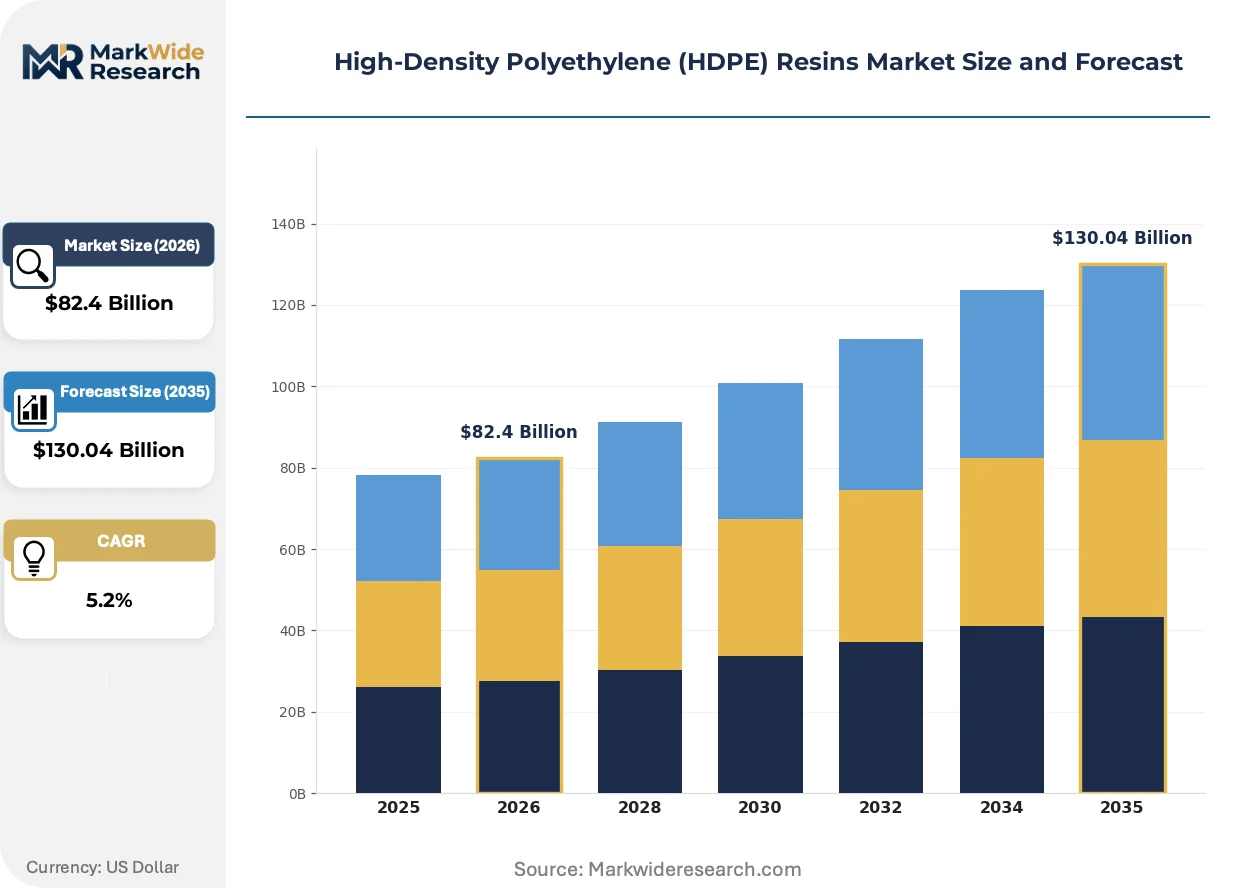
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $130.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Blow Molding, Extrusion, Film Grade, Pipe Grade Application: Packaging, Construction Materials, Consumer Goods, Agricultural Films, Industrial Containers End User: Plastic Manufacturers, Packaging Companies, Builders, Farmers, Chemical Processors Packaging Type: Granules, Pellets, Powder, Recycled Pellets, Loose Bulk |
| Companies Covered | Dow Inc., Chevron Phillips Chemical Company, LyondellBasell Industries, Formosa Plastics Corporation, Reliance Industries Limited, ExxonMobil Corporation, INEOS Group, Sinopec, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Density Polyethylene (HDPE) Resins Market Strategic Shifts & Innovations
Catalysis advances and regulatory recyclate mandates are converging to redefine grade differentiation. Producers now compete on molecular architecture precision rather than commodity scale alone.
Metallocene single-site catalysts are migrating from niche medical packaging into mainstream blow molding applications. Food-contact certified converters in Germany and the Netherlands are adopting these grades for dairy bottle production. This technology is compressing conventional Ziegler-Natta margins in clarity-sensitive segments while enabling downgauging without performance loss.
China's GB standards for plastic recyclability are mandating traceable recycled content thresholds in rigid packaging. MEE enforcement mechanisms are tightening supply chain documentation requirements. Domestic blow molders are responding by integrating certified post-consumer pellet streams ahead of export market access deadlines.
Buyer consolidation among European retail grocery chains is compressing supplier rosters and extending contract durations. Three-to-five-year offtake agreements with fixed-volume escalators are displacing spot-market procurement. This pattern is most visible in Germany and France where Aldi and Carrefour procurement teams centralize resin specification authority.
High-Density Polyethylene (HDPE) Resins Market Segmentation
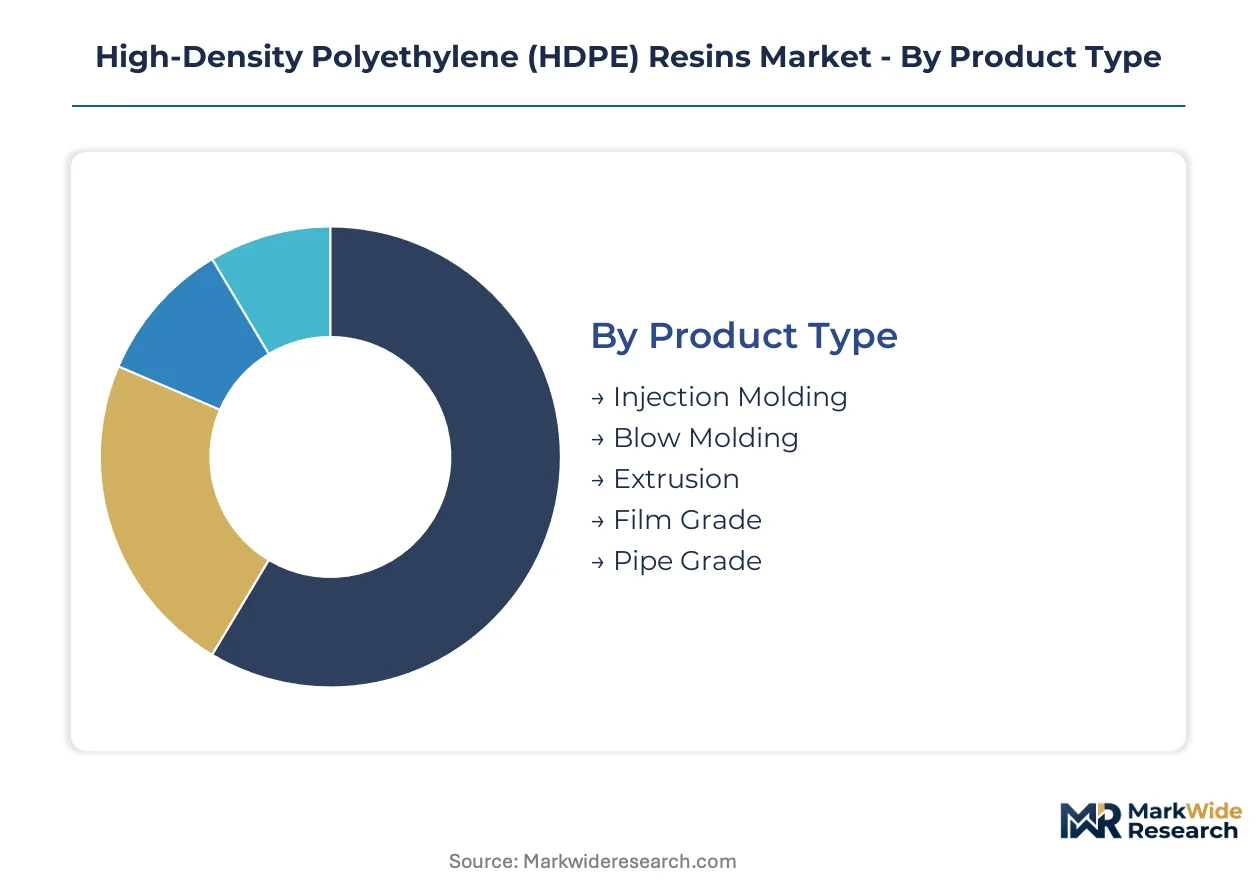
HDPE resin specifications diverge sharply across processing methods and end-use durability requirements. Molecular weight distribution and density tolerances determine grade selection for blow molding versus pipe extrusion. Understanding these technical boundaries enables procurement teams to match material certificates against regulatory compliance timelines.
Product Type:
Processing temperature windows and shear stability requirements fragment the technical landscape across five distinct manufacturing pathways.
- Injection Molding:Narrow molecular weight distribution grades with melt indices of 5–50 g/10 min enable thin-wall part production for consumer durables. Automotive component suppliers in Germany specify these grades for interior trim applications requiring dimensional stability under thermal cycling.
- Blow Molding:High molecular weight resins with density above 0.950 g/cm³ provide melt strength for large-part hollow forming. Dairy bottle converters in the Netherlands prioritize EFSA food-contact certified grades for extended shelf-life liquid packaging.
- Extrusion:Broad distribution polymers accommodate profile and sheet forming with balanced flow characteristics. Window frame manufacturers specify these grades for weather-resistant construction components.
- Film Grade:Linear low-density blends with HDPE base resins optimize tear resistance in agricultural covering applications. Stretch wrap producers favor these specifications for load containment films.
- Pipe Grade:PE100 and PE80 classifications deliver multi-decade hydrostatic strength for pressure-rated conduit systems. Municipal water authorities in India specify these resins for buried distribution networks replacing metallic infrastructure.
Established volume favors Pipe Grade; emerging adoption favors Blow Molding.
Application:
End-use performance requirements stratify procurement specifications across durability, chemical resistance, and regulatory exposure levels.
- Packaging:FDA and EFSA compliance mandates dominate rigid container specifications for food-contact applications. German retail chains centralize resin authority through three-to-five-year offtake agreements with certified converters.
- Construction Materials:Weathering resistance and load-bearing specifications govern geomembrane and structural profile selection. Infrastructure contractors specify these grades for landfill liners and tunnel waterproofing systems.
- Consumer Goods:Houseware and furniture producers prioritize surface finish consistency and colorability in injection molding grades. Asian durable goods manufacturers specify these resins for outdoor storage products.
- Agricultural Films:UV stabilizer packages extend service life in greenhouse and mulch film applications. Farmers in Spain and Italy specify these grades for season-extending covered cultivation systems.
- Industrial Containers:Chemical resistance specifications govern intermediate bulk container and drum manufacturing. Chemical processors require UN-certified grades for hazardous material transport compliance.
Margin compression concentrates in Packaging; specification premiums persist in Construction Materials.
End User:
Buyer technical sophistication and certification requirements create distinct procurement behavior patterns across the value chain.
- Plastic Manufacturers:Compounders and masterbatch producers specify base resin consistency for additive dispersion uniformity. These buyers maintain captive laboratory capacity for incoming material verification.
- Packaging Companies:Food-contact converters integrate post-consumer recyclate streams to meet retailer sustainability mandates. Aldi and Carrefour procurement teams enforce GB standard traceability documentation for Asian supply sources.
- Builders:Construction contractors prioritize long-term hydrostatic performance certification over unit cost minimization. These buyers specify PE100 pipe grades for fifty-year design life infrastructure commitments.
- Farmers:Agricultural end-users balance film thickness optimization against seasonal replacement economics. These buyers exhibit price sensitivity in commodity mulch film procurement.
- Chemical Processors:Industrial container specifications require UN dangerous goods testing and transport certification. These buyers maintain rigid supplier qualification protocols for hazardous material containment.
Technical specification authority concentrates with Plastic Manufacturers; volume scaling favors Packaging Companies.
Packaging Type:
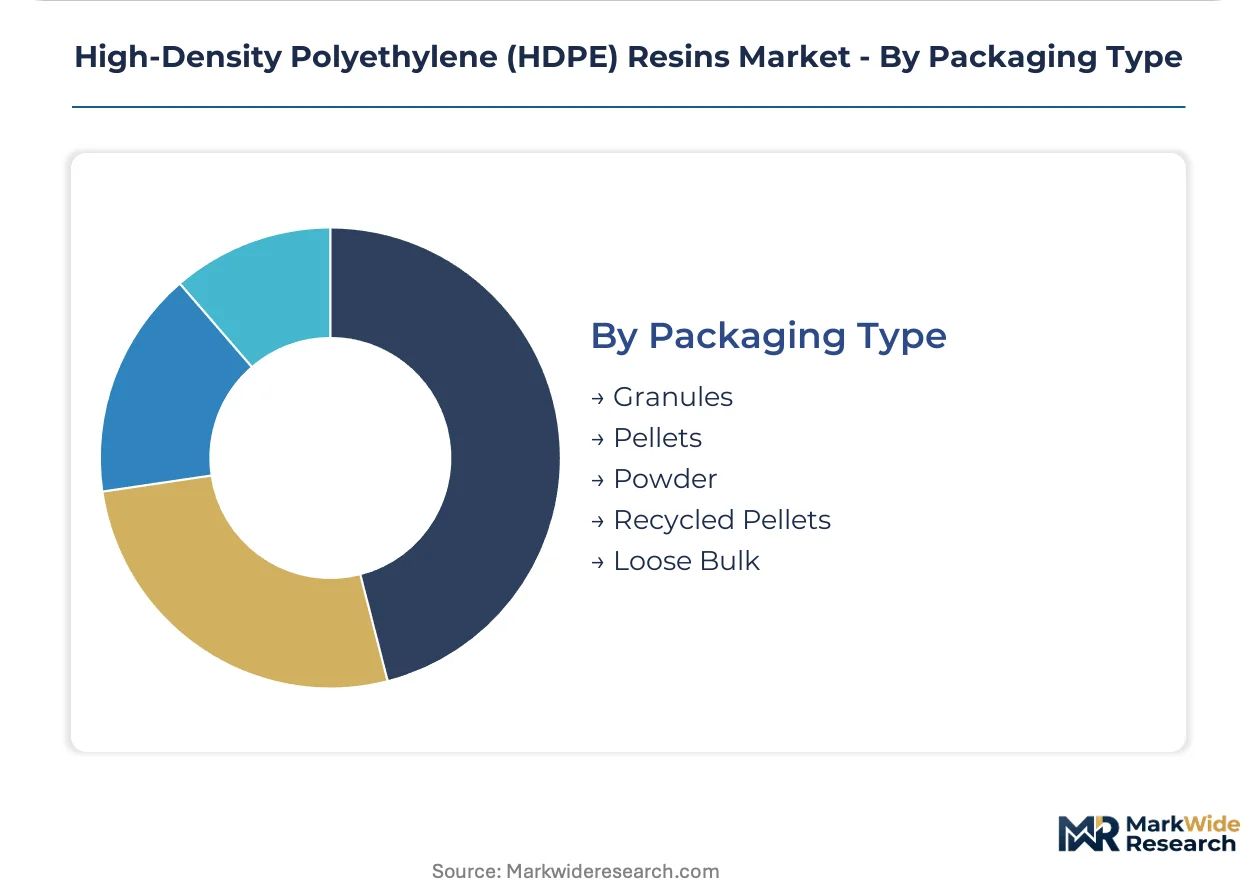
Material handling economics and contamination risk profiles determine physical form selection for downstream processing.
- Granules:Uniform particle size distribution enables precise feeding in automated compounding operations. Masterbatch producers specify these forms for high-throughput color concentrate manufacturing.
- Pellets:Cylindrical extruded forms dominate blow molding and injection molding feed systems. FDA-certified pellet streams command premium positioning in dairy bottle supply chains.
- Powder:Fine particle grades serve rotational molding and coating applications requiring sintering behavior. These forms exhibit higher dust exposure and handling complexity.
- Recycled Pellets:Post-consumer mechanically recycled streams require MEE documentation for Chinese GB standard compliance. Domestic blow molders integrate these pellets ahead of export market access deadlines.
- Loose Bulk:Railcar and silo truck delivery minimizes packaging cost for high-volume pipe extrusion operations. These forms require dedicated pneumatic handling infrastructure at receiving facilities.
Processing efficiency favors Pellets; sustainability positioning favors Recycled Pellets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-linked producers in Saudi Arabia and integrated petrochemical majors on the US Gulf Coast command discretionary export volumes, while Asian demand concentrates in pipe-grade procurement for municipal infrastructure replacement cycles.
United States
Ethane crackers along the Texas and Louisiana corridor leverage captive feedstock access to sustain cost leadership in injection molding grades. EPA emissions frameworks tighten cracker-to-resin pathway compliance costs for merchant buyers. Dow Inc. anchors supply through integrated Channelview complex scale, while LyondellBasell Industries maintains position in specialty blow molding segments.
Germany
Food-contact converters prioritize EFSA-certified grades for dairy bottle production requiring extended shelf-life barrier properties. REACH substance restrictions accelerate formulation upgrades toward certified recyclate streams in rigid packaging. Industrial clusters in North Rhine-Westphalia concentrate blow molding capacity serving Aldi and Carrefour centralized procurement mandates.
China
Domestic blow molders integrate certified post-consumer pellet streams ahead of export market access deadlines under tightening GB standards. MEE environmental enforcement mechanisms tighten supply chain documentation requirements for plastic recyclability compliance. Sinopec competes on volume in pipe-grade segments while Yangtze River Delta converters scale metallocene-grade adoption for high-clarity applications.
India
Municipal water authorities specify PE100 pipe grades for buried distribution networks replacing aging metallic infrastructure across underpenetrated district-level systems. BIS certification requirements govern material specifications for pressure-rated conduit procurement. Reliance Industries scales pipe-grade capacity through localized extrusion partnerships serving state-level utility tenders.
Saudi Arabia
State-linked producers control discretionary export volumes to Asian and European markets, amplifying price discovery opacity during supply disruptions. SABIC anchors regional supply through integrated cracker complexes with direct access to associated gas feedstocks. Eastern Province industrial cities concentrate export-oriented resin production serving global blow molding and pipe-grade demand.
High-Density Polyethylene (HDPE) Resins Market Key Industry Players
Integrated petrochemical majors and state-linked national champions split the market between feedstock-captive cost leadership and discretionary export volume control. Gulf Coast ethane crackers anchor North American supply positions while Middle Eastern producers leverage associated gas economics for Asian market penetration. Two strategic archetypes dominate: vertically integrated oil-to-resin operators with cracker ownership, and polymer-focused specialists with metallocene catalyst differentiation. Competitive moves concentrate on capacity expansion in India and Southeast Asia, plus portfolio diversification toward food-contact certified recyclate streams.
Within the integrated operator tier, Dow Inc. and LyondellBasell Industries exemplify Gulf Coast feedstock-captive positioning, while Sinopec occupies a scale-driven role in Asian pipe-grade supply. Reliance Industries represents the emerging market expansion archetype with India-focused municipal infrastructure commitments. These anchors illustrate how geographic feedstock access and regional demand specialization stratify competitive positioning across blow molding, pipe-grade, and injection molding segments.
| Leading Market Players |
|---|
| Dow Inc. |
| Chevron Phillips Chemical Company |
| LyondellBasell Industries |
| Formosa Plastics Corporation |
| Reliance Industries Limited |
| ExxonMobil Corporation |
| INEOS Group |
| Sinopec |
| SABIC |
| Others |
Cost & Logistics Intelligence
Undercapacity signals from Middle Eastern export complexes are tightening spot-market discipline and amplifying price discovery opacity for merchant buyers across Asian trading hubs.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across food-contact and non-food-contact grade segments. Three-tier pricing structure across premium metallocene-certified, standard Ziegler-Natta, and economy regrind levels separates buyers by certification burden and clarity requirements. Cost compression in standard injection molding grades is intensifying because polypropylene substitution in thin-wall applications erodes volume commitments. Packaging companies exhibit highest price sensitivity due to retailer sustainability mandates compressing resin specification premiums, while municipal water authorities prioritize hydrostatic performance certification over unit cost minimization.
Supply Chain Analysis
Ethane feedstock availability in Saudi Arabia, the United States, and Qatar anchors upstream cost positions for cracker-to-resin pathways. HDPE production draws from naphtha, ethane, and propane feedstock streams with regional economics tethered to local hydrocarbon extraction infrastructure. Single-source vulnerability concentrates in state-linked Middle Eastern exporters controlling discretionary spot volumes. Distribution runs through long-term offtake agreements with three-to-five-year fixed-volume escalators displacing spot-market procurement among European retail grocery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among European retail grocery chains is shifting procurement leverage toward centralized specification authority and extended contract durations.
For Market Incumbents: Harden food-contact certification portfolios against REACH substance restriction upgrades by investing in EFSA-compliant recyclate stream integration. Anchor cost positions through captive ethane access or backward integration into cracker capacity. Defend against metallocene-grade displacement by accelerating clarity-performance matching in dairy bottle segments.
For New Entrants and Emerging Players: Build out localized extrusion partnerships in underpenetrated Indian district-level water distribution networks requiring PE100 pipe-grade commitments. Target municipal infrastructure procurement with BIS-certified material specifications and multi-decade service life guarantees. Penetrate through digital procurement platform aggregation in Asian trading hubs disintermediating traditional distributor networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across metallocene catalyst handling and cracker optimization capabilities requiring specialized process engineering talent. Five-to-ten-year viability favors vertically integrated operators with feedstock-captive positions and regional demand specialization in pipe-grade or blow molding segments. Monitor FDA and EFSA food-contact approval timelines for mechanically recycled HDPE as inflection indicator for premium positioning in rigid container supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Capacity | Captive ethane access anchors cost leadership against naphtha-dependent merchant buyers. |
| Metallocene Catalyst Adoption | Narrow molecular weight distribution penetrates high-clarity blow molding segments in Germany and the Netherlands. |
| Post-Consumer Recyclate Certification | FDA and EFSA food-contact approvals unlock premium positioning in Aldi and Carrefour supply chains. |
| Localized Extrusion Partnerships | India-focused municipal water infrastructure commitments require district-level distribution network penetration. |
| Digital Procurement Platform Development | Spot-market aggregation tools disintermediate traditional distributor networks in Asian trading hubs. |
Research Approach
Initial hypotheses were tested against primary input from cracker operations managers, blow molding technical directors, municipal procurement officers, and resin distribution channel partners and refined through secondary validation. Trade data from customs authorities, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and MEE environmental enforcement disclosures provided foundational benchmarks. Bottom-up grade-volume modeling and top-down regional demand triangulation converged on segment-level outputs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include processing method, application durability requirement, end-user technical sophistication, and packaging physical form. CAGRs were derived through regression analysis against feedstock cost trajectories and infrastructure investment cycles. Metallocene-grade adoption curves and recyclate certification timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-linked Middle Eastern exporters or accelerated polypropylene substitution would shift outcomes. Cross-checking against customs trade flow data and cracker utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Polypropylene and High-Impact Polystyrene Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Emulsion PVC Market