
 Polysorbate Market | 2026-2036
Polysorbate Market Size, Share, and Industry Trends Forecast 2026-2036
Polysorbate Market Intelligence
The unbundling of polysorbate grades based on purity and application-specific testing is repositioning buyer choice away from commodity sourcing. Croda International plc leverages its specialization in high-purity excipients for biopharmaceutical applications. Evonik Industries competes on its broad portfolio and extensive manufacturing footprint across multiple regions. Meanwhile, BASF Corporation sustains its market presence through large-scale production and integrated supply chains for food and personal care segments.
Polysorbates are nonionic surfactants synthesized via the ethoxylation of sorbitan esters derived from sorbitol. The numeric designation, like in Polysorbate 80, specifies the linked fatty acid (oleic acid), with the compound's main purpose being emulsion stabilization. Demand for Polysorbate 80 in pharmaceutical applications, especially for biologics, generates the highest market value. Meanwhile, Polysorbate 20 and 60 serve the high-volume, cost-focused food & beverage and cosmetics industries.
Market access is governed by stringent quality standards set by pharmacopeias and regulatory bodies like the US FDA and the European Medicines Agency (EMA). These regulations mandate extensive characterization of excipients to control impurities, directly influencing manufacturing processes and costs for pharmaceutical-grade polysorbates. Success for suppliers will hinge on their ability to provide consistent, high-purity products that meet evolving regulatory expectations for novel therapeutics.
Market Dynamics
The central structural force shaping the polysorbate market is the unbundling of product grades based on purity. Stringent regulatory demands for well-characterized, high-purity excipients in biopharmaceutical applications are segmenting the market away from a commodity chemical footing.
Growth Catalysts
- Biologic Drug Expansion:The growing pipeline of monoclonal antibodies, vaccines, and cell therapies, which rely on polysorbates for formulation stability, is the primary demand driver, particularly in biomanufacturing hubs across China and the United States.
- Regulatory Mandates for Purity:Stricter guidelines from the EMA and FDA regarding excipient characterization and impurity control for parenteral drugs compel manufacturers to source higher-grade, extensively tested polysorbates to ensure drug safety and efficacy.
- High-Purity Formulations:The development of specialized polysorbates with low peroxide and hydrolytic degradation profiles directly addresses critical stability challenges in biologic drug products, creating demand for these premium, performance-oriented materials.
Market Restraints
- Feedstock Price Volatility:The costs of key raw materials, including vegetable-derived fatty acids like oleic acid and petrochemical-based ethylene oxide, are subject to significant price fluctuations, impacting manufacturer margins and pricing stability.
- Threat of Substitution:For specific formulations where polysorbate degradation is a primary concern, alternative stabilizers such as poloxamers and cyclodextrins present a potential substitution risk, particularly in next-generation therapeutic development.
- Concentrated High-Purity Supply:Production of cGMP-compliant, pharmaceutical-grade polysorbates is concentrated among a small number of specialized suppliers, creating potential bottlenecks and supply chain vulnerabilities for biopharmaceutical end-users.
Strategic Opportunities
- Emerging Biopharma Hubs:Expanding biopharmaceutical manufacturing capabilities in countries like South Korea and Brazil present an opportunity for polysorbate suppliers to establish a presence and provide local access to high-purity excipients.
- Novel Drug Delivery Systems:The application of polysorbates in advanced delivery platforms, such as lipid nanoparticles for mRNA therapeutics, opens a new, high-value market segment beyond traditional protein stabilization.
- Excipient Qualification Programs:Initiatives like the WHO Prequalification of Excipients program can create a globally harmonized standard, allowing suppliers with certified products to gain easier access to multiple international markets.
Industry Challenges
- Analytical Complexity:Characterizing and quantifying functionally relevant impurities in polysorbates, such as residual host cell proteins or catalysts, requires sophisticated, expensive, and often custom-developed analytical methods that are difficult to standardize across the industry.
- Pharmacopeial Harmonization Gaps:Discrepancies between major pharmacopeias, such as the USP, Ph. Eur., and JP, in testing methods and acceptance criteria create significant compliance burdens and increase the cost of serving a global market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysorbate Market |
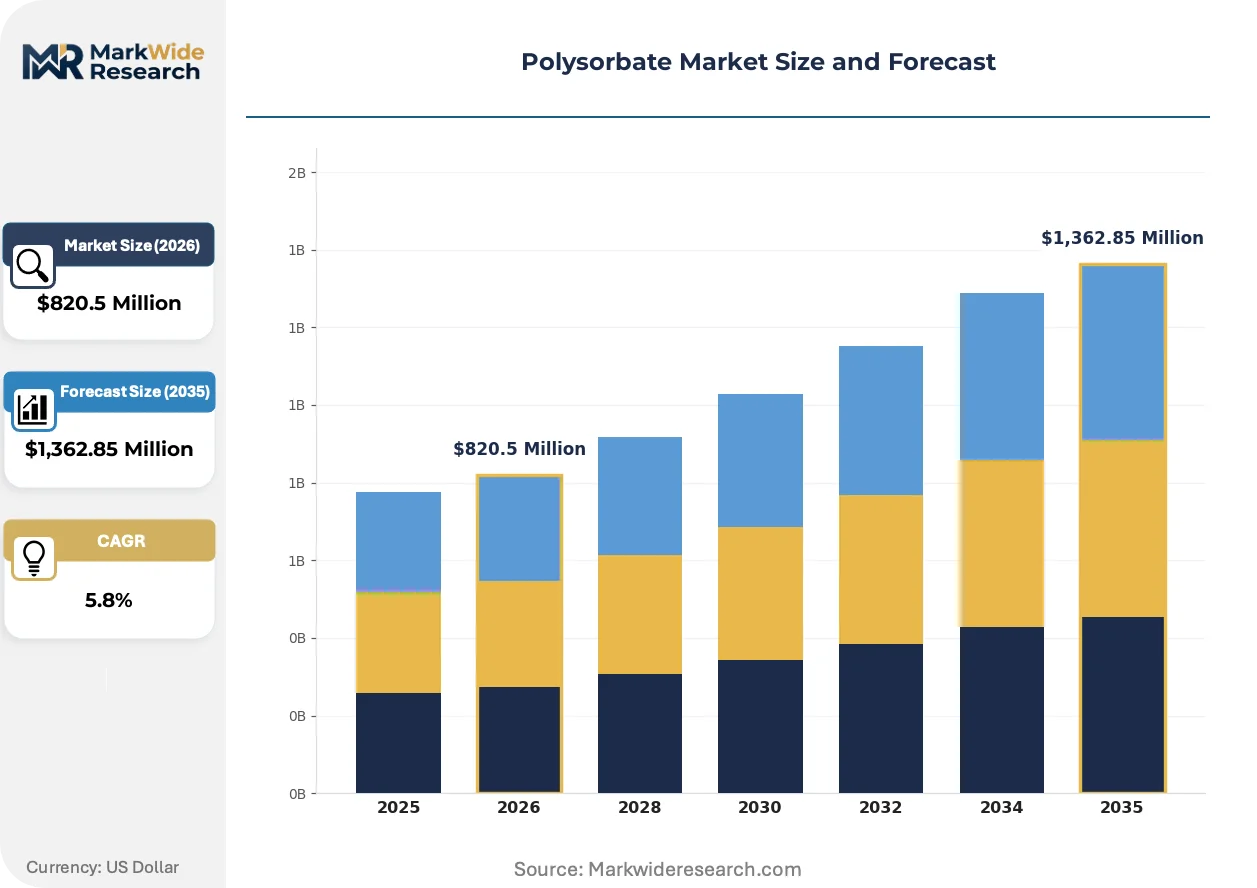
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,362.85 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysorbate 20, Polysorbate 40, Polysorbate 60, Polysorbate 80 Application: Pharmaceuticals, Cosmetics & Personal Care, Food & Beverage, Agrochemicals End User: Drug Manufacturers, Skincare Brands, Food Processors, Crop Protection Firms Packaging Type: Bulk Containers, Drums, Bottles, Intermediate Bulk Containers |
| Companies Covered | Evonik Industries, Solenis, BASF Corporation, Kao Corporation, Avril Group, Croda International plc, DuPont Nutrition & Health, AkzoNobel, Lonza Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysorbate Market Strategic Shifts & Innovations
Intensifying regulatory scrutiny over excipient quality is accelerating the market’s shift from a focus on cost to a focus on performance and purity. This evolution prioritizes materials that can ensure the stability and safety of increasingly complex biologic drugs.
Advanced analytical techniques like multi-attribute methods (MAM) provide a comprehensive profile of polysorbate quality in a single assay. Biopharmaceutical developers are adopting MAM for incoming excipient testing to better control raw material variability. This technology is integrating quality control more deeply into the drug development process, enabling faster identification of potential stability issues linked to excipient impurities.
Regulatory pressure from bodies like the US FDA on data integrity and quality management is compelling suppliers to provide more extensive characterization data. This forces investment in robust process controls and digital quality systems to track batch-to-batch consistency. Suppliers of pharmaceutical-grade Polysorbate 80 and 20 are most affected, as they must now deliver comprehensive data packages to support their customers' regulatory filings.
Buyer behavior for high-purity grades is evolving from transactional purchasing toward strategic supplier partnerships. The traditional model of sourcing from general chemical distributors is being displaced by direct, early-stage collaboration between biologic drug developers and specialized excipient manufacturers. This trend is most prominent in the United States and Europe, where risk mitigation for drug stability is a primary concern.
Polysorbate Market Segmentation
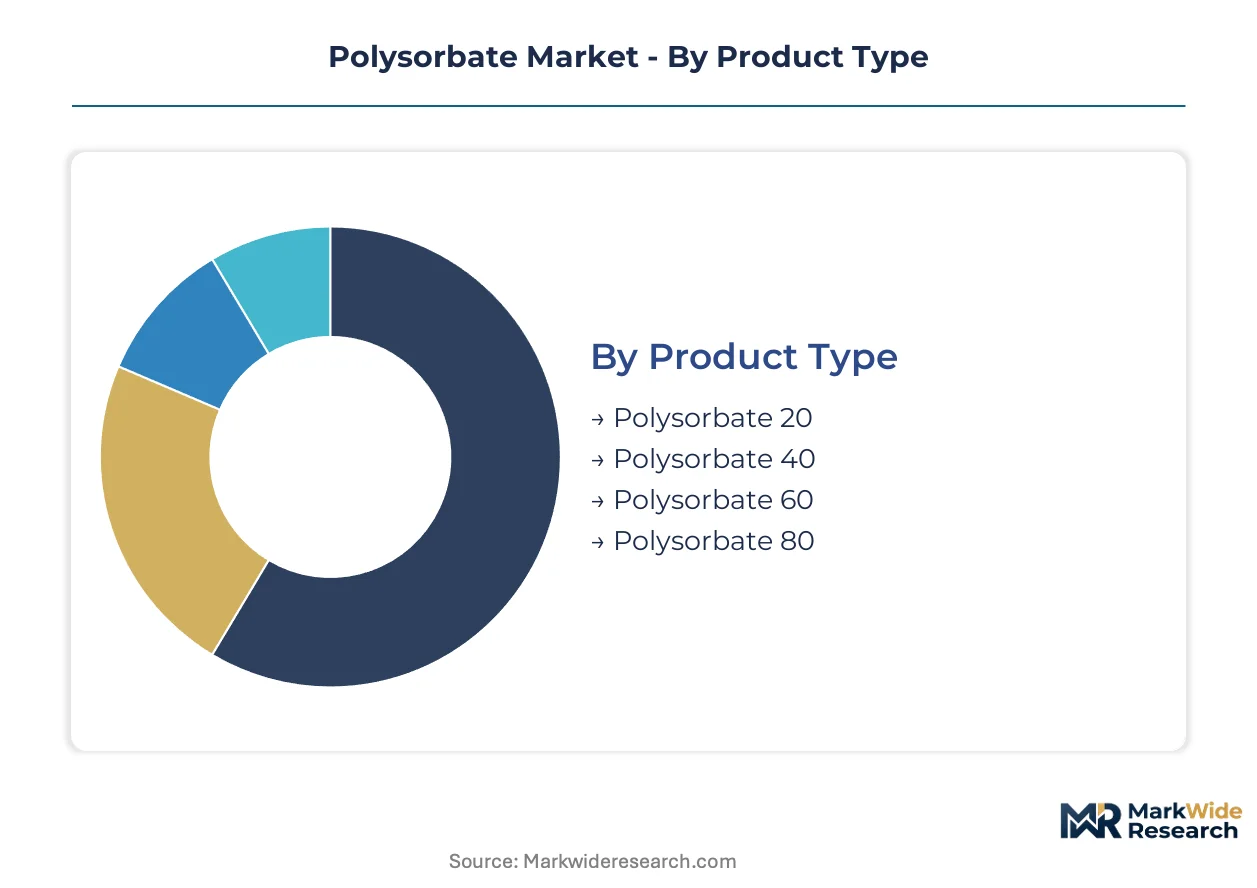
The polysorbate market's segmentation reflects diverse purity requirements and application-specific demands across industries. Understanding these distinct segments allows suppliers to tailor product offerings and align with evolving regulatory standards. This granular view highlights where value creation concentrates and where volume growth occurs.
Product Type:
The upgrade cycle from commodity to high-purity polysorbates is redefining product type preferences in critical applications.
- Polysorbate 80:This nonionic surfactant, primarily based on oleic acid, provides excellent emulsion stabilization for complex formulations. Demand concentrates heavily in biopharmaceutical manufacturing in China and the United States, driven by stringent stability requirements for monoclonal antibodies.
- Polysorbate 20:Derived from lauric acid, Polysorbate 20 functions as a versatile emulsifier and solubilizer across numerous consumer products. Its demand is substantial in the high-volume cosmetics and personal care industries, where cost-effectiveness and broad compatibility are key drivers.
- Polysorbate 40:This type of polysorbate, based on palmitic acid, finds niche applications as an emulsifier in specific food and personal care formulations.
- Polysorbate 60:Utilizing stearic acid, Polysorbate 60 serves as an emulsifier and stabilizer, primarily in the food & beverage and cosmetics sectors.
Volume placements concentrate in Polysorbate 20; the faster expansion belongs to Polysorbate 80.
Application:
Application-specific performance requirements dictate the selection and formulation of polysorbates, influencing market dynamics.
- Pharmaceuticals:Polysorbates in pharmaceuticals serve as critical excipients for stabilizing protein-based drugs, vaccines, and cell therapies. This segment experiences high demand for ultra-pure grades, driven by US FDA and EMA regulatory mandates for parenteral drug safety.
- Cosmetics & Personal Care:This segment utilizes polysorbates as emulsifiers, solubilizers, and dispersing agents in a wide range of products like lotions, shampoos, and fragrances. High-volume production for global skincare brands drives consistent demand for cost-effective, standard grades.
- Food & Beverage:Polysorbates act as emulsifiers in baked goods, ice cream, and salad dressings, preventing ingredient separation and enhancing texture.
- Agrochemicals:In agrochemical formulations, polysorbates improve the dispersion and efficacy of pesticides and herbicides, aiding crop protection.
The pharmaceutical sector commands the highest value per unit; volume expansion is strongest in food and personal care.
End User:
Customer procurement strategies are increasingly differentiating based on technical support and quality assurance, moving beyond basic price points.
- Drug Manufacturers:These users require cGMP-compliant, extensively characterized polysorbates for their complex biologic formulations. Their purchasing decisions prioritize supplier expertise and comprehensive documentation to meet stringent regulatory filing requirements.
- Food Processors:Large-scale food companies utilize polysorbates for emulsification and stabilization in diverse products, from baked goods to dairy. Their procurement emphasizes consistent supply, bulk availability, and adherence to food safety standards like those from EFSA.
- Skincare Brands:These companies incorporate polysorbates into various cosmetic products, seeking reliable suppliers that offer consistent quality and competitive pricing.
- Crop Protection Firms:Agrochemical manufacturers use polysorbates as formulation aids, focusing on suppliers who can provide stable, effective ingredients for their agricultural products.
Drug manufacturers seek strategic partnerships for specialized grades, while food processors prioritize consistent, large-scale supply.
Packaging Type:
The logistical efficiency and integrity of polysorbate delivery are driving packaging type choices for various end-users.
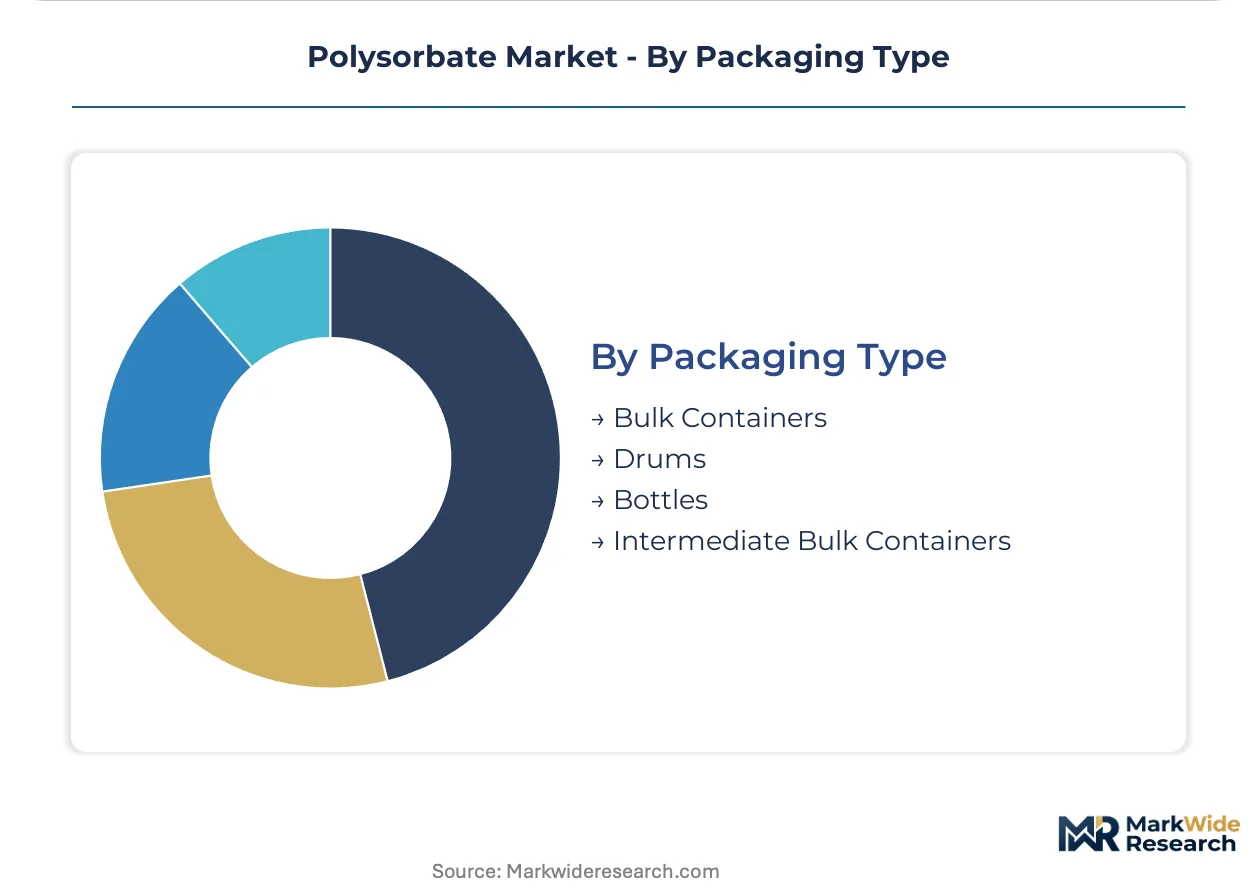
- Bulk Containers:These large-volume containers, such as ISO tanks or large drums, cater to industrial-scale users requiring substantial quantities. They are essential for cost-effective transport and storage in high-volume manufacturing operations, particularly for commodity grades.
- Intermediate Bulk Containers:IBCs offer a balance between bulk and smaller packaging, ideal for specialized or higher-purity polysorbates used in biopharmaceutical production. They provide efficient handling and reduced contamination risk for sensitive excipients.
- Drums:Standard drums provide a common packaging solution for medium-volume polysorbate requirements across various industrial and commercial applications.
- Bottles:Smaller bottles are typically used for laboratory-grade polysorbates, research quantities, or for highly specialized, low-volume applications.
Bulk containers dominate large-volume industrial supply chains, whereas intermediate bulk containers offer flexible solutions for specialized pharmaceutical batches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The expansion of biopharmaceutical manufacturing within special economic zones like those in China's Yangtze River Delta is concentrating polysorbate demand. These regions benefit from government incentives and a dense ecosystem of drug developers. This creates localized centers for high-purity excipient consumption.
China
Biologic drug expansion and local manufacturing capacity drive polysorbate demand across China. The NMPA's accelerated drug approval processes encourage domestic biopharmaceutical production. Major biomanufacturing hubs in Shanghai and Suzhou require consistent, high-purity polysorbate supply for their growing pipelines.
United States
The robust pipeline of monoclonal antibodies and cell therapies fuels demand for pharmaceutical-grade polysorbates in the United States. US FDA guidelines on excipient characterization necessitate extensively tested materials for parenteral drugs. Biopharmaceutical clusters in Boston and San Francisco actively seek strategic partnerships with specialized polysorbate suppliers.
Germany
Germany's strong pharmaceutical research and development sector generates significant demand for high-purity polysorbates. The European Medicines Agency (EMA) enforces stringent quality standards for excipients used in new drug formulations. Production sites in Bavaria and Hesse are key consumers, particularly for advanced biologic therapeutics.
South Korea
South Korea's emerging biopharmaceutical industry, particularly in biosimilars, is a growing market for polysorbates. The Ministry of Food and Drug Safety (MFDS) increasingly aligns its excipient regulations with international pharmacopeias. Incheon and Songdo's bio-clusters attract investment in advanced manufacturing, requiring specialized excipient support.
Brazil
Brazil's expanding pharmaceutical sector and focus on local drug production contribute to polysorbate consumption. ANVISA, the country's health surveillance agency, mandates quality control for imported and domestically produced excipients. Biopharmaceutical initiatives in São Paulo and Rio de Janeiro are developing new therapeutic formulations that incorporate polysorbates.
Polysorbate Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the polysorbate market. This market exhibits a tiered structure, separating providers of commodity-grade materials from those offering high-purity excipients. Strategic archetypes include large-scale chemical producers, specialized biopharma excipient suppliers, and regional distributors. Dominant competitive moves involve portfolio diversification into higher-value grades and strategic partnerships with biopharmaceutical developers.
Specialized biopharma excipient suppliers like Croda International plc exemplify the focus on high-purity materials for sensitive applications, particularly for complex biologic drugs. These players provide comprehensive documentation and support for regulatory filings. Meanwhile, Evonik Industries AG occupies a position characterized by a broad product portfolio and extensive manufacturing footprint across multiple regions, serving diverse end-users with both standard and specialty grades. BASF Corporation, a large-scale chemical producer, anchors the market through its integrated supply chains, primarily catering to the high-volume food and personal care segments with consistent, cost-effective polysorbates.
| Leading Market Players |
|---|
| Evonik Industries |
| Solenis |
| BASF Corporation |
| Kao Corporation |
| Avril Group |
| Croda International plc |
| DuPont Nutrition & Health |
| AkzoNobel |
| Lonza Group Limited |
Cost & Logistics Intelligence
Purity-driven bifurcation of polysorbate grades manifests in distinct pricing models and supply chain configurations. High-purity excipients for biopharmaceuticals command premium pricing, while commodity grades for food and cosmetics compete on cost.
Pricing Analysis
Lead-time-driven pricing favors premium for pre-qualified, high-purity polysorbates and discounts for readily available commodity stock. The dominant pricing model for pharmaceutical grades is contract-based long-term offtake, ensuring supply stability. Price differentiation stems from quality grade, specifically cGMP compliance, and extensive characterization data. Upward pricing pressure for high-purity materials arises from regulatory compliance costs and specialized manufacturing. Food and cosmetics manufacturers exhibit the highest price sensitivity, whereas drug manufacturers prioritize consistent quality over cost.
Supply Chain Analysis
Certification and qualification gating restrict market access for high-purity polysorbates, concentrating production among specialized suppliers. Geographic supply for these critical excipients largely centers in China, the United States, and Germany. The supply chain depends on raw materials like vegetable-derived fatty acids and petrochemical-based ethylene oxide. A structural risk is single-source vulnerability for cGMP-compliant grades, given the limited number of qualified producers. Distribution runs directly from specialized manufacturers to biopharmaceutical developers or through regional chemical distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polysorbate market is undergoing a vertical-integration race, driven by the need for enhanced control over excipient purity and supply chain resilience. Manufacturers are pursuing upstream control over feedstock sourcing to mitigate price volatility.
For Market Incumbents:
Lock in long-term supply agreements with biopharmaceutical clients to counter potential new entrant disruption. Invest in advanced analytical capabilities to provide comprehensive characterization data, addressing stricter regulatory mandates from the FDA and EMA. Expand cGMP manufacturing capacity in strategic biomanufacturing hubs like China and the United States to meet growing demand for high-purity Polysorbate 80. This strategy hedges against feedstock price volatility and ensures consistent product quality.
For New Entrants and Emerging Players:
Advanced analytical techniques, such as multi-attribute methods, create a technology-first wedge for specialized suppliers. Target the emerging biopharma hubs in South Korea and Brazil, focusing on novel drug delivery systems like lipid nanoparticles. Offer excipient qualification programs that align with global standards, providing comprehensive data packages to biopharmaceutical developers. This approach allows smaller players to differentiate on performance and regulatory support rather than scale.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized excipient manufacturers given the sustained growth in biologic drug development. Long-term viability over the next decade hinges on suppliers with robust quality systems and strong regulatory compliance. Target mid-sized, cGMP-certified polysorbate producers with established customer relationships in the pharmaceutical sector. The signal to watch is the increasing adoption of novel drug delivery systems that require highly specialized excipients.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Grades | Meets rising demand from biologic drug manufacturers in key biomanufacturing regions. |
| Investment in Advanced Analytical Characterization | Addresses stringent regulatory requirements from the FDA and EMA for excipient impurity control. |
| Backward Integration into Fatty Acid Sourcing | Mitigates feedstock price volatility and enhances supply chain security for polysorbate production. |
| Strategic Partnerships with Biopharma Developers | Secures early-stage product qualification and ensures long-term contract-based supply for novel therapeutics. |
| Development of Low-Peroxide Polysorbates | Provides enhanced stability for sensitive biologic formulations, reducing degradation risks. |
Research Approach
Independent corroboration across primary interviews, industry reports, and regulatory filings underwrites the qualitative findings. This involved discussions with drug development executives, regulatory affairs leads, procurement managers, and R&D directors across the value chain. Secondary validation drew from FDA filings, EMA submissions, customs and trade data, and public company 10-K reports. A rigorous bottom-up and top-down triangulation approach reconciled discrepancies and ensured data integrity.
Rate-of-change decomposition informed the polysorbate market forecast across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, packaging type, and regional biomanufacturing capacity. Compound annual growth rates were derived from historical trends and projected shifts in demand drivers. Key industry-specific forecast inputs included biologic drug pipeline expansion and evolving regulatory stringency for excipient purity.
Several conditions sit outside the modeled scope, including minor polysorbate grades and highly localized pricing variations. Forecasts reflect assumptions regarding stable geopolitical conditions and continued biopharmaceutical innovation. A model refresh is warranted upon material change in global trade policies or significant shifts in raw material supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Polycide Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Polymer Binders Market