
 Environmental Software Market | 2026-2036
Environmental Software Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Software Market Foresight
North American cloud infrastructure build-out is rewriting competitive dynamics for environmental software delivery. IBM Corporation leverages its Watson analytics backbone to anchor complex emissions modeling for heavy industry clients. SAP SE sustains dominance in Europe through embedded sustainability modules within its ERP core. Schneider Electric competes on the strength of its energy management hardware-software integration across industrial campuses.
Environmental software comprises digital platforms that collect, process, and visualize ecological data to manage compliance, resource consumption, and pollution outputs, typically integrating IoT sensor feeds with predictive algorithms and automated reporting engines. Cloud-Based deployment leads structural growth as enterprises abandon on-premise maintenance burdens for scalable SaaS architectures; Compliance Management applications capture mature, high-retention revenue pools while Carbon Footprint Tracking represents the fastest-expanding segment as scope 3 disclosure obligations deepen.
The EPA enforces mandatory greenhouse gas reporting for large U.S. facilities, while the EU Green Deal and CSRD impose granular sustainability disclosures across European value chains. EMA and ECHA frameworks increasingly require pharmaceutical and chemical producers to document environmental impact through auditable digital trails. Stakeholders must monitor how converging disclosure standards reshape platform interoperability requirements and procurement criteria.
Market Dynamics
The EU Green Deal and CSRD disclosure mandates are compressing enterprise procurement cycles, forcing manufacturing and energy buyers to abandon manual reporting for automated environmental management systems within compressed compliance windows.
Growth Catalysts
- CSRD Mandates:European corporations must submit auditable sustainability disclosures across scope 1-3 emissions, driving replacement of spreadsheet-based tracking with integrated carbon accounting platforms.
- F-Gas Regulation:German industrial clusters face intensified verification requirements for fluorinated gas emissions, accelerating deployment of IoT-enabled leak detection and automated reporting modules.
- Scope 3 Deepening:Supply chain emissions accounting is extending from direct operations to upstream logistics and raw material extraction, expanding addressable software functionality.
Market Restraints
- Integration Friction:Legacy ERP architectures in heavy industry resist seamless API connections with specialized environmental modules, extending implementation timelines.
- Sensor Hardware Dependency:Cloud-based emissions platforms require capital-intensive IoT sensor deployment across distributed industrial sites, constraining mid-market adoption.
- REACH Complexity:Chemical substance registration requirements create overlapping compliance obligations that fragment software procurement decisions across EHS and product stewardship teams.
Strategic Opportunities
- India Manufacturing:BIS energy efficiency standards and state-level pollution control mandates are creating first-mover advantages for SaaS providers targeting textile and pharmaceutical clusters.
- Digital Twin Convergence:Integration of predictive emissions modeling with industrial digital twins enables real-time scenario planning for decarbonization pathways.
- Outcome-Based Pricing:Vendors are piloting contracts tied to verified emissions reductions rather than seat licenses, aligning revenue with customer ESG outcomes.
Industry Challenges
- Data Science Talent Scarcity:Shortage of professionals combining environmental science expertise with machine learning implementation is constraining platform development velocity.
- Multi-Standard Harmonization:Divergent disclosure frameworks across EPA mandatory reporting, EU CSRD, and emerging national standards force redundant system configurations.
- Verification Bottlenecks:Third-party audit capacity for scope 3 claims lags software deployment, creating credibility gaps in reported metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Software Market |
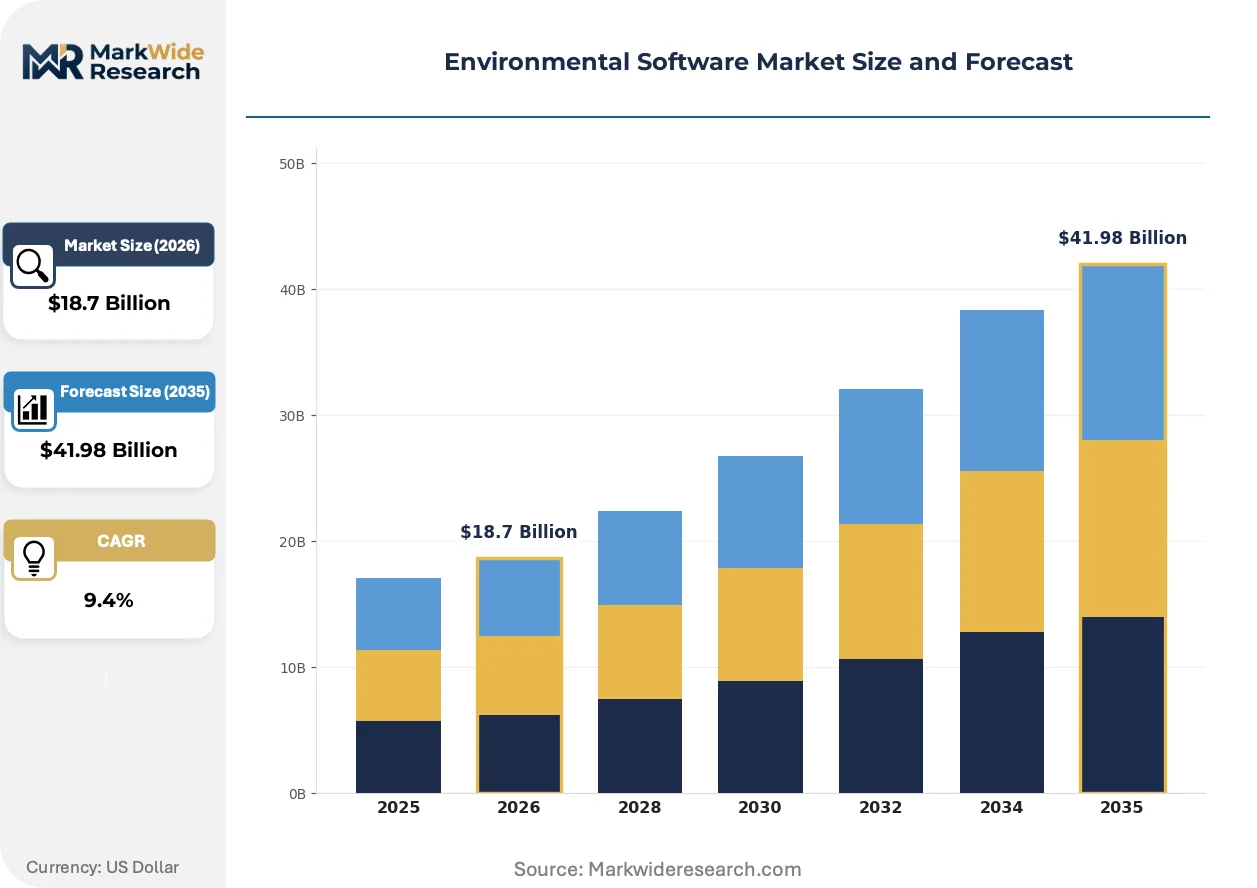
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Compliance Management, Resource Management, Carbon Footprint Tracking, Waste Management Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Government Agencies, Corporations, NGOs, Educational Institutions Functionality: Data Analytics, Reporting Tools, Monitoring Solutions, Optimization Features |
| Companies Covered | IBM Corporation, SAP SE, Microsoft Corporation, Schneider Electric, Wolters Kluwer, Workiva Inc., Salesforce Inc., General Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Software Market Shifts & Advancements
Machine learning inference at the network edge is compressing latency between sensor capture and compliance reporting, while regulatory fragmentation is spawning modular platform architectures designed for rapid reconfiguration.
Edge-native emissions analytics is rendering obsolete batch-processed data pipelines that previously delayed actionable intelligence by hours or days. Heavy industry operators in German chemical parks and Dutch refining corridors are deploying tensor-processing units directly at flare stacks and vent monitors. This architecture eliminates cloud round-trips for threshold alerts, compressing incident response from minutes to seconds and reducing connectivity costs for remote facilities.
REACH authorization procedures are tightening data requirements for chemical safety dossiers, forcing software vendors to embed substance volume tracking directly into manufacturing execution systems. Producers of polymers and specialty chemicals must now correlate production batches with tonnage-based registration thresholds in real time. The pharmaceutical sector faces particular pressure as EMA environmental risk assessments increasingly require site-specific discharge modeling rather than generic emission factors.
Enterprise buyers are consolidating environmental software procurement under chief sustainability officers, displacing fragmented purchasing across facility managers and EHS directors. This centralization favors integrated suites over point solutions, particularly in US manufacturing conglomerates with operations spanning multiple EPA regions. The shift is most pronounced in automotive supply chains, where tier-1 suppliers face simultaneous disclosure demands from OEMs and regulatory bodies.
Environmental Software Market Segmentation
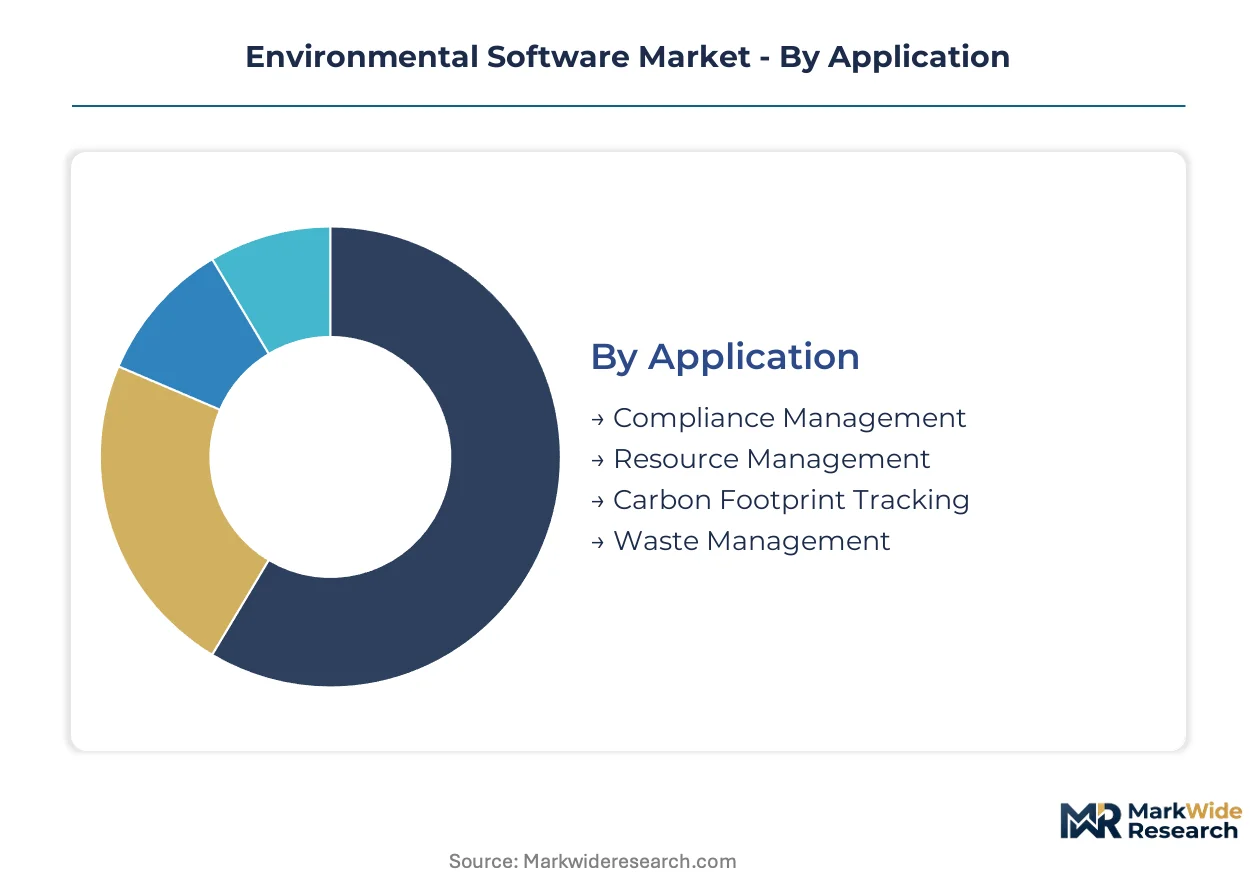
Environmental software segmentation reflects divergent maturity levels across compliance automation and emerging carbon accounting domains. Procurement patterns vary sharply between legacy on-premise installations in heavy industry and cloud-native deployments scaling across distributed supply chains.
Application:
Mature compliance modules dominate current revenue, while emerging carbon tracking capabilities capture accelerated procurement cycles under disclosure mandates.
- Compliance Management:Automated regulatory reporting engines integrate EPA mandatory greenhouse gas submissions, REACH dossier management, and CSRD sustainability disclosures into unified audit trails. German chemical manufacturers and Dutch refining operators represent the densest adoption clusters as ECHA enforcement intensifies verification requirements.
- Carbon Footprint Tracking:Scope 1-3 emissions accounting platforms correlate IoT sensor streams with procurement and logistics data to automate disclosure-ready calculations. Demand concentrates among automotive tier-1 suppliers facing simultaneous OEM requirements and EU CSRD deadlines, with scope 3 upstream accounting driving fastest functionality expansion.
- Resource Management:Water, energy, and raw material consumption optimization modules deploy predictive algorithms against utility billing and production schedule data.
- Waste Management:Hazardous substance tracking and circular economy documentation tools align disposal records with EPA RCRA manifests and state-level pollution control mandates.
Compliance Management handles the majority of throughput; Carbon Footprint Tracking is the fastest mover on share.
Deployment:
Cost tier differentiation separates capital-intensive infrastructure commitments from operational expenditure models favored by mid-market buyers.
- Cloud-Based:Scalable SaaS architectures eliminate on-premise maintenance burdens while enabling real-time sensor integration across distributed industrial sites. Manufacturing conglomerates with multi-facility footprints in the US and Germany are abandoning legacy servers for API-first platforms that compress implementation timelines.
- SaaS:Subscription licensing with automatic feature updates allows procurement without IT capital allocation, accelerating adoption among pharmaceutical and textile clusters in India under BIS energy efficiency mandates.
- On-Premise:Air-gapped installations persist in defense contractors and critical infrastructure operators with cybersecurity restrictions on external data transmission.
- Hybrid:Split architectures keep sensitive production data local while pushing anonymized benchmarking analytics to cloud aggregators.
Cloud-Based deployment captures the steepest expansion trajectory as enterprise IT strategies consolidate around vendor-managed infrastructure.
End User:
Customer type segmentation reveals procurement authority migration from facility-level managers to centralized sustainability functions.
- Corporations:Manufacturing and energy verticals drive platform revenue, with automotive supply chains and chemical producers deploying integrated suites across EPA regions and EU member states.
- Government Agencies:Environmental regulators and municipal utilities deploy monitoring networks for watershed protection and air quality enforcement.
- NGOs:Conservation organizations utilize open-data platforms for biodiversity tracking and deforestation alerts.
- Educational Institutions:University research campuses pilot digital twin integrations for emissions modeling curriculum and grant-funded sustainability initiatives.
Corporations dominate current procurement volume; Government Agencies are expanding most quickly as public sector digital transformation accelerates.
Functionality:
Technology capability layers separate foundational data infrastructure from predictive and optimization modules commanding premium pricing.
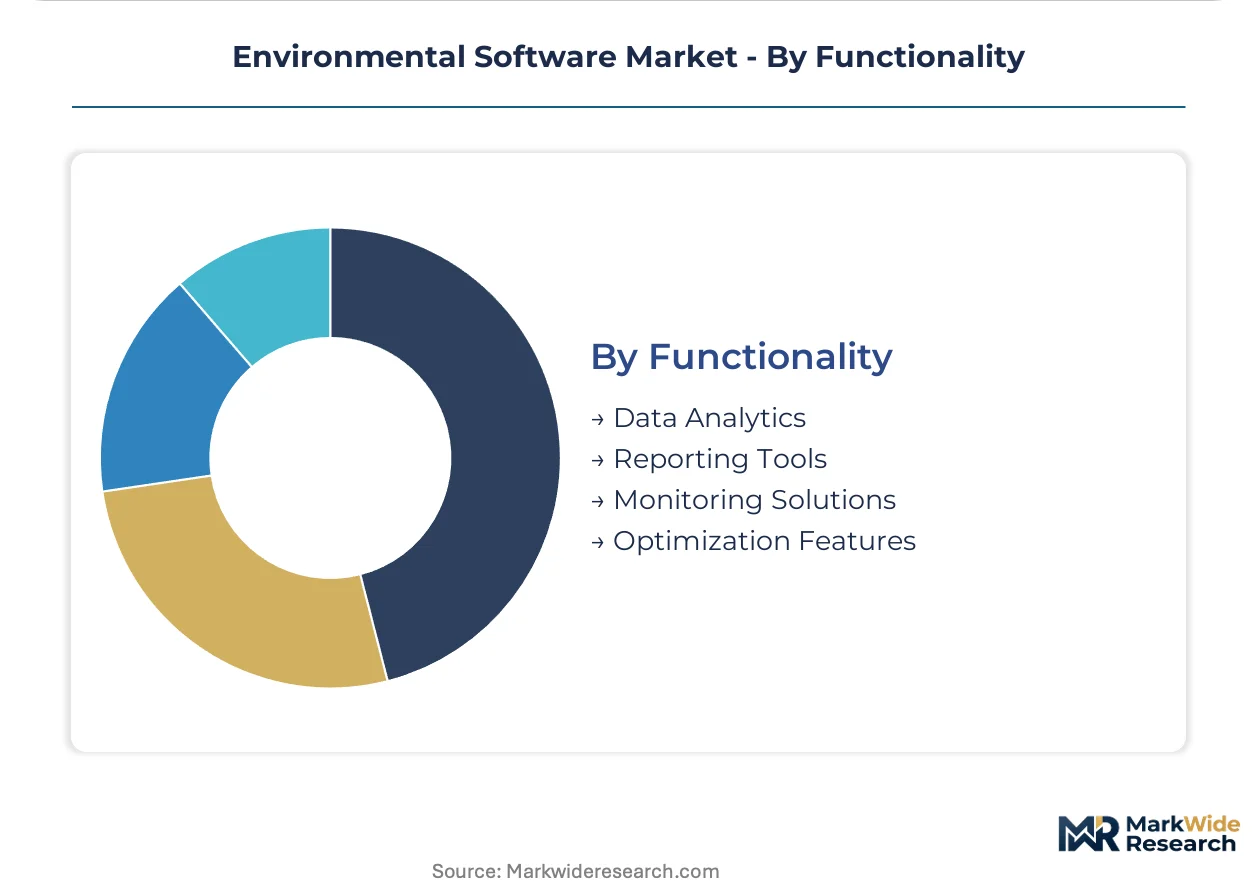
- Data Analytics:Machine learning inference engines process IoT sensor streams, satellite imagery, and enterprise resource planning extracts to identify emissions anomalies and resource inefficiencies. Edge-native tensor processing units deployed at German flare stacks and Dutch vent monitors eliminate cloud latency for threshold alerts.
- Monitoring Solutions:Real-time dashboards and mobile alerting systems visualize environmental parameters against regulatory limits, with IoT-enabled leak detection modules accelerating under F-Gas Regulation verification requirements.
- Reporting Tools:Automated document generation formats disclosures for EPA, ECHA, and CSRD submission templates.
- Optimization Features:Predictive scenario modeling recommends operational adjustments to minimize carbon intensity and compliance costs.
Data Analytics handles the majority of platform development investment; Monitoring Solutions are gaining share fastest as sensor hardware costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of mandatory greenhouse gas reporting anchors the United States as the dominant geography, while EU regulatory density under CSRD and REACH compresses procurement cycles across European industrial clusters.
United States
Manufacturing conglomerates with multi-facility footprints drive cloud migration as EPA mandatory reporting deadlines tighten. The Inflation Reduction Act allocates funding for industrial emissions monitoring infrastructure. Automotive supply chains in Michigan and Ohio deploy integrated suites to satisfy simultaneous OEM requirements and federal disclosure mandates.
Germany
Chemical producers and automotive tier-1 suppliers face the strictest verification requirements under REACH and the F-Gas Regulation. ECHA enforcement intensifies documentation obligations for fluorinated gas emissions. Industrial clusters in North Rhine-Westphalia and Bavaria accelerate IoT-enabled leak detection deployment across flare stacks and vent monitors.
China
Dual carbon goals and provincial emissions trading schemes pressure heavy industry operators to replace manual tracking with automated platforms. MEE regulations tighten monitoring requirements for steel and cement producers. Manufacturing execution systems in the Yangtze River Delta integrate substance volume tracking for real-time registration threshold compliance.
India
BIS energy efficiency standards and state-level pollution control mandates create first-mover opportunities for SaaS providers. The PLI scheme for manufacturing incentivizes digital infrastructure investment. Textile and pharmaceutical clusters in Gujarat and Maharashtra abandon spreadsheet-based tracking for subscription-licensed carbon accounting platforms.
United Kingdom
Post-Brexit alignment with EU disclosure standards maintains regulatory pressure on multinational headquarters operations. The Environment Agency enforces emissions trading scheme compliance for power generation and aviation. Financial services firms in London deploy sustainability disclosure tools to meet converging TCFD and emerging ISSB requirements.
Environmental Software Market Competitive Landscape
Capability concentration sits with specialized environmental analytics vendors; scale advantage sits with ERP incumbents embedding sustainability modules. The market structures around three tiers: diversified technology conglomerates with Watson-class analytics engines, enterprise software incumbents leveraging installed base relationships, and vertical specialists integrating hardware-software stacks for energy-intensive facilities. Dominant competitive moves include API-first platform architecture investments and outcome-based contract pilots tying vendor revenue to verified customer emissions reductions.
Within the diversified technology tier, IBM Corporation and Microsoft Corporation exemplify scale-driven positioning through cloud infrastructure and cognitive analytics capabilities. SAP SE occupies a distinct archetype as the ERP-embedded sustainability leader, while Schneider Electric represents vertical integration between energy management hardware and emissions software. Salesforce Inc. and Workiva Inc. sit within the disclosure automation specialist category, with Wolters Kluwer anchoring regulatory content integration. Siemens and General Electric exemplify industrial conglomerates leveraging operational technology footprints to cross-sell environmental monitoring solutions.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Schneider Electric |
| Wolters Kluwer |
| Workiva Inc. |
| Salesforce Inc. |
| General Electric |
| Siemens |
| Others |
Supply & Pricing Matrix
Sensor hardware manufacturing concentrates in Taiwan, South Korea, and China, concentrating margin pools with semiconductor foundries and IoT module integrators rather than software vendors downstream. Cloud infrastructure providers extract recurring infrastructure fees that compress SaaS gross margins even as subscription revenues scale across enterprise accounts.
Pricing Analysis
Annual subscription spreads between North American and Indian deployments reflect infrastructure cost differentials and localization requirements. Pricing stratifies across enterprise-grade compliance suites, mid-market SaaS tiers, and entry-level monitoring tools differentiated by API depth and sensor integration density. Cost compression in the mid-market tier is intensifying because Indian textile and pharmaceutical clusters demand subscription licensing without IT capital allocation. Government agencies exhibit lowest price sensitivity due to grant-funded procurement mandates, while mid-market manufacturing shows highest sensitivity to per-seat licensing escalators.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and chemical producers cascade through systems integrators, squeezing working capital for IoT deployment specialists. Hardware components draw from Taiwan for tensor processing units, China for sensor assemblies, and the Netherlands for emissions monitoring equipment. Single-source vulnerability sits with Taiwanese semiconductor foundries supplying edge-native analytics chips. Distribution runs through regional systems integrators with EPA and ECHA certification credentials who bundle software with sensor installation and compliance advisory services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, ECHA, and emerging national standards fragments procurement authority, creating specialist niches for modular platform architectures that incumbent ERP suites cannot address comprehensively.
For Market Incumbents: Harden API-first platform architectures against specialized carbon accounting entrants by embedding real-time sensor integration deeper into manufacturing execution systems. Consolidate position in German chemical parks through F-Gas Regulation certification investments that lock out competitors lacking ECHA verification workflows. Prioritize outcome-based contract pilots with automotive OEMs to align revenue with verified scope 3 emissions reductions. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical clusters under BIS energy efficiency mandates where incumbent ERP penetration remains shallow. Target textile manufacturers in Gujarat and Maharashtra with SaaS-native carbon accounting that bypasses capital-intensive on-premise deployment cycles. Lead with subscription licensing and automatic feature updates to exploit IT budget constraints at mid-market manufacturers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists holding ECHA and EPA certification workflows but lacking cloud-native architecture. Long-term viability hinges on platform consolidation around API-first delivery models that compress implementation timelines for manufacturing buyers. Monitor CSRD enforcement intensity across German automotive supply chains as the inflection signal for accelerated procurement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures compress implementation timelines for multi-facility manufacturing conglomerates. |
| Acquisition of Specialist Firm | ECHA-certified compliance modules fill regulatory workflow gaps in incumbent ERP portfolios. |
| Strategic Partnership | Sensor hardware alliances with Taiwanese foundries secure edge-native analytics chip supply. |
| Geographic Expansion | Indian pharmaceutical and textile clusters offer first-mover advantages under BIS mandates. |
| Product Launch | Outcome-based pricing pilots align vendor revenue with verified customer emissions reductions. |
Research Methodology
A spread of perspectives from chief sustainability officers, EHS directors, IT procurement officers, and systems integration specialists converged on the working assumptions underlying segment sizing. Primary fieldwork across German chemical parks, US automotive supply chains, and Indian pharmaceutical clusters was cross-checked against EPA mandatory reporting filings, ECHA registration databases, SEC 10-K sustainability disclosures, and BIS energy efficiency notifications. Bottom-up facility-level deployment estimates were reconciled with top-down vendor revenue triangulation.
Demand-supply balance modeling tracked procurement cycle compression against platform development velocity across the analysis window. Segmentation dimensions included deployment architecture, organization size, vertical industry, integration complexity with legacy ERP, and regional regulatory density. CAGRs were derived from slope analysis of disclosed vendor bookings and facility-level adoption curves. Forecast inputs incorporated CSRD disclosure deadline phasing and F-Gas Regulation enforcement intensity trajectories.
Stress conditions across sensor hardware cost inflation, cloud infrastructure pricing volatility, and regulatory harmonization failure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about procurement authority migration and disclosure mandate timelines. Macroeconomic contraction, regulatory delay, or breakthrough edge-computing cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Portable Filtration System Market
Environment & Sustainability
Singapore Waste Management Market
Environment & Sustainability
Smart Carbon Market
Environment & Sustainability
Metal Recycling Baler Market
Environment & Sustainability
Paper Recycling Market
Environment & Sustainability
Soil Remediation Market
Environment & Sustainability
Global High End Greenhouse Market
Environment & Sustainability
Desiccant Air Breather Market
Environment & Sustainability
US Medical Waste Management Market
Environment & Sustainability
Water Treatment Ozone Generator Market
Environment & Sustainability
Air Quality Control Systems Market
Environment & Sustainability
Wood Recycling Market
Environment & Sustainability
Europe Municipal Solid Waste Management Market
Environment & Sustainability
North America E-Waste Management Market
Environment & Sustainability
Mobile Wastewater Treatment Plant Market
Environment & Sustainability
Smart Water Softeners Market