
 Foodservice Coffee Market | 2026-2036
Foodservice Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Foodservice Coffee Market Intelligence
On-premise brewing equipment leasing is reshaping how operators manage capital deployment and recurring revenue streams. Starbucks Corporation leverages its captive roasting network to secure origin-level supply contracts across Latin America. Nestlé S.A. anchors its foodservice presence through automated dispensing systems deployed in institutional channels. JDE Peet's specializes in private-label roasting for European hotel chains seeking differentiated breakfast programs.
Foodservice coffee comprises commercially roasted beans, concentrates, and soluble formats formulated for out-of-home preparation at standardized extraction parameters of 195–205°F and 18–22% extraction yield. The category serves quick-service restaurants, hotels, and institutional feeders requiring volume consistency and flavor stability across multiple locations. Ground coffee occupies the largest volume share due to its compatibility with conventional batch brewers prevalent in cafeteria and catering operations. Coffee pods represent the fastest-expanding format as quick-service restaurants adopt single-serve systems to reduce waste and labor during off-peak hours. Liquid coffee concentrate commands premium positioning in fine dining and transportation hub applications where space constraints limit whole-bean infrastructure.
FDA food safety regulations and USDA organic certification requirements govern product labeling and processing standards for foodservice coffee distributed across the United States. State-level extended producer responsibility frameworks in California and Washington are adding compliance layers for single-serve packaging waste. Operators must monitor how origin-specific climate volatility and evolving extraction technology standards will reshape equipment procurement and supplier qualification criteria.
Market Dynamics
On-premise brewing equipment leasing is compressing capital cycles for quick-service operators while tightening supplier lock-in through proprietary capsule ecosystems and embedded service contracts.
Growth Catalysts
- Specialty coffee programs:Hotel chains and corporate campuses are expanding procurement volumes for differentiated breakfast and amenity offerings, driving demand for traceable arabica origins.
- FDA labeling modernization:Updated nutritional disclosure requirements for prepared beverages are accelerating format standardization across multi-location operators.
- Vietnam's robusta belt:Concentrated supply availability from this origin is enabling cost-competitive espresso blend formulations for institutional feeders.
Market Restraints
- Arabica input volatility:Climate-induced yield fluctuations in Brazil's Minas Gerais region are compressing margin predictability for roasters dependent on single-origin sourcing.
- California EPR frameworks:Extended producer responsibility mandates for single-serve packaging are adding compliance layers and per-unit cost burdens for pod-format suppliers.
- Batch brewer technical ceiling:Conventional equipment's 195–205°F extraction parameter rigidity limits flavor profile experimentation compared to precision-temperature alternatives.
Strategic Opportunities
- Underpenetrated transportation hubs:Airport and rail terminal concessions represent whitespace for liquid concentrate deployment where space constraints prohibit whole-bean infrastructure.
- EU Green Deal alignment:Carbon footprint disclosure requirements are creating first-mover advantage for roasters with verified supply chain transparency and renewable energy roasting operations.
- Automated dispensing convergence:Integration of IoT-enabled inventory tracking with touchless payment systems is opening institutional channel penetration for unattended coffee service.
Industry Challenges
- Q-grader talent scarcity:Certified cupping professionals capable of maintaining extraction yield consistency across distributed locations command premium compensation and extended recruitment timelines.
- USDA organic certification timelines:The 36-month transition period for conventional acreage conversion is constraining supply elasticity for operators targeting certified-sourced menu claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foodservice Coffee Market |
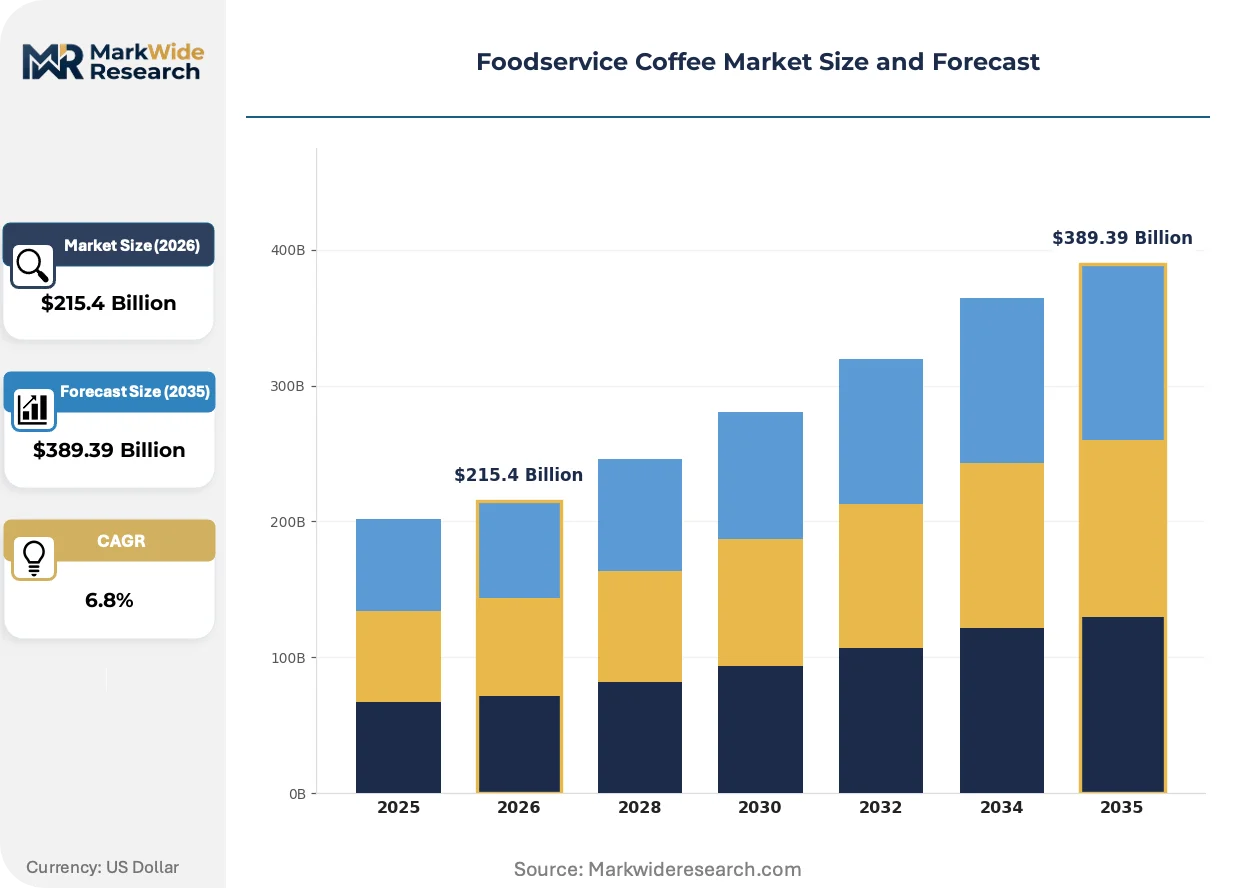
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $389.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Coffee, Instant Coffee, Coffee Pods, Whole Bean Coffee, Liquid Coffee Concentrate Service Type: Cafeteria, Quick Service Restaurant, Fine Dining, Catering Services, Institutional Foodservice End User: Corporate Offices, Universities, Hospitals, Hotels, Transportation Hubs Distribution Channel: Wholesale Distributors, Direct Sales, Online Platforms, Specialty Retailers, Vending Solutions |
| Companies Covered | Kraft Heinz Company, Luigi Lavazza S.p.A., Starbucks Corporation, Dunkin' Brands Group, Costa Limited, Nestlé S.A., Keurig Dr Pepper Inc., JDE Peet's, The J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foodservice Coffee Market Strategic Shifts & Innovations
Extraction technology standardization and regulatory disclosure mandates are converging to reshape equipment procurement criteria and supplier qualification protocols across out-of-home coffee preparation.
Precision temperature-profiling batch brewers with programmable extraction curves are rendering obsolete fixed-parameter equipment that cannot accommodate single-origin flavor differentiation demands. Regional coffee chains with 50–200 unit footprints are adopting these systems at replacement-cycle velocity. The technology is compressing equipment vendor margins while elevating roaster influence over brewing specifications.
California's extended producer responsibility framework for packaging waste is mandating producer-funded collection infrastructure for single-serve formats. Roasters and equipment lessors must now integrate reverse logistics costs into pricing models or absorb margin erosion. Quick-service operators in the state are responding by accelerating ground coffee format trials to preempt compliance exposure.
Direct origin contracting is displacing spot-market purchasing for volume foodservice accounts seeking supply security and traceability credentials. Hotel chains with 500-plus property portfolios are negotiating multi-year offtake agreements directly with Brazilian cooperatives. This pattern is most visible in North American and Western European markets where ESG disclosure requirements amplify provenance marketing value.
Foodservice Coffee Market Segmentation
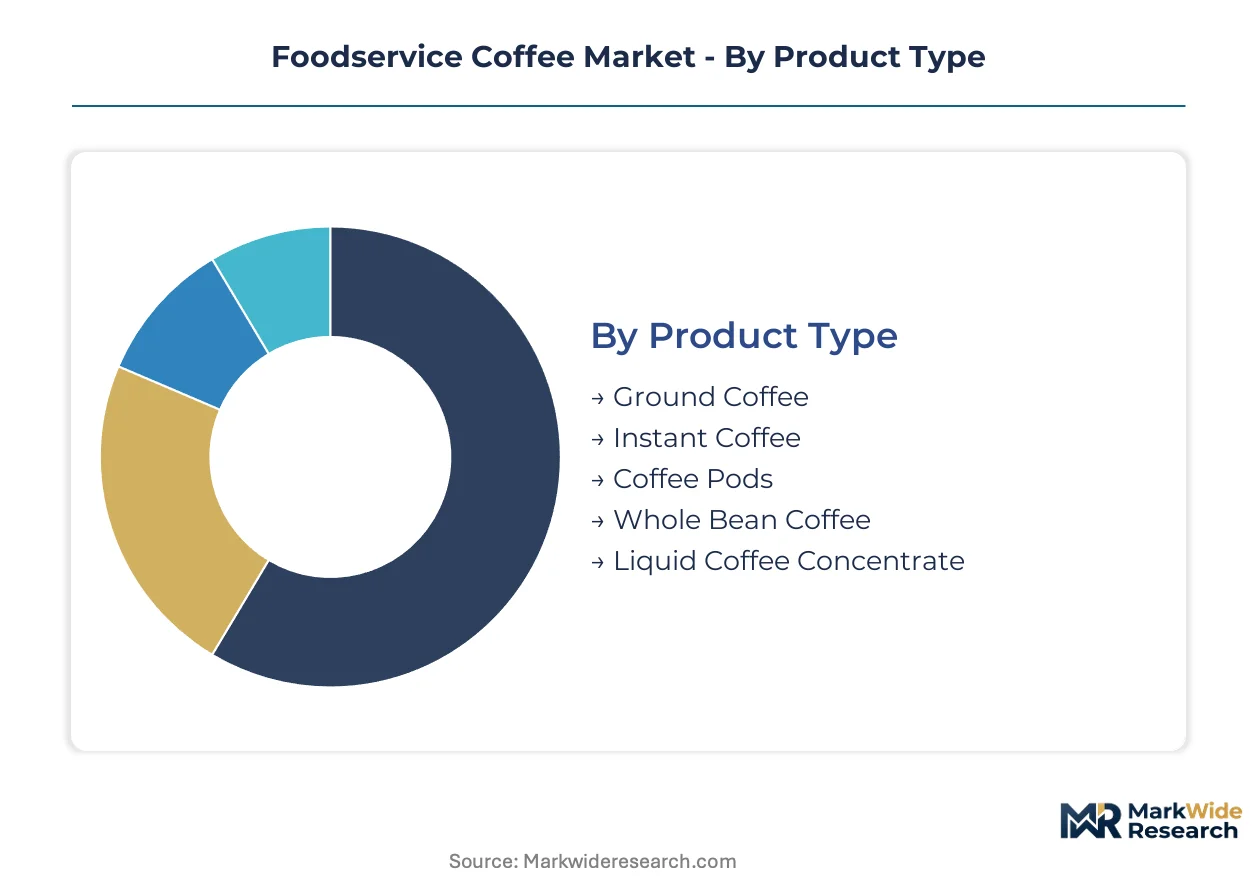
Equipment replacement cycles and format conversion timelines vary dramatically across foodservice coffee segments. Procurement managers must align capital planning with the operational velocity of each category.
Product Type:
Ground coffee and instant formats turn inventory fastest through high-velocity institutional channels, while pod systems and liquid concentrates lock operators into longer equipment depreciation schedules.
- Ground Coffee:Pre-ground arabica and robusta blends calibrated for 18-22% extraction yield in conventional batch brewers. Demand concentrates in US cafeteria operations and Brazilian hotel chains where labor minimization overrides precision brewing preferences.
- Instant Coffee:Spray-dried and freeze-dried soluble granules reconstituted at point-of-service. Transportation hubs across Southeast Asia deploy this format where equipment footprint and speed of service dominate procurement criteria.
- Coffee Pods:Single-serve capsules with proprietary brewing parameters. European quick-service restaurants are expanding pod infrastructure despite California EPR compliance costs.
- Whole Bean Coffee:Unroasted or freshly roasted beans requiring on-site grinding equipment. Specialty programs in German corporate campuses favor this format for provenance marketing.
- Liquid Coffee Concentrate:Shelf-stable extracts diluted at dispensing. Fine dining establishments in Japan leverage concentrate systems where kitchen space constraints prohibit batch brewing infrastructure.
Ground coffee dominates installed base. Coffee pods are where expansion concentrates.
Service Type:
Margin structures diverge sharply between self-service cafeteria models and full-service fine dining, with quick-service restaurants occupying the middle ground on both capital intensity and per-cup economics.
- Cafeteria:High-volume self-service operations with standardized portion controls. US hospital systems and Indian IT campuses drive procurement through cost-per-cup metrics and equipment durability requirements.
- Quick Service Restaurant:Counter-service formats with drive-through and mobile order integration. Chains across Mexico and Indonesia are retrofitting locations with automated dispensing systems to reduce labor during peak hours.
- Fine Dining:Table-service environments with customized preparation protocols. French and Italian establishments maintain demand for origin-specific whole bean programs with sommelier-style service rituals.
- Catering Services:Off-premise event preparation requiring transport-stable formats. UK and Australian catering operators favor liquid concentrate for setup speed at remote venues.
- Institutional Foodservice:Military, prison, and government feeding operations with strict nutritional and budget compliance. Contracts in Saudi Arabia and South Korea specify soluble coffee for shelf stability and cost control.
Institutional foodservice locks in the longest contract cycles. Quick service restaurants are climbing the fastest on equipment upgrade velocity.
End User:
Corporate offices and universities refresh equipment every 3-5 years, while hospitals and hotels operate on 7-10 year depreciation schedules that slow format migration.
- Corporate Offices:Workplace amenity programs competing for talent retention. Tech campuses in California and Texas are installing precision-temperature brewers to differentiate from standard batch systems.
- Universities:Student dining operations with high throughput and seasonal demand fluctuation. US and Canadian institutions are trialing pod systems in satellite locations to reduce waste during low-occupancy periods.
- Hospitals:24-hour feeding operations with dietary compliance requirements. NHS trusts in the UK and VA facilities in the US specify caffeine content labeling and infection-control dispensing protocols.
- Hotels:In-room and lobby service with brand consistency mandates. Marriott and Hilton properties across the Middle East are standardizing on single-origin ground coffee for breakfast programs.
- Transportation Hubs:Airport and rail concessions with extreme space constraints. Changi Airport and Frankfurt Airport operators are deploying concentrate systems to eliminate bean storage and grinder maintenance.
Hotels dominate contract value per outlet. Transportation hubs are gaining share fastest on new concession awards.
Distribution Channel:
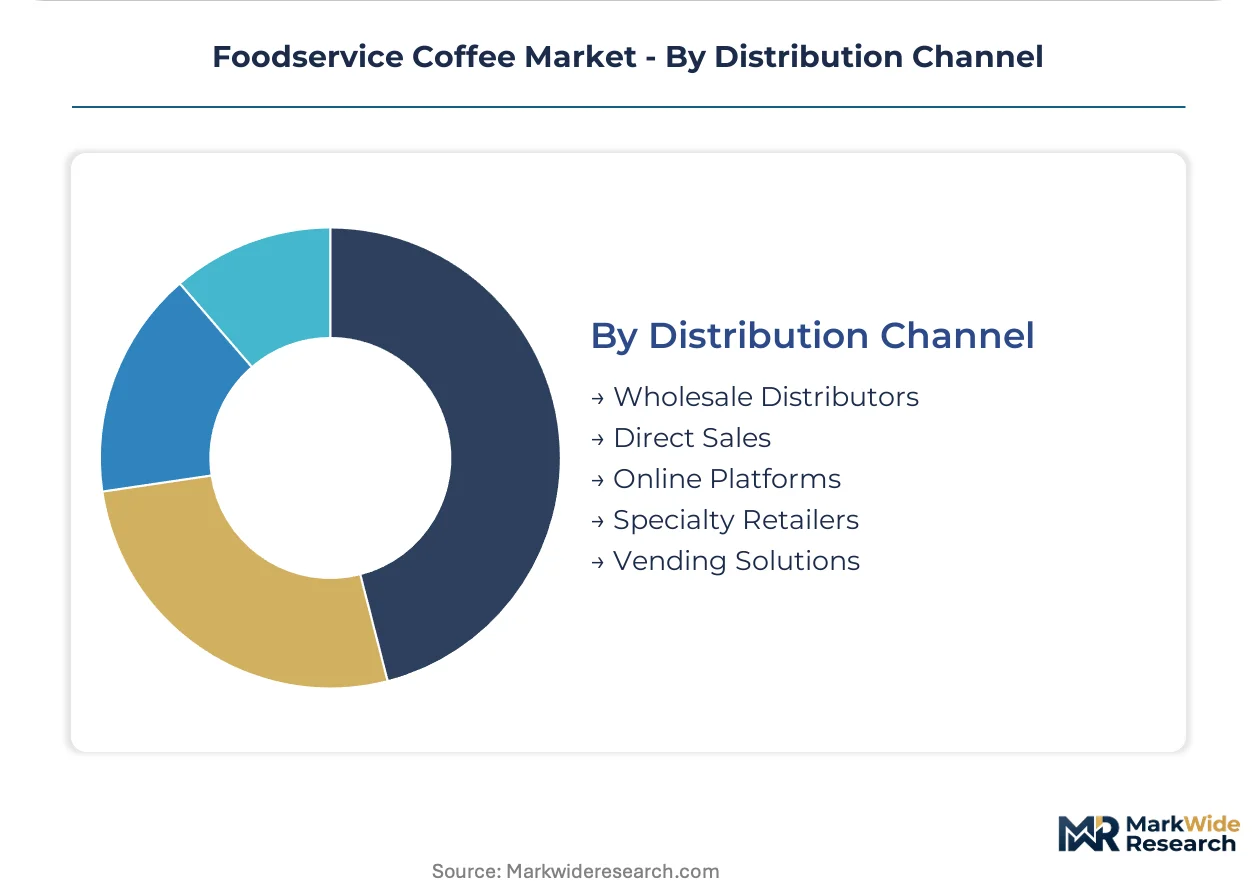
Direct sales relationships command premium positioning through technical service bundling, while wholesale distributors compete on breadth of format availability and geographic coverage.
- Wholesale Distributors:Multi-brand aggregators serving fragmented operator bases. Sysco and US Foods in North America leverage route density to consolidate ground coffee deliveries with broadline food orders.
- Direct Sales:Manufacturer-to-operator relationships with equipment leasing attachments. JDE Peet's and Nestlé deploy direct teams for European hotel chain accounts requiring customized private-label programs.
- Online Platforms:Digital procurement portals with subscription replenishment models. Small US restaurant groups are adopting Amazon Business and specialty coffee marketplaces for specialty-grade whole bean sourcing.
- Specialty Retailers:Regional roasters with foodservice divisions and origin storytelling. Intelligentsia and Stumptown serve independent cafes in Chicago and Portland with traceable supply chain credentials.
- Vending Solutions:Unattended equipment operators with revenue-share arrangements. Japanese vending machine deployers and European office service providers are integrating cashless payment and IoT inventory monitoring.
Wholesale distributors dominate transaction volume. Direct sales are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across foodservice coffee markets. Institutional buyers in India and Southeast Asia prioritize cost-per-cup metrics above origin credentials. Premium hotel chains in Western Europe and the Middle East absorb substantial arabica premiums for traceability claims.
United States
Quick-service restaurants drive pod-system deployment despite California's extended producer responsibility mandates adding per-unit compliance costs. FDA labeling modernization for prepared beverages accelerates format standardization across multi-location operators. Seattle and Portland specialty roasters anchor the Pacific Northwest cluster where precision-temperature equipment trials concentrate.
Germany
Corporate campus programs and hotel breakfast chains sustain demand for private-label arabica roasting with verified supply chain credentials. EU Green Deal carbon footprint disclosure requirements favor roasters with renewable energy operations. Hamburg and Bremen host major green coffee import terminals serving Central European distribution networks.
Brazil
Domestic hotel chains and institutional feeders consume substantial volumes of locally grown arabica and conilon robusta. Climate volatility in Minas Gerais compresses margin predictability for roasters dependent on single-origin sourcing. São Paulo and Minas Gerais form the core roasting cluster where direct cooperative contracting displaces spot-market purchasing.
Japan
Fine dining establishments and transportation hubs favor liquid concentrate systems where kitchen space constraints prohibit batch brewing infrastructure. METI energy efficiency standards influence equipment procurement criteria for automated dispensing systems. Tokyo and Osaka concentrate demand for premium concentrate formats in high-rent commercial districts.
United Arab Emirates
Luxury hotel properties and airport concessions standardize on single-origin ground coffee programs for brand differentiation in competitive hospitality markets. MOHAP food safety regulations govern import and labeling standards for out-of-home coffee preparation. Dubai International Airport and Abu Dhabi terminals deploy concentrate systems to eliminate bean storage infrastructure in space-constrained concessions.
Foodservice Coffee Market Key Industry Players
Capability concentration sits with specialty roasters possessing origin-level sourcing relationships and Q-grader talent; scale advantage sits with multinational beverage conglomerates with automated dispensing networks and institutional channel lock-in. The market structures around three tiers: captive roasting networks securing long-term supply contracts, equipment-integrated solution providers bundling leasing with proprietary formats, and private-label specialists serving European hotel chains. Consolidation pressure runs through direct origin contracting displacing intermediaries, and equipment lessors acquiring regional roasting assets to deepen service bundling.
Within the multinational beverage tier, Nestlé S.A. and JDE Peet's occupy positions defined by automated dispensing infrastructure and institutional channel penetration. Starbucks Corporation exemplifies the captive roasting network archetype with direct Latin American supply relationships. Among North American operators, Keurig Dr Pepper Inc. sits within the equipment-integrated pod system segment where proprietary capsule ecosystems create operator switching costs.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Luigi Lavazza S.p.A. |
| Starbucks Corporation |
| Dunkin' Brands Group |
| Costa Limited |
| Nestlé S.A. |
| Keurig Dr Pepper Inc. |
| JDE Peet's |
| The J.M. Smucker Company |
| Others |
Cost & Logistics Intelligence
Undercapacity in Vietnam's robusta-processing infrastructure is driving contract premiums for forward delivery while compressing spot-market liquidity for foodservice roasters seeking cost-competitive blend formulations. Roasters with captive milling operations in the Central Highlands capture margin advantages that spot-dependent competitors cannot match, reshaping procurement behavior across institutional channels.
Pricing Analysis
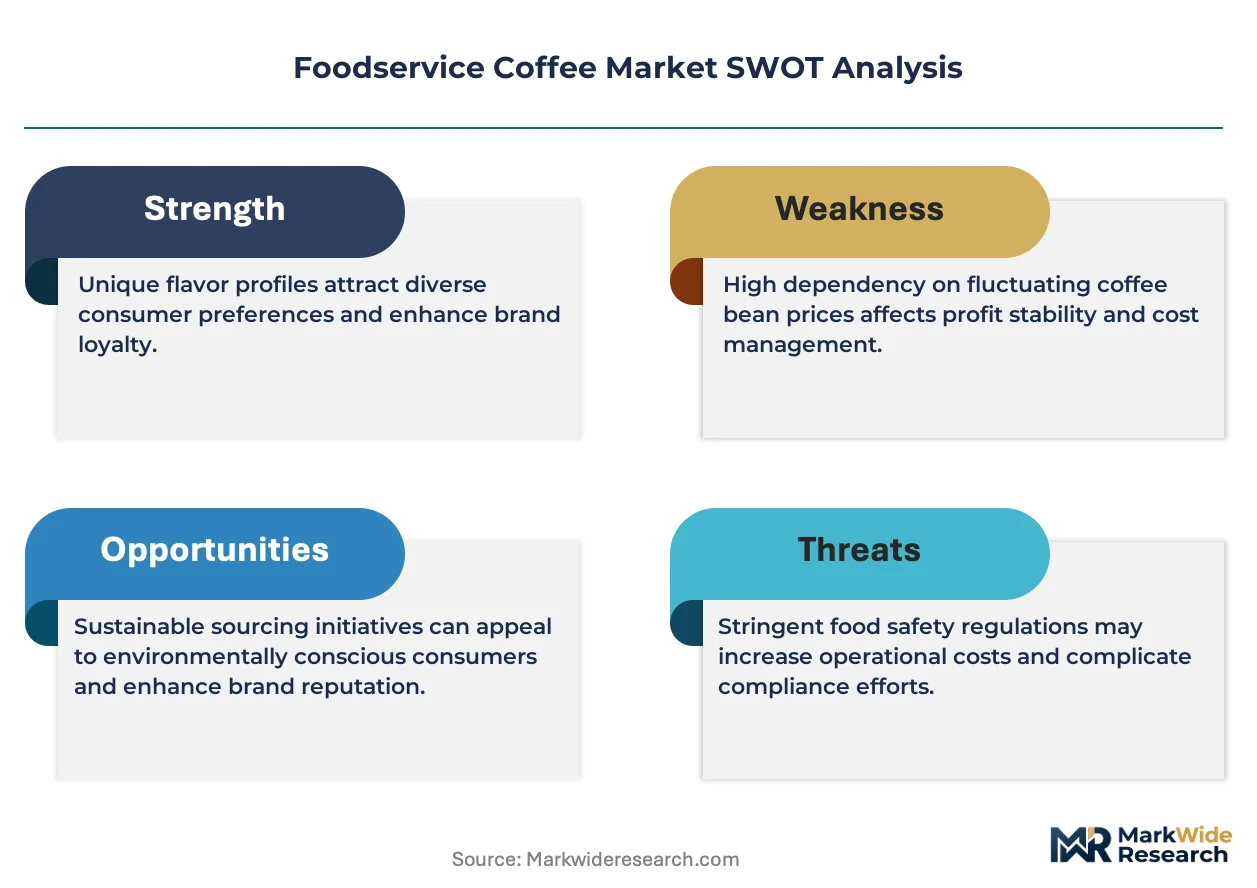
Equipment service contracts and consumable replenishment subscriptions generate lifetime value multiples exceeding initial hardware margins for automated dispensing lessors. Three-tier pricing structure across premium arabica, standard commercial blends, and economy robusta formulations reflects origin certification tiers and extraction precision capabilities. Cost compression in economy-tier ground coffee intensifies as Brazilian spot arabica volatility forces roasters to absorb margin erosion rather than pass through to price-sensitive institutional feeders. Quick-service restaurant chains exhibit highest price sensitivity due to cost-per-cup procurement metrics, while luxury hotel properties absorb premiums for traceable single-origin credentials.
Supply Chain Analysis
Green coffee sourcing draws from Brazil's Minas Gerais and Cerrado regions, Vietnam's Central Highlands, and Colombia's Huila department for differentiated arabica requirements. Raw material dependencies center on washed arabica parchment, natural process dried cherry, and wet-hulled robusta with moisture specifications calibrated for destination roasting profiles. Single-source vulnerability concentrates in Brazilian arabica where climate-induced yield compression threatens multi-year contract fulfillment. Distribution runs through Hamburg and Santos green coffee terminals into regional roasting clusters, with direct cooperative contracting displacing intermediary spot purchasing for volume foodservice accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across precision-temperature equipment segments as mid-size regional chains seek differentiation from standardized batch brewer deployments. Specialty program proliferation in corporate campuses and boutique hotels creates addressable niches beyond multinational conglomerate coverage.
For Market Incumbents: Entrench equipment-lease relationships through embedded IoT inventory tracking that elevates switching costs for multi-location operators facing California EPR compliance burdens. Acquire Q-grader talent pools in producing regions to secure cupping consistency across distributed roasting footprints. Prioritize backward integration into Vietnamese robusta milling to defend margin position against spot-market volatility. For New Entrants and Emerging Players: Mid-market European hotel chains seeking private-label differentiation represent the most penetrable entry point given JDE Peet's and Nestlé concentration on automated dispensing infrastructure. Transportation hub concessions in Asia-Pacific markets with space-constrained operations offer whitespace for liquid concentrate specialization. Target direct origin storytelling capabilities as the primary go-to-market angle against commoditized broadline distributor offerings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-integrated solution providers with proprietary capsule ecosystems and multi-year service attachments. Long-term viability favors roasters with verified supply chain transparency credentials aligned to EU Green Deal disclosure requirements. Acquisition target archetype: regional specialty roasters with Q-grader bench strength and direct cooperative contracts in Brazil or Colombia. Monitor California EPR framework expansion to additional states as inflection indicator for format migration acceleration away from single-serve pods.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Origin Contracting | Multi-year offtake agreements with Brazilian cooperatives secure supply transparency for ESG disclosure requirements. |
| Precision Equipment Deployment | Programmable temperature-profiling batch brewers enable flavor differentiation for specialty coffee programs. |
| Reverse Logistics Integration | Producer-funded collection infrastructure addresses California EPR mandates for single-serve packaging waste. |
| Q-Grader Talent Acquisition | Certified cupping professionals maintain extraction yield consistency across distributed roasting locations. |
| Concentrate Format Expansion | Shelf-stable extracts penetrate transportation hubs and fine dining where space constraints prohibit whole-bean infrastructure. |
Research Approach
A standing panel of foodservice procurement directors, roasting operations managers, hotel chain beverage program leads, and equipment leasing executives provided ongoing calibration across primary research phases. Secondary validation incorporated customs trade data for green coffee movements, FDA labeling guidance documents, EU Green Deal regulatory filings, and SEC disclosures from publicly traded beverage conglomerates. Bottom-up volume modeling triangulated against top-down market sizing from trade association aggregates.
Scenario-bracketing around climate volatility in Brazil's arabica belt and EPR framework expansion across US states bounded the projection envelope. Segmentation dimensions spanned product format, service type, end-user vertical, and distribution channel with regional regulatory cluster overlays. CAGRs were derived from equipment replacement cycle velocity and format conversion timelines specific to each segment. Forecast inputs included cooperative contract volume commitments and precision-temperature equipment adoption curves in North American and Western European markets.
Stress conditions across Brazilian arabica yield compression, Vietnamese robusta processing capacity constraints, and California EPR enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding equipment depreciation schedules and origin-specific supply elasticity. Cross-checking against USDA organic certification transition timelines and EU carbon footprint disclosure implementation progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Away from Home Market
Food Service
Galley Equipment Market
Food Service
Peer-To-Peer Dining Market
Food Service
Quick-Service Restaurants Market
Food Service
Snack Subscription Box Service Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Global Meal Kit Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Beverage Napkins Market
Food Service
United Arab Emirates Full Service Restaurants Market
Food Service
Commercial Grills Market
Food Service
Global Online Food Delivery Services Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
Vietnam Food Service Market
Food Service
United States Foodservice Market
Food Service
A La Carte Market