
 Food Delivery Services Market | 2026-2036
Food Delivery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Food Delivery Services Market Intelligence
Subscription-based loyalty programs, offering benefits like zero delivery fees, are repositioning the value proposition from per-order transactions to recurring revenue streams. DoorDash leverages its dominant North American presence and DashPass subscription model to create significant customer stickiness. Delivery Hero competes on a broad multinational scale, operating a diverse portfolio of local brands across Europe, Asia, and the Middle East, while Meituan dominates the Chinese market with an integrated service ecosystem.
Food delivery services are technology platforms connecting consumers with restaurants and merchants via a digital interface, typically a mobile application. These services manage the complex order-to-delivery logistics chain, utilizing either a dedicated gig-economy courier network or restaurant-employed staff. The restaurant-to-customer segment remains the largest by volume, but grocery delivery represents the fastest-growing category. Growth in the grocery segment is driven by consumer demand for convenience and partnerships between platforms and major supermarket chains.
Regulatory frameworks, including the European Union's Platform Work Directive and anti-monopoly rules from China's SAMR, are shaping labor classifications and competitive practices. In the United States, the FTC scrutinizes pricing transparency and service fees charged to both consumers and restaurants. Future platform profitability depends on navigating these evolving labor regulations while managing courier incentives and service fees.
Market Dynamics
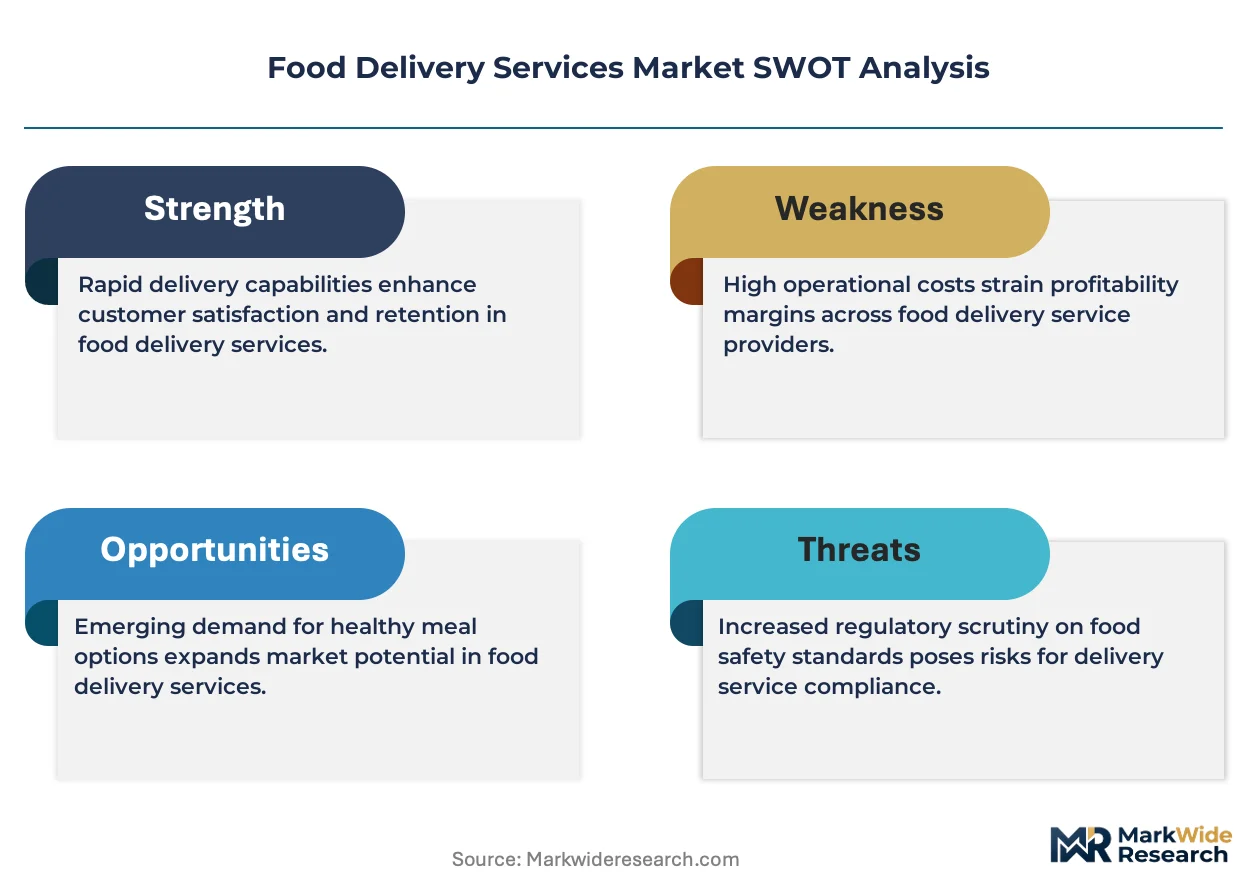
The central tension shaping the food delivery market is the clash between platform profitability models, which rely on gig-economy labor, and intensifying regulatory pressure from bodies like the European Union to formalize worker classifications and benefits, fundamentally altering operational cost structures.
Growth Catalysts
- Corporate Demand Expansion:A rising number of corporations are integrating catered office lunches and employee meal benefits into their human resources packages, creating a new, high-volume B2B revenue stream for delivery platforms.
- Smartphone Penetration:The continued proliferation of affordable smartphones and improving mobile data infrastructure in dense urban centers across India and Southeast Asia expands the addressable consumer base.
- Urbanization and Lifestyle Shifts:Growing urban populations with dual-income households and demand for convenience are a primary driver, particularly for the quick commerce and restaurant-to-customer segments.
Market Restraints
- Regulatory Labor Reclassification:The European Union's Platform Work Directive and similar legislative efforts in other jurisdictions threaten to reclassify gig-economy couriers as employees, significantly increasing labor costs and administrative burdens.
- Restaurant Margin Pressure:High commission fees charged by platforms create friction with restaurant partners, leading many to promote their own direct-to-consumer ordering channels as a substitute.
- Input Cost Volatility:Fluctuations in fuel prices directly impact the earnings of couriers and can necessitate unpopular service fee increases for consumers, affecting order volume.
Strategic Opportunities
- Grocery Delivery Expansion:The grocery segment represents the fastest-growing category, with significant opportunity in forming exclusive partnerships with national and regional supermarket chains to manage their e-commerce fulfillment.
- AI and Automation Integration:The convergence of AI-driven route optimization software with nascent drone and autonomous vehicle technology presents a long-term opportunity to radically reduce last-mile delivery costs.
- Non-Food Adjacencies:Platforms can leverage their existing logistics networks and user bases to expand into adjacent verticals, including pharmacy, retail, and package delivery, diversifying revenue streams.
Industry Challenges
- Courier Network Churn:High turnover rates among gig-economy couriers require constant recruitment and incentive spending to maintain network density and service levels, pressuring operational margins.
- POS System Fragmentation:Integrating a platform's order management system with the thousands of disparate, often legacy, point-of-sale (POS) systems used by independent restaurants creates significant technical and operational hurdles.
- Navigating Municipal Regulations:Compliance with a patchwork of city-specific rules in markets like the United States regarding delivery fee caps, courier pay standards, and zoning restrictions complicates scalable expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Delivery Services Market |
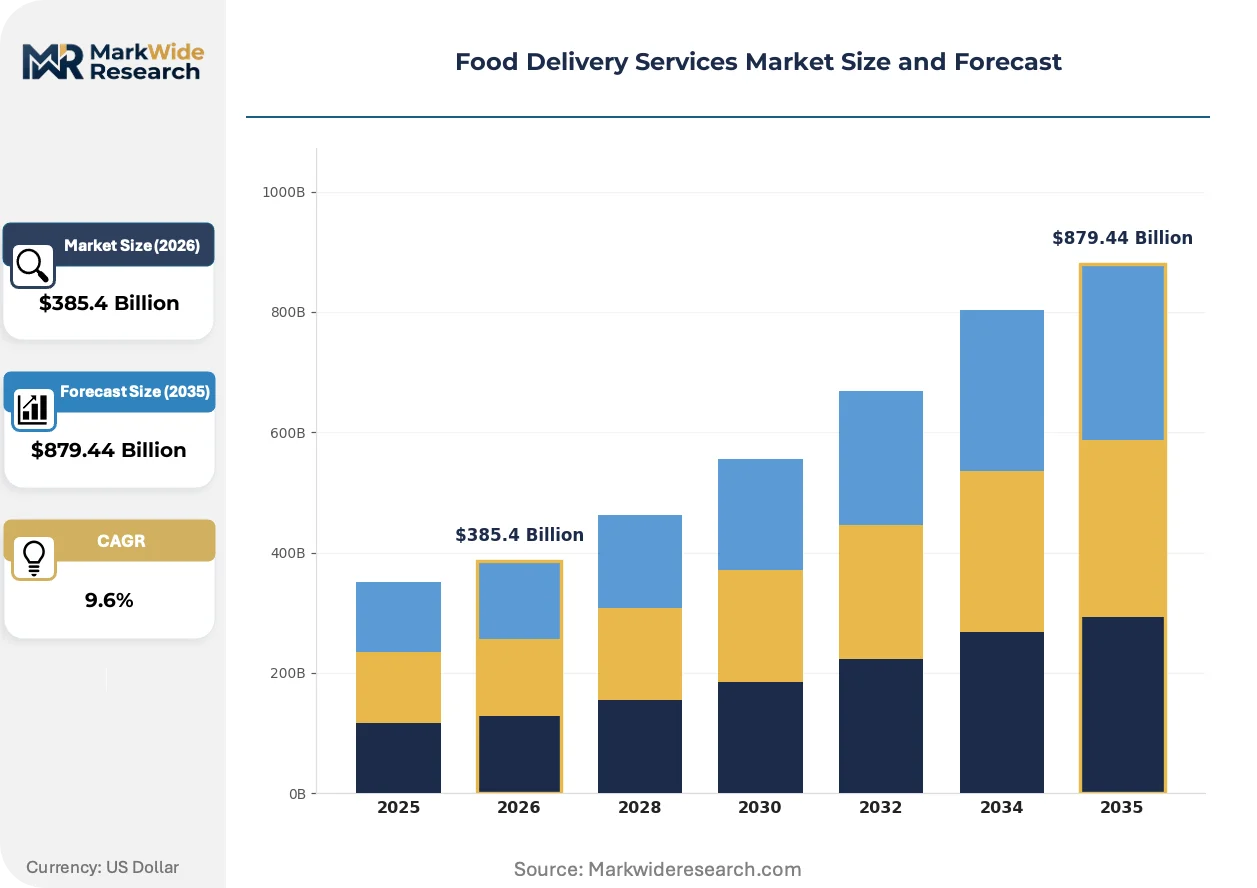
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $879.44 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Restaurant-to-Customer, Grocery Delivery, Meal Kit Delivery, Alcohol Delivery, Specialty Food Delivery Customer Type: Individual Consumers, Corporate Clients, Educational Institutions, Healthcare Facilities, Event Organizers Distribution Channel: Mobile Applications, Websites, Call Centers, Third-Party Aggregators, Social Media Platforms Payment Method: Credit & Debit Cards, Digital Wallets, Cash on Delivery, Bank Transfers, Buy Now Pay Later |
| Companies Covered | Delivery Hero, Just Eat Takeaway, DoorDash, Zomato, Deliveroo, Uber Eats, Meituan, Foodpanda, Grubhub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Delivery Services Market Strategic Shifts & Innovations
A focus on operational efficiency is driving innovation, with platforms investing heavily in automation and data analytics to optimize logistics. These technological advancements occur within a landscape of increasing regulatory oversight on pricing and labor practices, forcing strategic adaptation.
AI-Powered Logistics
AI-powered logistics engines are a core technology, using machine learning to forecast demand, optimize courier dispatching, and calculate dynamic delivery routes in real time. Delivery platforms are rapidly adopting these systems to reduce fuel consumption and cut down on delivery times. This application of predictive analytics is electrifying the last-mile delivery chain, enabling a shift from a reactive to a proactive operational model that anticipates order flow.
Pricing Transparency Mandates
The US Federal Trade Commission (FTC) is intensifying its scrutiny of non-transparent service fees charged to consumers and restaurants on digital platforms. This regulatory pressure is forcing platforms to overhaul their checkout processes and fee disclosures to avoid enforcement actions. The restaurant-to-customer segment is most directly impacted, with many services simplifying their pricing structures to clearly delineate food costs from delivery and service charges.
Subscription Model Proliferation
A significant behavioral shift is underway from per-order transactions to subscription-based loyalty programs that offer members benefits like zero delivery fees. This model, exemplified by programs like DashPass, unbundles the delivery cost from individual orders, fostering a recurring revenue relationship and higher customer retention. The trend is most visible in mature, highly competitive markets such as North America, where retaining high-frequency users is paramount.
Food Delivery Services Market Segmentation
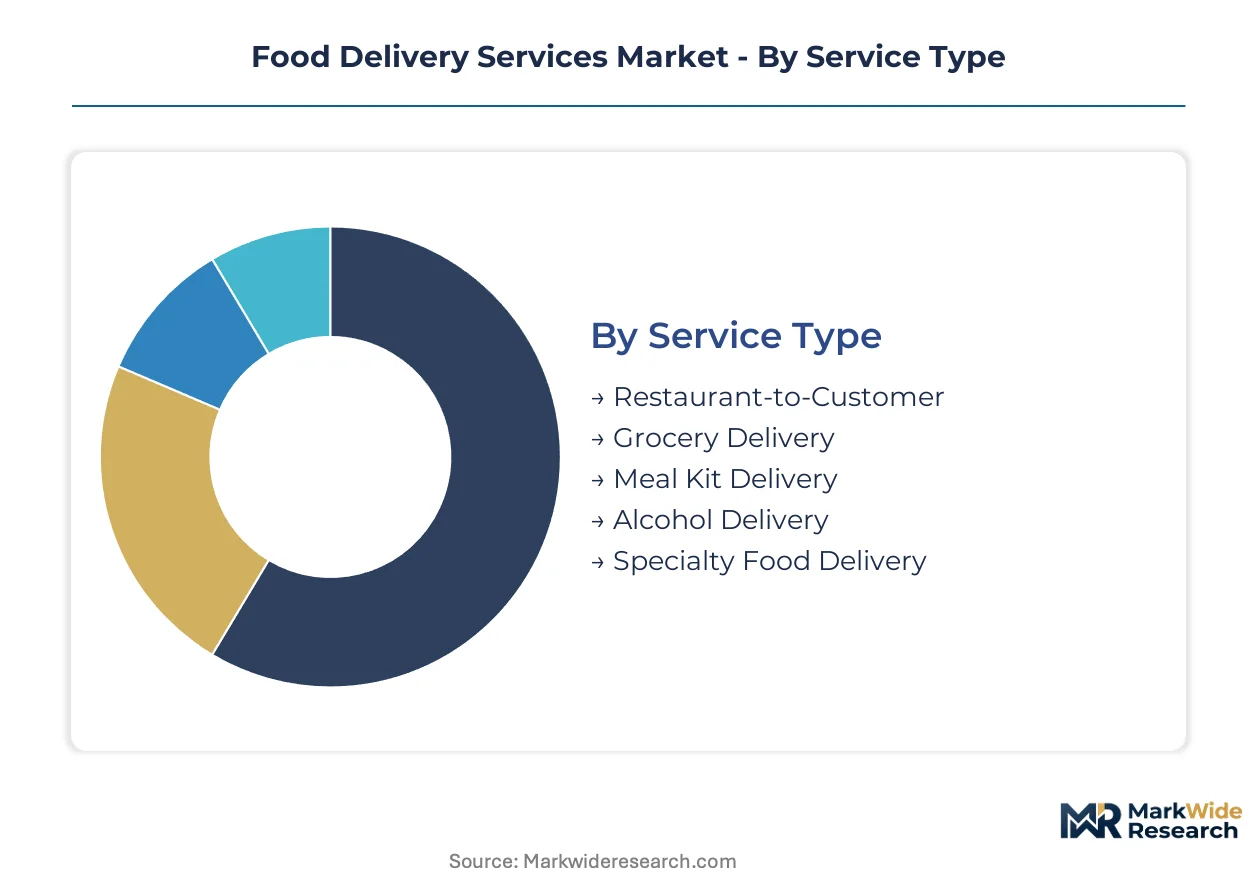
Understanding the distinct segments within the food delivery services market is crucial for strategic positioning and resource allocation. Each category delineates different aspects of service provision, customer interaction, and operational mechanics, influencing platform development and expansion priorities.
Service Type:
Food delivery platforms continuously upgrade their service offerings, replacing traditional models with more specialized options to capture diverse consumer needs.
- Restaurant-to-Customer:This segment involves the direct delivery of prepared meals from restaurants to consumers, forming the largest volume within the market. Demand concentrates in dense urban centers across India and Europe, driven by convenience and a wide selection of culinary options.
- Grocery Delivery:This service provides on-demand or scheduled delivery of groceries from supermarkets or dark stores directly to consumers' homes. Growth in this segment is particularly strong in the United States, fueled by partnerships with major supermarket chains and consumer demand for household staples.
- Meal Kit Delivery:Consumers receive pre-portioned ingredients and recipes for home cooking, offering a balance between convenience and culinary engagement.
- Alcohol Delivery:This segment focuses on the regulated delivery of alcoholic beverages from licensed retailers to eligible consumers, navigating complex local laws.
- Specialty Food Delivery:Platforms cater to niche markets, delivering gourmet items, organic produce, or specific dietary products from specialized vendors.
Restaurant-to-Customer sits at the top of the volume ranking, with Grocery Delivery climbing the fastest.
Customer Type:
The market's demand sources are fragmenting, moving beyond individual consumers to encompass institutional and corporate clients seeking tailored solutions.
- Individual Consumers:This category encompasses single users or households ordering food for personal consumption, representing the foundational customer base for most platforms. Demand is widespread globally, particularly in urban areas with high smartphone penetration.
- Corporate Clients:Businesses utilize food delivery services for catered office lunches, employee meal benefits, and client meetings, creating a significant B2B revenue stream. This segment is expanding rapidly in North America as companies enhance employee welfare packages.
- Educational Institutions:Universities and schools partner with platforms to provide meal options for students and staff, often integrating with campus meal plans.
- Healthcare Facilities:Hospitals and clinics leverage delivery services for staff meals or patient food needs, ensuring timely and convenient access to provisions.
- Event Organizers:Planners for conferences, parties, and social gatherings use platforms for bulk food orders, streamlining catering logistics.
Individual Consumers drive the foundational demand, while Corporate Clients represent a significant growth vector for platforms.
Distribution Channel:
Access points for food delivery services are evolving, with technology adoption dictating the primary channels consumers use to place orders.
- Mobile Applications:Dedicated smartphone applications serve as the primary interface for consumers to browse menus, place orders, and track deliveries. These applications dominate the market due to their convenience and real-time functionality.
- Websites:Desktop and mobile websites offer an alternative digital interface for ordering, often preferred by users who are not on mobile devices or for larger, more complex orders. Websites maintain a strong presence in established markets like the United States.
- Call Centers:Traditional telephone-based ordering systems cater to customers preferring direct human interaction or those without internet access.
- Third-Party Aggregators:These platforms list multiple restaurants and manage the entire delivery process, offering a consolidated ordering experience.
- Social Media Platforms:Integration with social media allows users to order directly through messaging apps or dedicated storefronts within social networks.
Mobile Applications offer the broadest reach, while Third-Party Aggregators expand platform partnerships.
Payment Method:
Financial innovation is reshaping transaction convenience, offering consumers a wider array of secure and flexible payment options for food delivery.
- Credit & Debit Cards:These traditional electronic payment methods remain widely accepted, providing secure transactions for a broad customer base. Their prevalence is high across developed markets like the European Union.
- Digital Wallets:Mobile payment solutions like Apple Pay, Google Pay, and platform-specific wallets offer contactless and expedited checkout processes. Digital wallets are gaining considerable traction in Asia, driven by smartphone penetration and integrated ecosystems.
- Cash on Delivery:Customers pay couriers directly in cash upon receipt of their order, a prevalent option in emerging markets like India.
- Bank Transfers:Direct electronic transfers from bank accounts offer a secure payment alternative, particularly for larger orders or corporate clients.
- Buy Now Pay Later:This emerging payment option allows consumers to defer or split payments for their orders, increasing purchasing flexibility.
Credit & Debit Cards remain widely accepted, but Digital Wallets are gaining preference due to their ease of use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global food delivery market demonstrates diverse regional dynamics, with robust corporate client expansion in the United States contrasting with the rapid consumer adoption driven by smartphone penetration in India. European markets navigate complex regulatory shifts, while China's integrated ecosystems dominate its domestic landscape.
United States
Corporate clients and the expanding grocery delivery segment drive demand across the United States. The FTC scrutinizes pricing transparency and service fees charged to both consumers and restaurants. Major platforms compete intensely within the New York City metropolitan area for market share.
India
India's food delivery market thrives on a young demographic and increasing smartphone penetration within dense urban centers. The country's competition commission actively monitors platform practices and market dominance. High order volumes concentrate in Bengaluru and Mumbai, reflecting strong consumer adoption.
China
China's market is characterized by an integrated service ecosystem and high demand for urban convenience. The SAMR enforces strict anti-monopoly rules on dominant digital platforms. Shanghai and Beijing metropolitan areas lead in the adoption of diverse delivery services.
Germany
Urbanization and a strong demand for convenience propel the restaurant-to-customer segment in Germany. The European Union's Platform Work Directive directly influences labor models and operational costs. Berlin and Munich urban centers demonstrate significant demand for quick commerce services.
United Kingdom
Lifestyle shifts and high smartphone penetration fuel demand across the United Kingdom, particularly in the grocery segment. Local councils implement specific rules regarding delivery operations and courier standards. London remains a key hub, driving innovation in diverse food and grocery delivery.
Food Delivery Services Market Key Industry Players
Branded platforms and white-label service providers split market share differently across the food delivery segments. The market exhibits a tiered structure, with a few dominant global players alongside numerous regional and local specialists. Strategic archetypes include super-app integrators, pure-play food delivery services, and logistics-as-a-service providers. Dominant competitive moves involve geographic expansion and portfolio diversification into adjacent verticals.
On the premium-tier vector, DoorDash exemplifies a subscription-driven model, anchoring its dominant position within the North American market through customer stickiness. Meituan, a Chinese technology company, represents the super-app archetype, integrating diverse services beyond food delivery to create a comprehensive ecosystem for its users. Berlin-based Delivery Hero operates across a broad multinational scale, sitting within the global segment through its diverse portfolio of local brands across Europe, Asia, and the Middle East, showcasing a decentralized operational strategy.
| Leading Market Players |
|---|
| Delivery Hero |
| Just Eat Takeaway |
| DoorDash |
| Zomato |
| Deliveroo |
| Uber Eats |
| Meituan |
| Foodpanda |
| Grubhub |
| Others |
Cost & Logistics Intelligence
Corporate Clients increasingly demand catered office lunches, influencing platforms to offer subscription-based models with tailored service fees. This shifts revenue from per-order transactions to recurring streams.
Pricing Analysis
Capacity additions in dense urban centers are reshaping price floors for delivery services, particularly for restaurant-to-customer deliveries. Platforms primarily utilize subscription-based models for loyalty alongside per-order transactional fees. Geographic delivery cost and platform brand premium differentiate service pricing. Pricing pressure stems from regulatory labor reclassification in Europe, while individual consumers exhibit high price sensitivity to service fees.
Supply Chain Analysis
Reverse logistics for food delivery primarily involves managing order cancellations and customer complaints, requiring rapid courier redeployments. The operational supply chain concentrates its gig-economy courier networks within dense urban centers across India and the United States. Key dependencies include smartphone penetration, mobile data infrastructure, and fuel. Courier network churn represents a significant structural risk, impacting distribution through digital platforms utilizing either gig-economy couriers or restaurant-employed staff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food delivery market presents a geographic-arbitrage play, with labor costs significantly lower in emerging markets like India compared to the regulatory burdens in the European Union. This disparity influences platform operational strategies and expansion priorities.
For Market Incumbents: Acquire AI-driven route optimization software developers to radically reduce last-mile delivery costs. This move counters the threat of increasing labor costs from regulatory shifts like the EU Platform Work Directive. Incumbents should also deepen subscription model penetration, leveraging existing North American customer stickiness to mitigate customer churn.
For New Entrants and Emerging Players: Educational institutions and healthcare facilities represent underserved buyer archetypes for tailored food delivery solutions. Target mid-sized urban centers in Southeast Asia for grocery delivery, leveraging lower operational overheads. A hyper-local go-to-market strategy, emphasizing exclusive partnerships with local vendors and community engagement, can build initial market share.
For Investors and Strategic Acquirers: Super-app integrators are the most active acquirers in this space, seeking to expand their ecosystem offerings. The market demonstrates long-term viability over the next decade, driven by sustained demand for urban convenience. Target logistics-as-a-service providers and specialized grocery delivery platforms. Monitor for successful integration of autonomous delivery technologies as a key inflection indicator for future profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Grocery Delivery Partnerships | Secures high-growth revenue streams through exclusive supermarket chain agreements. |
| Invest in AI-Powered Logistics | Reduces operational costs and improves delivery efficiency across urban networks. |
| Diversify into Non-Food Adjacencies | Leverages existing courier networks for pharmacy and retail package delivery. |
| Enhance Subscription Loyalty Programs | Increases customer retention and fosters recurring revenue relationships with users. |
| Acquire Last-Mile Automation Startups | Positions platforms for long-term cost reduction via drone and autonomous vehicle tech. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary data involved discussions with platform executives, restaurant owners, gig-economy couriers, and regulatory officials. This was triangulated with secondary sources including SEC filings, market reports, and government regulatory documents. The blended approach ensured both bottom-up granular detail and top-down market perspective.
Segment weighting across service type, customer type, and geographic region informed the analytical framework over the projection horizon. This framework integrated market size data, growth catalysts, and restraints to project future demand. Compound annual growth rates were derived via regression analysis and expert consensus. Key forecast inputs included smartphone penetration rates and urbanization trends in emerging markets.
Underlying measurement precision varies by segment; restaurant-to-customer and grocery delivery carry tighter precision. Forecasts reflect assumptions regarding evolving labor regulations and technological adoption. Practitioners should monitor new legislative actions and autonomous delivery pilot successes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Galley Equipment Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Europe Food Away from Home Market
Food Service
Meal Voucher Market
Food Service
Italy Foodservice Market
Food Service
Global Food Retail Market
Food Service
Online Grocery Market
Food Service
Snack Subscription Box Service Market
Food Service
South Africa Fast Food Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Kuwait Food Service Market
Food Service
Saudi Arabia Foodservice Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Benelux Foodservice Market