
 Kuwait Food Service Market | 2026-2036
Kuwait Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Food Service Market Insights
Meal bundling across quick service and full service formats is realigning how families and corporates allocate food expenditure. Americana Restaurants leverages its multi-brand portfolio to sustain foot traffic across diverse dayparts. M.H. Alshaya Co. anchors premium positioning through controlled mall-based locations. Kout Food Group competes via localized menu engineering that adapts regional poultry and dessert preferences.
Kuwait food service encompasses commercial preparation and sale of ready-to-consume meals through institutional, catering, quick service, and full service channels, operating under HACCP-aligned kitchen protocols and cold-chain specifications to ensure safety from procurement to plate. The sector serves consumption occasions spanning corporate contracts, family dining, tourism hospitality, and educational feeding programs. Quick service dominates transaction volume due to speed and price accessibility, while catering commands margin concentration through large-event contracts and institutional procurement. Home delivery and online ordering represent the fastest-expanding delivery mode as aggregator platforms restructure last-mile economics.
Kuwait Municipality enforces food safety licensing and hygiene inspections that determine market access for new entrants. The country's national standards body aligns commercial kitchen equipment with Gulf Standardization Organization requirements. MOHAP-adjacent emirate-level frameworks influence cross-border franchise standards imported from the UAE. Stakeholders must monitor how delivery platform commission structures and municipal zoning for cloud kitchens reshape capital deployment priorities.
Market Dynamics
Aggregator platforms are restructuring Kuwait's food service economics by compressing last-mile delivery margins and redirecting foot traffic from mall-based dining to cloud kitchen fulfillment. Kuwait Municipality's licensing requirements and HACCP-aligned kitchen protocols are simultaneously elevating operational barriers for new entrants.
Growth Catalysts
- Kuwait Municipality food safety certification:Mandatory HACCP-aligned protocols are standardizing kitchen operations across commercial food preparation facilities, creating uniform quality benchmarks that expand consumer trust in ready-to-consume meals.
- Working professional demand:Quick service restaurant formats are capturing transaction volume growth as office density in Kuwait City and Salmiya sustains high-frequency lunch and dinner occasions.
- Cloud kitchen zoning:Municipal land-use policies are enabling dedicated delivery-only production facilities, reducing real estate costs for operators focused on aggregator platform distribution.
Market Restraints
- Aggregator commission structures:Delivery platform economics extract 20-30% of order value, compressing net margins for operators dependent on third-party last-mile fulfillment.
- Cold-chain infrastructure concentration:Limited domestic logistics capacity for temperature-controlled distribution constrains menu expansion into premium perishable categories.
- Import dependency for protein inputs:Kuwait's domestic agricultural constraints force reliance on regional poultry and red meat suppliers, exposing operators to shipping cost volatility and customs processing delays.
Strategic Opportunities
- Educational feeding program expansion:Institutional catering contracts for K-12 and university campuses represent underpenetrated volume pools with predictable procurement cycles and multi-year tenors.
- Corporate contract catering:Oil sector and financial services employers are outsourcing in-house cafeteria operations, creating white space for specialized B2B food service operators.
- Tourism hospitality alignment:Hotel and resort F&B outsourcing is accelerating as hospitality groups prioritize asset-light management models, opening procurement channels for specialized caterers.
Industry Challenges
- HACCP certification timelines:New commercial kitchen approvals require 90-120 day inspection cycles, delaying revenue generation for capital-deployed facilities.
- Skilled kitchen labor scarcity:Experienced hot-line and pastry chefs command premium wages, inflating labor cost ratios above regional benchmarks.
- Legacy POS-aggregator integration:Older restaurant management systems require middleware development to synchronize inventory with real-time delivery platform orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Food Service Market |
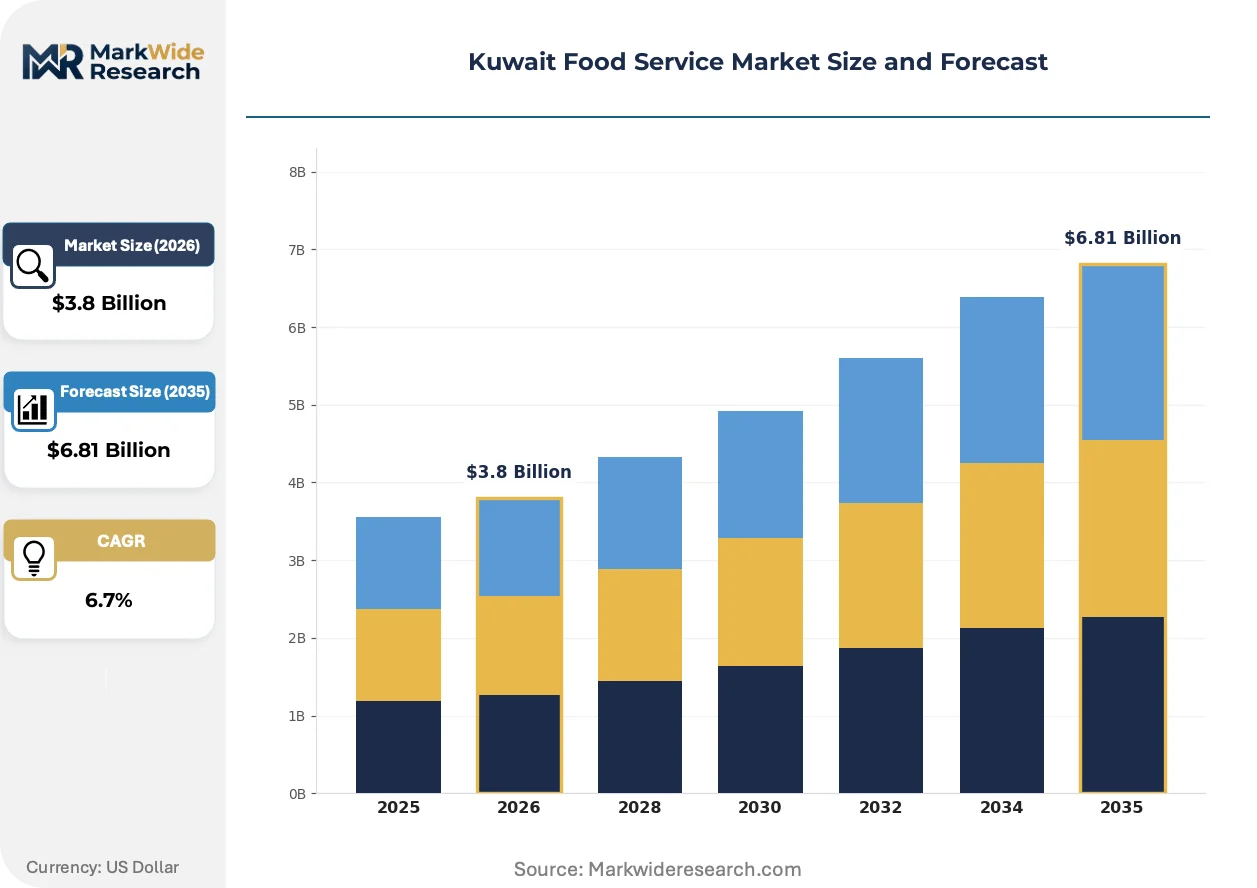
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Catering, Quick Service, Full Service, Institutional Food Type: Vegetarian, Seafood, Poultry, Desserts Customer Type: Families, Corporates, Tourists, Students Delivery Mode: Dine-In, Takeaway, Home Delivery, Online Ordering |
| Companies Covered | Alghanim Industries, Al Maousherji Catering Company, Americana Restaurants, Al Sayer Franchising Company, AlAmar Foods Company, M.H. Alshaya Co., Yum! Brands Inc., Gastronomica General Trading Company, Kout Food Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Food Service Market Trends and Innovations
Digital ordering infrastructure and municipal regulatory frameworks are converging to restructure how Kuwaiti consumers access prepared meals, compressing the interval between order placement and consumption while elevating food safety accountability.
Kitchen display systems and automated order routing are integrating with aggregator APIs to synchronize preparation timing with driver arrival windows. Full-service restaurants in Salmiya and Kuwait City are adopting these platforms to reduce ticket abandonment rates. This integration is compressing the competitive gap between quick-service speed and full-service menu breadth.
Kuwait Municipality's alignment with Gulf Standardization Organization equipment specifications is mandating stainless steel fabrication standards and ventilation hood certifications for new commercial kitchen permits. Operators must retrofit existing facilities or source compliant equipment for greenfield sites. Cloud kitchen developers in industrial zones are responding by pre-certifying entire facility shells to accelerate tenant onboarding.
Family dining occasions are fragmenting across multiple simultaneous delivery orders rather than single large-format meals. Parents and children are placing separate app-based orders from different restaurant brands converging on the same household. This pattern is most visible in high-income residential compounds where aggregator penetration exceeds 70% of monthly food expenditure.
Kuwait Food Service Market Segmentation
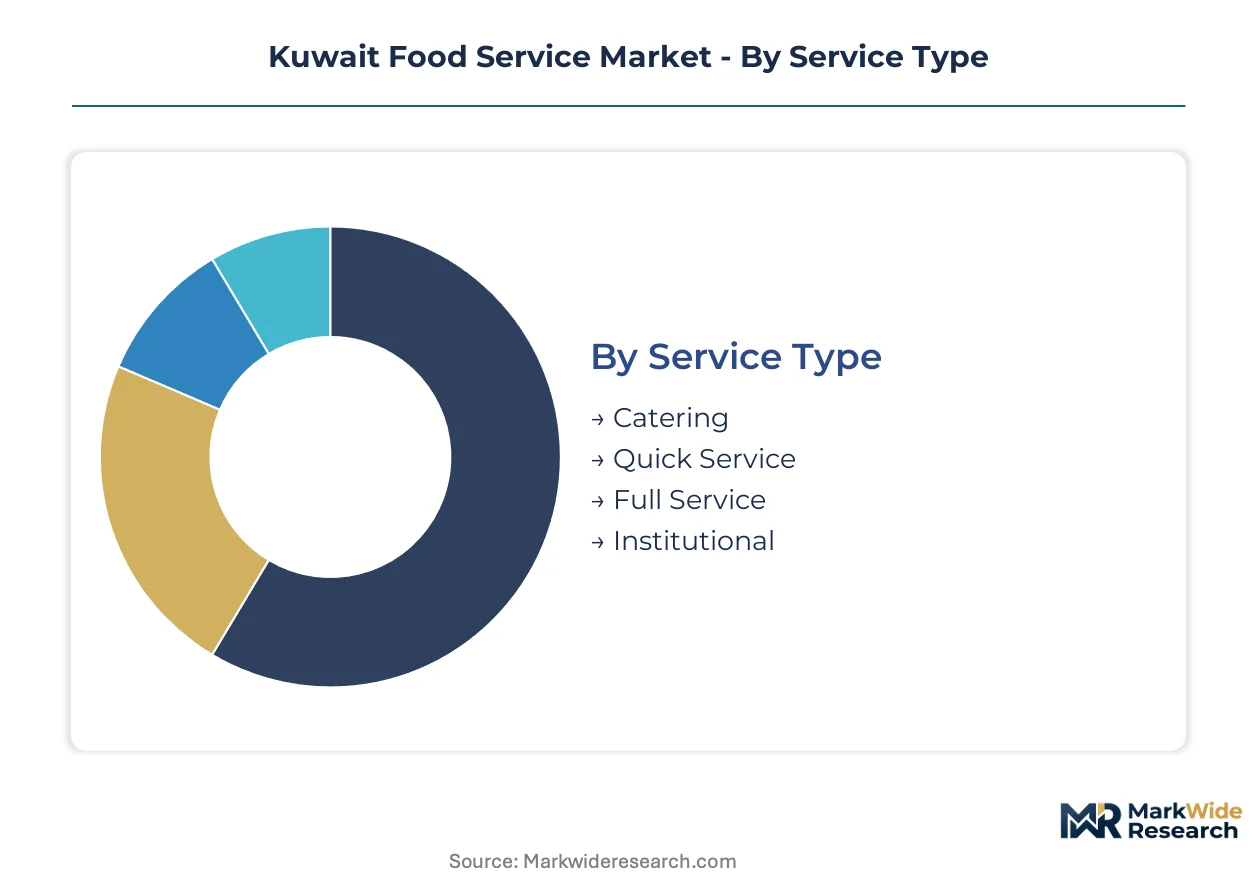
Service format selection determines capital deployment intensity, labor skill requirements, and regulatory compliance scope across Kuwait's food service landscape. Operators must align segment positioning with municipal zoning permissions and aggregator platform economics.
Service Type:
Format replacement cycles accelerate as cloud kitchen infrastructure and digital ordering platforms compress traditional dine-in renovation timelines.
- Catering:Large-volume meal production for events, institutions, and corporate contracts operates through centralized commissary kitchens with HACCP-certified cold-chain logistics. Oil sector employers in Ahmadi Governorate sustain demand for daily workforce feeding programs.
- Quick Service:Speed-oriented formats with limited menu breadth and standardized preparation protocols dominate transaction frequency in Kuwait City commercial districts. Working professionals drive lunch-hour volume concentration.
- Full Service:Table-service restaurants with extended meal durations and higher per-cover spending anchor family dining occasions in Salmiya mall complexes.
- Institutional:Dedicated feeding operations for educational facilities, healthcare campuses, and government ministries operate under extended procurement contracts with predictable volume commitments.
Quick Service sits at the top of the volume ranking, with Institutional climbing the fastest as educational outsourcing expands.
Food Type:
Menu engineering decisions balance import dependency costs against localized palate preferences and religious dietary requirements.
- Vegetarian:Plant-forward offerings exclude all meat and poultry derivatives, expanding as health-conscious consumption patterns penetrate affluent Kuwaiti households.
- Seafood:Marine protein preparations rely on regional supply chains from Gulf Cooperation Council fishing fleets and aquaculture operations.
- Poultry:Chicken-centric menu items dominate protein allocation due to price accessibility and cultural acceptance across all customer segments.
- Desserts:Traditional Arabic sweets and Western-style confectionery command premium pricing in both dine-in and delivery channels.
Poultry captures the largest share of protein-focused expenditure, with Desserts expanding most quickly through gifting and celebration occasions.
Customer Type:
Segment targeting shapes location strategy, pricing architecture, and daypart optimization across Kuwait's governorates.
- Families:Multi-generational dining units seek value-oriented formats with child-friendly amenities and spacious seating configurations.
- Corporates:Business-to-business procurement from financial services and energy sector employers demands consistent quality and invoice-grade documentation.
- Tourists:Hospitality-aligned consumption concentrates in hotel districts and cultural attraction zones with multilingual service capabilities.
- Students:Price-sensitive cohorts at Kuwait University and private K-12 campuses prioritize convenience and mobile payment integration.
Families generate the highest per-occasion spend, with Corporates gaining share fastest through outsourced cafeteria contracts.
Delivery Mode:
Fulfillment channel selection determines real estate cost structure, labor deployment models, and technology stack requirements.
- Dine-In:On-premise consumption requires full-service seating infrastructure and front-of-house staffing in high-rent mall and waterfront locations.
- Takeaway:Counter-service collection without seating minimizes footprint requirements while capturing impulse purchase occasions.
- Home Delivery:Third-party driver networks extend reach into residential compounds and apartment towers across Hawalli and Farwaniya governorates.
- Online Ordering:Platform-mediated purchase initiation through aggregator apps restructures discovery and payment workflows.
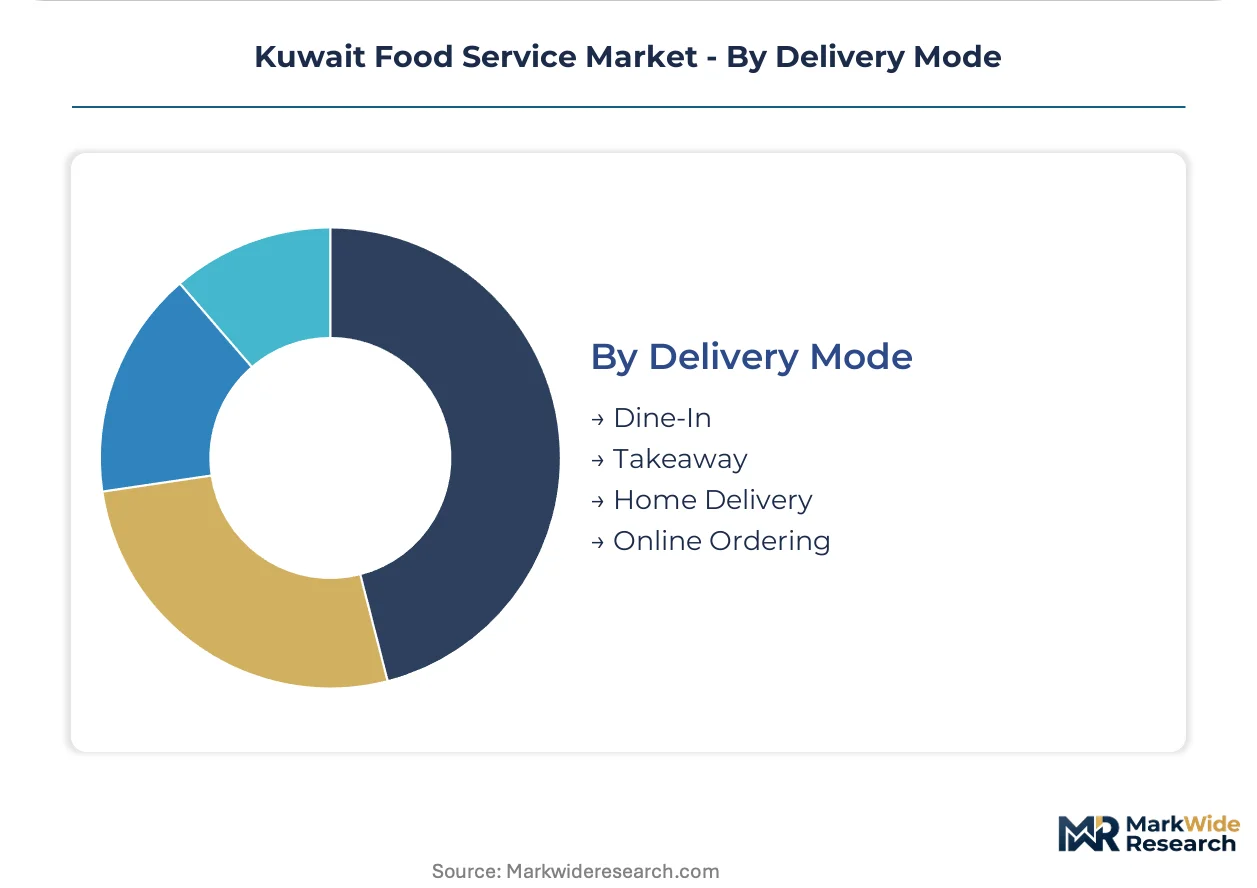
Home Delivery leads transaction volume, with Online Ordering showing the steepest expansion trajectory as smartphone penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait's food service industry traces its modern structure to the post-1970s oil boom, when expatriate workforce expansion and mall-based retail development created the infrastructure for organized commercial dining.
Kuwait City
Corporate headquarters density and banking sector employment sustain high-frequency lunch transactions across quick service and full service formats. Kuwait Municipality enforces HACCP-aligned kitchen certifications for all new commercial permits. The Sharq and Al-Mirqab districts concentrate premium full-service restaurants serving Gulf Cooperation Council business travelers.
Hawalli Governorate
Salmiya's retail mall complexes anchor family dining occasions with multiplex cinema adjacencies driving evening traffic peaks. The national standards body mandates Gulf Standardization Organization equipment specifications for ventilation and refrigeration systems. Block 4 commercial corridors host the highest cloud kitchen density as aggregator platforms restructure fulfillment economics.
Ahmadi Governorate
Oil sector workforce feeding programs generate institutional catering volume through multi-year corporate contracts. Ministry of Health-adjacent frameworks influence cross-border food safety standards imported from UAE-based hospitality groups. Al-Ahmadi industrial zones accommodate centralized commissary kitchens serving remote rig-site operations.
Farwaniya Governorate
Residential compound density in Khaitan and Ardhiya sustains home delivery transaction concentration exceeding other governorates. Municipal zoning for dedicated delivery-only facilities reduces real estate costs for cloud kitchen operators. The Jleeb Al-Shuyoukh corridor serves as the primary logistics hub for temperature-controlled distribution to apartment towers.
Jahra Governorate
Agricultural cooperative integration supports localized poultry and dairy procurement for institutional feeding programs. Land-use policies restrict commercial kitchen development in heritage preservation zones. Saad Al-Abdullah City represents emerging demand as residential expansion outpaces restaurant supply.
Kuwait Food Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across location control and brand portfolio breadth, creating a tiered structure where mall-based operators capture higher per-cover spending than street-front competitors. The vendor base clusters around three strategic archetypes: multi-brand franchise aggregators, single-concept specialists, and institutional catering contractors. Consolidation pressure intensifies as aggregator platforms favor operators with centralized kitchen infrastructure. Dominant competitive moves include portfolio diversification across dayparts and backward integration into commissary production.
Within the multi-brand franchise tier, Americana Restaurants, M.H. Alshaya Co., and Kout Food Group exemplify divergent approaches to market coverage. Americana Restaurants occupies a position as a portfolio-heavy operator spanning quick service and casual dining concepts. M.H. Alshaya Co. represents premium positioning through controlled mall-based location strategies. Kout Food Group anchors localized menu engineering capabilities adapting regional poultry and dessert preferences. Alghanim Industries and Al Maousherji Catering Company sit within the institutional and catering contractor archetype serving oil sector and government ministry contracts.
| Leading Market Players |
|---|
| Alghanim Industries |
| Al Maousherji Catering Company |
| Americana Restaurants |
| Al Sayer Franchising Company |
| AlAmar Foods Company |
| M.H. Alshaya Co. |
| Yum! Brands Inc. |
| Gastronomica General Trading Company |
| Kout Food Group |
| Others |
Pricing and Supply Chain Analysis
GCC poultry price benchmarks cascade through Kuwait's food service supply chain, compressing margins at quick-service tiers while insulating premium full-service operators who pass input volatility through menu engineering and portion adjustments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes Kuwait's food service landscape. Price differentiation hinges on HACCP certification tier and mall-based location premium versus street-front or cloud kitchen formats. Cost compression in economy tiers is intensifying because aggregator commission structures extract twenty to thirty percent of order value. Working professionals in Kuwait City commercial districts exhibit highest price sensitivity, while family dining occasions in Salmiya mall complexes demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-institutional channels handle oil sector and government ministry procurement volumes with multi-year contract tenors. Geographic supply concentration draws from Saudi Arabia, UAE, and Brazil for poultry inputs, with regional GCC fishing fleets anchoring seafood procurement. Raw material dependencies center on temperature-controlled protein shipments, specialized dessert ingredients, and commercial kitchen equipment compliant with Gulf Standardization Organization specifications. Single-source vulnerability runs through regional poultry suppliers exposed to shipping cost volatility. Distribution runs through aggregator platform networks for last-mile residential delivery and centralized commissary systems for institutional contracts.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's food service market functions as a stable compounder underpinned by expatriate workforce expansion and educational feeding program outsourcing that generates predictable recurring revenue streams.
For Market Incumbents: Extend cloud kitchen infrastructure into Farwaniya and Jahra governorates where residential density outpaces restaurant supply. Deepen backward integration into HACCP-certified commissary production to offset aggregator commission pressure. Secure municipal pre-certification for facility shells to compress tenant onboarding timelines against new entrant delays. For New Entrants and Emerging Players: Begin with institutional catering contracts in Ahmadi Governorate's oil sector workforce feeding programs, the most penetrable segment given multi-year procurement cycles and limited incumbent specialization. Pursue corporate cafeteria outsourcing for financial services employers in Kuwait City as the primary go-to-market angle, leveraging invoice-grade documentation capabilities as differentiation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized B2B catering contractors possessing oil sector relationships and HACCP-certified cold-chain infrastructure. Long-term viability rests on educational and corporate outsourcing tailwinds rather than discretionary dine-in exposure. Monitor aggregator platform commission structure negotiations as the critical inflection signal for operator margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Expansion | Municipal zoning in Farwaniya reduces real estate costs for delivery-only production facilities. |
| HACCP Certification Pre-Investment | Pre-certified facility shells accelerate tenant onboarding and revenue generation timelines. |
| Backward Integration into Commissary Production | In-house centralized kitchens offset aggregator commission compression and secure institutional contracts. |
| Educational Feeding Program Capture | K-12 and university outsourcing generates predictable procurement cycles with multi-year tenors. |
| Aggregator Platform API Integration | Kitchen display system synchronization reduces ticket abandonment and compresses preparation intervals. |
Research Methodology
Coverage spans Kuwait's six governorates, with primary inputs from each region's distinct demand profile. Primary interviews with restaurant operations directors, municipal licensing officials, aggregator platform account managers, and oil sector procurement officers combined with secondary validation from Kuwait Municipality food safety filings, Gulf Standardization Organization equipment specifications, and Ministry of Health-adjacent emirate-level regulatory frameworks. Bottom-up outlet counts and top-down expenditure estimates underwent cross-triangulation to reconcile volume and value outputs.
Granularity-level modeling operated at service format, food type, customer segment, and delivery mode dimensions across the analysis window. CAGRs derived from trend extrapolation of historical transaction volumes adjusted for working professional population growth and educational institution outsourcing penetration. Forecast inputs incorporated municipal cloud kitchen zoning approvals and aggregator platform smartphone penetration curves.
Several conditions sit outside the modeled scope, including sovereign oil revenue volatility affecting corporate catering budgets and abrupt aggregator platform commission restructuring. Forecasts reflect assumptions about HACCP certification timeline stability and regional poultry supply continuity. Periodic stress-testing of base assumptions is recommended given import dependency exposure and customs processing variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Commercial Air Fryer Market
Food Service
Street Vendors Market
Food Service
Indonesia Foodservice Market
Food Service
Food Trays Market
Food Service
Europe Barbeque Grill Market
Food Service
Food & Beverage in Asia Market
Food Service
Supermarkets Market
Food Service
Snack Subscription Box Service Market
Food Service
Plates Market
Food Service
Food Service Dairy Products Market
Food Service
Global Cafe and Bars Market
Food Service
Clear Ice Maker Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
New Zealand Foodservice Market
Food Service
Commercial Charbroiler Market