
 Citrus Pectin Market | 2026-2036
Citrus Pectin Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Pectin Market Analysis
Brazil is rewriting competitive dynamics in citrus pectin through expanded orange processing capacity and peel-derived feedstock availability. Cargill leverages its integrated supply chain from Brazilian orchards to European extraction facilities. Herbstreith & Fox KG Pektin-Fabriken anchors premium-grade production through specialized manufacturing in Germany. Silvateam dominates amidated pectin variants for low-sugar food systems.
Citrus pectin is a complex polysaccharide extracted from citrus fruit peels, primarily composed of galacturonic acid units with varying degrees of methoxylation that determine its gelling properties under specific calcium and pH conditions. It functions as a gelling agent, stabilizer, and thickener across food, pharmaceutical, and cosmetic applications. High methoxyl pectin occupies the largest volume share in conventional jam and confectionery applications where rapid set and firm texture remain essential. Low methoxyl pectin captures expanding share in reduced-sugar and clean-label food products where calcium-reactive gelling eliminates sugar dependence. Pharmaceutical applications represent the fastest-growing segment as pectin gains traction in wound healing formulations and colon-targeted drug delivery matrices.
The FDA governs pectin as a GRAS substance in food applications while imposing specific purity standards for pharmaceutical-grade material. The EU's REACH regulation and EFSA food additive evaluations shape extraction solvent limits and labeling requirements across European markets. Brazil's ANVISA and Ministry of Agriculture enforce residue thresholds that directly affect export eligibility for domestic processors. Stakeholders must monitor evolving pharmaceutical excipient monographs and clean-label certification schemes to secure positioning in premium application tiers.
Market Dynamics
The EU's revised REACH chemicals framework is tightening extraction residue limits, forcing processors to reconfigure solvent recovery systems and validate alternative purification methods across European extraction facilities.
Growth Catalysts
- Pharmaceutical excipient demand:Controlled-release drug formulations are incorporating pectin matrices for colon-targeted delivery, with FDA GRAS status accelerating pharmaceutical-grade qualification timelines.
- Clean-label food migration:Low-methoxyl amidated pectin variants are displacing synthetic stabilizers in reduced-sugar jam and dairy applications where calcium-reactive gelling eliminates sugar dependence.
- Sao Paulo processing concentration:Brazil's orange juice industry clusters generate captive peel feedstock supply, lowering raw material logistics costs for integrated processors.
Market Restraints
- Citrus peel supply volatility:Brazilian orange crop fluctuations from climate stress directly compress feedstock availability for pectin extraction, creating input cost instability.
- Specialized solvent dependency:Isopropanol and ethanol recovery requirements under REACH extraction residue limits add capital intensity to purification stages.
- Alginate and carrageenan substitution:Seaweed-derived hydrocolloids compete in dairy and pet food stabilizer applications where texture performance specifications overlap.
Strategic Opportunities
- Wound healing formulations:Hemostatic pectin dressings are penetrating hospital procurement channels in Germany and France where chronic wound management protocols favor polysaccharide-based absorbents.
- Cosmetic emulsion stabilization:Amidated low-methoxyl grades are entering clean beauty formulations as silicone alternatives in skin care emulsions.
- EU Green Deal bioeconomy incentives:Circular economy funding streams support citrus waste valorization projects that upgrade peel processing residues to pharmaceutical-grade pectin.
Industry Challenges
- Pharmaceutical monograph compliance:USP-NF and EP excipient certification timelines extend 18-24 months, delaying market entry for new extraction facilities.
- Skilled extraction technologist scarcity:Methoxylation degree control and amidation chemistry expertise concentrate among aging workforces in German and Italian processing centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Pectin Market |
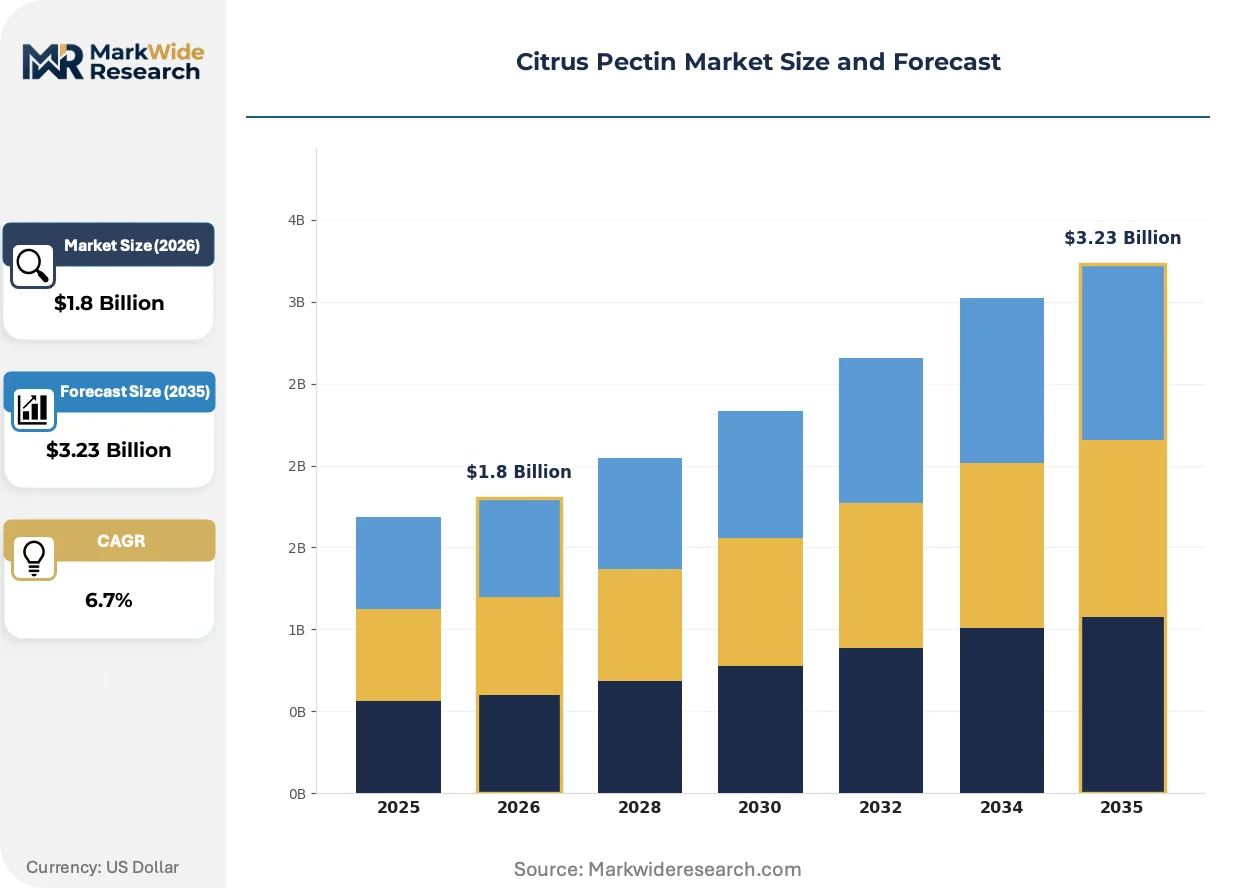
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Methoxyl Pectin, Low Methoxyl Pectin, Amidated Pectin, Others Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Powder, Liquid, Gel, Granular End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Dietary Supplement Firms |
| Companies Covered | Cargill, Herbstreith & Fox KG Pektin-Fabriken, Silvateam, CEAMSA, CP Kelco, Ingredion, Tate & Lyle, IFF, Yantai Andre Pectin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Pectin Market Emerging Trajectories
Process analytical technology and enzymatic modification methods are compressing extraction yield variability and enabling real-time quality control across pectin production lines.
Enzymatic esterification using engineered pectin methylesterases is digitizing degree-of-methoxylation control, replacing batch-wise chemical de-esterification. Pharmaceutical formulators in Switzerland and Denmark are adopting enzyme-modified grades for precision gelling in colon-targeted tablets. This shift is digitizing specification consistency while reducing solvent inventory requirements at extraction sites.
REACH Annex XVII updates on extraction solvent residues are tightening isopropanol limits to 50 ppm in food-grade material, compelling German processors to install membrane filtration upgrades. The regulation is compressing margins for non-integrated facilities while favoring capital-rich producers with captive solvent recovery infrastructure.
Direct procurement contracts between pharmaceutical excipient buyers and Brazilian peel processors are displacing traditional distributor intermediaries. Large generic drug manufacturers in India and contract development organizations in Ireland are negotiating long-term offtake agreements with Sao Paulo-based suppliers. This channel compression is most visible in high-methoxyl grades for conventional tablet binding where specification standardization enables direct relationships.
Citrus Pectin Market Segmentation
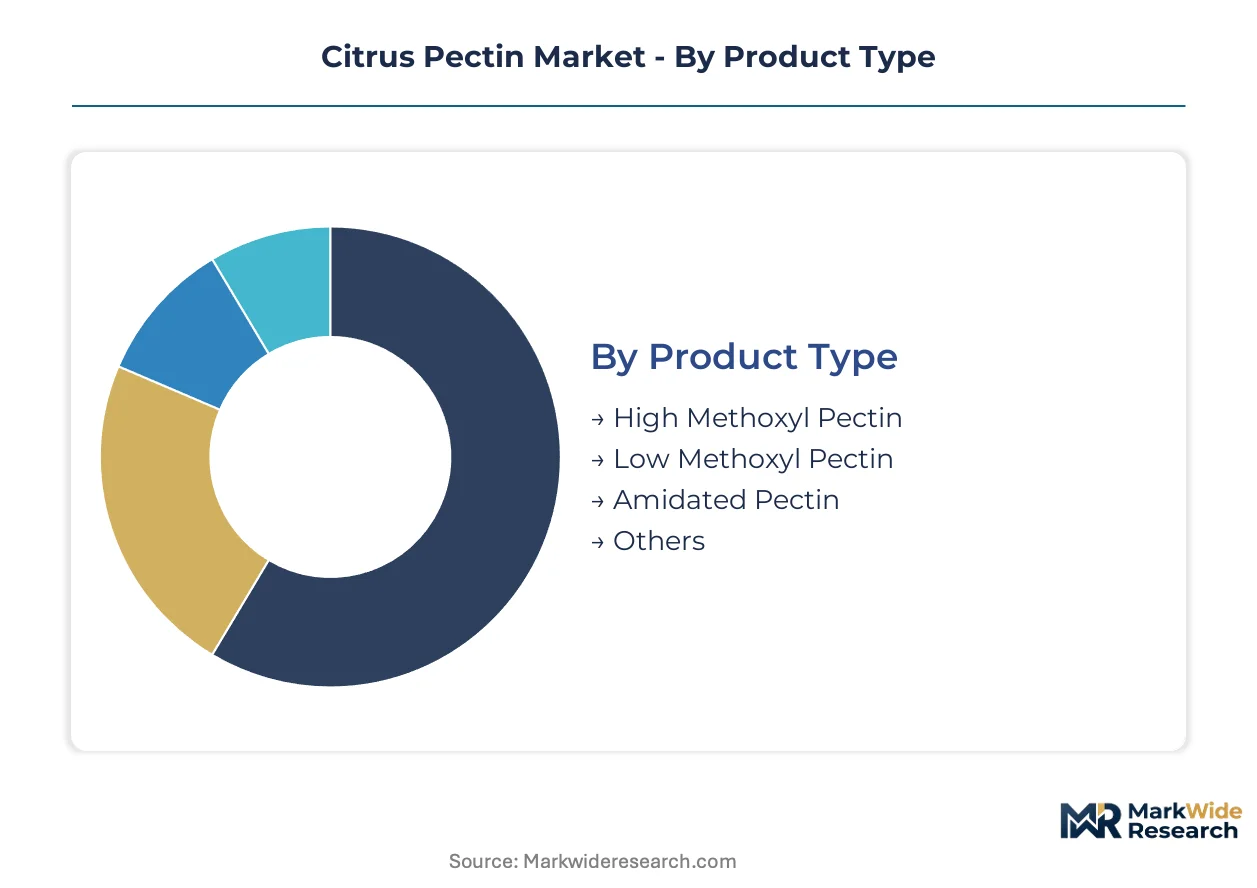
Pectin specifications vary dramatically across end-use requirements, with pharmaceutical-grade material commanding qualification timelines that stretch 18-24 months while food-grade product cycles in quarterly procurement windows. Segmentation reveals where technical barriers protect margin tiers and where specification standardization invites price competition.
Product Type:
Cycle times diverge sharply: high-methoxyl grades turn on seasonal jam formulation calendars, amidated variants lock into 2-3 year pharmaceutical excipient validation cycles, and low-methoxyl pectin sits in between as clean-label food migrations accelerate.
- High Methoxyl Pectin:Galacturonic acid chains carry >50% methylesterification, enabling rapid-set gelling in high-sugar environments above 55% soluble solids. Confectionery and traditional jam manufacturers in Germany and France specify HM grades for texture consistency where rapid gelation protects production line throughput.
- Low Methoxyl Pectin:De-esterified to <50% methoxylation, this grade reacts with calcium ions across reduced-sugar formulations. Dairy stabilizer demand in Switzerland and Denmark is climbing fastest as clean-label yogurt systems dislocate modified starch.
- Amidated Pectin:Partial amidation of carboxyl groups yields thermal-reversible gels tolerant of calcium variation. Pharmaceutical wound dressing applications in German hospital procurement channels favor amidated grades for hemostatic absorbency.
- Others:Specialized esterified and acetylated variants serve niche cosmetic emulsion requirements.
High Methoxyl Pectin dominates installed base. Low Methoxyl Pectin is where expansion concentrates.
Application:
Cost tier stratification separates commodity food thickeners from pharmaceutical excipients where USP-NF certification adds 40-60% price premiums over technical grades.
- Food & Beverage:Jam, confectionery, and dairy stabilizer applications specify pectin for gel strength and mouthfeel control. Brazilian orange peel supply clusters in Sao Paulo state directly feed this volume tier through integrated processors.
- Pharmaceuticals:Colon-targeted drug delivery matrices exploit pectin's resistance to gastric enzymes. Swiss and Danish formulators are adopting enzyme-modified grades for precision-controlled release kinetics in tablet coatings.
- Cosmetics:Clean beauty emulsions substitute amidated low-methoxyl grades for silicone-based stabilizers in skin care formulations.
- Nutraceuticals:Dietary supplement gummies and controlled-release capsules leverage GRAS status for accelerated product launches.
Food & Beverage commands volume leadership. Pharmaceuticals generates the steepest expansion trajectory.
Form:
Supply concentration favors powder production at Brazilian and German extraction sites, while liquid and gel forms require secondary formulation infrastructure closer to end-use manufacturing.
- Powder:Spray-dried standardized powder dominates bulk logistics and long-haul export from Sao Paulo processing clusters to European compounders.
- Liquid:Pre-hydrated solutions serve dairy processors seeking direct dosing without dissolution equipment capital.
- Gel:Ready-to-use gel concentrates penetrate small-batch confectionery and artisanal jam producers.
- Granular:Low-dust handling properties attract pharmaceutical tableting operations with stringent airborne particulate controls.
Powder commands installed base. Liquid is where expansion concentrates.
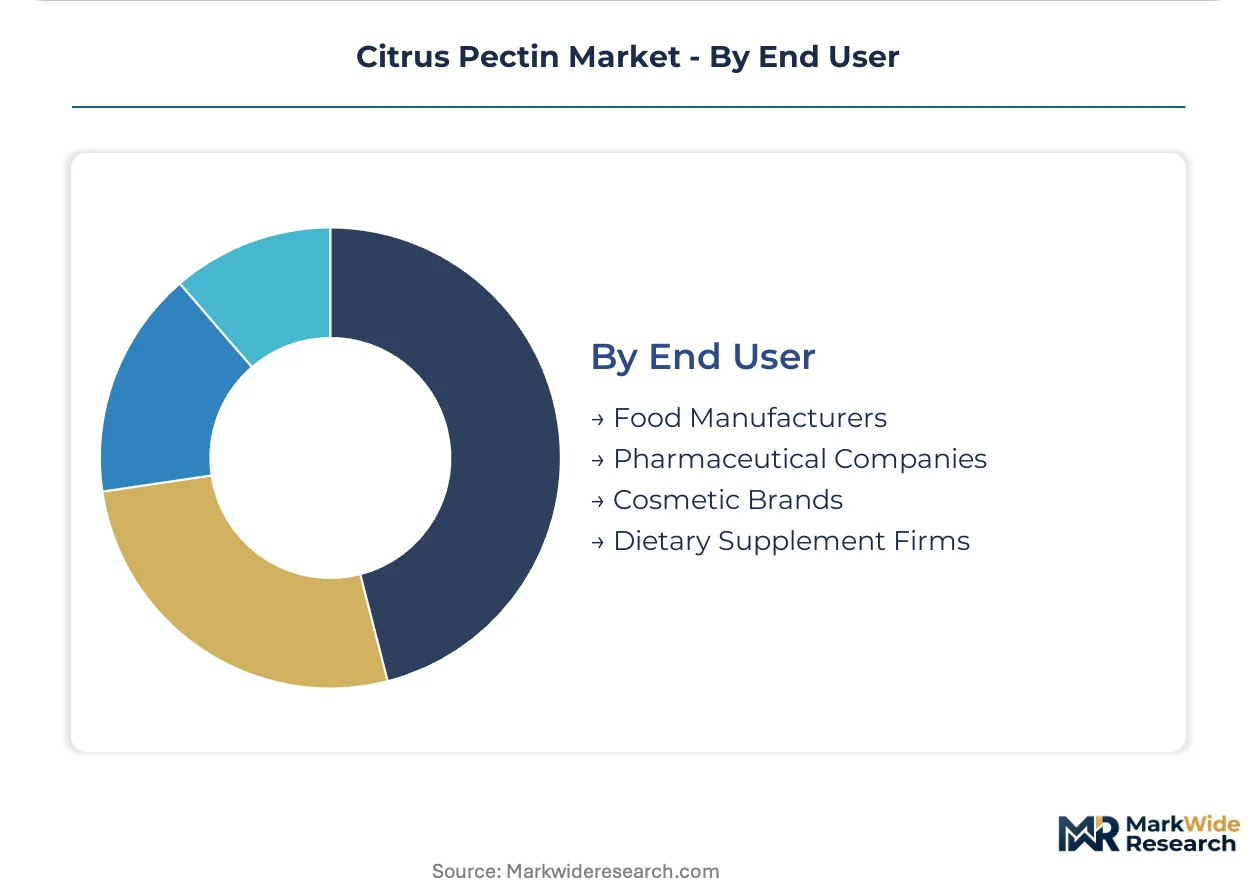
End User:
Customer type determines specification stringency: pharmaceutical companies enforce USP-NF and EP monograph compliance, while food manufacturers prioritize batch-to-batch viscosity consistency.
- Food Manufacturers:Industrial jam and dairy compounders in France and Germany specify gel strength ranges with tight tolerances to protect production line yields.
- Pharmaceutical Companies:Generic drug manufacturers in India and contract development organizations in Ireland negotiate direct offtake agreements with Brazilian peel processors, bypassing traditional distributor channels.
- Cosmetic Brands:Clean beauty formulators in Switzerland specify amidated grades for silicone-free emulsion stability.
- Dietary Supplement Firms:Gummy and soft-chew manufacturers leverage pectin's vegan positioning against gelatin alternatives.
Food Manufacturers dominate installed base. Pharmaceutical Companies is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peel feedstock availability clusters around orange processing infrastructure, with extraction capacity trailing juice industry geography. Regulatory divergence across jurisdictions fragments certification requirements for pharmaceutical-grade material.
Brazil
São Paulo state's orange juice clusters generate captive peel supply for integrated processors. ANVISA residue thresholds directly condition export eligibility for domestic extractors. Campinas and surrounding municipalities concentrate extraction facilities that serve European pharmaceutical compounders.
Germany
Specialized amidation chemistry expertise concentrates in Baden-Württemberg processing centers. ECHA REACH Annex XVII tightens isopropanol residue limits to 50 ppm for food-grade certification. Bodensee region extraction sites invest in membrane filtration to maintain EU market access.
United States
FDA GRAS status accelerates pharmaceutical-grade qualification timelines for colon-targeted drug delivery applications. Midwest dairy stabilizer demand drives low-methoxyl pectin consumption in clean-label yogurt systems. New Jersey and Pennsylvania house excipient distributors negotiating direct Brazilian offtake agreements.
Switzerland
Swissmedic pharmaceutical excipient standards enforce 18-24 month monograph compliance timelines. Geneva and Basel formulators adopt enzyme-modified grades for precision tablet coating applications. Domestic compounders source amidated variants for wound healing hemostatic dressings.
China
Domestic jam and confectionery manufacturers specify high-methoxyl grades for rapid-set gelling in high-sugar environments. NMPA pharmaceutical excipient regulations tighten purity documentation for imported material. Shandong Province citrus processing expansion feeds regional extraction capacity growth.
Citrus Pectin Market Vendor Landscape
Vertically integrated agribusiness conglomerates and specialized extraction specialists split the market into distinct capability tiers. Consolidation pressure concentrates among capital-rich producers with captive solvent recovery infrastructure. Three archetypes dominate: orchard-integrated processors controlling peel supply, premium-grade specialists with pharmaceutical monograph certification, and regional formulators serving food-grade volume tiers. Competitive moves center on backward integration into Brazilian peel sourcing and membrane filtration upgrades for REACH compliance.
Within the orchard-integrated tier, Cargill leverages Brazilian supply chain control. Specialized German manufacturers Herbstreith & Fox KG Pektin-Fabriken occupy positions anchored by amidation chemistry expertise. Silvateam represents the premium-grade specialist archetype with focused capabilities in modified pectin variants.
| Leading Market Players |
|---|
| Cargill |
| Herbstreith & Fox KG Pektin-Fabriken |
| Silvateam |
| CEAMSA |
| CP Kelco |
| Ingredion |
| Tate & Lyle |
| IFF |
| Yantai Andre Pectin |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European extraction facilities is compressing utilization rates below break-even thresholds, forcing processors to accept thinner margins on food-grade contracts while reserving premium pricing power for pharmaceutical-grade material with active USP-NF certification pipelines.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European markets, separating certified pharmaceutical excipients from technical food-grade material. Three-tier pricing stratifies across premium pharmaceutical grades with full monograph compliance, standard food-grade variants meeting residual solvent limits, and economy technical grades for industrial applications. Cost compression in standard food-grade tiers is intensifying because Brazilian integrated processors are expanding direct-to-compounder contracts, bypassing distributor markups. Generic drug manufacturers in India exhibit the highest price sensitivity due to procurement centralization, while Swiss wound dressing formulators show minimal sensitivity given specification-locked supply agreements.
Supply Chain Analysis
Export eligibility restrictions under Brazil's ANVISA residue protocols limit feedstock flows to European pharmaceutical compounders, creating tiered access based on certification status. Supply concentrates in Brazil, Germany, and Switzerland, with São Paulo state generating captive orange peel feedstock and Baden-Württemberg hosting specialized amidation chemistry capacity. Raw material dependencies center on citrus peel supply from juice processing clusters, isopropanol for extraction purification, and engineered pectin methylesterases for enzymatic modification. Single-source vulnerability runs through São Paulo's orange crop exposure to climate stress. Distribution runs through direct procurement contracts between Brazilian peel processors and European pharmaceutical buyers, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized extraction technologists capable of precision methoxylation control are aging out of German and Italian processing centers faster than training pipelines replenish, concentrating capability premiums among incumbent certification holders.
For Market Incumbents: Harden pharmaceutical monograph certification pipelines by extending 18-24 month USP-NF validation timelines for new extraction capacity, while securing backward integration into São Paulo peel sourcing to defend against Brazilian crop volatility. Expand membrane filtration infrastructure to maintain REACH Annex XVII compliance as isopropanol residual limits tighten. Prioritize amidation chemistry R&D to differentiate amidated low-methoxyl grades from alginate and carrageenan substitutes in dairy stabilizer applications. For New Entrants and Emerging Players: China's Shandong Province offers underpenetrated white-space for regional jam and confectionery manufacturers seeking high-methoxyl grades with rapid-set gelling specifications. Target cosmetic emulsion stabilization in Swiss clean beauty formulators seeking silicone alternatives, where specification standardization remains lower than pharmaceutical tiers. Establish enzymatic modification partnerships with Danish or Swiss precision formulators to bypass capital-intensive chemical de-esterification infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade extraction facilities due to membrane filtration and solvent recovery infrastructure requirements. Long-term viability favors acquisition targets with captive Brazilian peel supply and active pharmaceutical excipient certification pipelines. Monitor direct procurement contract announcements between São Paulo processors and Indian generic manufacturers as inflection signals for distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Excipient Certification | USP-NF and EP monograph compliance unlocks 40-60% price premiums over technical grades in colon-targeted drug delivery applications. |
| Backward Integration into Peel Supply | Captive São Paulo orange peel sourcing insulates processors from Brazilian crop volatility and ANVISA export eligibility disruptions. |
| Membrane Filtration Infrastructure | REACH Annex XVII isopropanol limits at 50 ppm favor capital-rich producers with installed solvent recovery systems. |
| Enzymatic Modification Capability | Engineered pectin methylesterases enable precision degree-of-methoxylation control for Swiss and Danish tablet coating formulators. |
| Direct Procurement Contracts | Long-term offtake agreements between Brazilian processors and Indian generic manufacturers compress distributor margins. |
Methodological Framework
A standing panel of extraction plant managers, pharmaceutical formulation scientists, citrus procurement leads at juice processors, and regulatory affairs specialists at excipient distributors provided ongoing calibration across the research cycle. Primary interviews combined with secondary validation from FDA GRAS substance filings, ECHA REACH Annex XVII updates, ANVISA residue threshold documentation, and Brazilian Ministry of Agriculture export records. Bottom-up volume estimates from São Paulo processing clusters triangulated against top-down demand projections from European pharmaceutical compounders.
Scenario-bracketing framed demand trajectories across high-methoxyl, low-methoxyl, and amidated product grades, with end-use segmentation across food and beverage, pharmaceutical, cosmetic, and nutraceutical applications. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-validation against customs trade data and excipient distributor shipment records. Forecast inputs incorporated enzyme-modification adoption rates in Swiss precision formulators and wound dressing procurement volumes in German hospital systems.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Brazilian orchard-integrated processors to bypass European extraction facilities entirely would shift outcomes. Material shifts in REACH solvent residue limits or ANVISA export certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Soy Protein Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Europe Amino Acid Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
GCC Egg Powder Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Global Dry Yeast Market
Ingredients
Chickpea Flour Market
Ingredients
North America Lipid Market
Ingredients
Italy Soy Protein Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
Siraitia Grosvenorii Extract Market