
 Enhanced Flight Vision Systems ( EFVS) Market | 2026-2036
Enhanced Flight Vision Systems ( EFVS) Market Size, Share, and Industry Trends Forecast 2026-2036
Enhanced Flight Vision Systems ( EFVS) Market Foresight
The gap between synthetic vision generation and real-time sensor fusion is narrowing as multi-spectral imaging architectures replace single-band infrared designs. Collins Aerospace leverages in-house waveguide optics manufacturing to sustain its position in integrated head-up displays. Elbit Systems Ltd anchors its portfolio on military-grade thermal cores adapted for commercial helicopter platforms. Honeywell International Inc differentiates through proprietary image-processing algorithms that reduce pilot cognitive load during low-visibility approaches.
Enhanced Flight Vision Systems combine infrared sensors, thermal imagers, and synthetic vision processors to project real-time terrain and obstacle imagery onto cockpit displays, enabling operations below natural visual minimums with resolution thresholds typically exceeding 640x512 pixels. The technology dimension splits across thermal imaging, which dominates current line-fit installations due to proven reliability in precipitation, and synthetic vision, which captures retrofit momentum as software-upgrade pathways lower hardware swap costs. Commercial aviation leads application demand from regulatory pressure on Category III approach capabilities, while helicopter operations occupy a specialized niche where EFVS enables EMS and offshore missions in degraded visual environments.
FAA Advisory Circular 90-106 and EASA CS-AWF certification frameworks mandate operational credit protocols that directly shape product development roadmaps and airworthiness approval timelines. The EU AI Act and emerging machine-vision autonomy standards in Europe are beginning to intersect with EFVS validation for single-pilot and reduced-crew operations. Stakeholders must monitor how regulatory divergence between FAA performance-based standards and EASA prescriptive technical requirements will influence platform certification costs and fleet deployment strategies.
Market Dynamics
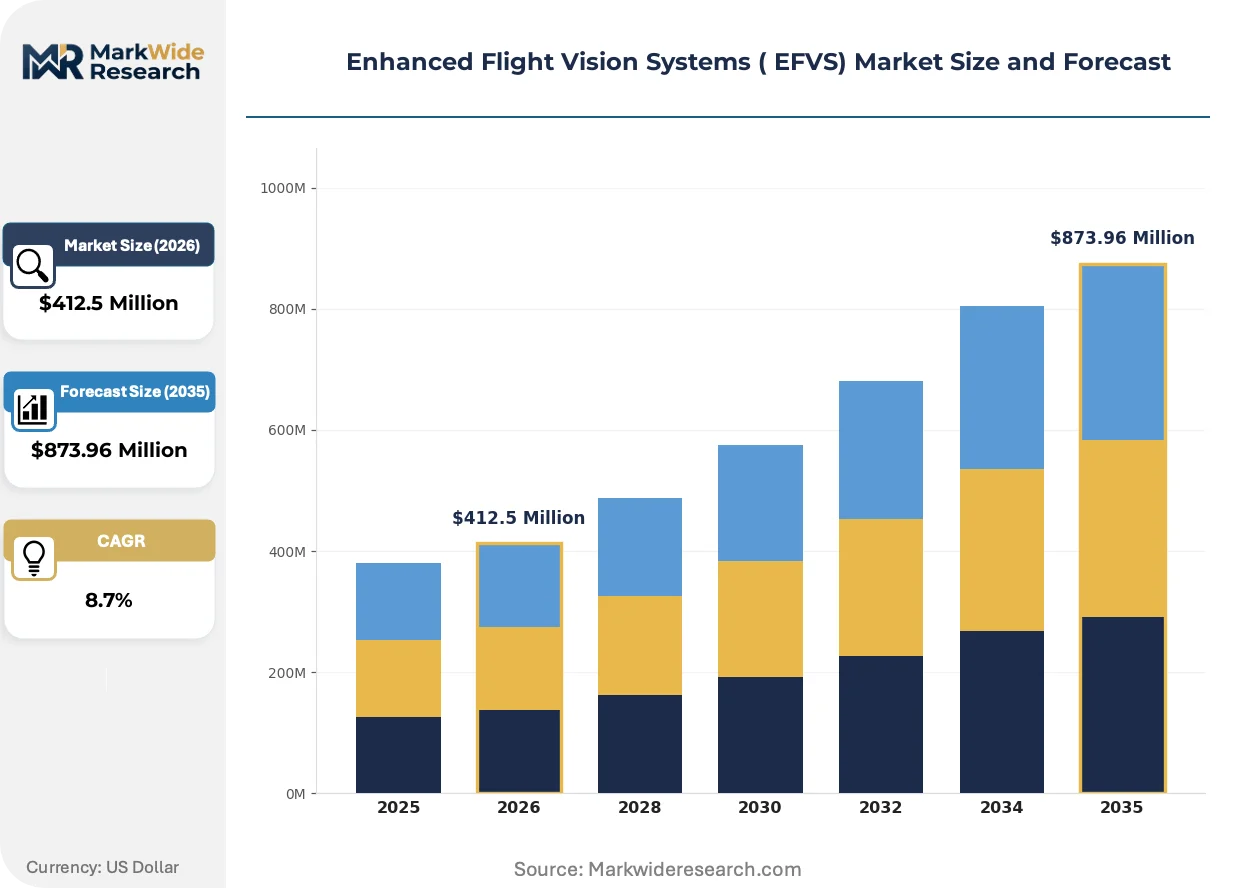
FAA and EASA low-visibility operational mandates are compressing certification timelines while thermal imaging sensor miniaturization reduces hardware footprints. This regulatory-technology intersection is forcing retrofit prioritization decisions across commercial fleets.
Growth Catalysts
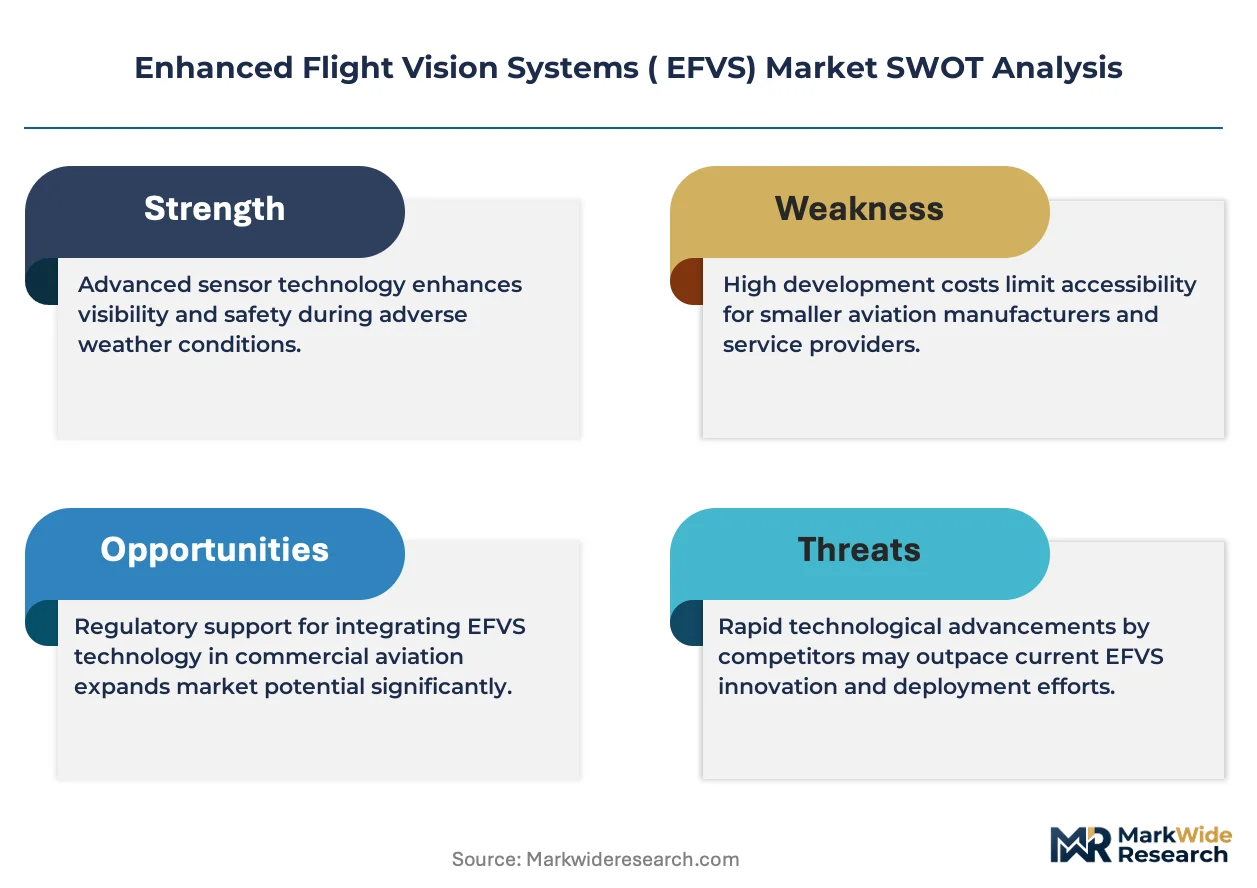
- FAA Advisory Circular 90-106:Mandates operational credit protocols that accelerate fleet retrofit schedules for Category III approach capabilities.
- Multi-spectral imaging architectures:Replace single-band infrared designs, narrowing the gap between synthetic vision generation and real-time sensor fusion.
- Helicopter EMS and offshore missions:Degraded visual environment operations in North America drive specialized EFVS adoption outside commercial aviation.
Market Restraints
- Waveguide optics supply concentration:In-house manufacturing capabilities concentrate among integrated head-up display producers, limiting supplier diversity.
- EASA prescriptive technical requirements:Divergence from FAA performance-based standards inflates platform certification costs and extends airworthiness approval timelines.
- Thermal core input volatility:Military-grade thermal imager availability fluctuates with defense procurement cycles, constraining commercial adaptation.
Strategic Opportunities
- EU AI Act intersection:Emerging machine-vision autonomy standards create validation pathways for single-pilot and reduced-crew EFVS configurations.
- Software-upgrade retrofit pathways:Synthetic vision processors enable hardware-sparing installations, lowering swap costs for aging commercial fleets.
- Real-time image processing convergence:Advances in edge computing and sensor fusion open integration with predictive terrain databases.
Industry Challenges
- Pilot cognitive load management:Proprietary algorithm development requires specialized human-factors engineering expertise that remains scarce in commercial aviation.
- Resolution threshold certification:Sustaining 640x512 pixel minimums across precipitation conditions demands continuous sensor calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enhanced Flight Vision Systems ( EFVS) Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal Imaging, Infrared Sensors, Synthetic Vision, Image Processing Application: Commercial Aviation, Military Aviation, Helicopter Operations, UAVs End User: Airlines, Government Agencies, Private Operators, Military Installation Type: Line Fit, Retrofit, Standalone, Integrated Systems |
| Companies Covered | Honeywell International Inc, Collins Aerospace, Elbit Systems Ltd, L3Harris Technologies Inc, Thales Group, Astronics Corporation, FLIR Systems Inc, BAE Systems, Garmin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enhanced Flight Vision Systems ( EFVS) Market Shifts & Advancements
EFVS technology trajectories center on sensor fusion sophistication, regulatory framework evolution, and procurement model adaptation. These forces are compressing traditional equipment replacement cycles.
Multi-spectral imaging architectures is digitizing terrain representation by combining infrared, thermal, and synthetic vision inputs into unified cockpit displays. Commercial airlines in the United States are adopting these systems at accelerated retrofit pace to meet operational mandates. The technology is digitizing legacy single-band approaches, compressing the competitive window for standalone infrared suppliers.
EU AI Act provisions on machine-vision autonomy are intersecting with EASA CS-AWF certification frameworks for reduced-crew operations. This regulatory overlap creates dual compliance obligations for manufacturers targeting European single-pilot platforms. Helicopter operators in offshore North Sea environments face the steepest validation requirements, driving earlier engagement with notified bodies.
After-sales service unbundling is fragmenting traditional integrated support contracts into discrete sensor calibration, software maintenance, and training modules. Regional MRO providers in the United States are capturing calibration work previously retained by OEMs. This shift is most visible among mid-size commercial carriers seeking to reduce per-flight-hour support costs.
Enhanced Flight Vision Systems ( EFVS) Market Segmentation
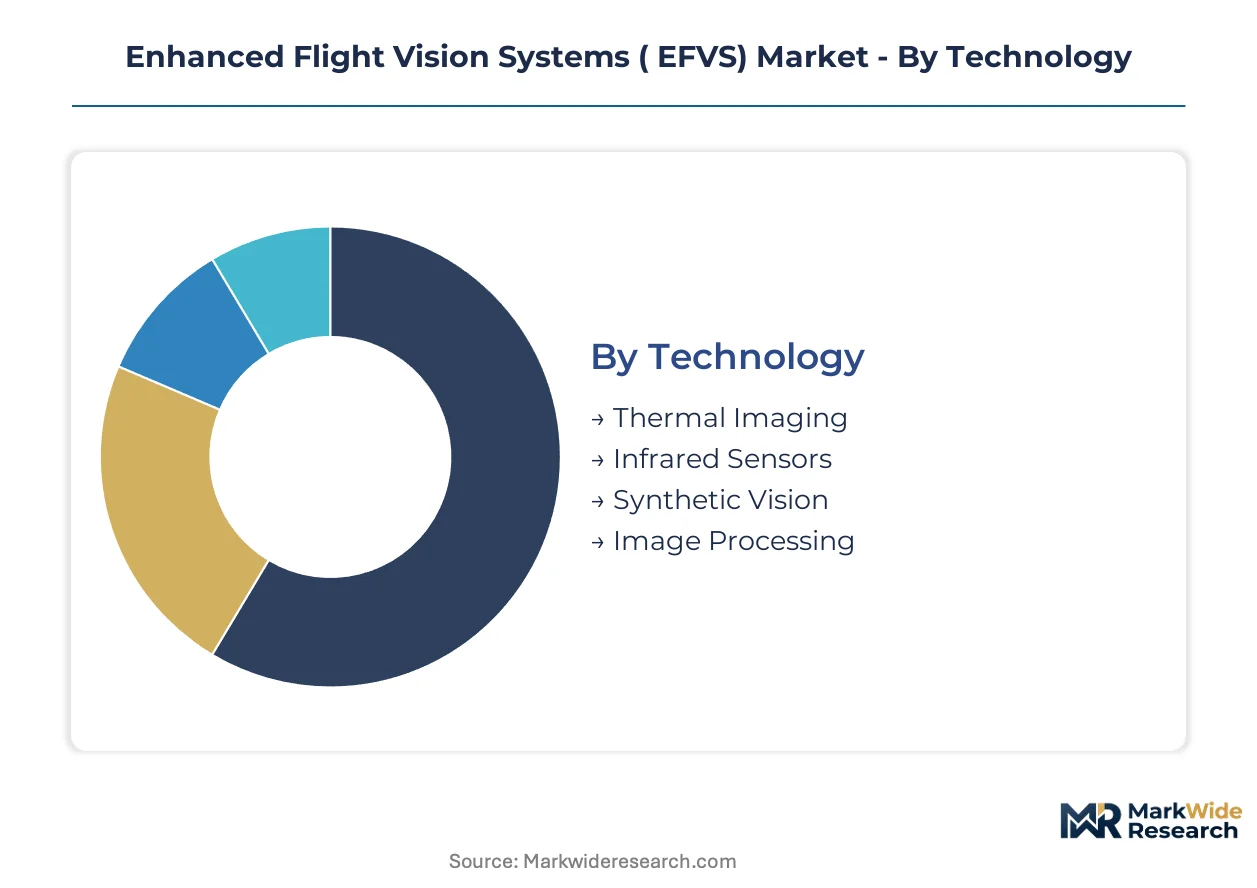
EFVS procurement patterns diverge sharply across technology architectures and installation pathways. Fleet operators weigh hardware swap costs against software-upgrade trajectories when selecting system configurations for low-visibility operations.
Technology:
Cost tier differentiation separates proven thermal hardware from emerging synthetic vision software pathways.
- Thermal Imaging:Infrared cameras capture terrain heat signatures with resolution thresholds typically exceeding 640x512 pixels. Commercial airlines in the United States prioritize this technology for Category III approach certifications under FAA mandates.
- Infrared Sensors:Single-band and multi-spectral detectors convert electromagnetic radiation into cockpit-display imagery. Precipitation resilience drives adoption across North Atlantic routes where fog and rain degrade natural visibility.
- Synthetic Vision:Database-driven terrain rendering reduces hardware footprints through software-centric architectures. Retrofit momentum accelerates as carriers seek hardware-sparing upgrade paths.
- Image Processing:Real-time edge computing algorithms fuse sensor inputs into unified pilot displays. Proprietary algorithm development concentrates among integrated avionics manufacturers.
Thermal Imaging holds installed capacity. Synthetic Vision is rotating up the share rankings.
Application:
Volume concentration varies by operational environment and regulatory pressure intensity.
- Commercial Aviation:Fixed-wing passenger and cargo operations face the steepest low-visibility mandate compliance requirements. FAA Advisory Circular 90-106 and EASA CS-AWF frameworks compress fleet retrofit timelines.
- Military Aviation:Defense procurement cycles govern thermal core availability for adapted commercial platforms. Mission requirements prioritize multi-spectral threat detection alongside terrain visualization.
- Helicopter Operations:EMS and offshore missions in degraded visual environments create specialized demand outside fixed-wing markets. North Sea oil platform routes drive the most demanding validation requirements.
- UAVs:Unmanned platforms require reduced-size sensor packages with autonomous landing capabilities. Regulatory frameworks for beyond-visual-line-of-sight operations remain fragmented across jurisdictions.
Commercial Aviation dominates current procurement volumes. Helicopter Operations are climbing the fastest as offshore energy investment recovers.
End User:
Customer type determines procurement scale and support contract structures.
- Airlines:Network carriers and low-cost operators pursue fleet-wide standardization to simplify pilot training and maintenance protocols. United States-based carriers lead retrofit installation activity.
- Government Agencies:National aviation authorities and public safety departments procure systems for regulatory compliance demonstration and first-responder applications.
- Private Operators:Corporate flight departments and charter services select configurations balancing capability against per-aircraft acquisition costs.
- Military:Defense ministries integrate EFVS with broader mission systems through classified procurement channels.
Airlines command the largest order backlogs. Government Agencies are expanding procurement as low-visibility operational mandates broaden.
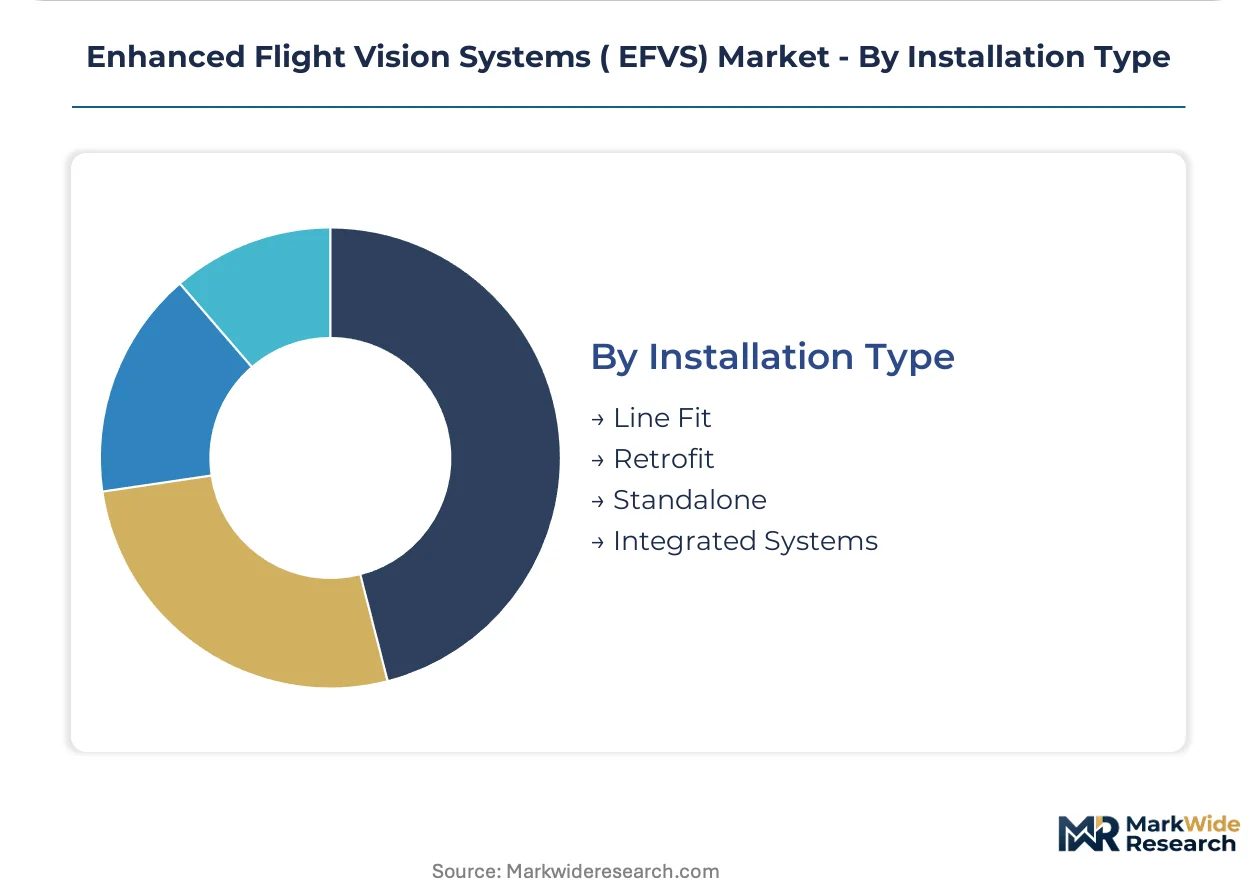
Installation Type:
Maturity curves separate factory-integrated designs from aftermarket retrofit solutions.
- Line Fit:OEM-integrated systems installed during airframe manufacture offer optimized weight distribution and power consumption. Airbus and Boeing delivery schedules influence annual volume.
- Retrofit:Aftermarket installation on in-service aircraft accelerates as regulatory deadlines approach. Aging commercial fleets in the United States generate concentrated demand.
- Standalone:Self-contained units with dedicated displays suit operators avoiding full cockpit avionics integration.
- Integrated Systems:Multi-function displays combining EFVS with primary flight instruments reduce panel space requirements.
Line Fit captures new-build commitments. Retrofit is gaining share fastest as mandate deadlines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retrofit-focused carriers and offshore helicopter operators drive EFVS procurement intensity across concentrated aviation markets. Regulatory mandate timelines compress installation schedules unevenly by jurisdiction.
United States
Network carriers accelerate Category III retrofit programs ahead of FAA Advisory Circular 90-106 operational credit deadlines. The FAA mandates specific training protocols for pilots utilizing EFVS during low-visibility approaches. Dallas-Fort Worth and Atlanta hubs concentrate installation activity as major carriers standardize fleet configurations.
Germany
Lufthansa Group and cargo operators pursue EASA CS-AWF certification for reduced-crew long-haul operations. EASA prescriptive technical requirements extend validation timelines compared to performance-based alternatives. Hamburg and Munich maintenance clusters host specialized EFVS integration facilities serving Central European fleets.
United Kingdom
North Sea helicopter operators face the steepest degraded visual environment validation requirements in offshore energy markets. The UK Civil Aviation Authority enforces stringent approach minima for platform supply missions. Aberdeen serves as the primary concentration for EMS and offshore EFVS deployment expertise.
France
Airbus integration lines at Toulouse drive line-fit demand for new-generation narrowbody deliveries. The country's national aviation regulator coordinates with EASA on single-pilot cockpit validation frameworks. Paris-Le Bourget corporate aviation clusters adopt standalone EFVS units for premium charter operations.
Japan
ANA and JAL retrofit schedules align with Tokyo Haneda and Narita capacity expansion timelines. METI promotes domestic sensor component manufacturing through targeted industrial policy. Nagoya aerospace clusters develop waveguide optics subsystems for regional display integrators.
Enhanced Flight Vision Systems ( EFVS) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent certification pathways. The vendor base separates into three tiers: integrated avionics manufacturers with captive display production, thermal core specialists supplying sensor subsystems, and software-centric processors leveraging upgrade pathways. Dominant competitive moves include strategic partnerships for regulatory co-certification and selective backward integration into optics manufacturing.
Among US-based conglomerates with aerospace divisions, Honeywell International Inc and Collins Aerospace exemplify the integrated-system archetype through captive supply chains. Elbit Systems Ltd represents the defense-adaptation model, translating military thermal core expertise toward commercial helicopter platforms. These three anchors illustrate how geographic origin and legacy specialization shape competitive positioning without converging on identical capability stacks.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Collins Aerospace |
| Elbit Systems Ltd |
| L3Harris Technologies Inc |
| Thales Group |
| Astronics Corporation |
| FLIR Systems Inc |
| BAE Systems |
| Garmin Ltd |
| Others |
Supply & Pricing Matrix
Waveguide optics manufacturing concentrates in Japan and the United States, concentrating margin capture among integrated head-up display producers while fragmenting pricing power for standalone sensor suppliers. Cost-plus contracts with thermal core indexation dominate procurement, compressing margins for non-integrated vendors as military-grade imager availability fluctuates.
Pricing Analysis
Cost-plus contracts with thermal core indexation anchor system pricing, tying hardware costs to defense procurement cycles. Price differentiation separates FAA-certified configurations from EASA-validated alternatives, with dual-certification premiums reflecting extended validation timelines. Pricing pressure intensifies in the retrofit segment as software-upgrade pathways reduce hardware swap premiums. Regional carriers exhibit highest price sensitivity, while network carriers prioritize standardization over per-unit cost optimization.
Supply Chain Analysis
Supplier-financing facilities extend payment terms to 180 days for thermal imager procurement, straining working capital for mid-tier integrators. Manufacturing concentrates in the United States, Japan, and Israel, with waveguide optics and thermal cores forming critical input dependencies. Single-source vulnerability in military-grade thermal imager supply creates certification timeline risk for commercial adaptations. Distribution runs through OEM-integrated channels and specialized avionics MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFVS procurement is shifting toward platform-economics logic as sensor fusion architectures demand interoperability across avionics suites, with multi-spectral imaging ecosystems displacing standalone component markets.
For Market Incumbents: Pre-empt synthetic vision commoditization by deepening captive waveguide optics production and securing exclusive thermal core allocation agreements. Software-centric entrants threaten hardware margins through upgrade-pathway disruption. Backward integration into edge-computing processors preserves algorithm differentiation. For New Entrants and Emerging Players: Establish a beachhead in helicopter EMS retrofit installations, where degraded visual environment requirements outpace incumbent certification bandwidth. North Sea offshore operators present the most penetrable segment given EASA validation complexity. Lead with standalone display units avoiding full cockpit integration costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed avionics specialists holding EASA CS-AWF certification but lacking FAA dual-validation. Long-term viability hinges on regulatory convergence across jurisdictions. Watch for EU AI Act machine-vision autonomy standards as inflection signal for reduced-crew platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Co-Certification Partnership | Dual FAA-EASA validation compresses time-to-revenue for new platform introductions. |
| Thermal Core Supply Agreement | Long-term military surplus allocation secures commercial production continuity. |
| Software-Defined Vision Upgrade | Synthetic vision pathways reduce hardware retrofit costs for aging commercial fleets. |
| Helicopter Platform Specialization | EMS and offshore niche commands premium pricing outside commoditized commercial aviation. |
| After-Sales Service Unbundling | Discrete calibration modules capture MRO revenue previously retained by OEMs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with avionics procurement directors, FAA certification engineers, helicopter operations managers, and thermal imaging R&D leads; and secondary validation against FAA Advisory Circular filings, EASA CS-AWF certification databases, OEM delivery schedules, and customs import records for waveguide optics components. Bottom-up installation forecasts triangulated against top-down fleet mandate compliance requirements.
Forecast inputs span technology architecture, installation pathway, application environment, and regulatory jurisdiction across the projection horizon. CAGRs derive from segment-level volume build-ups adjusted for airworthiness approval timeline distributions. Fleet age profiles and mandate deadline clustering shape retrofit acceleration curves. Thermal core availability constraints and sensor miniaturization cost curves inform hardware pricing trajectories.
Stress conditions across thermal imager supply volatility, EASA-FAA regulatory divergence, and single-pilot cockpit adoption timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification pathway standardization and fleet replacement cycles. Macroeconomic contraction, autonomous landing technology breakthrough, or prescriptive regulatory expansion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Light Electric Aircraft Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Aero Wing Market
Aircraft
Aircraft Window Frame Market
Aircraft
Active Air Deflector Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
General Aviation Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Sailplane Market
Aircraft
Latin America General Aviation Market
Aircraft
Middle-East Aviation Market
Aircraft
Helicopter Flight Management System Market