
 Firefighting Aircraft Market | 2026-2036
Firefighting Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Firefighting Aircraft Market Analysis
Municipal fire department procurement is expanding across drought-prone jurisdictions seeking dedicated aerial suppression capability rather than seasonal contract reliance. Lockheed Martin leverages its C-130 platform heritage to sustain long-cycle military-to-civilian conversion programs for aerial firefighting operators. Airbus competes through its multi-role tanker architecture, while Conair Group specializes in aftermarket conversion of regional airframes into firefighting configurations.
Firefighting aircraft are purpose-modified or purpose-built aerial vehicles engineered to deliver water, foam, or retardant payloads across wildland-urban interface zones, typically incorporating reinforced fuselage structures and gravity or pressurized drop systems rated for low-altitude, high-G flight profiles. Fixed-wing platforms dominate operational deployment for large-area coverage, while helicopter segments command premium positioning in precision initial attack and night-flying missions. Heavy and ultra-heavy aircraft size classes anchor capital expenditure pools, though light segments attract growing interest from rural districts with constrained apron infrastructure.
The FAA governs supplemental type certificate requirements for aerial firefighting modifications, while EASA enforces REACH-aligned restrictions on chemical retardant compositions entering European watersheds. The EPA regulates retardant toxicity thresholds under the Clean Water Act, directly influencing formulation chemistry and supplier qualification. Stakeholders must monitor evolving state-level aviation procurement mandates and retardant environmental litigation that could accelerate fleet electrification roadmaps or restrict operational windows in sensitive ecological zones.
Market Dynamics
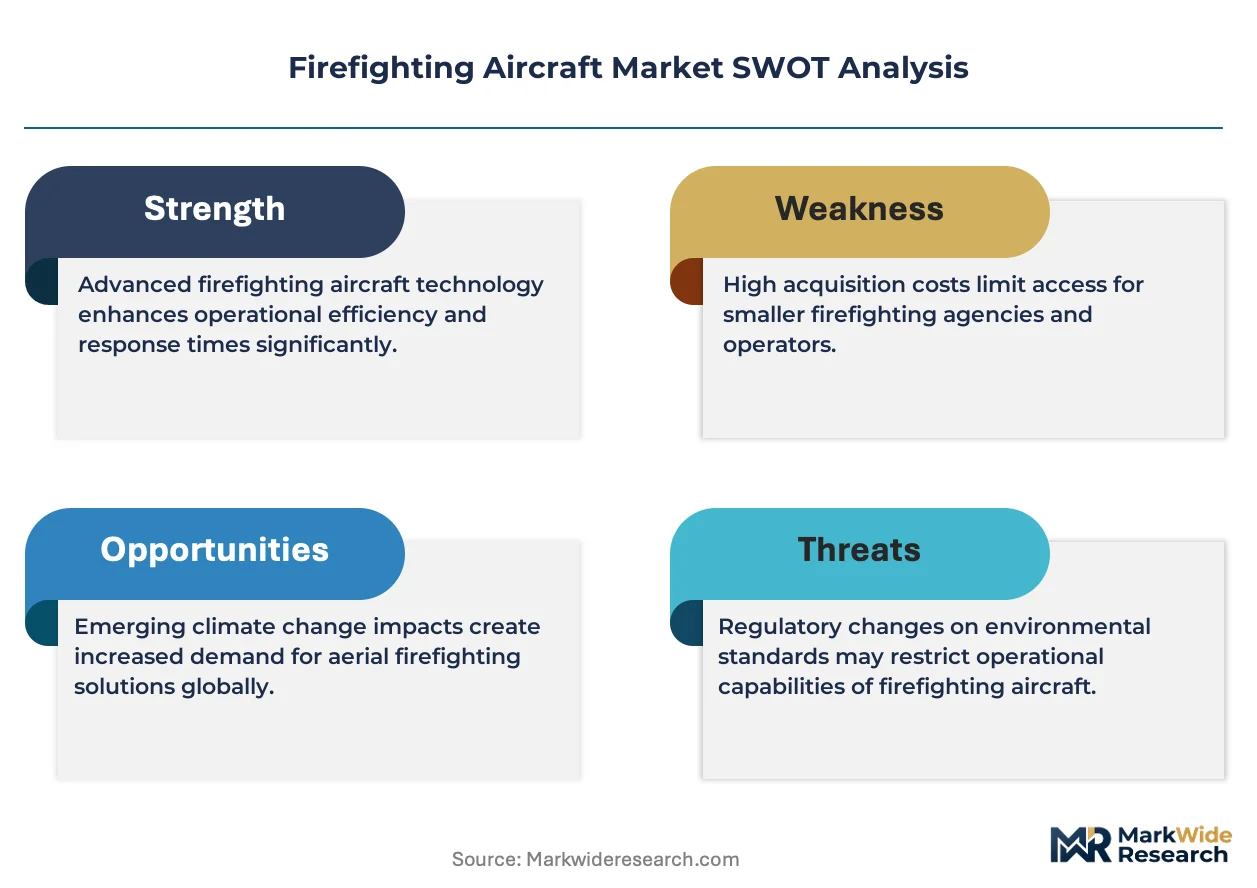
Climate-intensified wildfire seasons are compressing procurement cycles for aerial firefighting assets, forcing municipal agencies to abandon seasonal contract models in favor of dedicated fleet ownership and multi-year platform commitments.
Growth Catalysts
- Extended Fire Seasons:State aviation units in California, Oregon, and Washington are acquiring permanent aerial suppression capability rather than relying on federal interagency dispatch. This institutionalizes capital expenditure flows.
- REACH-Aligned Retardant Reformulation:EASA restrictions on chemical compositions entering European watersheds are accelerating R&D investment in biodegradable retardant chemistry, creating supplier qualification opportunities for compliant formulations.
- Low-Altitude Flight Certification:FAA supplemental type certificate streamlining for firefighting modifications is reducing airframe conversion timelines, enabling faster fleet refresh cycles for regional operators.
Market Restraints
- Airframe Supply Concentration:Conversion-ready military surplus platforms concentrate with Lockheed Martin C-130 and De Havilland Canada Dash 8 families, creating single-source dependency for heavy-class capacity expansion.
- Retardant Input Volatility:Ammonium phosphate and guar gum feedstock prices fluctuate with agricultural commodity cycles, pressuring operational cost predictability for aerial application contractors.
- Emissions Compliance Friction:FAA and EASA carbon intensity benchmarks for commercial aviation are tightening operational windows for legacy turboprop fleets, threatening airframe economic life extensions.
Strategic Opportunities
- Rural District Infrastructure Gap:Constrained apron infrastructure in Montana, Idaho, and Colorado counties is creating demand for short-takeoff light aircraft configurations that bypass heavy runway requirements.
- Hybrid-Electric Propulsion Convergence:Battery-electric auxiliary power integrated with turbine cores is absorbing development investment from NASA and FAA demonstration programs, promising reduced thermal signature and night-flying capability.
- California SB-85 Procurement Mandate:State-level aviation asset acquisition targets for Cal Fire are creating dedicated funding streams independent of federal appropriation cycles, insulating order flow from congressional volatility.
Industry Challenges
- Airworthiness Certification Timeline:FAA supplemental type certificate approval for gravity-drop system modifications averages 18-24 months, compressing revenue realization for conversion specialists.
- Pilot Specialization Scarcity:Low-altitude, high-G firefighting flight profiles demand specific instrument ratings and terrain-following certification that general commercial aviation training pipelines do not produce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firefighting Aircraft Market |
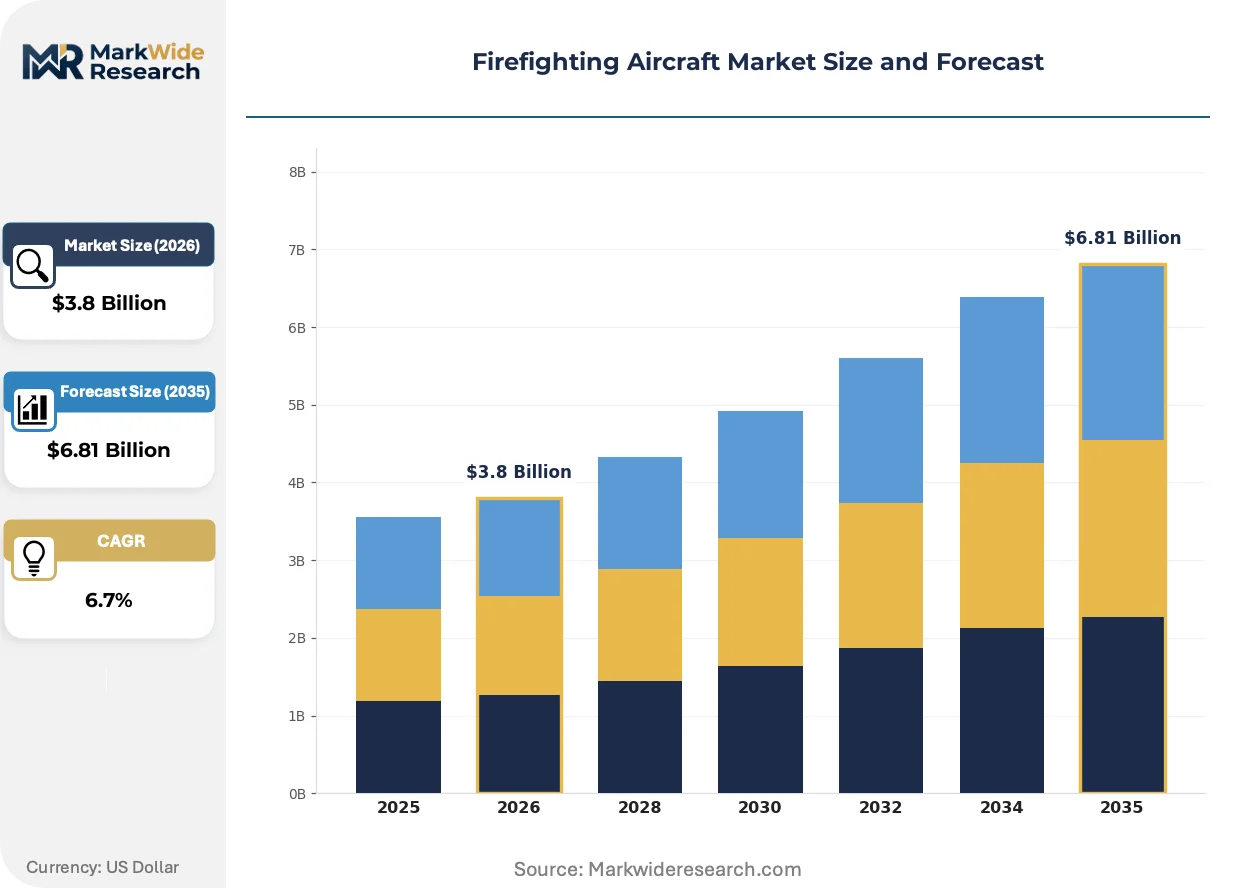
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aerial Platform Type: Fixed-Wing, Helicopter, Drone, Amphibious Aircraft Size: Light, Medium, Heavy, Ultra-Heavy Delivery Mechanism: Water Droplet, Foam Dispenser, Retardant Shooter, Airtank End User: Government Agencies, Private Companies, NGOs, Fire Departments |
| Companies Covered | Lockheed Martin Corporation, Airbus SE, Textron Inc., Air Tractor, Inc., Bombardier Inc., Leonardo S.p.A., Conair Group Inc., De Havilland Aircraft of Canada Limited, Neptune Aviation Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firefighting Aircraft Market Emerging Trajectories
Digital mission management and autonomous drop coordination are displacing manual flight crew judgment in aerial suppression operations, restructuring fleet capability requirements and operator training investments.
Modular tank systems with rapid reconfiguration between water, foam, and retardant payloads are absorbing design priority from airframe modifiers. State aviation units in Australia and Spain are specifying these systems for multi-mission flexibility. The technology is absorbing capital allocation from fixed single-purpose tank architectures, compressing the addressable market for dedicated retardant-only platforms.
EPA Clean Water Act enforcement on retardant toxicity thresholds is tightening formulation chemistry standards, forcing suppliers to eliminate sodium ferrocyanide corrosion inhibitors. Aerial application contractors in the western United States are reformulating under EPA oversight, while European operators face parallel ECHA substance restriction timelines. The regulatory convergence is compressing supplier margins and consolidating qualification toward integrated chemical-airframe service providers.
California's shift from federal cost-share agreements to direct state procurement of exclusive-use aircraft is restructuring contract structures. Municipal fire departments are bypassing seasonal call-when-needed arrangements for guaranteed availability contracts with embedded crew and maintenance provisions. This behavioral pivot is most visible in Cal Fire's aviation unit expansion, where dedicated heavy helicopter and air tanker fleets now operate under state-controlled dispatch protocols rather than interagency coordination frameworks.
Firefighting Aircraft Market Segmentation
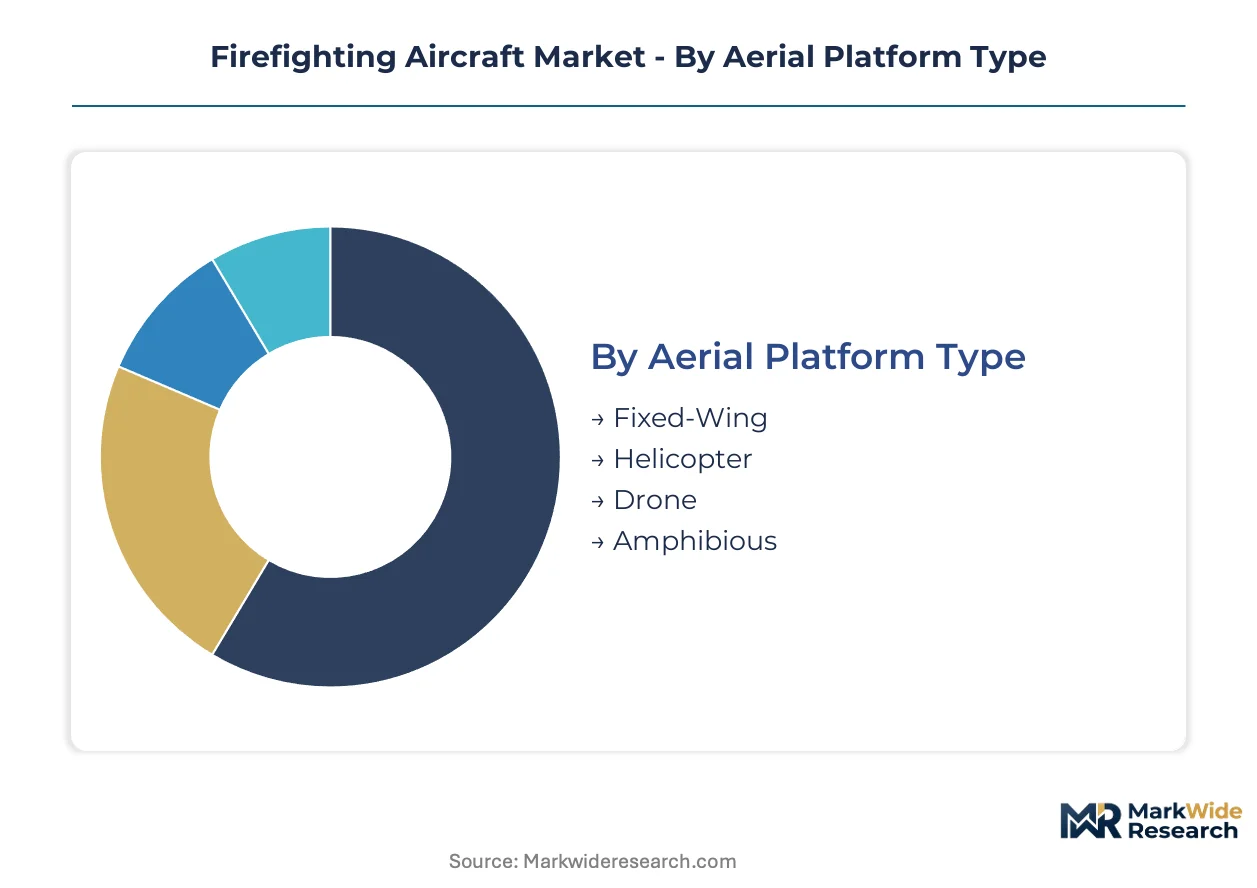
Firefighting aircraft segmentation reveals distinct procurement patterns between integrated fleet systems and standalone asset deployment. Platform architecture, payload capacity, and institutional buyer type collectively determine operational economics and regulatory compliance pathways across aerial suppression markets.
Aerial Platform Type:
Integration depth varies sharply across platform categories, with fixed-wing assets embedding into multi-airframe coordinated systems while drones operate as standalone sensor-drop nodes.
- Fixed-Wing:These platforms incorporate reinforced wing structures and gravity-fed tank systems rated for low-altitude retardant release across extended wildland perimeters. Demand concentrates in California and Oregon state aviation units seeking large-area coverage capacity independent of federal dispatch timelines.
- Helicopter:Rotary-wing configurations enable precision bucket operations and night-flying missions through thermal signature management. Procurement is accelerating among municipal fire departments in Washington and Colorado counties requiring initial attack capability in steep terrain inaccessible to fixed-wing assets.
- Drone:Unmanned systems deploy as standalone reconnaissance and incendiary monitoring platforms with modular drop payloads under 50 gallons.
- Amphibious:Water-scooping hull designs integrate lake and reservoir access for continuous operation without ground-based tanker support.
Volume placements concentrate in Fixed-Wing; the faster expansion belongs to Helicopter as night-flying certification spreads.
Aircraft Size:
Cost tier stratification separates capital-intensive ultra-heavy procurement from operational expenditure-driven light segment leasing.
- Heavy:Platforms exceeding 12,000-gallon retardant capacity anchor state-level fleet modernization programs through exclusive-use contracts. California SB-85 procurement mandates direct funding toward this segment, insulating order flow from federal appropriation volatility.
- Ultra-Heavy:These configurations exceed 20,000-gallon thresholds and require extended runway infrastructure available only at major air tanker bases.
- Medium:3,000-8,000-gallon capacity suits regional cooperative agreements between adjacent counties.
- Light:Short-takeoff configurations under 3,000 gallons address Montana and Idaho rural districts with constrained apron infrastructure.
Capital deployment concentrates in Heavy; Light aircraft are climbing the fastest as county-level procurement accelerates.
Delivery Mechanism:
Application specificity determines whether mechanisms embed in multi-mission tank architectures or serve dedicated single-purpose roles.
- Retardant Shooter:Pressurized systems enable targeted line construction through variable-flow nozzles calibrated for wind conditions and fuel type. EASA REACH-aligned restrictions on chemical compositions are accelerating R&D investment in biodegradable formulations compatible with these pressurized delivery systems.
- Water Droplet:Gravity-fed tank releases dominate initial attack protocols for structure protection in wildland-urban interface zones.
- Foam Dispenser:Aerated concentrate systems embed in modular tank configurations for rapid reconfiguration between mission types.
- Airtank:Conventional gravity-drop systems remain standard for large-area coverage operations across federal interagency frameworks.
Operational hours concentrate in Airtank; Retardant Shooter systems are gaining share fastest as precision requirements intensify.
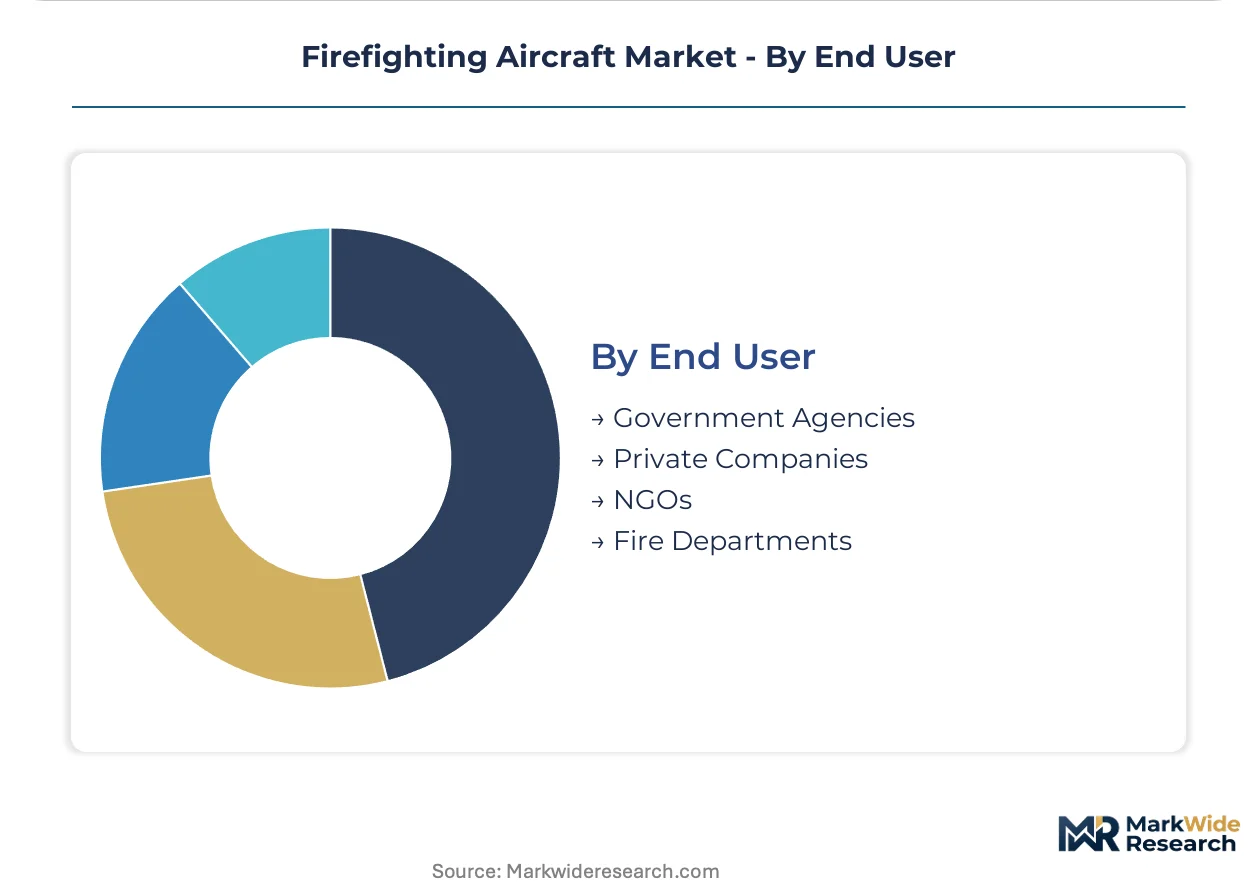
End User:
Customer type segmentation separates sovereign procurement with embedded maintenance crews from commercial contract operators supplying call-when-needed capacity.
- Government Agencies:Federal and state aviation units procure under multi-year exclusive-use agreements with guaranteed availability clauses. Cal Fire's direct state-controlled dispatch protocols now bypass interagency coordination frameworks, restructuring contract structures toward embedded crew and maintenance provisions.
- Fire Departments:Municipal agencies in drought-prone jurisdictions are abandoning seasonal contract models for dedicated fleet ownership.
- Private Companies:Aerial application contractors supply surge capacity under call-when-needed arrangements with variable cost structures.
- NGOs:Non-governmental operators concentrate in international deployment and training assistance programs.
Procurement volume concentrates in Government Agencies; Fire Departments show the steepest expansion trajectory as municipal ownership models institutionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Conversion-ready airframe supply concentrates in North American and European manufacturing clusters, while procurement demand intensifies across drought-prone jurisdictions in the western United States, Mediterranean Europe, and fire-prone Australian states.
United States
State aviation units in California, Oregon, and Washington are acquiring permanent aerial suppression capability rather than relying on federal interagency dispatch. FAA supplemental type certificate requirements govern airframe modifications for aerial firefighting operations. Cal Fire's aviation unit expansion in Sacramento anchors the heaviest concentration of state-controlled heavy helicopter and air tanker fleets.
Canada
De Havilland Aircraft of Canada Limited sustains regional airframe conversion programs for North American operators seeking Dash 8 platforms. Transport Canada certification alignment with FAA standards facilitates cross-border fleet mobility. British Columbia and Alberta provincial aviation units in Vancouver and Calgary coordinate aerial suppression capacity across the Pacific Northwest fire complex.
France
Airbus SE leverages multi-role tanker architecture to compete in European aerial firefighting procurement cycles. EASA REACH-aligned restrictions on chemical retardant compositions entering watersheds reshape formulation chemistry standards. The Provence-Alpes-Côte d'Azur region around Marseille hosts concentrated state fleet operations for Mediterranean wildland-urban interface protection.
Italy
Leonardo S.p.A. maintains rotary-wing production lines serving European and export markets for precision initial attack missions. National fire service procurement under Italy's civil protection framework institutionalizes multi-year platform commitments. The Lazio region surrounding Rome coordinates aerial assets across central Italian fire districts with steep terrain requirements.
Australia
State aviation units in New South Wales and Victoria specify modular tank systems for multi-mission flexibility between water, foam, and retardant payloads. The country's national aviation regulator enforces low-altitude flight certification standards for terrain-following operations. Sydney and Melbourne anchor the eastern seaboard's concentrated aerial suppression infrastructure for extended fire seasons.
Firefighting Aircraft Market Vendor Landscape
Top-tier vendors anchor platform manufacturing and military-to-civilian conversion programs, while mid-tier specialists concentrate on aftermarket airframe modification and regional operator support. The competitive structure exhibits dual concentration around aerospace primes with legacy military transport heritage and dedicated aerial firefighting conversion houses. Three strategic archetypes dominate: military platform converters, multi-role commercial aircraft manufacturers, and specialized aerial application modifiers. Consolidation pressure manifests through exclusive-use contract capture and airframe supply chain integration.
Within the military heritage converter tier, Lockheed Martin Corporation exemplifies long-cycle C-130 platform sustainment for aerial firefighting operators. Airbus SE occupies a position bridging multi-role tanker commercial aviation with modular firefighting configurations. Among dedicated conversion specialists, Conair Group Inc. represents the aftermarket modification archetype for regional airframe transformation.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Airbus SE |
| Textron Inc. |
| Air Tractor, Inc. |
| Bombardier Inc. |
| Leonardo S.p.A. |
| Conair Group Inc. |
| De Havilland Aircraft of Canada Limited |
| Neptune Aviation Services |
| Others |
Supply Flow & Price Mechanics
Ammonium phosphate and guar gum feedstock costs flow from agricultural commodity markets through to aerial application contractor pricing tiers, with heavy-class platform operators absorbing volatility while municipal buyers lock in multi-year exclusive-use contracts to stabilize unit economics.
Pricing Analysis
Margin tightening in light aircraft configurations reflects constrained apron infrastructure premiums across Montana and Idaho rural districts. Three-tier pricing structure across exclusive-use contracts, call-when-needed arrangements, and dry-lease bare airframes separates state aviation units from municipal fire departments and commercial surge operators. Certification investment for FAA supplemental type certificates drives price differentiation between conversion-ready military surplus platforms and new-production multi-role architectures. Buyer price sensitivity concentrates among county-level procurement officers with fixed capital budgets, while Cal Fire's SB-85 mandate insulates heavy-class segment demand from congressional appropriation volatility.
Supply Chain Analysis
FAA supplemental type certificate approval timelines gating airframe modification programs extend 18-24 months, compressing revenue realization for conversion specialists and consolidating supplier qualification toward integrated chemical-airframe service providers. Conversion-ready military surplus concentrates in United States C-130 platforms and Canadian Dash 8 families, with raw material dependencies spanning aluminum airframe structures, turbine engine cores, and REACH-compliant retardant formulations. Single-source vulnerability in heavy-class capacity expansion threatens fleet modernization timelines for state aviation units. Distribution runs through exclusive-use contract channels with embedded crew and maintenance provisions rather than spot-market spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play as emissions compliance friction and airworthiness certification timelines force smaller conversion specialists toward acquisition or exit.
For Market Incumbents: Cement airframe supply chain integration through captive conversion capacity or long-term platform access agreements with military surplus disposition programs. FAA carbon intensity benchmarks threaten legacy turboprop fleet economic life extensions; prioritize hybrid-electric propulsion R&D partnerships with NASA demonstration programs to defend positioning against emerging clean-sheet entrants. For New Entrants and Emerging Players: California SB-85 procurement mandate in the United States opens a window for short-takeoff light aircraft specialists targeting Montana and Idaho rural districts with constrained apron infrastructure. EASA REACH-aligned retardant reformulation requirements in Europe create supplier qualification opportunities for biodegradable chemistry innovators. Pursue direct county-level relationships bypassing federal interagency dispatch frameworks as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Cal Fire's shift from federal cost-share agreements to direct state procurement is the leading indicator that exclusive-use contract structures with embedded crew provisions will dominate capital deployment across drought-prone jurisdictions. Target aftermarket conversion specialists with established FAA supplemental type certificate portfolios and existing military surplus platform relationships. Watch for state-level aviation asset acquisition targets decoupled from federal appropriation cycles as the inflection signal for order flow insulation.| Strategic Initiative | Industry Significance |
|---|---|
| Military Surplus Platform Access Agreement | Secures conversion-ready C-130 and Dash 8 airframes for long-cycle modification programs. |
| Hybrid-Electric Propulsion Partnership | Positions operators for FAA night-flying certification through reduced thermal signature aircraft. |
| Biodegradable Retardant Formulation Investment | Qualifies suppliers for EASA REACH-aligned restrictions entering European watersheds. |
| Exclusive-Use Contract Capture | Institutionalizes Cal Fire-style state-controlled dispatch protocols with embedded maintenance. |
| Modular Tank System Development | Enables rapid reconfiguration between water, foam, and retardant for multi-mission flexibility. |
Methodological Framework
Independent corroboration across conversion program managers at Lockheed Martin and De Havilland Canada, aerial application contractor operations directors, and Cal Fire aviation unit procurement officers underwrites the qualitative findings. Secondary validation draws from FAA supplemental type certificate filings, EPA Clean Water Act enforcement actions on retardant toxicity, EASA REACH substance restriction timelines, and state aviation unit budget appropriations. Bottom-up airframe deployment counts triangulate against top-down market value estimates across the analysis window.
Comparable-period anchoring to historical fire season intensity and state procurement cycle timing structures the forecast framework. Segmentation dimensions span aerial platform type, aircraft size class, delivery mechanism, and end-user procurement model, with hybrid-electric propulsion adoption curves and retardant formulation regulatory compliance timelines as industry-specific forecast inputs. CAGRs derive from unit placement trajectories and average contract value expansion across the projection horizon.
The model assumes a particular technology adoption path for battery-electric auxiliary power integration; alternative pathways for turbine-core hybrid architectures or full-electric platforms would alter the outlook. Forecasts reflect assumptions regarding fire season length extension, state-level procurement mandate durability, and airframe conversion timeline compression. A model refresh is warranted upon material change in FAA emissions compliance benchmarks or EASA retardant formulation restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aerospace Winglet System Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Aircraft Oxygen System Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Global Helicopter Market