
 Citrus Gummies Market | 2026-2036
Citrus Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Gummies Market Outlook
Premium functional tier is bifurcating the citrus gummies landscape as consumers trade up from basic confectionery to clinically positioned supplements. Nordic Naturals leverages its marine-sourced nutrient heritage to anchor credibility in the adult wellness segment. Goli Nutrition Inc competes through aggressive direct-to-consumer channel control and apple cider vinegar hybrid positioning. Herbaland Naturals Inc specializes in pectin-based vegan formulations that differentiate its offering from gelatin-dependent competitors.
Citrus gummies denote chewable confectionery or supplement matrices incorporating citrus-derived bioactive compounds, typically manufactured via starch molding or depositing processes with controlled moisture content below 15 percent to ensure shelf stability. Their primary commercial purpose spans both recreational snacking and targeted nutrient delivery, with functional variants incorporating vitamin C, citrus bioflavonoids, or fiber additives. The functional product type currently leads volume contribution as athletes and dietary supplement users migrate from pills to palatable delivery formats. Sugar-free formulations command margin concentration due to stevia and monk fruit sweetener premiums, while pectin-based vegan alternatives displace gelatin across European and North American health food stores.
The FDA oversees structure-function claims and good manufacturing practice compliance for citrus gummies sold as dietary supplements in the United States, while EFSA evaluates health claim substantiation across EU member states where the MDR and novel food regulations constrain rapid product iteration. India's FSSAI has tightened labeling requirements for imported functional confectionery, creating additional testing burdens for brands targeting its emerging middle class. Stakeholders must monitor evolving cross-jurisdictional claim standards to determine whether regional formulation customization or unified global recipes offer superior risk-adjusted returns.
Market Dynamics
The clean-label pivot across North America and Europe is compressing formulation cycles as manufacturers reformulate around pectin bases and natural sweeteners to preempt regulatory tightening.
Growth Catalysts
- EFSA Novel Food Pathway:Accelerated approval timelines for citrus bioflavonoid isolates enable faster functional claim substantiation in EU markets.
- Athlete Segment Migration:Endurance sports practitioners in Germany and Australia switch from effervescent tablets to chewable vitamin C delivery for gastric tolerance.
- Starch Molding Automation:Servo-controlled depositing lines cut moisture variance below 2 percent, extending shelf stability without synthetic preservatives.
Market Restraints
- Monk Fruit Concentrate Volatility:Supply concentrates in Guangxi Province, exposing margin structures to climate-induced harvest fluctuations.
- Gelatin Reputational Risk:Bovine and porcine sourcing triggers clean-label disqualification in vegan-dominant retail channels across Scandinavia.
- FSSAI Import Testing Burden:India's mandatory heavy metal screening adds 6-8 week clearance delays for functional confectionery entrants.
Strategic Opportunities
- Brazil ANVISA Harmonization:Pending alignment with FDA structure-function claim standards opens pathway for US-formulated products.
- Pediatric Iron-Fortified Lines:Bioavailability-enhanced citrus matrices address deficiency rates in Indonesian urban centers.
- Direct-to-Clinic Sampling:Dietitian channel bypasses retail slotting fees for clinical-grade positioning in Canadian provinces.
Industry Challenges
- Pectin Rheology Expertise Gap:Gel strength calibration for tropical climates requires specialized food polymer chemists in short supply.
- Dual Certification Timelines:Simultaneous USDA Organic and Non-GMO Project verification extends launch windows by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Gummies Market |
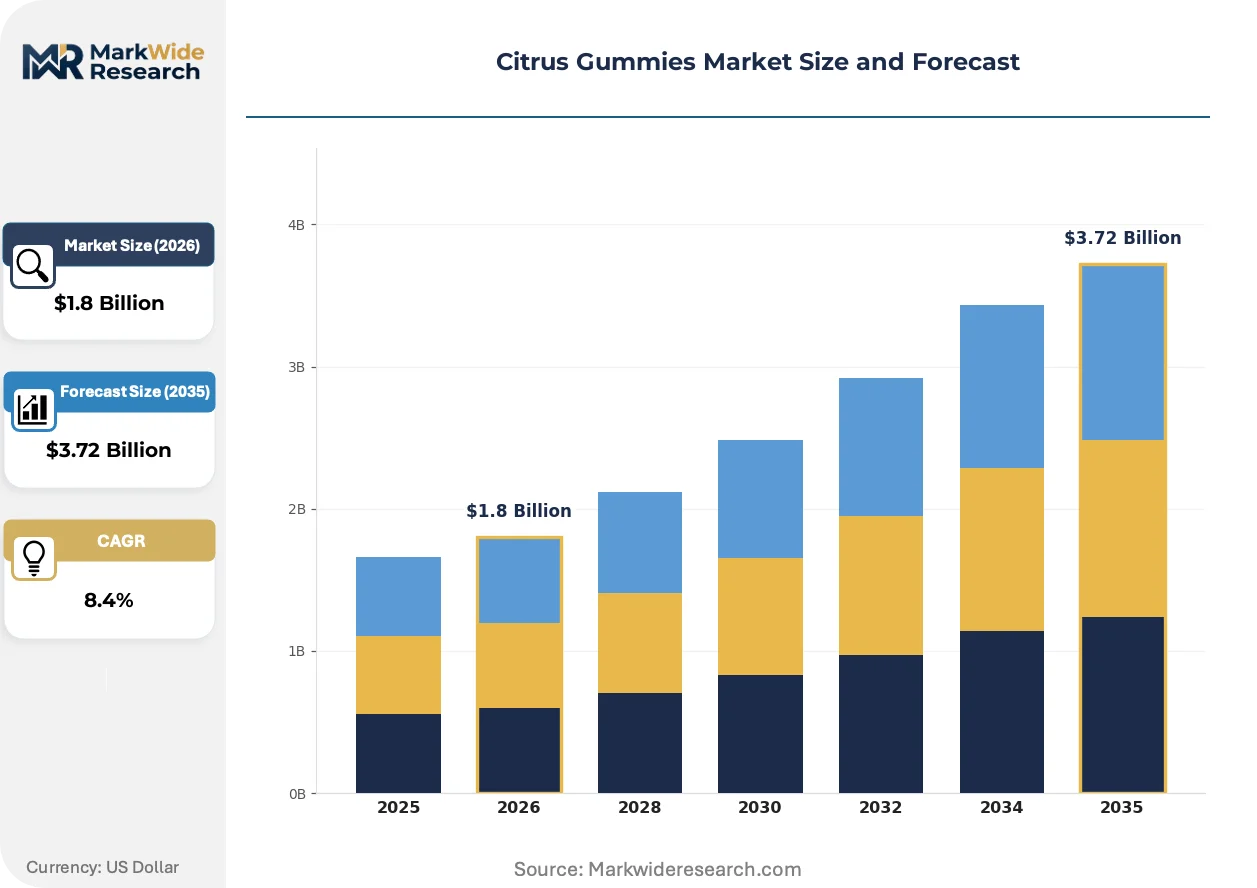
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegan, Sugar-Free, Functional, Regular Ingredients: Citrus Extracts, Gelatin, Pectin, Natural Sweeteners Distribution Channel: Supermarkets, Online Stores, Health Food Stores, Pharmacies Target Audience: Health-Conscious Consumers, Kids, Athletes, Dietary Supplement Users |
| Companies Covered | Nutranext LLC, Hero Nutritionals LLC, Herbaland Naturals Inc, Zanon Vitamec, Pfizer Inc, Nature's Way, Nordic Naturals, Goli Nutrition Inc, Ferrara Candy Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Gummies Market Strategic Shifts
Formulation science is converging with precision nutrition as manufacturers engineer release profiles and bioavailability markers previously reserved for pharmaceutical applications.
Microencapsulation of heat-sensitive citrus flavonoids using lipid-shell technology protects active compounds through starch molding temperatures above 80°C. Adult wellness brands in California and Bavaria adopt these systems for shelf-stable probiotic-citrus hybrids. The technology is decomposing the traditional barrier between confectionery processing and pharmaceutical-grade stability requirements.
REACH restrictions on titanium dioxide whitening agents force reformulation toward calcium carbonate and rice starch alternatives across EU manufacturing facilities. EFSA's 2021 reclassification of TiO2 as a suspected carcinogen triggered immediate recipe changes in gummy coatings and opacity layers. French and Italian producers now lead conversion to mineral-free appearance standards, pressuring export-dependent competitors to match.
Subscription-based replenishment models displace impulse purchasing in the United States as consumers automate monthly vitamin C and immunity protocol deliveries. Direct-to-consumer platforms capture patient data that informs personalized dosage recommendations, shifting value from product margin to adherence analytics. This behavioral pivot concentrates in coastal metropolitan markets where healthcare cost sensitivity drives preventive spending.
Citrus Gummies Market Segmentation
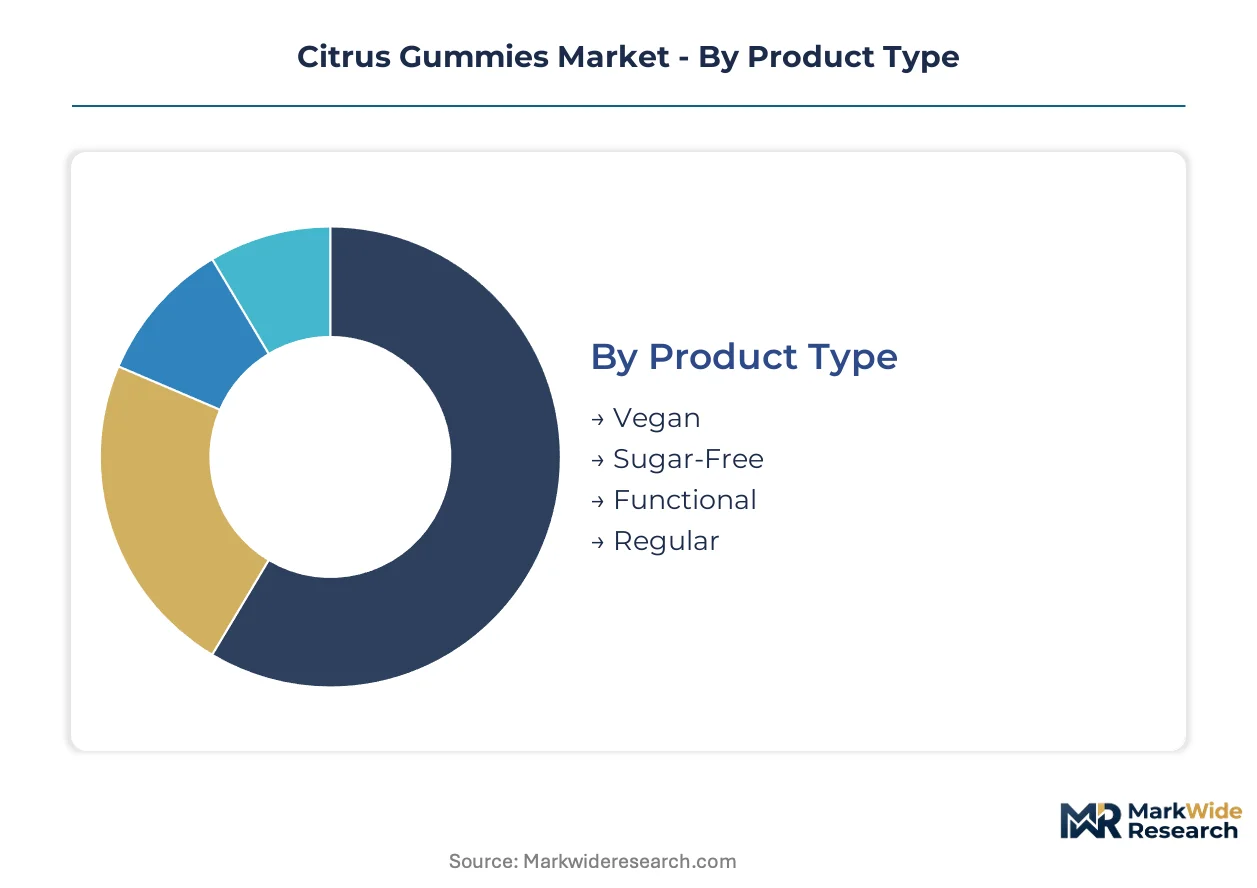
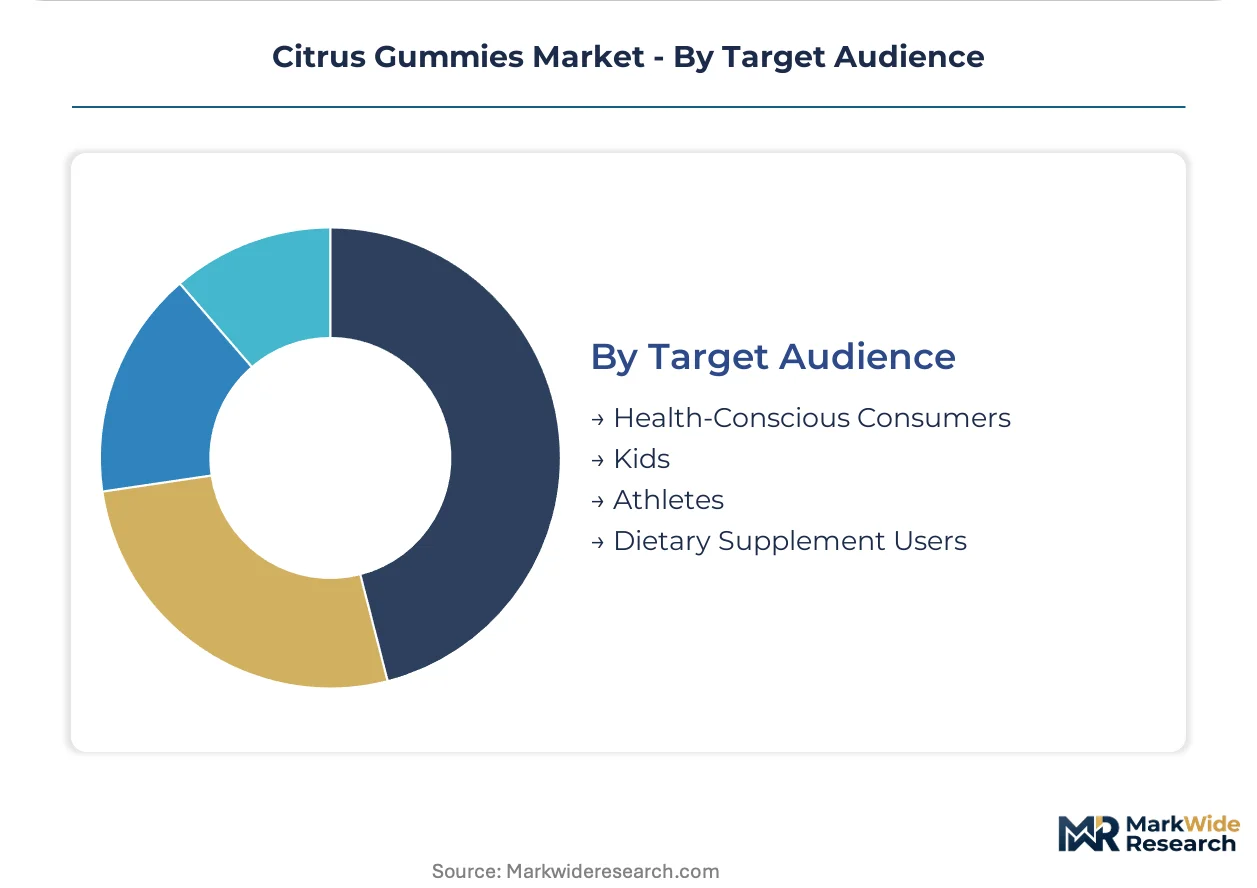
Citrus gummies segment along four distinct axes that determine channel strategy and margin architecture. Product type and ingredient composition dictate regulatory pathway and manufacturing investment, while distribution channel and target audience shape pricing power and customer acquisition costs.
Product Type:
Channel-mix dynamics vary sharply across product tiers, with functional and vegan variants commanding premium placement in health food stores and pharmacies while regular formulations dominate supermarket impulse aisles.
- Functional:Clinically positioned formulations incorporate bioactive dosages of vitamin C, citrus bioflavonoids, or fiber matrices. Athletes in Germany and dietary supplement users across California drive demand as gastric tolerance concerns displace effervescent tablets. EFSA structure-function claim substantiation requirements extend launch timelines but protect margin premiums.
- Vegan:Pectin-based matrices replace gelatin to access Scandinavian retail channels where bovine and porcine sourcing triggers clean-label disqualification. Pectin rheology expertise gaps constrain supply expansion in tropical climates where gel strength calibration demands specialized food polymer chemists.
- Sugar-Free:Stevia and monk fruit formulations target diabetes-conscious segments and ketogenic diet adherents.
- Regular:Conventional sucrose-based confectionery occupies mass-market price tiers with minimal functional positioning.
By volume, regular formulations lead. By growth pace, functional variants are expanding most quickly.
Ingredients:
Cost tier stratification runs from commodity gelatin inputs to certified organic citrus extracts, with natural sweetener premiums compressing mid-tier margins.
- Citrus Extracts:Concentrated bioflavonoid isolates and cold-pressed peel oils constitute the primary active ingredient class. Microencapsulation using lipid-shell technology protects heat-sensitive compounds through starch molding temperatures above 80°C, enabling probiotic-citrus hybrid stability previously reserved for pharmaceutical applications.
- Pectin:Citrus-derived and apple-sourced gelling agents enable vegan certification and clean-label positioning. REACH restrictions on titanium dioxide force reformulation toward calcium carbonate and rice starch alternatives, pressuring EU manufacturers to convert opacity layers.
- Gelatin:Bovine and porcine collagen hydrolysates retain cost advantages but face reputational exclusion from vegan-dominant channels.
- Natural Sweeteners:Monk fruit concentrate supply concentrates in Guangxi Province, exposing margin structures to climate-induced harvest fluctuations.
Pectin inputs command the steepest price escalation trajectory, while gelatin remains the cost baseline.
Distribution Channel:
Customer type determines channel priority, with athletes and supplement users gravitating toward pharmacies and health food stores while parents purchase kids' formulations through supermarkets.
- Pharmacies:Clinical-grade positioning requires FDA structure-function claim compliance or EFSA health claim substantiation. Direct-to-clinic sampling in Canadian provinces bypasses retail slotting fees for dietitian channel penetration.
- Online Stores:Subscription-based replenishment models capture patient adherence data that informs personalized dosage recommendations, shifting value from product margin to analytics services.
- Health Food Stores:Clean-label certification gates entry, with dual USDA Organic and Non-GMO Project verification extending launch windows.
- Supermarkets:Impulse placement depends on velocity guarantees and promotional fund commitments.
Online channels are gaining share fastest, though pharmacies retain the highest basket values.
Target Audience:
Application intensity separates recreational snacking from protocol-driven daily consumption, with the latter generating superior lifetime value metrics.
- Dietary Supplement Users:Pill-averse consumers seeking palatable nutrient delivery drive migration from tablets to chewable formats. FSSAI import testing burdens in India add 6-8 week clearance delays, complicating emerging market entry.
- Athletes:Endurance practitioners prioritize gastric tolerance and rapid absorption kinetics. Bioavailability-enhanced citrus matrices address iron deficiency protocols in Southeast Asian urban centers.
- Health-Conscious Consumers:Preventive spending concentrates in coastal US metropolitan markets where healthcare cost sensitivity automates monthly immunity protocol deliveries.
- Kids:Pediatric iron-fortified lines require taste-masking expertise and choking hazard compliance.
Dietary supplement users represent the largest addressable population, while athletes show the steepest per-capita consumption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangxi Province concentrates monk fruit concentrate supply, exposing margin structures to climate-induced harvest fluctuations. FDA structure-function claim oversight in the United States and EFSA health claim substantiation in Europe create divergent compliance burdens for multinational brands. Functional gummy demand clusters in coastal metropolitan markets across three continents.
United States
Health-conscious consumers in California and New York Metro drive premiumization in sugar-free and vegan subcategories. FDA oversees structure-function claims and good manufacturing practice compliance for dietary supplement positioning. Los Angeles-based wellness brands pioneer subscription-based replenishment models that capture patient adherence data.
Germany
Endurance athletes in Bavaria and North Rhine-Westphalia switch from effervescent tablets to chewable vitamin C delivery for gastric tolerance. EFSA evaluates health claim substantiation where MDR and novel food regulations constrain rapid product iteration. Munich clusters clinical-grade positioning expertise for pharmacy channel penetration.
India
Dietary supplement users in Maharashtra and Delhi-NCR migrate from pills to palatable delivery formats. FSSAI tightened labeling requirements for imported functional confectionery, creating 6-8 week clearance delays. Mumbai serves as the primary entry point for brands targeting the emerging middle class.
Brazil
Pending ANVISA harmonization with FDA structure-function claim standards opens pathway for US-formulated products. São Paulo anchors South American demand for pediatric iron-fortified lines addressing deficiency rates. Rio de Janeiro health food stores drive clean-label certification requirements for market entry.
Australia
TGA oversight shapes clinical-grade import standards for bioavailability-enhanced citrus matrices. Melbourne and Sydney concentrate athlete segment demand for rapid absorption kinetics. Brisbane manufacturers experiment with pectin rheology calibration for tropical climate shelf stability.
Citrus Gummies Market Competitive Environment
Concentration sits with mid-cap specialists possessing dual USDA Organic and Non-GMO Project certification capabilities. The vendor base spans pharmaceutical heritage players, marine-sourced nutrient specialists, and aggressive direct-to-consumer challengers. Three archetypes dominate: clinical-grade formulators, vegan-clean-label purists, and digitally native vertical brands. Competitive moves center on pectin formulation patents and dietitian channel bypass strategies that avoid retail slotting fees.
Within the clinical-grade tier, Nordic Naturals leverages marine-sourced heritage to anchor credibility in adult wellness positioning. Goli Nutrition Inc exemplifies direct-to-consumer channel control through hybrid functional-confectionery positioning. Herbaland Naturals Inc occupies the vegan-specialist archetype with pectin-based formulation expertise that differentiates from gelatin-dependent competitors.
| Leading Market Players |
|---|
| Nutranext LLC |
| Hero Nutritionals LLC |
| Herbaland Naturals Inc |
| Zanon Vitamec |
| Pfizer Inc |
| Nature's Way |
| Nordic Naturals |
| Goli Nutrition Inc |
| Ferrara Candy Company |
| Others |
Value Chain & Pricing Dynamics
Six-to-eight week FSSAI import clearance timelines compress working capital cycles for entrants targeting India, binding pricing power to inventory carrying capacity and supplier relationship depth in Guangxi Province monk fruit sourcing.
Pricing Analysis
EFSA Novel Food regulations dictate the pricing tier structure across European pharmacy channels, separating clinically substantiated functional gummies from confectionery-positioned alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with USDA Organic and Non-GMO Project verification commanding 40-60 point markups over conventional formulations. Cost compression in sugar-free tiers is intensifying because monk fruit concentrate harvest volatility in Guangxi Province exposes margin structures to climate-induced supply shocks. Dietary supplement users show lowest price sensitivity due to protocol-driven daily consumption habits, while mass-market impulse buyers in supermarket channels exhibit highest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian pectin raw material flows, with Indonesian citrus peel extraction and Thai tapioca starch derivatives feeding European and North American manufacturing networks. Supply concentrates in Guangxi Province for monk fruit, Yunnan for stevia cultivation, and Kerala for pectin from citrus waste streams, creating geographic clustering around tropical bioactive sourcing. Single-source vulnerability runs through Guangxi's climate-exposed harvest cycles, where drought or flood patterns transmit directly into input cost volatility. Distribution runs through direct-to-consumer subscription platforms for premium functional tiers, while mass-market regular formulations rely on supermarket broker networks and velocity-based slotting arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Citrus gummies sit in early-cycle expansion as athletes and dietary supplement users accelerate migration from pills to palatable delivery formats, with functional positioning still penetrating sub-15 percent of addressable supplement user households.
For Market Incumbents: Secure pectin formulation patents and captive supply relationships with Guangxi Province monk fruit processors before climate volatility triggers input cost spikes. Lock in dual USDA Organic and Non-GMO Project certification pipelines to extend competitive moats against gelatin-dependent challengers facing clean-label disqualification in Scandinavian retail channels. Channel control through direct-to-clinic sampling in Canadian provinces bypasses retail slotting fee erosion while capturing dietitian endorsement networks. For New Entrants and Emerging Players: USDA Organic fast-track certification unlocks health food store placement without 14-18 month dual verification delays that constrain mid-tier competitors. Pediatric iron-fortified lines in Indonesian urban centers offer the most penetrable white-space target, with bioavailability-enhanced citrus matrices addressing documented deficiency rates through taste-masked delivery. Direct-to-consumer launch with subscription-based replenishment models captures adherence analytics that inform personalized dosage recommendations and shift value toward data services. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-cap specialists with dual certification capabilities and pectin rheology expertise face acquisition pressure from pharmaceutical heritage players seeking functional confectionery entry. Target archetypes include vegan-formulation specialists with proven tropical climate gel strength calibration and established dietitian channel relationships. Signal to watch is ANVISA-FDA harmonization progress in Brazil, which would trigger immediate valuation step-ups for US-formulated product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Pectin Formulation Patent Filing | Protects gel strength calibration methods for tropical climate shelf stability against competitor replication. |
| Direct-to-Clinic Sampling Program | Bypasses retail slotting fees in Canadian provinces while securing dietitian endorsement for clinical-grade positioning. |
| Guangxi Province Supplier Integration | Captive monk fruit concentrate sourcing insulates margin structures from climate-induced harvest volatility exposure. |
| Pediatric Iron-Fortified Line Launch | Addresses deficiency rates in Indonesian urban centers through bioavailability-enhanced citrus matrix delivery systems. |
| Subscription Platform Data Monetization | Shifts value capture from product margin to adherence analytics services in coastal US metropolitan markets. |
Study Parameters
A spread of perspectives from brand managers at functional gummy manufacturers, category buyers at health food retailers, pharmacy procurement directors, pectin supply specialists, and regulatory affairs consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA structure-function claim filings, EFSA Novel Food approval databases, FSSAI import clearance records, and customs trade data on monk fruit concentrate flows. Bottom-up demand modeling from athlete segment consumption patterns and top-down market sizing from retail audit channels were triangulated to anchor volume estimates.
Segmentation dimensions modeled span product type tier, ingredient composition class, distribution channel format, and target audience archetype across the projection horizon. CAGRs were derived from adoption curve analysis of pill-to-gummy format migration rates, calibrated against EFSA approval timeline acceleration and starch molding automation penetration. Industry-specific forecast inputs include pectin rheology expertise scarcity indices and FSSAI clearance duration volatility bands.
Underlying assumptions cover sustained athlete segment migration from effervescent tablets, stable Guangxi Province monk fruit harvest yields, and EFSA Novel Food pathway efficiency, with deviation risk concentrated in climate-induced input cost spikes and regulatory harmonization delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Pralines Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
North America Marshmallow Market
Confectionery
Global Candy Market
Confectionery
US Confectionery Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Global Compound Chocolate Market
Confectionery
Cookie Dough Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
UK Chocolate Market