
 North America Chocolate Confectionery Market | 2026-2036
North America Chocolate Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chocolate Confectionery Market Insights
Market Context
E-commerce fulfillment networks are reshaping how chocolate confectionery reaches North American consumers, with direct-to-consumer platforms capturing share from traditional wholesale routes. The Hershey Company leverages its century-old manufacturing footprint to sustain volume leadership across mass retail channels. Lindt & Sprungli AG differentiates through premium positioning in airport duty-free and boutique formats. Mondelez International, Inc. anchors its North American portfolio with iconic brands that dominate seasonal merchandising cycles.
Product Definition and Segment Structure
Chocolate confectionery comprises cocoa mass, cocoa butter, sugar, and milk solids formulated into molded bars, enrobed pieces, and filled assortments, with tempering and conching processes determining final texture and shelf stability. Milk chocolate occupies the largest volume share across North American households, while dark chocolate commands premium shelf space as cocoa percentage claims attract health-conscious adult demographics. Online retail represents the fastest-expanding sales channel, though supermarkets retain decisive influence through end-cap displays and holiday promotional calendars. Bulk packaging serves foodservice and corporate gifting segments, whereas individual wrappers dominate convenience store impulse purchases.
Regulatory Environment and Outlook
The FDA enforces allergen labeling under FALCPA and monitors added-sugar declarations through updated Nutrition Facts panels, while USDA organic certification shapes ingredient sourcing for premium tiers. Health Canada and PMRA coordinate cross-border pesticide residue standards for imported cocoa beans, affecting supply chain compliance costs. Stakeholders must monitor evolving state-level sugar tax proposals and clean-label ingredient mandates that could redirect R&D spending toward alternative sweeteners and reduced-calorie formulations.
Market Dynamics
The FDA's updated Nutrition Facts panel mandating added-sugar disclosure is forcing reformulation across milk chocolate portfolios, compressing margins while accelerating clean-label R&D investment.
Growth Catalysts
- E-commerce fulfillment infrastructure:Direct-to-consumer platforms bypass traditional wholesale markups, capturing impulse purchases previously lost to convenience store distribution.
- Corporate hospitality procurement:Premium gifting assortments penetrate Fortune 500 procurement calendars, anchoring year-end volume spikes.
- USDA organic certification:Premium tier differentiation through certified sourcing commands shelf space in Northeast corridor specialty retail.
Market Restraints
- Cocoa butter price volatility:Weather-driven supply interruptions in West African origins compress margin stability for mass-market producers.
- FALCPA allergen labeling complexity:Cross-contamination protocols add facility segregation costs that disadvantage smaller contract manufacturers.
- Plant-based confectionery substitution:Oat milk and coconut cream alternatives attract lactose-intolerant demographics away from traditional milk chocolate.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring production to Monterrey and Toluca corridors reduces freight exposure to Panama Canal congestion.
- Airport duty-free channel penetration:Travel retail recovery post-2023 creates whitespace for premium positioning in Toronto Pearson and Dallas-Fort Worth hubs.
- State-level sugar tax preemption:Early reformulation to reduced-calorie profiles positions portfolios ahead of California and New York legislative momentum.
Industry Challenges
- Conching technician scarcity:Specialized tempering expertise retirement outpaces culinary school pipeline, constraining artisan capacity expansion.
- Legacy ERP integration friction:Batch traceability requirements for FDA compliance collide with decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chocolate Confectionery Market |
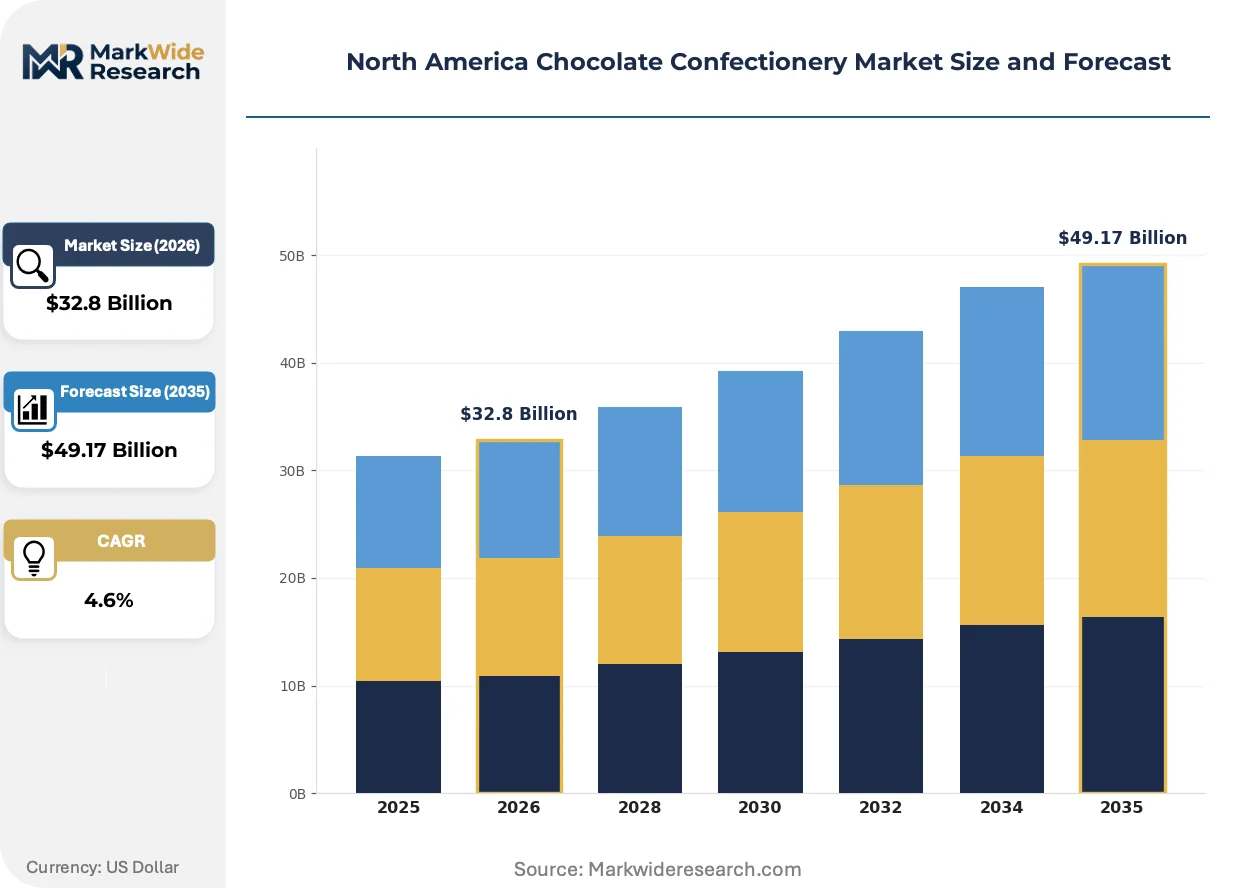
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Packaging Type: Box, Wrapper, Pouch, Bulk Sales Channel: Supermarket, Online Retail, Convenience Store, Specialty Store Consumer Demographics: Kids, Teens, Adults, Seniors |
| Companies Covered | Nestle S.A., Lindt & Sprungli AG, The Hershey Company, Ghirardelli Chocolate Company, The Barry Callebaut Group, Mars, Inc., Ferrero International S.A., Godiva, Mondelez International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chocolate Confectionery Market Trends and Innovations
Precision fermentation and alternative protein platforms are disrupting cocoa butter economics, while regulatory pressure on sugar content accelerates ingredient substitution R&D across North American manufacturing footprints.
Precision fermentation-derived cocoa butter substitutes are rendering obsolete traditional bean-to-bar supply dependencies. Mid-tier manufacturers in Pennsylvania and Ontario are piloting these lipids at commercial scale. The technology is compressing price volatility exposure while challenging terroir-based marketing claims.
The FDA's added-sugar line-item mandate on Nutrition Facts panels is forcing disclosure transparency across all retail formats. Reformulation timelines have compressed from 18-month cycles to 8-month sprints. Dark chocolate portfolios with existing lower-sugar positioning capture shelf space from legacy milk chocolate incumbents.
Subscription-based replenishment models are displacing seasonal impulse purchasing in household procurement. Direct-to-consumer platforms in the Northeast corridor now capture recurring revenue from pantry-stocking behavior. This shift concentrates customer lifetime value metrics while demanding flexible co-manufacturing capacity.
North America Chocolate Confectionery Market Segmentation
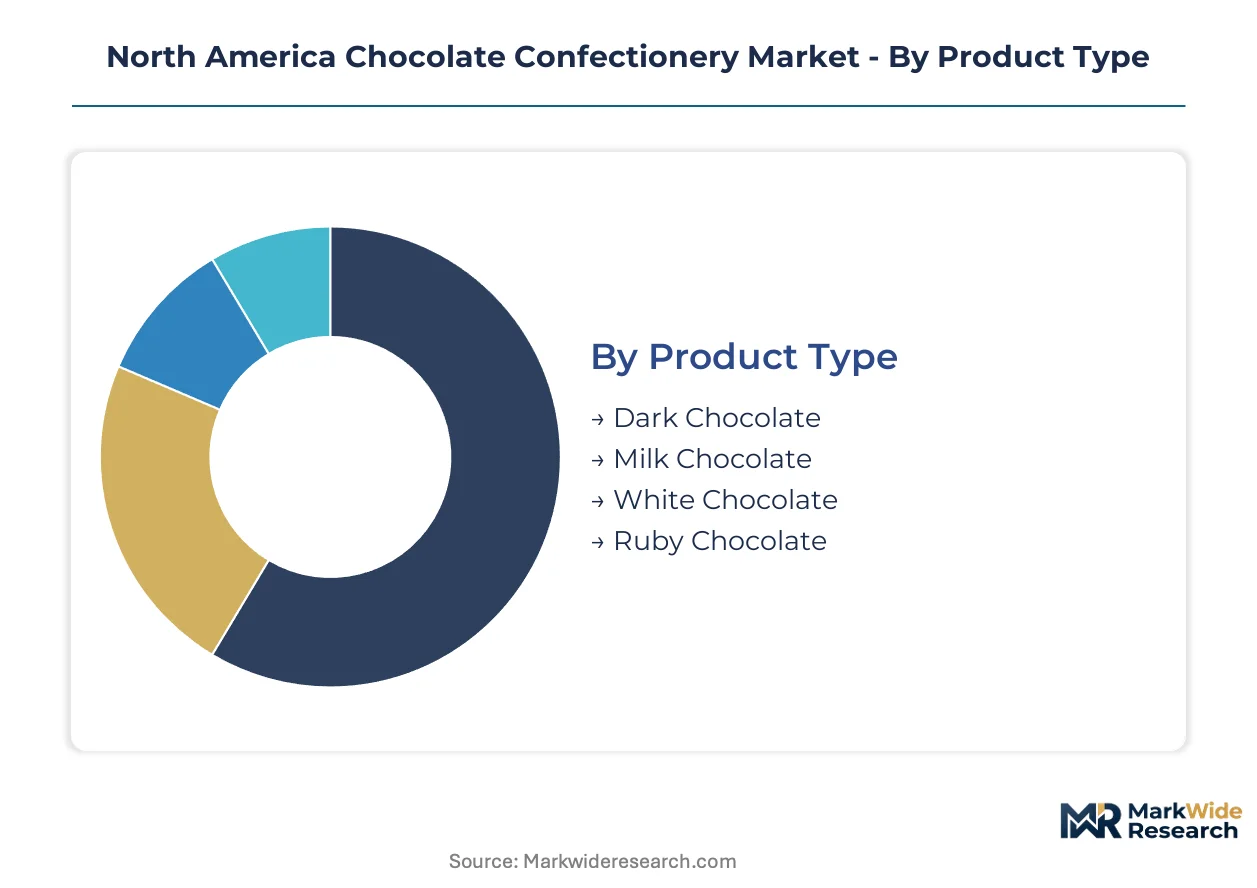
Segmentation reveals how formulation priorities, procurement rhythms, and channel economics diverge across the North America chocolate confectionery market. Cycle times vary dramatically—from impulse convenience purchases measured in hours to corporate gifting contracts negotiated across fiscal quarters.
Product Type:
Reformulation velocity separates the segments, with regulatory pressure on added-sugar disclosure compressing development timelines unevenly across cocoa percentages.
- Milk Chocolate:Formulated with cocoa solids below 50% combined with milk powder and higher sugar content. Household penetration concentrates in the Midwest's mass retail corridor, where FDA added-sugar labeling is forcing 8-month reformulation sprints versus traditional 18-month cycles.
- Dark Chocolate:Contains 50-90% cocoa mass with minimal milk solids and reduced sugar profiles. The Northeast corridor's specialty retail channel anchors demand, as existing lower-sugar positioning captures shelf space from legacy milk chocolate portfolios under disclosure mandates.
- White Chocolate:Cocoa butter base without cocoa solids, relying on milk powder and sugar for structure. Premium dessert applications in Canadian foodservice drive intermittent volume.
- Ruby Chocolate:Pink-hued variant from specific cocoa bean varieties with natural berry notes. Limited commercial scale in North American manufacturing constrains availability to boutique importers.
Milk chocolate dominates installed base. Dark chocolate is where expansion concentrates.
Packaging Type:
Cost tier alignment shapes procurement behavior, with premium formats commanding per-unit margins that offset lower velocity.
- Wrapper:Individual foil or paper enclosures for single-serve portions. Convenience store impulse purchases across the United States generate highest turnover velocity with lowest per-unit revenue.
- Box:Rigid or folding carton assemblies for assortments and gifting. Corporate hospitality procurement in the Northeast corridor drives year-end volume spikes with extended production lead times.
- Pouch:Flexible film structures for shareable formats and resealable consumption. Club store channels in Texas and California favor this format for pantry-stocking behavior.
- Bulk:Industrial totes and foodservice pails for manufacturing input or institutional foodservice. Bakery and ice cream manufacturing in Ontario and Pennsylvania anchor steady demand with contract-based purchasing.
Wrapper formats dominate unit volume. Box formats concentrate margin expansion.
Sales Channel:
Customer acquisition economics diverge sharply, with digital platforms displacing traditional wholesale markups while brick-and-mortar retains decisive influence through merchandising control.
- Supermarket:Grocery retail with end-cap displays and seasonal promotional calendars. Holiday merchandising cycles in the United States sustain volume leadership despite share erosion to digital channels.
- Online Retail:Direct-to-consumer platforms and third-party marketplace fulfillment. Subscription-based replenishment models in the Northeast corridor now capture recurring revenue from pantry-stocking behavior.
- Convenience Store:Small-format retail with impulse-oriented product placement. Single-serve wrapper formats dominate this channel with highest purchase frequency and lowest basket values.
- Specialty Store:Boutique confectioners and premium retail with curated assortments. Airport duty-free recovery post-2023 creates whitespace in Toronto Pearson and Dallas-Fort Worth hubs.
Supermarkets dominate installed base. Online retail is climbing the fastest.
Consumer Demographics:
Maturity gradients separate the segments, with aging cohorts driving premium migration while younger demographics anchor mass-market volume.
- Adults:Primary decision-makers for household procurement with health-conscious orientation toward dark chocolate and clean-label claims. The Northeast corridor's specialty retail concentration aligns with this demographic's premium willingness-to-pay.
- Kids:Gift-recipient and parental-purchase influence segment with preference for milk chocolate and character-licensed formats. Seasonal merchandising cycles concentrate volume in Halloween and Easter windows.
- Teens:Independent purchasing with social sharing behavior and price sensitivity. Convenience store channels capture this demographic's impulse-driven transaction patterns.
- Seniors:Reduced portion-size preference with functional benefit seeking around antioxidant claims and lower glycemic impact. Direct-to-consumer subscription models serve this segment's pantry-stocking reliability needs.
Adults dominate installed base. Seniors represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's container terminals anchor cocoa butter import flows into the United States, while the Laredo-Colombia Solidarity International Bridge channels finished confectionery southward into Mexican retail channels.
United States
Northeast corridor specialty retail drives premium dark chocolate adoption among health-conscious demographics. FDA's updated Nutrition Facts panel mandating added-sugar disclosure compresses reformulation timelines to eight-month cycles. Pennsylvania's Hershey manufacturing cluster sustains mass-market volume leadership through century-old conching infrastructure.
Canada
Toronto Pearson International Airport's duty-free recovery post-2023 creates whitespace for premium gifting assortments targeting corporate hospitality procurement. Health Canada and PMRA coordinate pesticide residue standards for imported cocoa beans, elevating compliance costs for cross-border suppliers. Ontario's foodservice manufacturing corridor in Mississauga anchors bulk chocolate demand from bakery and ice cream producers.
Mexico
Monterrey and Toluca manufacturing corridors attract nearshoring investment seeking Panama Canal congestion relief. The country's national food safety regulator enforces labeling standards aligned with USMCA trade integration. Jalisco's Guadalajara metro area concentrates artisan chocolate production for domestic premium consumption.
North America Chocolate Confectionery Market Competitive Landscape
On the supply side, the industry is bifurcated between mass-market volume producers and premium positioning specialists, with mid-tier manufacturers facing margin compression from cocoa butter price volatility and regulatory reformulation costs. Three archetypes dominate: heritage-anchored domestic giants with century-old manufacturing footprints, Swiss and Belgian premium specialists leveraging terroir marketing in airport duty-free and boutique channels, and diversified multinational confectionery portfolios with seasonal merchandising scale. Competitive moves concentrate on Mexico manufacturing expansion for freight optimization and early reformulation to reduced-calorie profiles ahead of state-level sugar tax momentum.
Within the heritage-anchored tier, The Hershey Company exemplifies mass-market volume leadership through Pennsylvania-based manufacturing infrastructure. Lindt & Sprungli AG occupies the premium specialist position with Swiss heritage positioning in boutique and travel retail formats. Mondelez International, Inc. represents the diversified multinational archetype with portfolio breadth spanning seasonal merchandising cycles.
| Leading Market Players |
|---|
| Nestle S.A. |
| Lindt & Sprungli AG |
| The Hershey Company |
| Ghirardelli Chocolate Company |
| The Barry Callebaut Group |
| Mars, Inc. |
| Ferrero International S.A. |
| Godiva |
| Mondelez International, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cocoa butter price volatility in West African origins compresses margin stability for mass-market producers while simultaneously widening spreads between premium and economy tiers and forcing supply chain reconfiguration toward Mexico nearshoring corridors.
Pricing Analysis
Volume-discount tiering structures separate procurement economics across the North American chocolate confectionery market. Three-tier pricing stratifies across premium Swiss heritage positioning, standard mass-market formulations, and private-label economy alternatives. Cost compression in milk chocolate portfolios is intensifying because FDA added-sugar disclosure mandates accelerate reformulation spending. Corporate hospitality buyers in the Northeast corridor exhibit lowest price sensitivity, while convenience store operators driving single-serve wrapper volume face acute margin pressure.
Supply Chain Analysis
Export-control regime angles are minimal in cocoa commodity flows, though pesticide residue standards enforced by Health Canada and PMRA create regulatory friction limiting certain West African bean shipments into Canadian processing facilities. Supply concentration centers on Côte d'Ivoire and Ghana for raw cocoa mass, with Ecuador and Peru gaining share in premium flavor-grade segments. Cocoa butter and milk powder dependencies expose manufacturers to agricultural commodity cycles. Single-source vulnerability in West African bean procurement amplifies weather-driven disruption risk. Distribution runs through Port of Houston container terminals for U.S. manufacturing clusters, with Laredo-Colombia Solidarity International Bridge channeling finished goods into Mexican retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated e-commerce platforms and subscription-based direct-to-consumer operators, fragmenting traditional wholesale channel influence that once anchored manufacturer pricing power.
For Market Incumbents: Build formulation moats through precision fermentation-derived cocoa butter substitutes that decouple from bean-to-bar supply dependencies. Anchor backward integration into Mexican manufacturing corridors near Monterrey and Toluca to preempt Panama Canal logistics exposure. Defend against plant-based confectionery substitution by accelerating oat milk and coconut cream alternative R&D pipelines. For New Entrants and Emerging Players: Pursue airport duty-free channel penetration at Toronto Pearson and Dallas-Fort Worth hubs where travel retail recovery creates whitespace for premium positioning. Target the seniors demographic segment where direct-to-consumer subscription models capture pantry-stocking reliability needs with minimal incumbent competition. Deploy USDA organic certification as the primary go-to-market angle to command shelf space in Northeast corridor specialty retail. For Investors and Strategic Acquirers: Mid-tier contract manufacturers with flexible co-manufacturing capacity represent the most compelling acquisition target archetype as subscription-based replenishment models concentrate demand for production agility. Long-term viability over the coming decade hinges on reformulation capabilities ahead of state-level sugar tax momentum in California and New York. Watch for FDA enforcement actions on added-sugar disclosure compliance as the inflection indicator for portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Commercial lipid production in Pennsylvania and Ontario manufacturing corridors reduces cocoa butter price volatility exposure. |
| Mexico Manufacturing Expansion | Nearshoring to Monterrey and Toluca corridors bypasses Panama Canal congestion affecting U.S. Gulf Coast import flows. |
| Reduced-Calorie Reformulation | Early positioning ahead of California and New York sugar tax proposals captures regulatory arbitrage advantages. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models in the Northeast corridor concentrate customer lifetime value metrics. |
| USDA Organic Certification Investment | Premium tier differentiation commands shelf space in specialty retail channels concentrated along the Northeast corridor. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings in this study. Conversations with brand managers at heritage-anchored manufacturers, category buyers at Northeast corridor specialty retailers, supply planners at foodservice manufacturing facilities, and channel sales heads at duty-free operators provided operational ground truth. Secondary validation drew from FDA nutrition labeling guidance documents, Health Canada pesticide residue bulletins, USDA organic certification databases, and customs import records for cocoa butter flows through Port of Houston. Bottom-up volume modeling triangulated against top-down expenditure estimates across consumer demographic segments.
Calibration approaches anchored volume and value outputs to observed pricing dynamics across premium, standard, and economy tiers. Segmentation dimensions modeled include product type by cocoa percentage, packaging format by cost tier alignment, sales channel by customer acquisition economics, and consumer demographic by maturity gradient. CAGRs were derived from trend extrapolation adjusted for regulatory reformulation timelines and channel shift velocities. Forecast inputs incorporated precision fermentation adoption curves and state-level sugar tax legislative momentum.
Sensitivities concentrate around West African weather patterns affecting cocoa bean supply, FDA enforcement intensity on added-sugar disclosure, and e-commerce fulfillment infrastructure expansion rates. Forecasts reflect assumptions about regulatory timelines and technology adoption thresholds without claiming predictive certainty. Material shifts in cocoa butter substitute commercialization economics or USMCA trade integration enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Candy Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Diet Candy Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Brain Mint Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
White Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
North America Dark Chocolate Market
Confectionery
Europe Dark Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
Chocolate Couverture Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Europe Confectionery Market