
 Cookie Dough Market | 2026-2036
Cookie Dough Market Size, Share, and Industry Trends Forecast 2026-2036
Cookie Dough Market Analysis
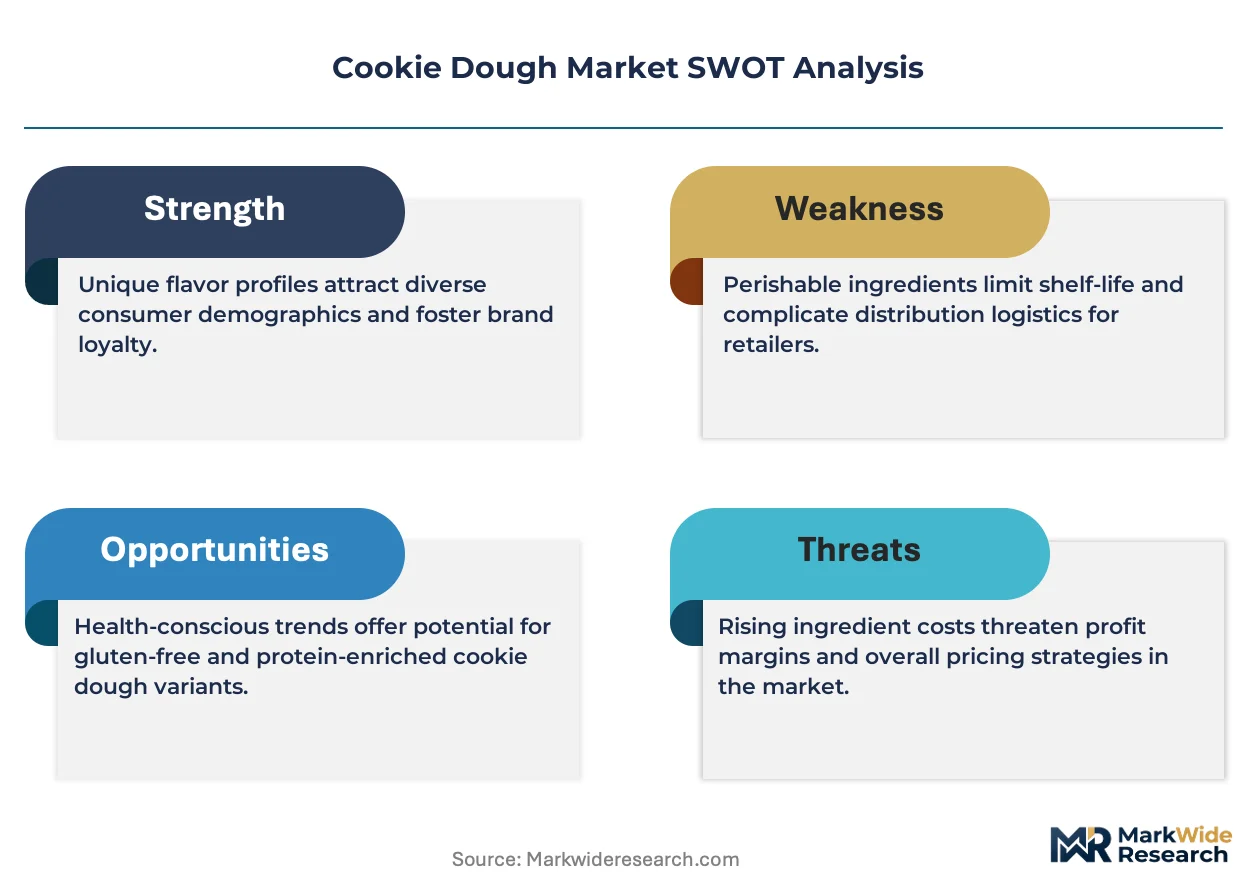
ISO 22000 certification is reorganizing competitive access in the cookie dough sector, as food safety management system validation becomes a non-negotiable threshold for retail and foodservice distribution. General Mills Inc. leverages its refrigerated logistics network to sustain national retail penetration, while Nestlé S.A. anchors European market presence through Cérélia Group's manufacturing infrastructure. Rhino Foods Inc. specializes in foodservice bulk formats, occupying a distinct position in the restaurant supply channel.
Cookie dough comprises a blend of wheat flour, fat, sweeteners, and flavor inclusions, formulated either for direct consumption or thermal processing into baked cookies, with water activity and pH controlled to inhibit pathogen survival. Frozen cookie dough retains the largest value share due to extended shelf stability and institutional procurement scale, though edible cookie dough commands superior unit margins through premium positioning in retail single-serve packs. Gluten-free cookie dough represents the fastest-expanding product type, driven by celiac-safe certification requirements and dedicated production line investments.
The FDA governs pathogen control in flour-based ready-to-eat products through FSMA preventive controls, while the USDA oversees dairy ingredient standards in formulations containing butter or milk derivatives. The EU's EFSA guidance on raw flour treatment and the F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants are reshaping cold chain economics for frozen distribution. Stakeholders must monitor evolving state-level cottage food laws and clean-label ingredient disclosure mandates that will determine which formulations secure shelf space in the next planning cycle.
Market Dynamics
The FDA's Food Safety Modernization Act preventive controls for ready-to-eat flour processing are forcing capital-intensive line modifications across refrigerated and edible cookie dough production, compressing margins for mid-tier manufacturers while favoring ISO 22000-certified operators with validated kill-step protocols.
Growth Catalysts
- Café channel expansion:Specialty coffee chains are adding ready-to-bake portions to dessert menus, creating pull-through demand for portion-controlled formats with extended refrigerated shelf life.
- FSMA compliance infrastructure:The FDA's updated pathogen control requirements are accelerating consolidation toward certified producers with validated food safety management systems.
- Gluten-free formulation advances:Celiac-safe certification protocols and dedicated production line investments are opening premium shelf placement in conventional grocery channels.
Market Restraints
- Wheat flour input volatility:Commodity price swings for hard red winter wheat constrain margin predictability for frozen dough producers with long-dated retail contracts.
- Cold chain concentration risk:Hydrofluorocarbon refrigerant phase-downs under the EU F-Gas Regulation are elevating logistics costs for frozen distribution networks dependent on legacy cooling infrastructure.
- Pathogen detection limitations:Current rapid testing protocols for Salmonella and E. coli in low-moisture flour matrices extend hold-and-release cycles, constraining throughput velocity.
Strategic Opportunities
- Clean-label ingredient mandates:State-level cottage food law revisions are creating first-mover advantage for brands with simplified ingredient decks and transparent sourcing claims.
- Single-serve edible formats:Refrigerated grab-and-go packs are capturing impulse purchase occasions in convenience and campus retail channels previously unserved by bulk frozen formats.
- Foodservice bulk customization:Restaurant chains are sourcing proprietary flavor inclusions and dough rheology specifications, creating captive supply relationships with co-manufacturing partners.
Industry Challenges
- Cross-contamination control talent:Certified food safety managers with allergen segregation expertise command premium compensation, constraining regional facility expansion timelines.
- Legacy equipment retrofit costs:Validated kill-step installations for flour treatment require seven-figure capital commitments with extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cookie Dough Market |
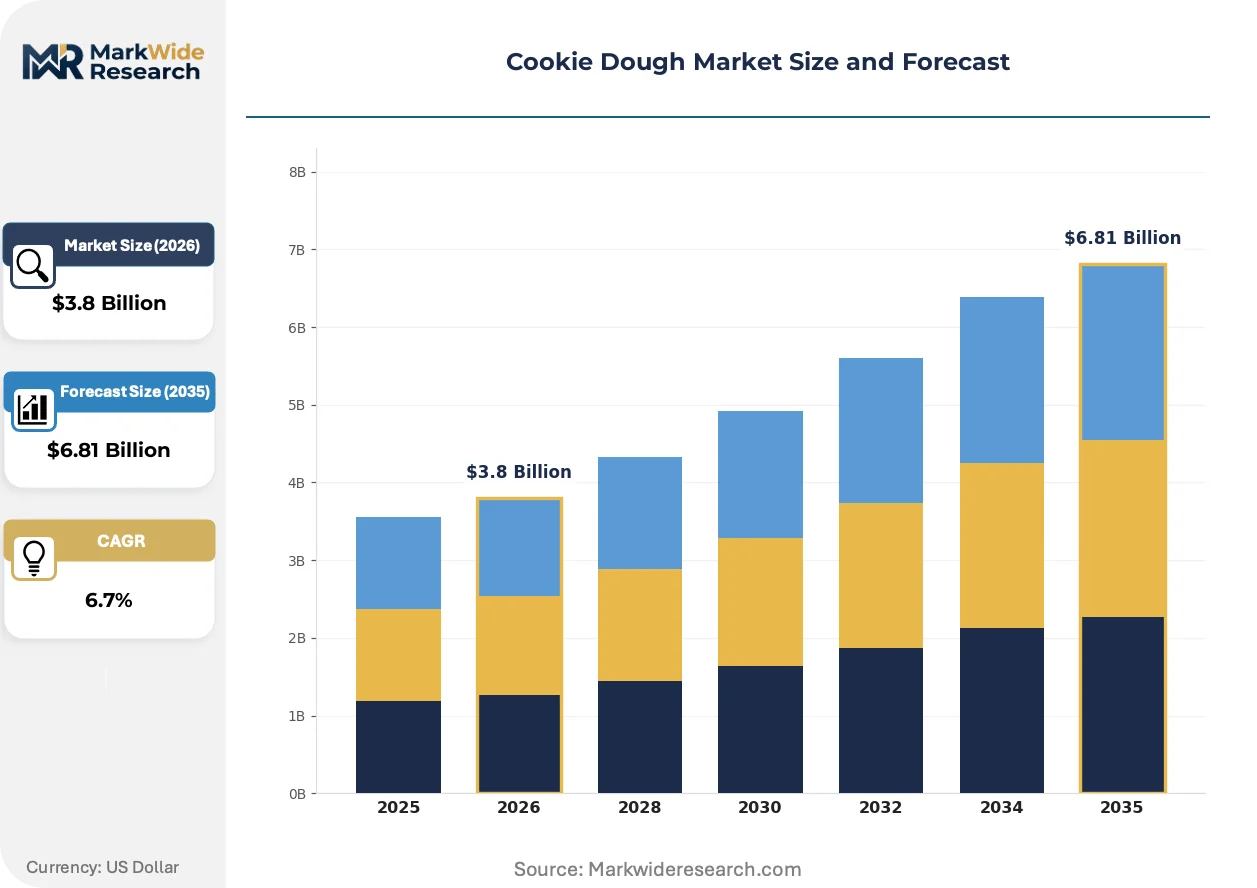
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Cookie Dough, Frozen Cookie Dough, Refrigerated Cookie Dough, Gluten-Free Cookie Dough End User: Retail Consumers, Restaurants, Bakeries, Cafés Flavor: Chocolate Chip, Peanut Butter, Snickerdoodle, Red Velvet Packaging Type: Tubs, Single-Serve Packs, Pouches, Bulk Packaging |
| Companies Covered | Dawn Foods UK Ltd., Dough-to-Go Inc., General Mills Inc., Gregory's Foods Inc., Neighbors LLC, Nestlé S.A., Rhino Foods Inc., Immaculate Baking Company, Cérélia Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cookie Dough Market Emerging Trajectories
Ready-to-eat cookie dough formulations are converging with controlled water activity and pH engineering to eliminate thermal processing requirements, compressing the traditional bake-sale paradigm into shelf-stable retail formats.
High-pressure processing technology is miniaturizing pathogen intervention systems for mid-scale producers. Regional co-manufacturers in the United States are adopting compact HPP units to achieve 5-log reduction validation without centralized thermal infrastructure. This capability is compressing the minimum efficient scale for FSMA-compliant edible dough production from industrial to craft-batch volumes.
The EU F-Gas Regulation's hydrofluorocarbon phase-down schedule is forcing refrigerated logistics operators to retrofit fleet cooling systems with natural refrigerant alternatives. Frozen dough distributors are absorbing elevated capital costs while negotiating pass-through clauses with retail partners. Cold storage facilities in Germany and France are accelerating ammonia and CO2 system conversions to maintain operating permits.
Retail buyers are consolidating procurement toward dual-source certified suppliers with validated kill-step documentation and dedicated allergen-free lines. Conventional grocery chains are displacing open-dating rotation models with scan-based trading agreements that transfer shrink risk upstream. This behavioral shift concentrates most visibly in United States club and mass merchant channels where private-label edible dough programs require quarterly third-party audit verification.
Cookie Dough Market Segmentation
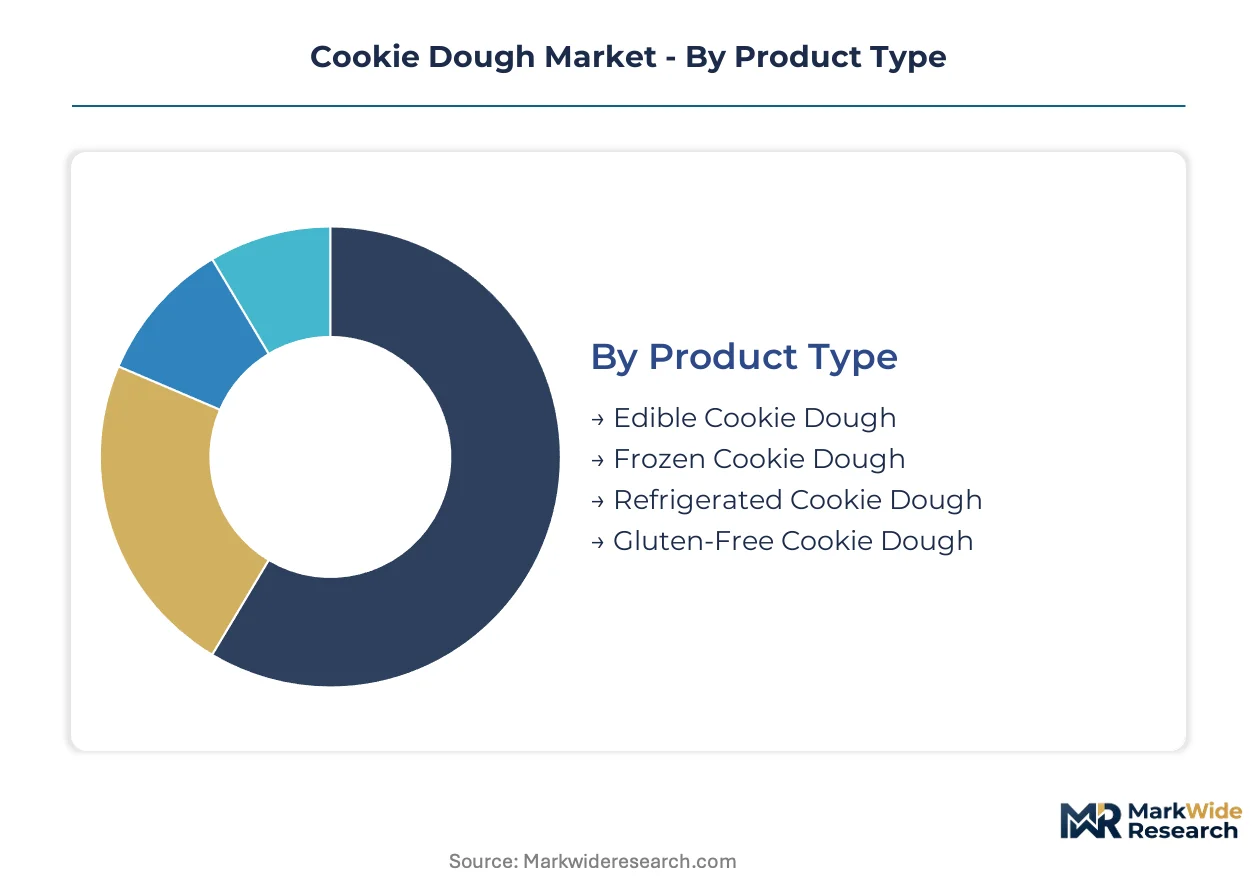
Cookie dough producers navigate four distinct segmentation axes that determine pricing power and channel access. Product format dictates cold chain requirements and margin structure. End-user concentration shapes batch size and customization depth. Flavor and packaging decisions drive impulse velocity and shelf placement economics.
Product Type:
Margin pools concentrate in ready-to-eat formats that bypass thermal processing infrastructure and capture premium shelf placement in convenience retail.
- Frozen Cookie Dough:Extended shelf stability through sub-zero storage enables institutional procurement at scale. Demand concentrates in United States foodservice distributors supplying quick-service chains with standardized portion control. Long-dated contracts with chain operators constrain margin flexibility during wheat commodity swings.
- Edible Cookie Dough:Formulated with heat-treated flour and controlled water activity for direct consumption without baking. Single-serve packs in United States convenience and campus retail channels command unit premiums through impulse placement. FSMA preventive control compliance elevates entry costs, compressing competitive field toward ISO 22000-certified operators.
- Refrigerated Cookie Dough:Requires continuous cold chain maintenance with shorter shelf windows. Ready-to-bake positioning targets home bakers seeking fresher texture outcomes than frozen alternatives.
- Gluten-Free Cookie Dough:Dedicated production lines and celiac-safe certification protocols open premium placement in conventional grocery. Almond and rice flour substitutions elevate input costs against wheat-based formulations.
The dominant share belongs to Frozen Cookie Dough, while Gluten-Free Cookie Dough is closing the gap fastest.
End User:
Volume concentration tilts toward foodservice operators with centralized procurement and specification control.
- Restaurants:Chain operators source proprietary flavor inclusions and dough rheology specifications through captive co-manufacturing relationships. Bulk format procurement with quarterly audit requirements transfers food safety liability upstream.
- Retail Consumers:Supermarket and mass merchant channels drive single-serve and family-size tub demand. United States club store buyers impose scan-based trading agreements that shift shrink risk to suppliers.
- Cafés:Specialty coffee chains expanding dessert menus create pull-through demand for portion-controlled ready-to-bake formats with extended refrigerated stability.
- Bakeries:Independent operators and in-store bakery programs require bulk packaging with consistent batch-to-batch performance for scratch-alternative production.
Restaurants capture the largest volume share, though Cafés are expanding their procurement fastest as dessert menu diversification accelerates.
Flavor:
Consumer recognition and ingredient cost profiles stratify margin capture across classic and novelty positioning.
- Chocolate Chip:Vanilla-based dough with semisweet inclusion remains the baseline reference standard. Ubiquitous placement across all channels limits differentiation but ensures consistent velocity.
- Peanut Butter:Allergen labeling requirements and dedicated line segregation elevate production complexity. Strong performance in United States convenience retail and foodservice dessert applications.
- Snickerdoodle:Cinnamon-sugar positioning targets seasonal and limited-time offering strategies in retail channels.
- Red Velvet:Cocoa-tinted dough with cream cheese flavor inclusions commands premium pricing through visual differentiation and occasion-based gifting positioning.
Chocolate Chip maintains volume leadership, while Red Velvet achieves the steepest expansion trajectory through premium positioning and social media visibility.
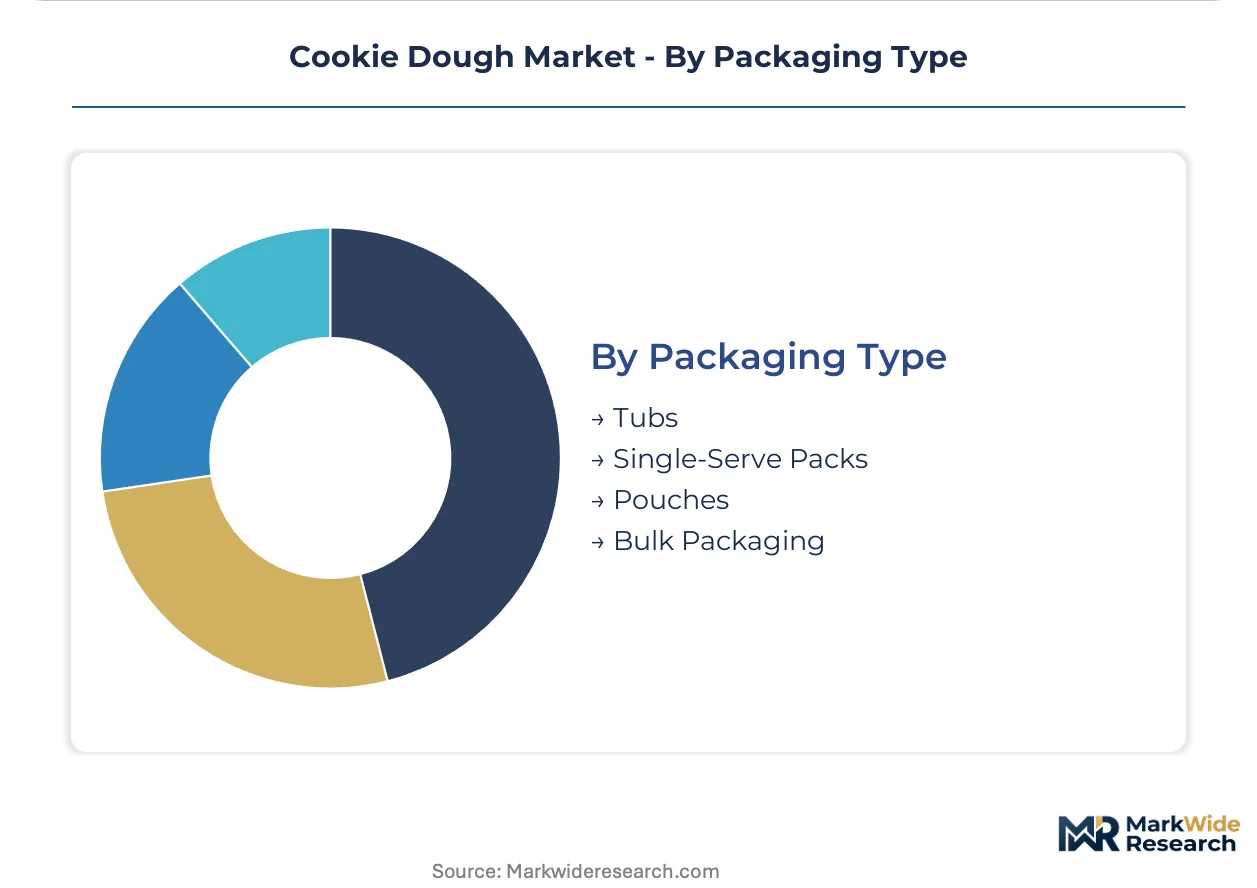
Packaging Type:
Cold chain economics and retail format constraints determine optimal packaging selection.
- Single-Serve Packs:Refrigerated grab-and-go formats capture impulse occasions in United States convenience, campus, and travel retail channels previously unserved by bulk frozen alternatives.
- Tubs:Family-size refrigerated formats target home baking occasions with multiple-use value positioning. Dominant in conventional grocery cookie dough sets.
- Pouches:Flexible packaging reduces shipping cube and refrigeration load. Emerging in direct-to-commerce and subscription channel fulfillment.
- Bulk Packaging:Foodservice totes and pails for restaurant and bakery operators with high-throughput production requirements. Custom labeling supports private-label and proprietary brand programs.
Tubs hold the largest installed base, though Single-Serve Packs are gaining share fastest through convenience channel expansion and on-the-go consumption trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA preventive controls and EU F-Gas refrigerant mandates are redirecting capital toward certified production hubs in North America and Europe, while Asia-Pacific markets absorb technology transfer for localized edible dough manufacturing.
United States
Specialty coffee chains and convenience retail channels drive refrigerated single-serve demand. FDA FSMA preventive control requirements for ready-to-eat flour processing elevate entry costs toward ISO 22000-certified operators. Minneapolis-St. Paul anchors General Mills' refrigerated logistics network, sustaining national retail penetration through validated cold chain infrastructure.
Germany
Industrial bakery outsourcing and frozen foodservice procurement concentrate volume in Baden-Württemberg and Bavaria. EU F-Gas Regulation hydrofluorocarbon phase-downs force cold storage retrofits with ammonia and CO2 systems. Cologne-Düsseldorf logistics corridors absorb elevated capital costs while negotiating pass-through clauses with retail partners.
United Kingdom
Café channel expansion and premium grocery placement support edible dough velocity in London and Southeast England. Food Standards Agency guidance on raw flour treatment aligns with EFSA pathogen control frameworks. Manchester-Leeds manufacturing clusters specialize in gluten-free dedicated line production for celiac-safe certification.
France
Artisan bakery co-manufacturing and dessert menu diversification at brasserie chains create pull-through for portion-controlled formats. ANSM and DGCCRF oversight of ready-to-eat food processing reinforces HACCP validation requirements. Lyon-Auvergne-Rhône-Alpes hosts Cérélia Group manufacturing infrastructure anchoring European market presence.
Canada
Cross-border supply integration with United States distributors and provincial cottage food law variations shape regional competitive access. Health Canada flour treatment standards and PMRA ingredient oversight parallel FDA frameworks. Toronto-Ontario and Vancouver-British Columbia concentrate refrigerated logistics nodes serving club store and mass merchant channels.
Cookie Dough Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with ISO 22000 validation separating bankable retail suppliers from regional co-manufacturers. The competitive field compresses toward dual-source certified operators capable of documented kill-step protocols and dedicated allergen-free lines. Three archetypes dominate: multinational CPG conglomerates with refrigerated logistics networks, foodservice bulk specialists with captive restaurant relationships, and regional co-manufacturers adopting compact HPP technology. Consolidation accelerates through validated facility acquisitions and quarterly third-party audit verification programs.
Within the multinational tier, Nestlé S.A. and General Mills Inc. exemplify scale-driven operators with continental cold chain infrastructure. Rhino Foods Inc. occupies a distinct position as a foodservice bulk format specialist serving restaurant supply channels. Regional private specialists including Dough-to-Go Inc. and Neighbors LLC represent the craft-batch segment adopting miniaturized pathogen intervention systems to achieve FSMA compliance without industrial capital commitments.
| Leading Market Players |
|---|
| Dawn Foods UK Ltd. |
| Dough-to-Go Inc. |
| General Mills Inc. |
| Gregory's Foods Inc. |
| Neighbors LLC |
| Nestlé S.A. |
| Rhino Foods Inc. |
| Immaculate Baking Company |
| Cérélia Group |
| Others |
Supply Flow & Price Mechanics
Heat-treated flour substitution for conventional raw flour is simultaneously relocating production toward FDA-inspected facilities and compressing margin spreads between certified and uncertified suppliers. This input shift forces manufacturers to absorb seven-figure capital commitments for validated kill-step infrastructure while passing through elevated logistics costs under EU F-Gas refrigerant mandates.
Pricing Analysis
Certification level creates the primary spread between premium ISO 22000-validated operators and regional co-manufacturers lacking documented kill-step protocols. Three-tier pricing structure separates FSMA-compliant edible dough from refrigerated ready-to-bake formats and commodity frozen bulk, with gluten-free dedicated-line products commanding additional premiums. Pricing pressure stems from wheat commodity volatility constraining long-dated foodservice contracts. Quick-service chains exhibit highest price sensitivity due to centralized procurement leverage, while specialty cafés accept premium positioning for portion-controlled formats with extended shelf stability.
Supply Chain Analysis
Refrigerated logistics chokepoints at Minneapolis-St. Paul and Cologne-Düsseldorf corridors concentrate North American and European distribution capacity. Wheat flour sourcing draws from United States hard red winter belt and Canadian prairie provinces, with almond and rice flour alternatives anchoring gluten-free production in Manchester-Leeds clusters. Single-source vulnerability runs through legacy hydrofluorocarbon cooling infrastructure facing accelerated phase-down timelines. Distribution runs through foodservice distributors for bulk formats and direct-store-delivery networks for refrigerated retail packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing miniaturization disrupts minimum efficient scale assumptions, enabling craft-batch FSMA compliance without industrial capital burdens. FDA preventive control enforcement accelerates consolidation toward certified operators with validated documentation systems.
For Market Incumbents: Consolidate through acquisition of regional co-manufacturers with compact HPP installations to secure dual-source redundancy. Absorb certified food safety manager talent pools to defend against wage inflation constraining facility expansion timelines. Prioritize backward integration into heat-treated flour supply to lock input security against commodity volatility.
For New Entrants and Emerging Players: Campus retail and convenience channel service gaps expose white-space opportunities where bulk frozen formats fail to reach impulse purchase occasions. Target single-serve edible packs with clean-label positioning under revised cottage food law windows. Pursue co-manufacturing partnerships with established cold chain operators to bypass seven-figure infrastructure requirements.
For Investors and Strategic Acquirers: FDA FSMA enforcement milestones reshape the acquisition landscape toward ISO 22000-certified assets with documented kill-step validation. Five-to-ten year viability favors operators with dedicated allergen-free lines and quarterly third-party audit relationships. Monitor state-level cottage food law revision velocity as inflection indicator for craft-batch competitive entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Compact HPP Technology Adoption | Enables mid-scale producers to achieve FSMA compliance without centralized thermal infrastructure investments. |
| Gluten-Free Dedicated Line Expansion | Opens premium shelf placement in conventional grocery through celiac-safe certification protocols. |
| Foodservice Bulk Customization Programs | Creates captive supply relationships with restaurant chains sourcing proprietary flavor inclusions. |
| Refrigerated Single-Serve Format Launch | Captures impulse occasions in convenience and campus retail channels previously unserved by bulk alternatives. |
| Natural Refrigerant Cold Chain Retrofit | Maintains EU operating permits under F-Gas Regulation hydrofluorocarbon phase-down schedules. |
Methodological Framework
The analysis maps frozen, edible, refrigerated, and gluten-free cookie dough segments, each validated through plant managers at co-manufacturing facilities, category buyers at club stores, foodservice distribution procurement leads, and regulatory affairs specialists. Primary interviews combined with secondary validation from FDA FSMA guidance documents, EFSA raw flour treatment advisories, EU F-Gas Regulation filings, and refrigerated logistics operator disclosures. Bottom-up volume builds triangulated against top-down value estimates across product format and end-user dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated product type, end-user concentration, flavor positioning, and packaging format dimensions with regional regulatory cluster overlays. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion announcements. Wheat commodity price assumptions and cold chain cost pass-through coefficients informed margin compression scenarios.
Forecasts assume regulatory continuity in FDA preventive control enforcement and EU F-Gas phase-down schedules; material policy shifts would require re-modeling. Pathogen detection protocol advances or accelerated refrigerant substitution timelines present specific revision triggers. Revision becomes warranted when gluten-free certification adoption rates cross conventional grocery penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Low Calorie Nutella Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
UK Compound Chocolate Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Mooncake Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Chocolate Spread Market
Confectionery
Mints Market
Confectionery
Low-Fat Sweets Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Canada Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
Low Calorie Keto Desserts Market