
 Chocolate Hazelnut Spread Market | 2026-2036
Chocolate Hazelnut Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Hazelnut Spread Market Outlook
Multi-source hazelnut procurement is decoupling from traditional single-origin Turkish dependency as manufacturers diversify into Italian and Georgian orchards. Ferrero International S.A. anchors its supply chain through long-term grower contracts across Piedmont. The Hershey Company leverages North American peanut-butter infrastructure to co-manufacture hybrid SKUs. Nestlé S.A. competes on cocoa sustainability certification density across European retail channels.
Chocolate hazelnut spread is a fat-based confectionery emulsion typically containing 13% minimum hazelnut paste, 7-10% cocoa powder, and 30-40% sugar by weight, produced through two-stage refining and conching of roasted nuts with chocolate liquor. Its primary commercial purpose is shelf-stable bread-spread consumption and industrial bakery filling applications. Conventional formulations still dominate retail volume, though organic and reduced-sugar variants command disproportionate margin pools in German and French supermarkets. Glass jar packaging sustains premium positioning in specialty stores, while pouch formats are gaining fastest velocity through online retail channels serving café and food-service bulk buyers.
EU Green Deal deforestation regulations and REACH chemical standards shape hazelnut import compliance costs and cocoa butter substitution thresholds for European producers. FDA food-labeling rules and USDA organic certification govern US market access and shelf-space allocation. Stakeholders must monitor evolving EU packaging waste directives and emerging state-level sugar taxes to anticipate reformulation investments and channel-mix reallocations before regulatory deadlines harden.
Market Dynamics
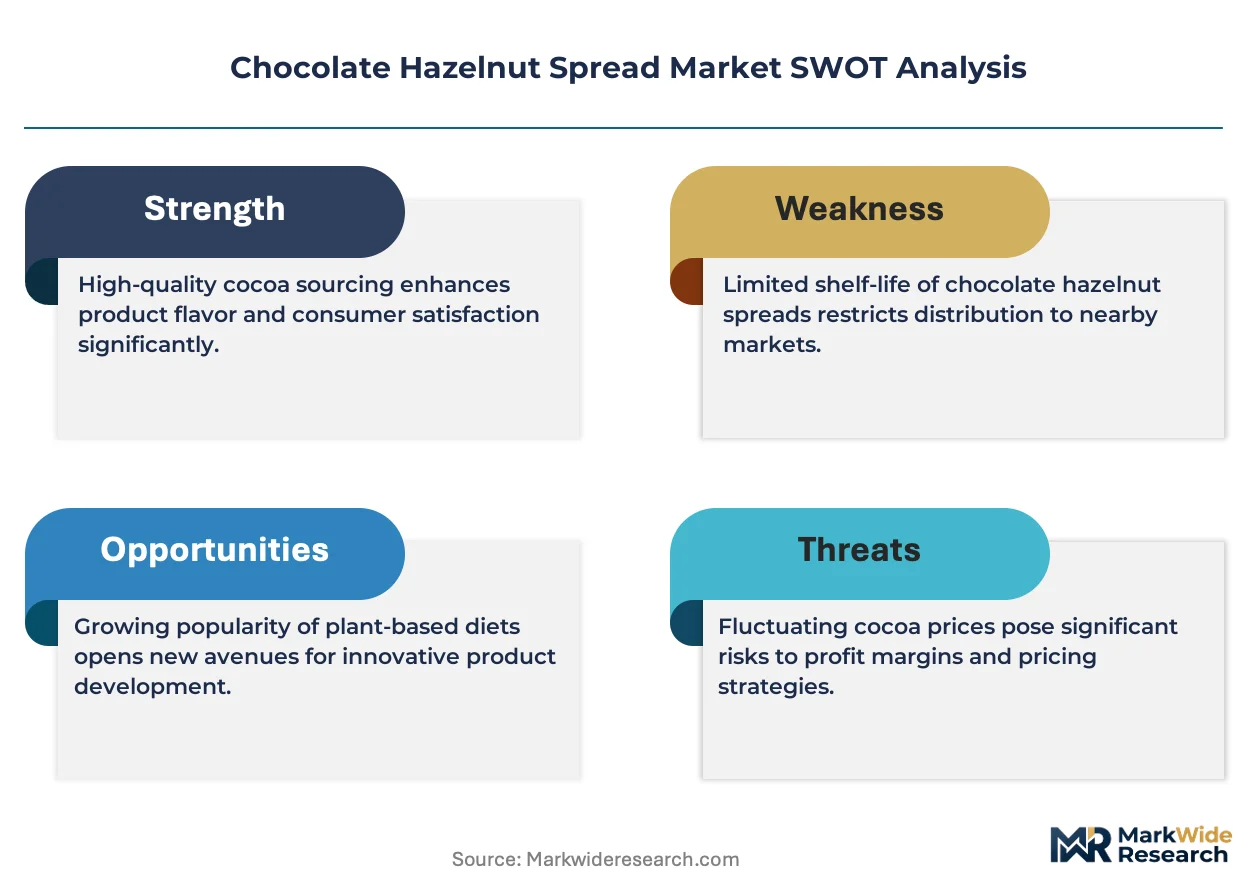
EU Green Deal deforestation-free supply chain mandates are forcing cocoa and hazelnut procurement restructuring across European manufacturing networks, decoupling long-standing Turkish sourcing dependencies.
Growth Catalysts
- Clean-label bakery demand:Artisanal positioning in German and French retail channels pulls reformulated SKUs with simplified ingredient decks and certified sustainable cocoa.
- Pouch format velocity:Food-service bulk buyers through online retail channels accelerate adoption of flexible packaging for café and industrial bakery applications.
- REACH chemical standards:European compliance thresholds for cocoa butter substitutes drive investment in refined emulsion stability and alternative fat structuring.
Market Restraints
- Hazelnut supply concentration:Turkish orchard dependency creates price volatility exposure despite diversification into Italian and Georgian growing regions.
- Sugar taxation trajectory:Emerging state-level levies in Western European jurisdictions threaten margin compression on conventional high-sugar formulations.
- Glass jar cost structure:Premium packaging format sustains positioning but constrains volume elasticity against lower-cost pouch alternatives.
Strategic Opportunities
- Georgian orchard development:Underpenetrated Caucasus growing regions offer hazelnut volume expansion outside traditional Mediterranean supply bases.
- Reduced-sugar white space:German and French supermarket premium tiers show disproportionate margin capture for reformulated variants meeting evolving nutritional profiling.
- EU packaging waste directives:Regulatory tailwinds for recyclable and reduced-material formats favor early movers in flexible pouch and mono-material jar design.
Industry Challenges
- Deforestation certification timelines:EU Green Deal compliance documentation requirements compress supplier audit and traceability system implementation windows.
- Emulsion reformulation complexity:Cocoa butter substitution thresholds demand reworked refining and conching protocols without sacrificing shelf stability or mouthfeel.
- Multi-origin sourcing integration:Procurement fragmentation across Piedmont, Lazio, and Georgian orchards strains quality consistency and lot traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Hazelnut Spread Market |
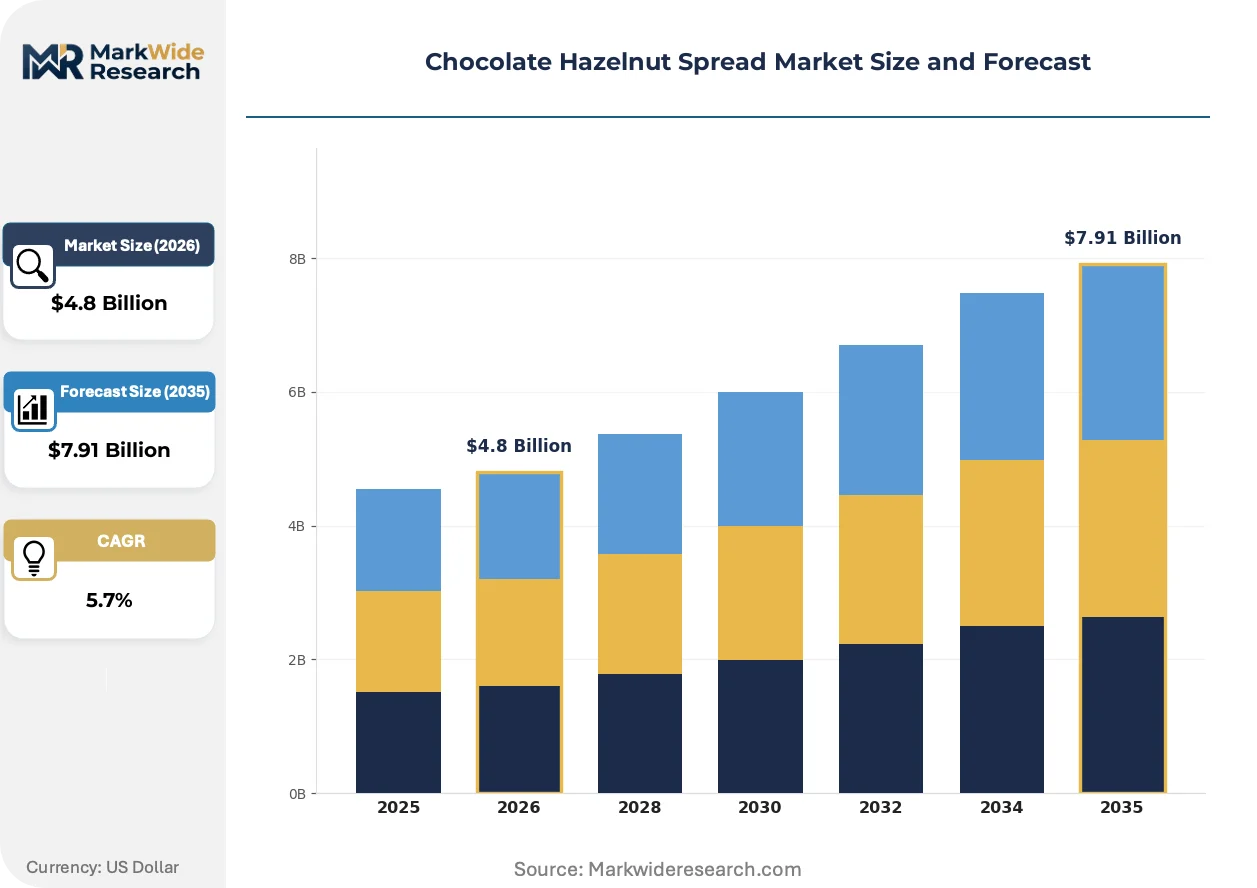
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Reduced Sugar, Dairy-Free Packaging Type: Glass Jar, Plastic Jar, Pouch, Bulk Container Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service End User: Households, Food Manufacturers, Bakeries, Cafés |
| Companies Covered | The Hershey Company, NUTKAO S.r.l., Ferrero International S.A., Pernigotti S.p.A., Dr. Oetker, Nestlé S.A., Lindt & Sprüngli, Rigoni di Asiago, Mondelez International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Hazelnut Spread Market Strategic Shifts
Reformulation science and packaging engineering are reshaping competitive positioning in chocolate hazelnut spread manufacturing, with sustainability certification density becoming a primary purchase trigger in European retail.
High-pressure processing for hazelnut paste stabilization is converging with clean-label emulsion systems to extend shelf life without synthetic preservatives. German private-label manufacturers adopt these systems fastest, compressing the premium-conventional price gap while maintaining artisanal positioning claims.
EU Green Deal deforestation-free supply chain regulations now mandate geolocation traceability for cocoa and hazelnut imports into European processing facilities. Industrial consequence includes mandatory supplier requalification and third-party audit density increases. German and Italian manufacturing clusters face the steepest compliance cost curves as they source from highest-risk origin territories.
Café culture expansion in urban German centers rotates demand toward food-service bulk formats and customizable viscosity specifications. Online retail channels displace traditional wholesale distribution for mid-size bakery and hospitality buyers. This pattern concentrates in Berlin and Munich metropolitan procurement networks, where direct-to-operator platforms capture growing share of institutional volume.
Chocolate Hazelnut Spread Market Segmentation
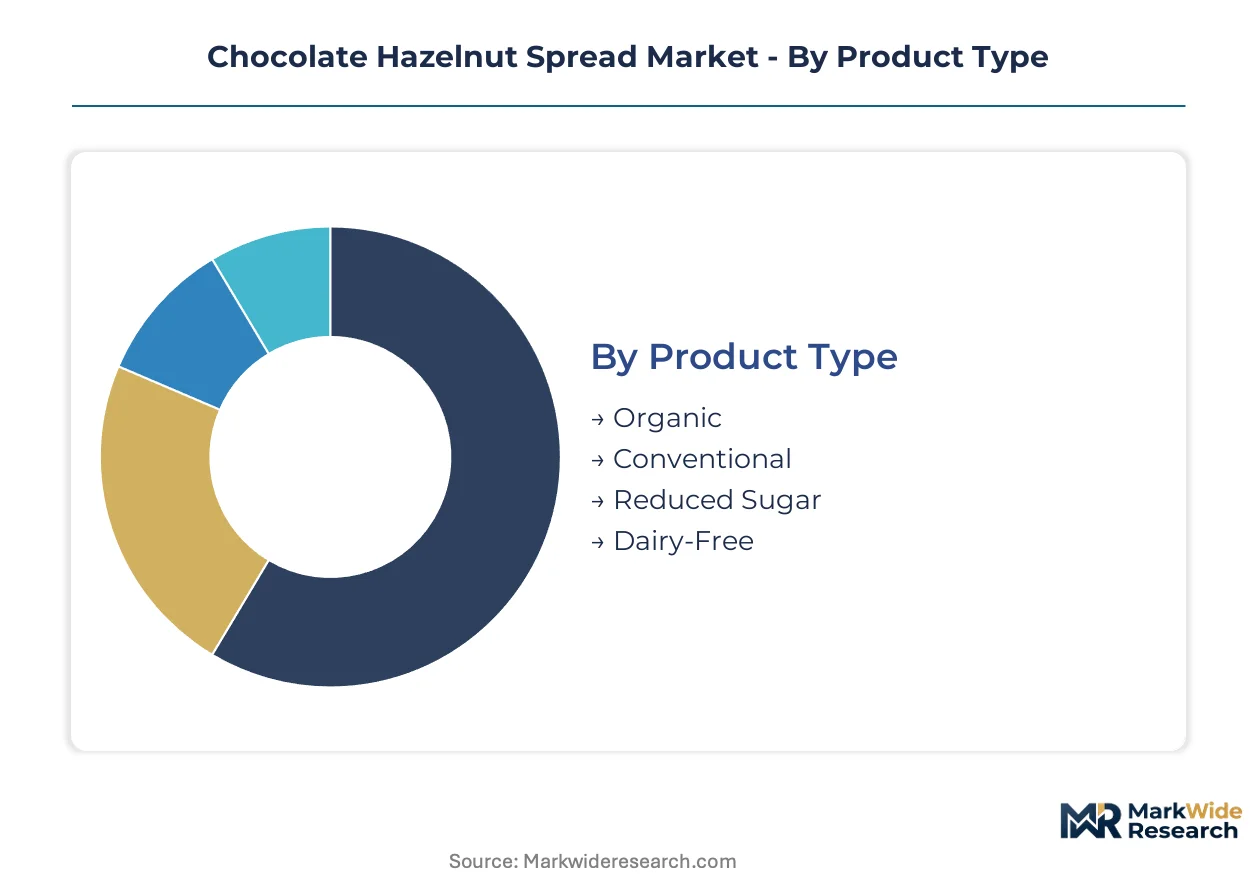
Segmentation in chocolate hazelnut spread markets reveals how formulation, packaging, and channel choices map to distinct margin structures and regulatory exposure. Each dimension carries divergent growth trajectories and compliance cost profiles that reshape competitive positioning.
Product Type:
Standalone retail SKUs dominate shelf space while industrial formulations embed deeper into bakery and confectionery supply chains with customized viscosity and stability specifications.
- Organic:Certified formulations command premium placement in German and French supermarket tiers. Clean-label positioning aligns with EU Green Deal traceability mandates, though hazelnut supply constraints limit volume scaling.
- Conventional:Standard formulations with 30-40% sugar content and 13% minimum hazelnut paste anchor mass-market retail. Turkish hazelnut dependency keeps procurement costs volatile despite Italian and Georgian diversification efforts.
- Reduced Sugar:Reformulated variants address emerging state-level sugar taxation in Western Europe. German private-label manufacturers compress the premium-conventional price gap fastest.
- Dairy-Free:Plant-based emulsion systems substitute cocoa butter alternatives to meet vegan positioning. REACH chemical standards for fat structuring drive reformulation complexity.
Volume placements concentrate in Conventional; the faster expansion belongs to Reduced Sugar.
Packaging Type:
Cost tier separation runs from premium glass through economy pouches, with format choice determining channel access and food-service penetration depth.
- Glass Jar:Premium positioning sustains artisanal claims in specialty retail. German and Italian manufacturing clusters face steepest EU packaging waste directive compliance curves for this format.
- Pouch:Flexible formats accelerate through online retail channels serving Berlin and Munich café procurement networks. Food-service bulk buyers favor reduced material costs and customizable viscosity dispensing.
- Plastic Jar:Mid-tier positioning balances shelf presence with lighter logistics costs. Mono-material designs respond to recyclability mandates.
- Bulk Container:Industrial-scale filling for bakery and confectionery manufacturers. Direct-to-operator platforms displace traditional wholesale distribution in metropolitan German markets.
Revenue pools concentrate in Glass Jar; pouch formats are climbing the fastest through food-service channels.
Distribution Channel:
Customer type fragmentation separates household impulse purchasing from institutional procurement with divergent service and specification requirements.
- Supermarkets:Mass-market retail with premium private-label density in German chains. Shelf-space allocation hinges on sustainability certification density.
- Online Retail:Direct-to-operator platforms capture mid-size bakery and hospitality buyers in urban German centers. Pouch and bulk formats gain velocity here.
- Specialty Stores:Curated assortments emphasizing artisanal provenance and Piedmont hazelnut sourcing. Glass jar dominance sustains premium positioning.
- Food Service:Institutional supply with customizable viscosity and volume specifications. Café culture expansion in Berlin and Munich rotates demand toward this channel.
Transaction volume concentrates in Supermarkets; steepest expansion trajectory belongs to Online Retail.
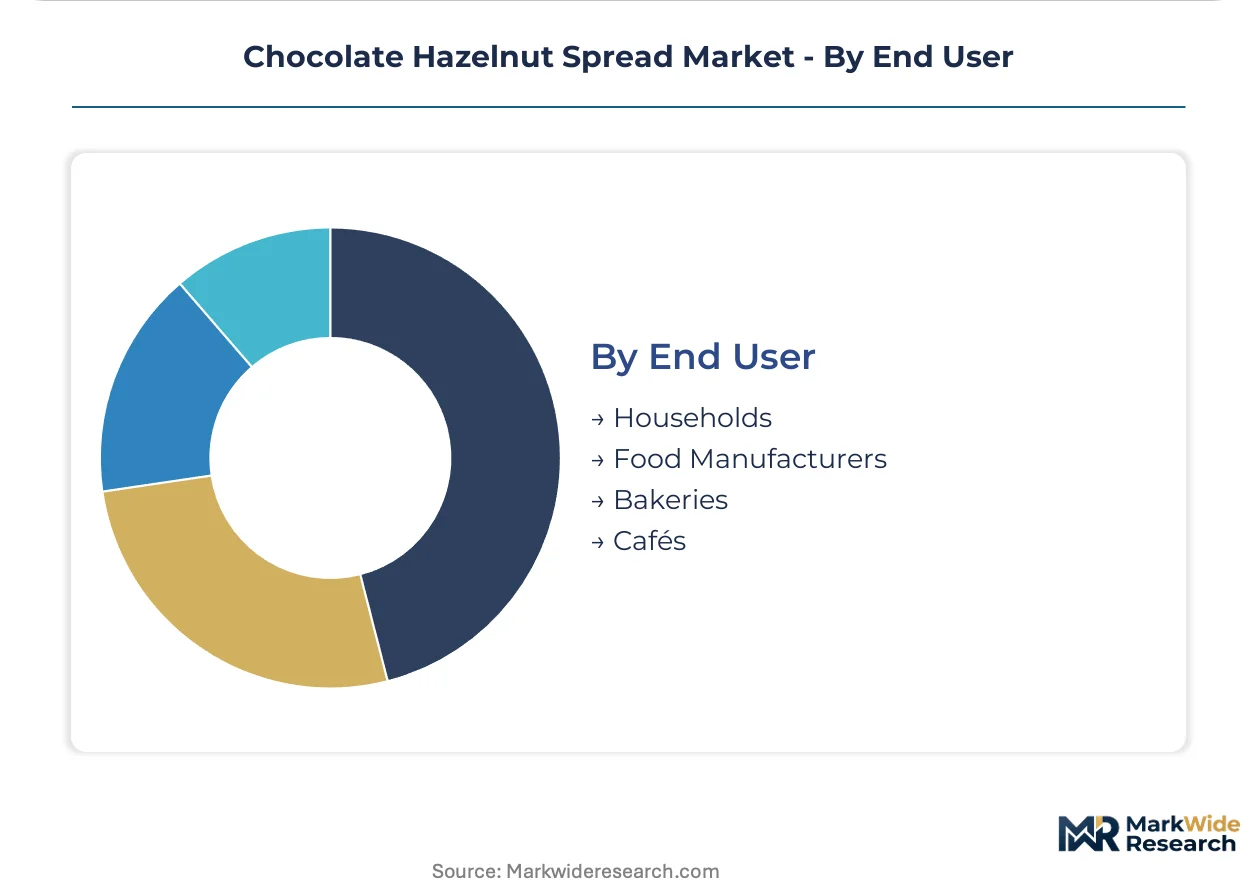
End User:
Application maturity separates established household consumption from emerging industrial embedding in processed food manufacturing.
- Households:Bread-spread consumption with brand loyalty anchored by taste preference and shelf stability. German retail channels show strongest per-capita consumption.
- Bakeries:Industrial filling applications for croissants, pastries, and confectionery. Clean-label demand pulls reformulated SKUs with simplified ingredient decks.
- Food Manufacturers:Ingredient supply for ice cream, confectionery, and dessert products. Multi-origin hazelnut procurement strains quality consistency across Piedmont, Lazio, and Georgian sources.
- Cafés:Customizable viscosity for beverage and dessert applications. Urban German procurement networks concentrate demand here.
Volume foundations sit with Households; Bakeries are gaining share fastest on clean-label bakery demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for chocolate hazelnut spread concentrates in Western European retail channels, where café culture and clean-label bakery applications sustain category momentum. German and Italian manufacturing clusters anchor production capacity. Regulatory pressure from EU Green Deal deforestation mandates reshapes procurement geography across all major processing facilities.
Germany
Premium private-label spreads and urban café culture drive per-capita consumption leadership. EFSA nutritional profiling guidelines pressure reformulation toward reduced-sugar variants. Berlin and Munich metropolitan procurement networks rotate demand toward food-service bulk formats through direct-to-operator platforms.
Italy
Piedmont hazelnut provenance commands artisanal positioning in specialty retail channels. REACH chemical standards for cocoa butter substitutes drive emulsion stability investments across Lombardy processing facilities. Turin-based manufacturing clusters source through long-term grower contracts across Piedmont and Lazio orchards.
France
Supermarket premium tiers capture disproportionate margin pools for organic and reduced-sugar SKUs. ANSM food-labeling enforcement tightens ingredient declaration requirements. Parisian retail channels concentrate demand for glass jar formats sustaining premium positioning claims.
United States
North American peanut-butter infrastructure enables hybrid SKU co-manufacturing for bread-spread crossover appeal. FDA food-labeling rules and USDA organic certification govern shelf-space allocation. Pennsylvania and Illinois manufacturing clusters leverage existing nut-processing equipment for spread production.
Turkey
Ordu and Giresun provinces remain the dominant hazelnut origin despite manufacturer diversification efforts. Turkish Ministry of Agriculture and Forestry export standards face EU Green Deal traceability audit requirements. Black Sea coastal growing regions experience price volatility from concentrated supply exposure.
Chocolate Hazelnut Spread Market Competitive Environment
Long-term grower contracting dominates the current landscape as manufacturers secure deforestation-certified hazelnut supply. The vendor base stratifies across three tiers: integrated confectionery conglomerates with captive cocoa operations, regional specialists leveraging single-origin provenance claims, and private-label manufacturers serving supermarket chains. Two strategic archetypes have emerged: sustainability-certification leaders competing on traceability density, and format-innovation specialists capturing food-service velocity through pouch and bulk packaging. Competitive moves center on backward integration into orchard assets and portfolio diversification into reduced-sugar and dairy-free variants.
Within the integrated conglomerate tier, Ferrero International S.A. and Nestlé S.A. exemplify divergent sourcing strategies. Ferrero anchors its position through Piedmont orchard contracts and geolocation traceability systems. Nestlé competes on cocoa sustainability certification density across European retail channels. Among North American players, The Hershey Company occupies a position leveraging existing nut-butter infrastructure for hybrid spread production. Italian regional specialist Rigoni di Asiago represents the single-origin provenance archetype with organic positioning.
| Leading Market Players |
|---|
| The Hershey Company |
| NUTKAO S.r.l. |
| Ferrero International S.A. |
| Pernigotti S.p.A. |
| Dr. Oetker |
| Nestlé S.A. |
| Lindt & Sprüngli |
| Rigoni di Asiago |
| Mondelez International, Inc. |
| Others |
Value Chain & Pricing Dynamics
Orchard labor concentration in Turkey's Black Sea provinces anchors cost structures across all pricing tiers, with harvest labor differentials between Turkish, Italian, and Georgian growing regions widening spreads between premium Piedmont-sourced SKUs and mass-market formulations.
Pricing Analysis
After-sales service unbundling distinguishes food-service bulk contracts from retail shelf pricing, with pouch format buyers absorbing logistics coordination while glass jar retail carries full trade promotion support. Three-tier pricing structure across premium, standard, and economy levels separates Piedmont single-origin organic from Turkish conventional from private-label economy SKUs. Price differentiation hinges on sustainability certification density and hazelnut provenance tier. Cost compression in conventional formulations is intensifying because Turkish supply volatility feeds through to procurement contracts. Food-service buyers show highest price sensitivity; specialty retail consumers demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Turkey's Ordu and Giresun provinces despite manufacturer diversification into Italian and Georgian orchards. Geographic supply concentration spans Turkey, Italy, and Georgia for hazelnut raw material, with Côte d'Ivoire and Ghana anchoring cocoa butter inputs. Raw material dependencies center on hazelnut paste, cocoa liquor, and vegetable fat structuring agents. Regulatory restriction from EU Green Deal deforestation mandates threatens supply continuity for non-compliant origins. Distribution runs through direct-to-operator platforms displacing traditional wholesale in German metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal traceability mandates erect barrier-to-entry moats favoring incumbents with certified supply chain infrastructure already deployed.
For Market Incumbents: Hedge Turkish supply exposure through long-term contracting across Piedmont and Lazio orchards while accelerating geolocation traceability system deployment ahead of audit deadline compression. Backward integration into Georgian orchard development secures volume expansion outside traditional Mediterranean bases. Certification investment in organic and reduced-sugar variants captures margin pools in German and French premium tiers. For New Entrants and Emerging Players: EU packaging waste directives in Germany open a window for mono-material pouch specialists targeting Berlin and Munich café procurement networks through direct-to-operator platforms. Reduced-sugar white space in French supermarket premium tiers offers most penetrable entry point. Go-to-market angle should lead with sustainability certification density as primary purchase trigger. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale organic specialists possessing deforestation-certified supply chains given accelerating retailer shelf-space allocation toward traceability-verified SKUs. Long-term viability favors targets with captive orchard relationships spanning multiple origins. Signal to watch is German private-label manufacturer consolidation pace as compliance costs compress marginal players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Piedmont and Georgian land acquisition secures deforestation-certified hazelnut supply outside Turkish concentration. |
| Reduced-Sugar Reformulation Program | ANSM nutritional profiling alignment captures margin expansion in French supermarket premium tiers. |
| Flexible Pouch Format Expansion | Berlin and Munich direct-to-operator platform penetration rotates food-service volume from glass jar dependency. |
| Geolocation Traceability System Deployment | EU Green Deal compliance documentation satisfies mandatory supplier audit requirements ahead of deadline hardening. |
| Multi-Origin Sourcing Integration | Piedmont, Lazio, and Georgian procurement fragmentation hedges Turkish price volatility while maintaining quality consistency. |
Study Parameters
Multi-period observation of hazelnut procurement contract terms, sustainability certification penetration rates, and packaging format velocity anchored the trend analysis, supplemented by interviews with category buyers at German supermarket chains, procurement directors at Italian processing facilities, food-service operators in Berlin and Munich, and hazelnut growers across Turkish Black Sea provinces. Secondary validation drew from EU customs trade data, EFSA nutritional profiling guidelines, EU Green Deal regulatory filings, and REACH chemical standard updates. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Segment-weighting applied differential growth assumptions to organic, conventional, reduced-sugar, and dairy-free formulation tiers, with packaging format and distribution channel cross-tabulations informing volume allocation. Modeled dimensions spanned product type, packaging configuration, and end-user application across the projection horizon. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and channel-mix shifts. Industry-specific forecast inputs included hazelnut crop yield projections and EU packaging waste directive implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for high-pressure pasteurization stabilization would alter the outlook for clean-label shelf-life extension. Forecasts reflect assumptions about regulatory enforcement intensity and consumer willingness-to-pay for certification density. Hazelnut supply disruption from climate volatility or trade restriction represents primary revision risk. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Confectionery Fats Market
Confectionery
Chocolate Flavors Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
Fruit Jellies Market
Confectionery
North America Dark Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Milk Chocolate Market
Confectionery
South Africa Confectionery Market
Confectionery
Brazil Chocolate Market
Confectionery
Black Treacle Market
Confectionery
Low Calorie Treats Market
Confectionery
Europe Chocolate Market
Confectionery
Real and Compound Chocolate Market