
 Original and Flavored Syrup Market | 2026-2036
Original and Flavored Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Original and Flavored Syrup Market Insights
The gap between premium artisan syrups and mass-market commodity formulations is realigning procurement patterns across the foodservice channel. Monin Inc. leverages its French heritage and flavor innovation pipeline to command premium placement in specialty cafes and cocktail bars. The Coca-Cola Company anchors volume through fountain syrup contracts with national quick-service chains. Tate & Lyle PLC competes on functional ingredient systems that reduce sugar content while preserving mouthfeel.
Original and flavored syrups are concentrated aqueous solutions of sucrose, fructose, or alternative sweeteners infused with natural or artificial flavor compounds, typically standardized to 65-75 Brix for shelf stability and consistent dilution ratios. These syrups function primarily as flavor delivery and sweetening agents in beverages, bakery applications, and dessert manufacturing. Fruit syrups lead volume in the product type category, though maple syrup commands disproportionate margin due to protected origin labeling and limited North American supply. The food service chains segment within end users generates the highest throughput, while agave nectar and artificial sweetener formulations are gaining fastest within sweetening agents as calorie-conscious menus expand.
The FDA enforces strict added sugar disclosure and serving size regulations that compel manufacturers to reformulate or relabel portfolios. The USDA's National Organic Program and state-level maple grading standards in Vermont and Quebec shape premium positioning and export eligibility. Stakeholders must monitor evolving sweetener classifications and clean-label certification requirements as procurement criteria tighten across institutional foodservice accounts.
Market Dynamics
The FDA's added sugar disclosure mandates are compressing formulation cycles across the Original and Flavored Syrup Market, forcing manufacturers to accelerate clean-label transitions while maintaining 65-75 Brix stability thresholds.
Growth Catalysts
- Specialty Coffee Expansion:Third-wave coffeehouses in the United States are standardizing premium syrup portfolios, creating pull-through demand for artisan flavor profiles in independent cafés.
- Clean-Label Certification:The USDA National Organic Program and Quebec maple grading standards are unlocking export eligibility and price premiums for certified producers.
- Reduced-Calorie Reformulation:Stevia and monk fruit extraction technologies are enabling sugar reduction without viscosity loss, satisfying foodservice chain procurement criteria.
Market Restraints
- Input Cost Volatility:Cane sugar and high-fructose corn syrup prices fluctuate with Brazilian harvest cycles and ethanol policy shifts, squeezing margin predictability.
- Supply Concentration Risk:Quebec and Vermont control over 70% of global maple syrup reserves through strategic reserve systems, creating geographic single-point vulnerability.
- Technical Shelf-Life Limitations:Natural flavor compounds degrade faster than artificial alternatives, constraining clean-label product distribution radius.
Strategic Opportunities
- Untapped Foodservice Channels:Ghost kitchens and virtual beverage brands in the United States are adopting syrup-based signature drinks without traditional café infrastructure.
- Functional Ingredient Convergence:Prebiotic fiber and adaptogen infusions are merging with traditional sweetening systems, opening wellness-positioned product lines.
- State-Level Clean-Label Incentives:California's Proposition 65 enforcement patterns are accelerating preemptive reformulation ahead of federal mandates.
Industry Challenges
- Flavor Chemist Talent Scarcity:The specialized skill set for natural flavor stability engineering commands premium compensation, constraining R&D scaling.
- Dual Certification Timelines:Simultaneous organic and kosher certification processes extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Original and Flavored Syrup Market |
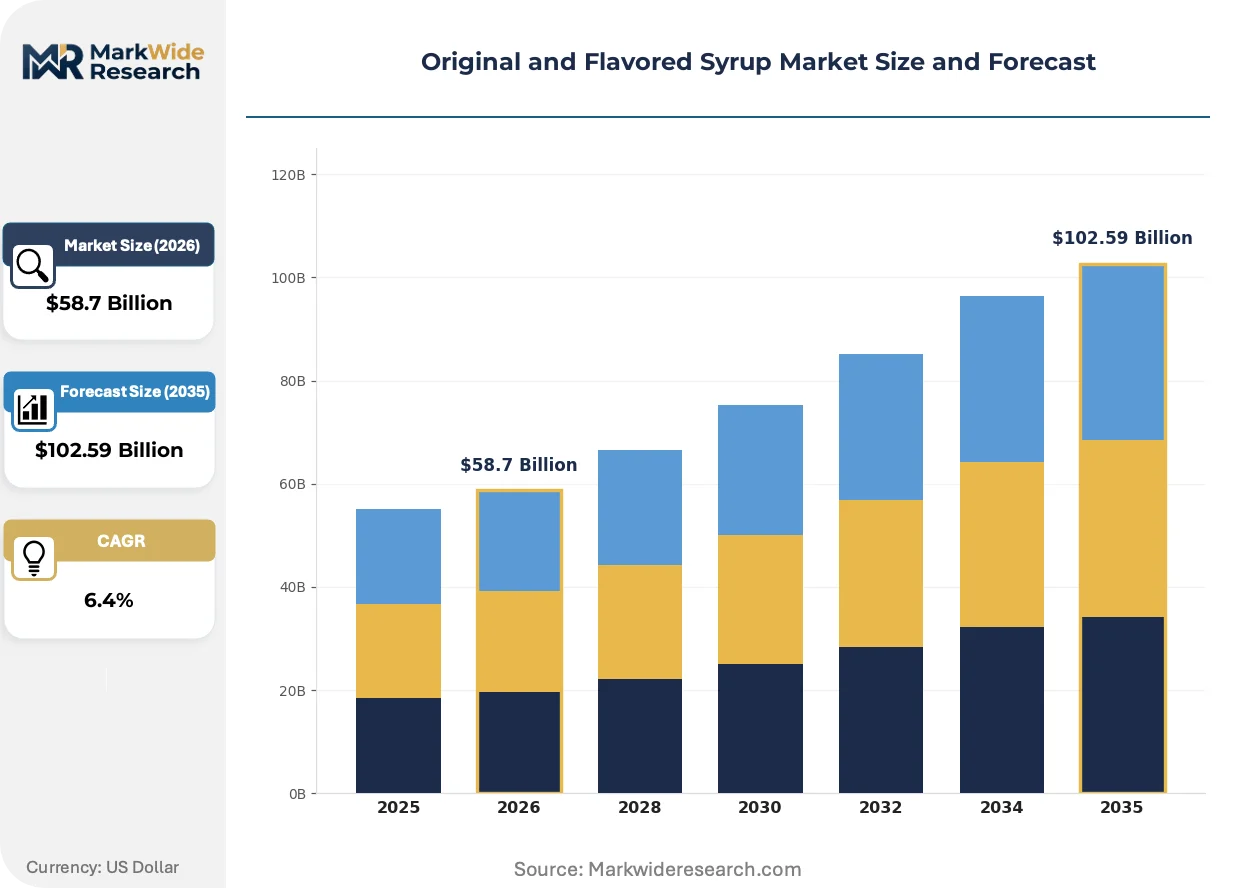
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Original Syrup, Maple Syrup, Fruit Syrup, Chocolate Syrup End User: Households, Restaurants, Cafes, Food Service Chains Packaging Type: Bottles, Jars, Sachets, Pouches Sweetening Agent: Cane Sugar, High Fructose Corn Syrup, Agave Nectar, Artificial Sweeteners |
| Companies Covered | Monin Inc., The Coca-Cola Company, The Hershey Company, Archer Daniels Midland Company, PepsiCo, Inc., Kerry Group plc, Torani Inc., Sensient Technologies Corporation, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Original and Flavored Syrup Market Trends and Innovations
Reformulation pressure is converging with extraction technology advances to reshape how sweetness and flavor are delivered across beverage and bakery applications.
Encapsulation technology is integrating volatile natural flavor compounds into lipid or carbohydrate matrices, protecting aromatic integrity through pasteurization and extended ambient storage. Mid-sized syrup manufacturers in the Pacific Northwest are adopting spray-dried and coacervation systems at pilot scale. This capability compression is enabling regional players to compete with multinational shelf-life performance without artificial preservative portfolios.
EFSA's 2023 revised guidance on novel food status for steviol glycosides is clarifying approval pathways for next-generation sweetener blends across European Union member states. The regulation is accelerating dossier preparation costs but reducing regulatory uncertainty for exporters. Reduced-sugar syrup formulations targeting foodservice chains are prioritizing EFSA-compliant ingredient sourcing to maintain cross-border distribution eligibility.
Direct-to-operator sample programs are displacing traditional foodservice broker networks for artisan syrup penetration. Specialty roasters and independent cocktail bars in Austin, Portland, and Brooklyn are receiving curated flavor kits with batch-specific tasting notes and pairing guides. This channel experimentation is most visible in United States metropolitan markets where operator decision-making concentrates in single-owner establishments rather than corporate procurement committees.
Original and Flavored Syrup Market Segmentation
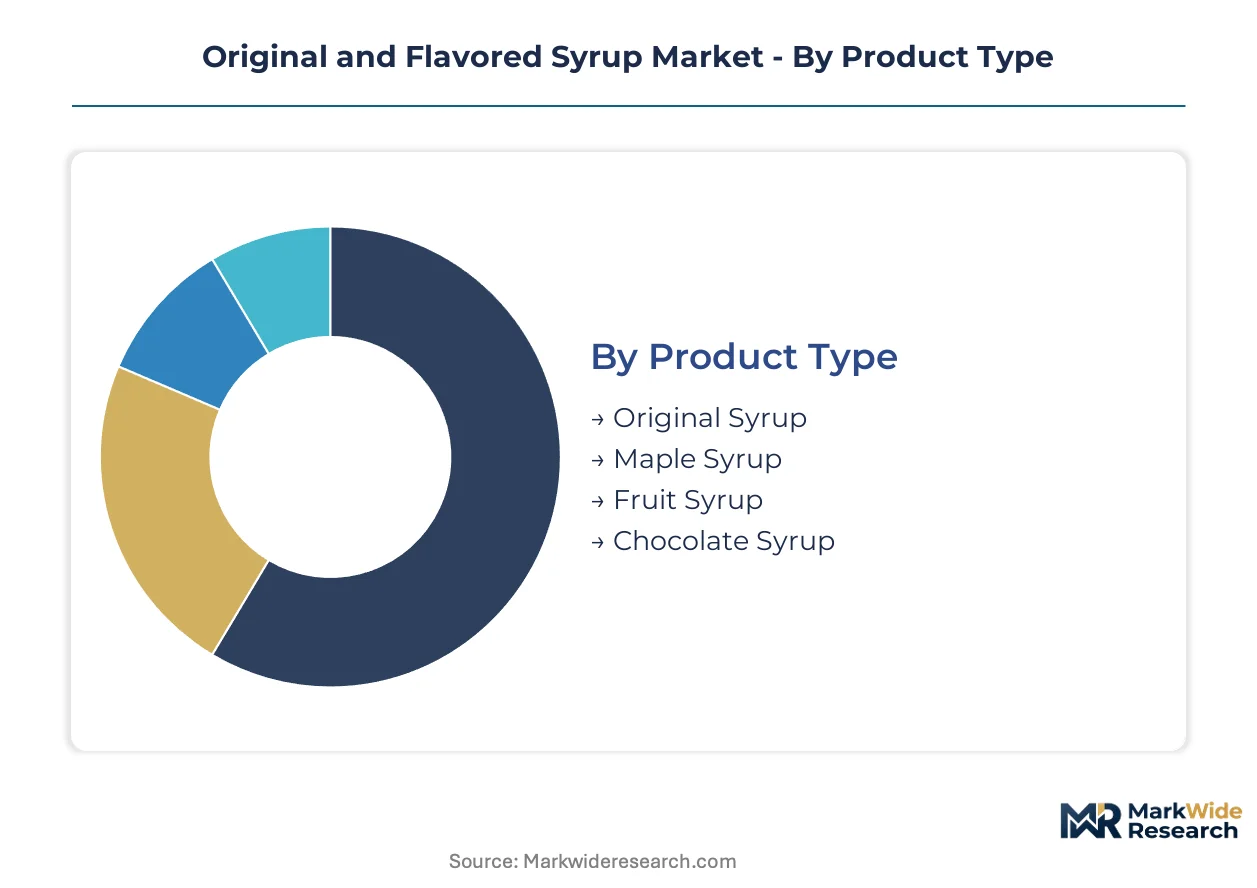
Syrup manufacturers configure production lines around viscosity specifications and thermal processing requirements that vary sharply across product categories. Capital allocation decisions follow end-use concentration patterns, with foodservice scale dictating bulk handling infrastructure and retail channels demanding flexible packaging formats.
Product Type:
Fruit syrup and chocolate syrup production demands the heaviest upfront investment in aseptic filling systems and flavor stabilization technology.
- Original Syrup:Unflavored sucrose or invert sugar solutions standardized to 65-75 Brix serve as base ingredients for beverage manufacturing and industrial bakery applications. Demand concentrates in United States foodservice distributors supplying fountain beverage systems, where consistent dilution ratios outweigh flavor complexity.
- Fruit Syrup:Aqueous solutions infused with concentrated fruit purees or natural flavor compounds require pH adjustment and pasteurization protocols that extend production cycles. United States specialty coffee chains are standardizing pomegranate and blackberry variants for signature beverage programs, driving procurement of cold-fill compatible formulations.
- Maple Syrup:Protected-origin products from Quebec and Vermont command premium positioning through graded density standards and reserve system release schedules.
- Chocolate Syrup:Cocoa suspension systems stabilized with emulsifiers target dessert and beverage applications with distinct viscosity profiles.
Most installed capacity flows through original syrup. Expansion is steepest in fruit syrup.
End User:
Volume throughput and procurement sophistication split sharply between fragmented household purchasers and consolidated institutional accounts.
- Food Service Chains:National quick-service and fast-casual operators negotiate multi-year fountain syrup contracts with volume-tier pricing and exclusive flavor development clauses. United States-based coffeehouse chains anchor category pull-through, with procurement committees mandating 65-75 Brix consistency and clean-label certification.
- Restaurants:Independent full-service operators purchase through broadline distributors, prioritizing portion-control packaging and back-of-bar versatility for cocktail programs. Portland and Brooklyn cocktail bars are driving adoption of artisan syrups with batch-specific tasting notes.
- Cafes:Third-wave coffeehouses in Austin and similar metropolitan clusters standardize premium syrup portfolios for signature latte formulations.
- Households:Retail purchasers through grocery and e-commerce channels favor smaller format bottles with extended shelf-life labeling.
Procurement concentration sits with food service chains. Growth is most visible in cafes.
Packaging Type:
Packaging selection tracks distribution radius and operator handling constraints across institutional and retail channels.
- Bottles:PET and glass formats dominate retail and tabletop foodservice applications, with ergonomic grip design and dispensing closure engineering driving repeat purchase rates.
- Jars:Wide-mouth glass containers target premium maple syrup positioning with origin labeling and grading transparency.
- Sachets:Single-serve foil packets serve airline, hospitality, and foodservice portion-control requirements with minimal waste protocols.
- Pouches:Flexible film formats with fitment closures are gaining adoption in ghost kitchen and virtual beverage brands for reduced shipping cube and disposal efficiency.
Throughput volume runs through bottles. Adoption is climbing fastest in pouches.
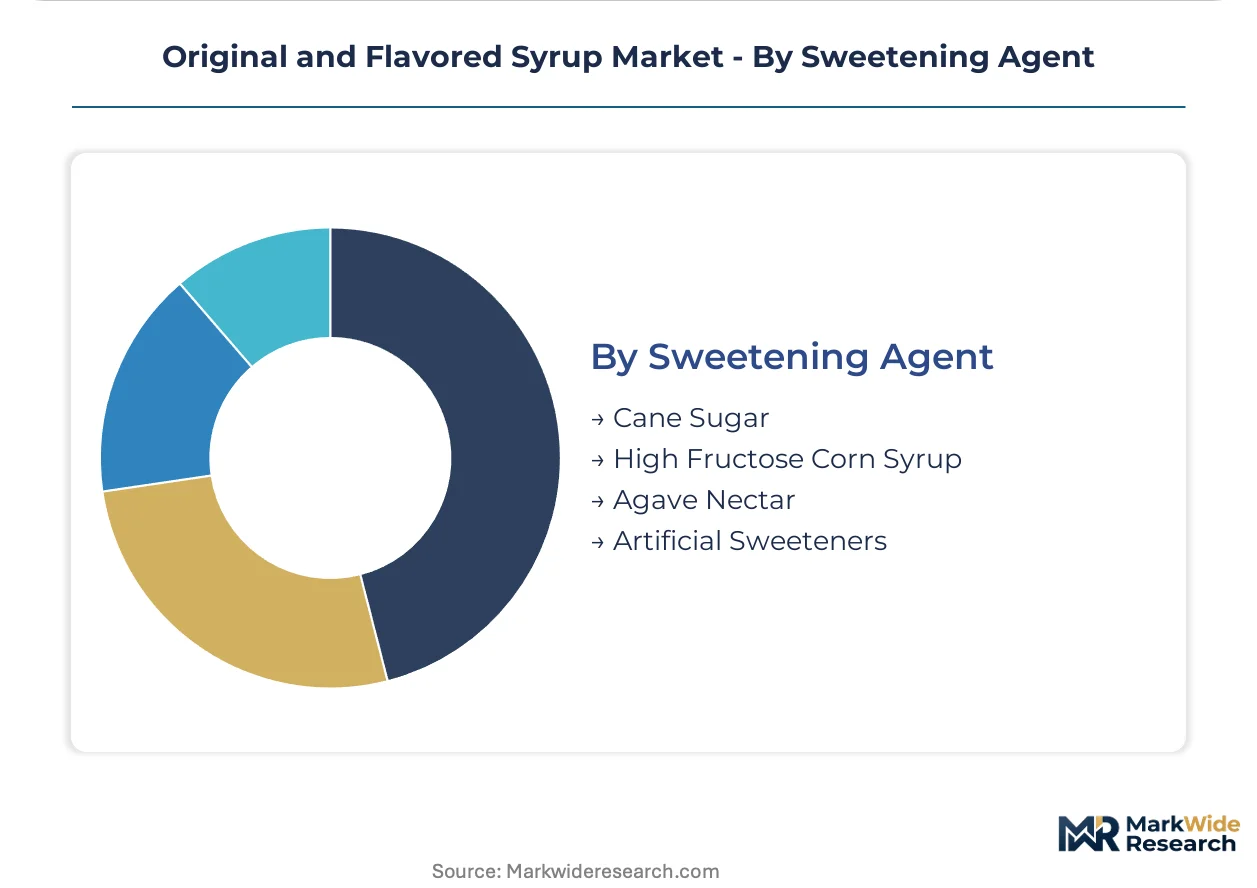
Sweetening Agent:
Ingredient system selection determines regulatory compliance burden and reformulation cycle frequency across export markets.
- Cane Sugar:Sucrose from Brazilian and domestic sources provides baseline sweetness with clean flavor profile and established supply security, though price volatility tracks ethanol policy shifts and harvest cycles.
- High Fructose Corn Syrup:Corn-derived sweeteners anchor mass-market fountain syrup economics through United States domestic production, with FDA added sugar disclosure rules pressuring gradual displacement.
- Agave Nectar:Low-glycemic index positioning from Mexican supply chains targets calorie-conscious menu development in United States specialty beverage channels.
- Artificial Sweeteners:Stevia and monk fruit extraction technologies enable sugar reduction without viscosity loss, satisfying foodservice chain procurement criteria for reduced-calorie lines.
Existing formulation base rests on cane sugar and high fructose corn syrup. Reformulation investment is concentrating in artificial sweeteners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States craft beverage culture commands premium syrup volumes, while Brazil's cane sugar infrastructure anchors commodity sweetener supply chains for fountain beverage manufacturing.
United States
Third-wave coffeehouses in Austin and Portland standardize artisan syrup portfolios for signature latte programs. FDA added sugar disclosure mandates compress formulation cycles toward clean-label alternatives. Brooklyn cocktail bars drive adoption of batch-specific tasting notes through direct-to-operator sample programs.
Canada
Quebec's strategic maple syrup reserve system controls release schedules for protected-origin products. Health Canada enforces strict grading standards that shape export eligibility for premium positioning. Vancouver specialty roasters integrate certified organic syrups into regional beverage programs.
Germany
EFSA novel food guidance on steviol glycosides clarifies approval pathways for reduced-sugar formulations targeting foodservice chains. Bavarian industrial bakeries demand consistent 65-75 Brix specifications for standardized dilution ratios. Berlin's third-wave café cluster tests natural flavor encapsulation technologies.
Japan
METI clean-label initiatives accelerate reformulation toward monk fruit and stevia extraction systems. Tokyo coffeehouse chains mandate shelf-life stability without artificial preservatives. Osaka food manufacturers pilot prebiotic fiber infusions merging wellness positioning with traditional sweetening.
Brazil
Ethanol policy shifts and harvest cycles generate cane sugar price volatility squeezing margin predictability. São Paulo-based fountain syrup contractors negotiate multi-year volume agreements with quick-service operators. Minas Gerais processing infrastructure supplies high-fructose formulations for mass-market beverage manufacturing.
Original and Flavored Syrup Market Competitive Landscape
Top-tier vendors anchor fountain syrup contracts with national quick-service chains, while mid-sized artisan producers occupy specialty café and cocktail bar channels. The vendor base splits between heritage flavor houses and commodity sweetener conglomerates. Strategic archetypes include French heritage-positioned innovators, corn-derived mass-market suppliers, and functional ingredient system specialists. Competitive moves concentrate on clean-label certification acquisition and encapsulation technology licensing.
Within the heritage-positioned tier, Monin Inc. and Torani Inc. exemplify French and Italian-origin flavor innovation pipelines commanding premium placement in independent cafés. Tate & Lyle PLC occupies a position among functional ingredient specialists competing on sugar reduction without viscosity loss. The Coca-Cola Company anchors the scale-driven commodity segment through domestic corn-sweetener infrastructure and fountain equipment integration.
| Leading Market Players |
|---|
| Monin Inc. |
| The Coca-Cola Company |
| The Hershey Company |
| Archer Daniels Midland Company |
| PepsiCo, Inc. |
| Kerry Group plc |
| Torani Inc. |
| Sensient Technologies Corporation |
| Tate & Lyle PLC |
| Others |
Pricing and Supply Chain Analysis
USDA National Organic Program certification gates qualified supply and premium-tier pricing access, with certified producers commanding placement in United States specialty coffee chains while non-certified competitors face margin compression in mass-market fountain syrup contracts.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for cane sugar-derived formulations, intensifying competition at the commodity tier. Three-tier pricing structure across premium artisan, standard foodservice, and economy fountain tiers separates Monin-grade heritage positioning from private-label alternatives. Pricing pressure stems from high-fructose corn syrup displacement as FDA added sugar disclosure rules tighten. Quick-service chains exhibit highest price sensitivity; craft cocktail bars demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Quebec's strategic maple syrup reserve system, which controls over seventy percent of global protected-origin inventory. Raw material flows draw from Brazilian cane sugar harvests, Vermont maple grading infrastructure, and Mexican agave nectar cultivation. Tariff exposure concentrates in North American sweetener trade corridors. Distribution runs through broadline foodservice distributors for institutional accounts and direct-to-operator sample programs for artisan penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by recurring fountain syrup contracts with quick-service chains that generate predictable offtake across economic cycles.
For Market Incumbents: To counter clean-label certification delays from dual organic-kosher timelines, accelerate encapsulation technology licensing and secure captive supply of Quebec maple reserve allocations. Prioritize R&D investment in stevia-monk fruit extraction systems that preserve 65-75 Brix stability without viscosity loss. For New Entrants and Emerging Players: Enter via ghost kitchen and virtual beverage brand channels in United States metropolitan clusters, where syrup-based signature drinks bypass traditional café infrastructure requirements. Target Austin and Portland third-wave coffeehouses with curated flavor kits featuring batch-specific tasting notes. Deploy direct-to-operator sampling to circumvent entrenched foodservice broker networks. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized Pacific Northwest encapsulation technology adopters because spray-dried and coacervation capabilities enable regional players to match multinational shelf-life performance. Five-to-ten year viability hinges on clean-label transition completion. Monitor EFSA novel food guidance enforcement patterns as inflection indicator for reduced-sugar formulation export eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Spray-dried flavor matrices protect aromatic integrity through pasteurization without artificial preservatives. |
| Clean-Label Certification Investment | USDA National Organic Program and Quebec grading standards unlock export eligibility and price premiums. |
| Direct-to-Operator Channel Buildout | Curated flavor kits with tasting notes displace traditional foodservice broker networks in Brooklyn and Portland. |
| Reduced-Calorie Reformulation Pipeline | Stevia and monk fruit extraction technologies satisfy foodservice chain procurement criteria for wellness-positioned lines. |
| Strategic Maple Reserve Allocation | Quebec strategic reserve release schedules anchor protected-origin premium positioning against commodity alternatives. |
Research Methodology
Bottom-up foodservice chain modeling reconciled against top-down sweetener supply tracking forms the analytical core. Primary interviews with flavor chemists, fountain equipment technicians, specialty café procurement managers, and broadline distributor category buyers combined with secondary validation from FDA filing databases, USDA National Organic Program certification registries, Quebec maple grading records, and EFSA novel food guidance documents. Triangulation between volume-tier contract data and artisan producer shipment patterns ensures segment-level accuracy.
Input-output matrices map sweetener source flows through processing stages to end-use concentration patterns across the projection horizon. Segmentation dimensions include product type viscosity specifications, end-user procurement sophistication tiers, packaging format handling constraints, and sweetening agent regulatory compliance burdens. CAGRs derive from contract renewal rate analysis and reformulation investment velocity. Forecast inputs incorporate Brazilian ethanol policy shifts and EFSA steviol glycoside approval timelines.
Inputs from Quebec maple reserve release schedules and Brazilian harvest cycle reports were available through the study window; gaps in ghost kitchen adoption velocity and virtual brand syrup procurement patterns introduce uncertainty bands. Forecasts reflect assumptions regarding clean-label transition pace and encapsulation technology cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Cholic Acid Market