
 North America Residential Boiler Market | 2026-2036
North America Residential Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Boiler Market Analysis
The gap between premium condensing systems and commodity non-condensing units is realigning procurement patterns across the channel. Viessmann Manufacturing Company Inc. leverages its German engineering heritage to dominate the high-efficiency segment. Bosch Thermotechnology competes through integrated heat pump-boiler hybrid systems. Carrier Global Corporation anchors its position via extensive contractor training networks and aftermarket parts availability.
A residential boiler is a self-contained heating appliance that generates hot water or steam for space heating through hydronic distribution systems, typically operating at pressures between 12 and 30 psi and thermal outputs ranging from 50,000 to 300,000 BTU per hour. The device serves as the central heat generator in forced-hot-water baseboard, radiant floor, and steam radiator configurations found in single-family homes and small multi-unit dwellings. Combi boilers are capturing disproportionate share in urban retrofit markets where space constraints eliminate separate water heater needs. Natural gas-fired condensing technology leads volume but electric boilers represent the fastest-growing fuel category in jurisdictions with aggressive decarbonization mandates. High-efficiency boilers command the dominant margin pool despite higher installed costs, as utility rebates and federal tax credits compress payback periods for consumers.
The U.S. Department of Energy minimum efficiency standards and ENERGY STAR certification requirements shape product design and disqualify legacy non-condensing models from new construction in multiple states. Canada's Natural Resources Office of Energy Efficiency and provincial rebate programs in Ontario and Quebec accelerate cold-climate heat pump and condensing boiler deployment. Builders and contractors must track evolving federal incentive structures and state-level building code adoptions to align inventory and specification practices with compliance timelines.
Market Dynamics
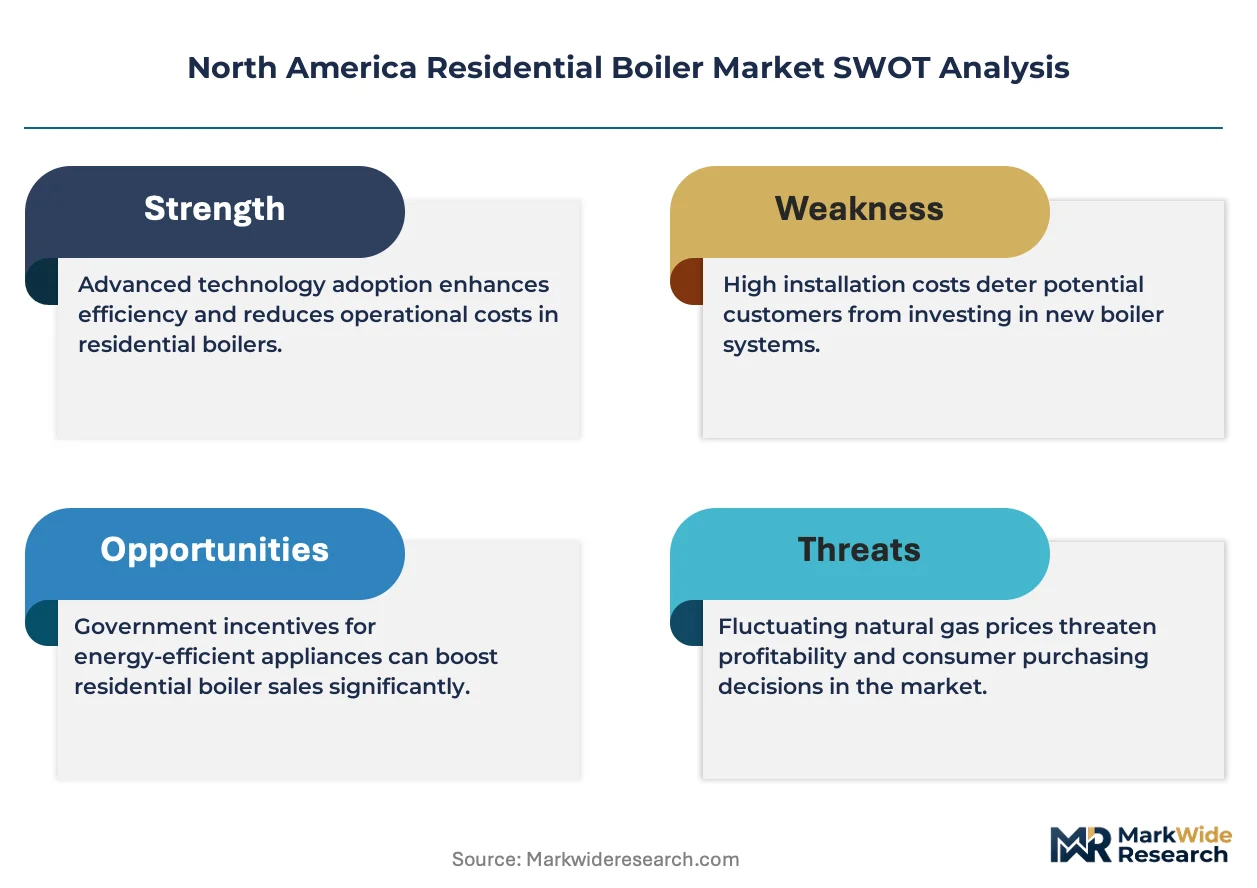
The U.S. Department of Energy's furnace and boiler efficiency standards are forcing condensing technology into the specification baseline, eliminating legacy non-condensing models from new construction pipelines across multiple states. This regulatory compression is reshaping manufacturer R&D allocation and contractor inventory planning simultaneously.
Growth Catalysts
- ENERGY STAR Certification Requirements:The EPA's efficiency benchmarks are disqualifying sub-90 AFUE units from federal tax credit eligibility, redirecting consumer demand toward high-efficiency condensing systems in cold-climate states.
- Canadian Provincial Rebate Programs:Ontario and Quebec utilities are accelerating condensing boiler deployment through point-of-sale incentives that compress payback periods for homeowners replacing aging equipment.
- Hydronic Distribution Retrofits:Steam-to-hot-water conversion projects in century-old housing stock across the Northeastern United States are generating replacement demand for modern modulating boilers.
Market Restraints
- Copper and Stainless Steel Input Volatility:Heat exchanger material costs swing with commodity markets, compressing margin predictability for manufacturers of premium condensing units.
- Condensate Neutralization Complexity:The acidic discharge from high-efficiency boilers requires pH treatment infrastructure that adds installed cost and maintenance burden in retrofit applications.
- Air-Source Heat Pump Substitution:Cold-climate heat pumps achieving sub-zero performance are capturing specification share in jurisdictions with aggressive building electrification mandates.
Strategic Opportunities
- Combi Boiler Urban Retrofits:Space-constrained multifamily dwellings in Boston, Toronto, and Montreal present white space for integrated space-and-water-heating units that eliminate separate tank requirements.
- Heat Pump-Boiler Hybrid Convergence:Dual-fuel systems pairing electric heat pumps with gas-fired backup are qualifying for IRA incentives while addressing capacity gaps in extreme cold.
- Utility Demand Response Integration:Smart-thermostat-enabled load modulation programs in New York and California create recurring revenue streams for connected boiler fleet operators.
Industry Challenges
- Condensing Technician Certification Gap:Proper combustion analysis and venting design require specialized training that outpaces current HVAC apprenticeship pipeline output.
- Legacy Steam System Integration Friction:Century-old single-pipe steam radiators resist retrofit with modern modulating boilers, forcing complex control strategies or full distribution replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Boiler Market |
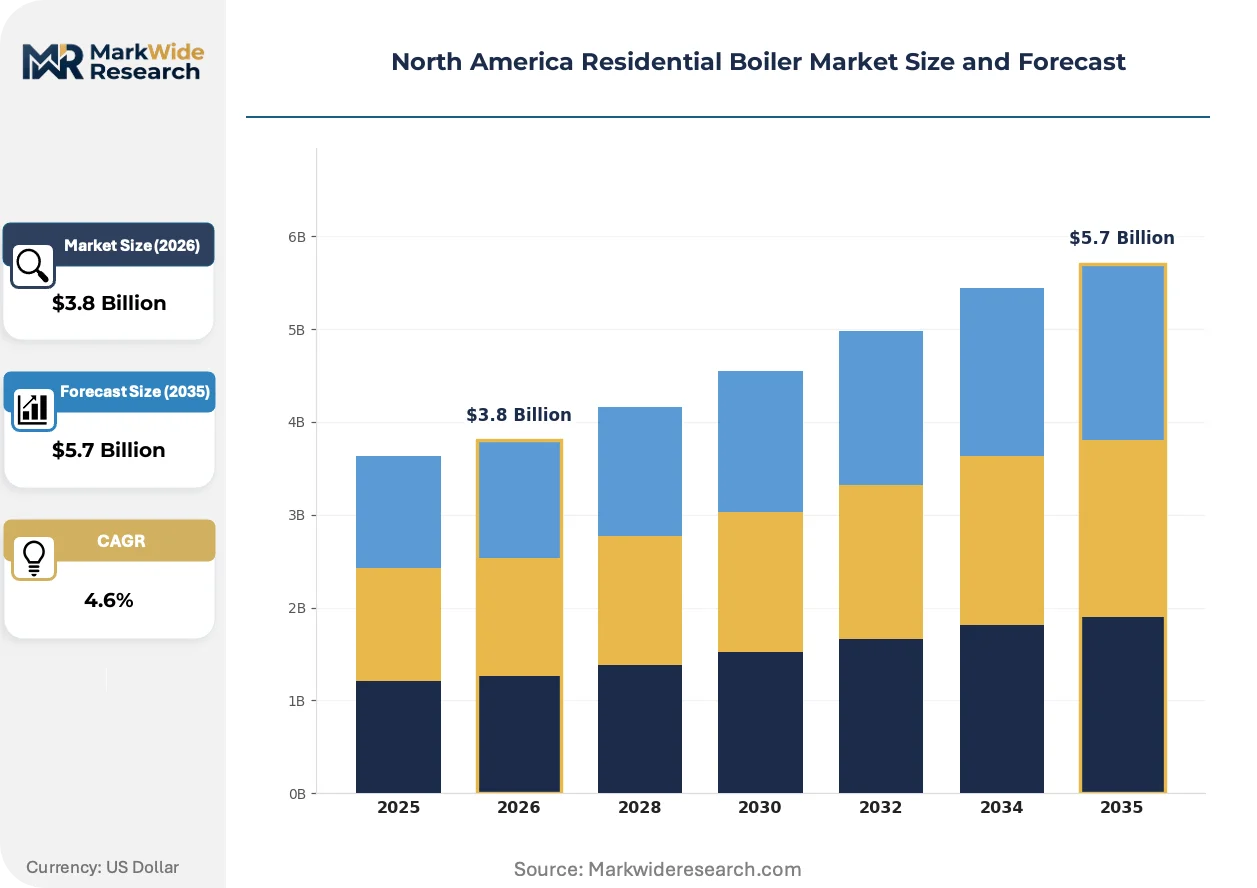
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combi Boiler, System Boiler, Conventional Boiler, High-Efficiency Boiler Fuel Type: Natural Gas, Oil, Electric, Propane Technology: Condensing, Non-Condensing, Modulating, Single Stage End User: Homeowners, Property Managers, Contractors, Builders |
| Companies Covered | Viessmann Manufacturing Company Inc., Bosch Thermotechnology, Carrier Global Corporation, Lennox International Inc., Johnson Controls, Weil-McLain, Navien, A.O. Smith Corporation, Vaillant Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Boiler Market Emerging Trajectories
Condensing combustion architecture is absorbing the central engineering focus across the North American supply base, with control electronics and connectivity modules now commanding disproportionate R&D investment relative to core heat exchange physics.
Modulating burner technology with 10:1 turndown ratios is absorbing static efficiency losses from oversized equipment cycling in partially loaded homes. High-performance envelope retrofits in Vermont and Maine are reducing design-day loads, forcing boilers to operate at fractional capacity for extended shoulder seasons. This operational pattern is absorbing market share toward low-minimum-fire units that maintain condensing mode across broader output ranges.
The U.S. Department of Energy's pending furnace and boiler efficiency standards are tightening minimum AFUE thresholds and test procedure methodologies. Manufacturers are pre-emptively redesigning heat exchanger geometries and combustion air systems to secure certification ahead of compliance deadlines. The Northeastern United States specification channel is responding by accelerating inventory turnover of qualifying models ahead of grandfathering deadlines.
Homeowner specification behavior is fragmenting between contractor-dependent replacement cycles and self-directed research via utility rebate portals. The traditional distributor-contractor channel in Pennsylvania and Ohio faces disintermediation pressure from direct-to-consumer platforms that bundle equipment with certified installer matching. This channel tension is most visible in emergency replacement scenarios where speed-to-install trumps brand loyalty.
North America Residential Boiler Market Segmentation
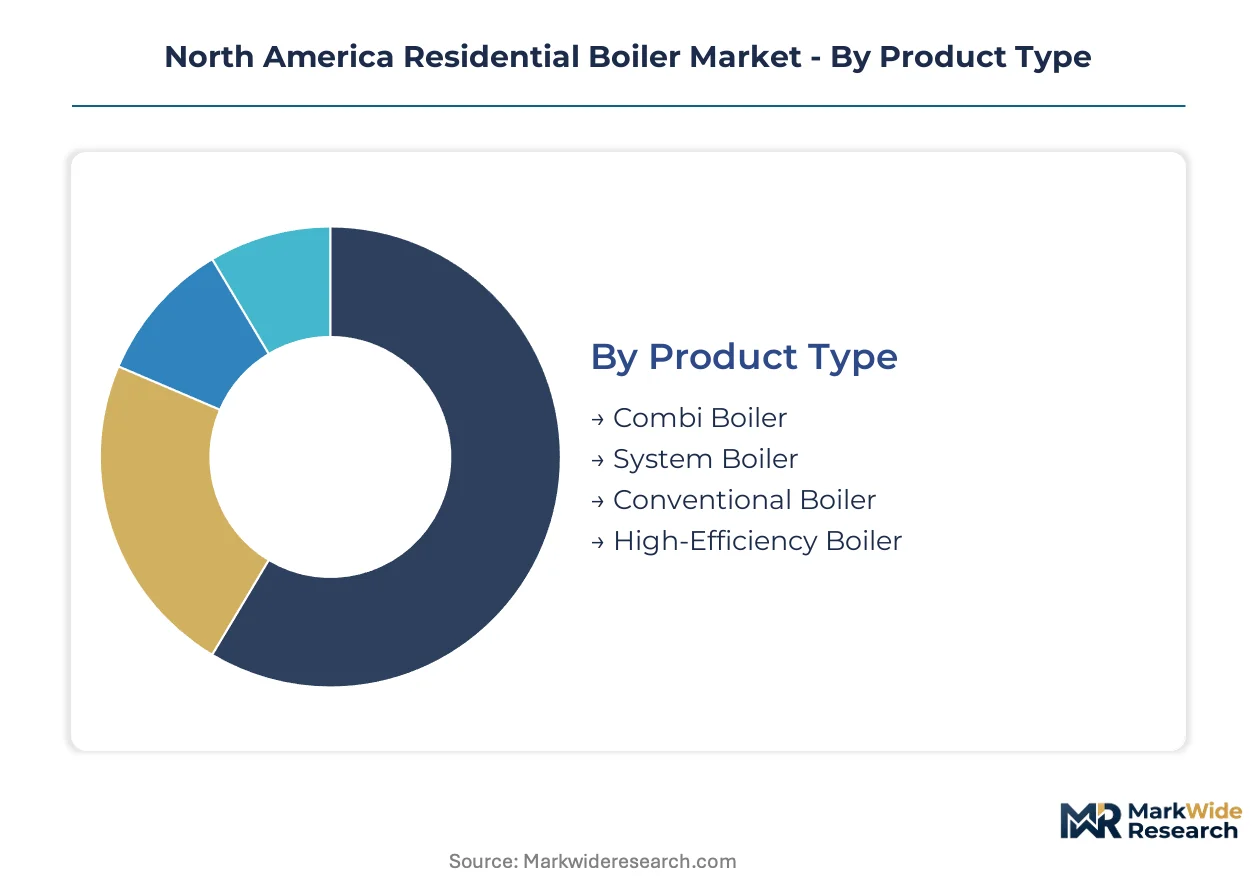
Residential boiler procurement patterns diverge sharply across buyer types, fuel availability, and retrofit versus new construction contexts. Understanding these segment boundaries clarifies where technology investments concentrate and which customer relationships command premium positioning.
Product Type:
Space constraints and hot water integration needs separate urban retrofit buyers from suburban replacement customers.
- Combi Boiler:Integrated space-and-water-heating units eliminate separate tank requirements in multifamily dwellings. Demand concentrates in Boston, Toronto, and Montreal where century-old housing stock with limited mechanical closets requires footprint minimization. The EPA's ENERGY STAR certification thresholds favor these units in federal tax credit calculations.
- High-Efficiency Boiler:Condensing combustion systems achieve AFUE ratings above 90% through secondary heat exchanger recovery. The U.S. Department of Energy's pending efficiency standards are compressing specification timelines in the Northeastern United States as contractors accelerate inventory turnover ahead of grandfathering deadlines.
- System Boiler:Sealed-system designs with integrated expansion vessels suit properties with multiple bathrooms requiring simultaneous hot water delivery.
- Conventional Boiler:Open-vent systems with separate hot water cylinders persist in rural markets with hard water conditions where combi heat exchanger scaling risks dominate replacement decisions.
Volume sits with conventional and system boilers in suburban single-family retrofits; growth tilts toward combi configurations in dense urban housing stock.
Fuel Type:
Pipeline infrastructure density and electrification policy intensity create divergent procurement economics across jurisdictions.
- Natural Gas:Mains-connected properties in the Midwestern and Northeastern United States access the lowest operating cost per BTU. Distribution utility rebate programs in Ontario and Quebec compress payback periods for condensing upgrades in cold-climate zones.
- Electric:Resistance and electrode boilers command specification share in jurisdictions with aggressive building electrification mandates. Vermont and Maine utilities are accelerating deployment through time-of-use rate structures that reward thermal storage integration.
- Oil:Tank-fed systems persist in rural New England and Atlantic Canada where natural gas pipeline extension remains uneconomical.
- Propane:Bulk-tank deliveries serve exurban properties beyond mains infrastructure where heating oil environmental regulations are tightening.
Natural gas retains volume dominance; electric configurations are expanding most quickly in states with renewable portfolio standards exceeding 50%.
Technology:
Regulatory compliance timelines and technician certification requirements stratify specification behavior across customer segments.
- Condensing:Secondary heat exchanger designs recover latent combustion energy to achieve AFUE ratings of 90-98%. The U.S. Department of Energy's furnace and boiler efficiency standards are eliminating non-condensing models from new construction pipelines across multiple states.
- Modulating:Burners with 5:1 to 10:1 turndown ratios match output to partial loads in high-performance envelope retrofits. Vermont and Maine contractors specify these units for shoulder-season efficiency where oversized equipment cycling losses dominate operating cost.
- Non-Condensing:Single-pass heat exchanger designs persist in emergency replacement scenarios where venting modification costs exceed equipment price differentials.
- Single Stage:Fixed-output burners occupy the economy tier in rental property maintenance cycles where capital constraints override efficiency optimization.
Non-condensing units retain volume in emergency rural replacements; specification tilts toward modulating condensing systems in planned retrofits with utility rebate capture.
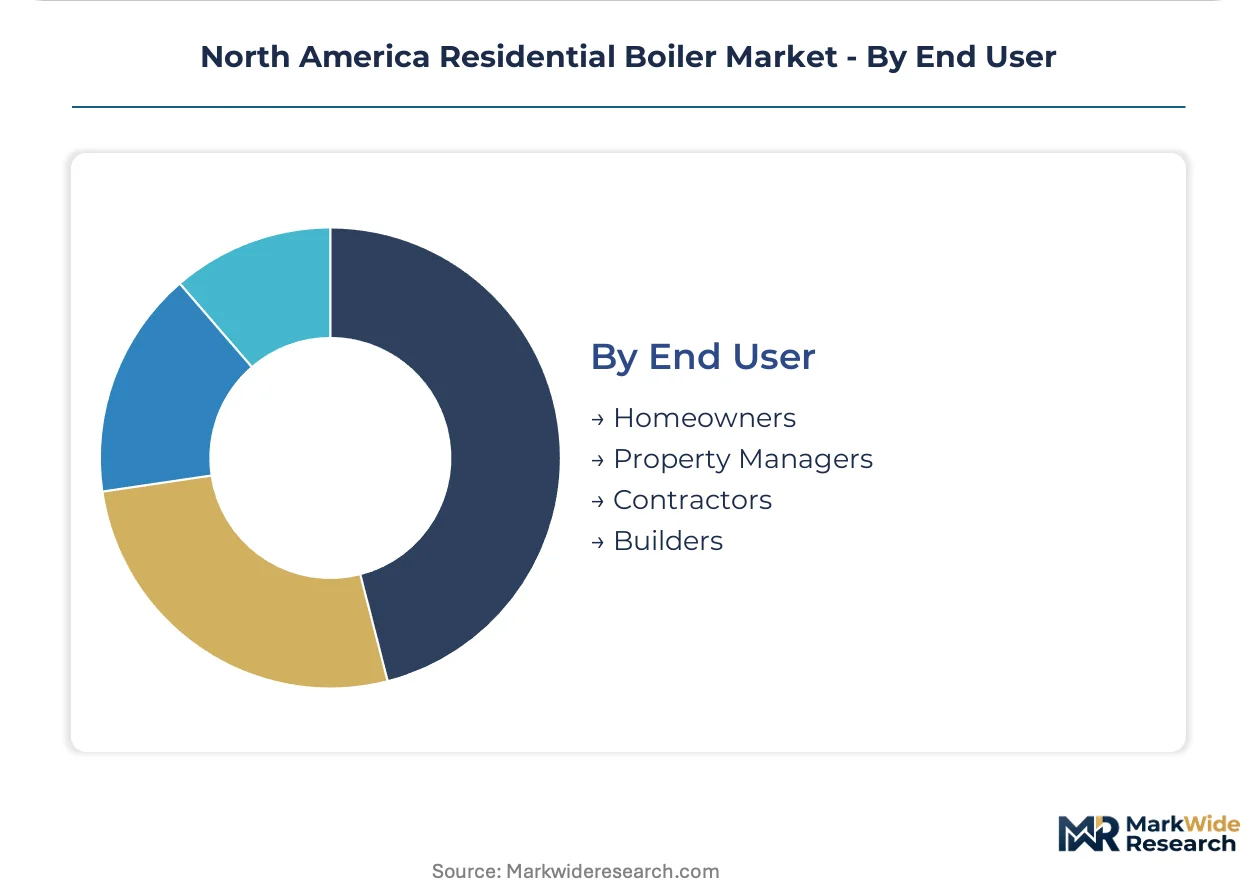
End User:
Decision authority fragmentation and specification knowledge asymmetry create distinct channel engagement requirements.
- Contractors:Licensed HVAC technicians control emergency replacement decisions where speed-to-install trumps brand comparison. Inventory availability and distributor credit terms determine specification outcomes in the Pennsylvania and Ohio markets.
- Builders:Production home developers in Texas and Florida specify builder-grade units where first-cost minimization dominates procurement criteria and warranty transferability secures post-closing risk mitigation.
- Homeowners:Self-directed research via utility rebate portals is fragmenting traditional distributor-contractor channel control in discretionary replacement cycles.
- Property Managers:Multi-unit portfolio operators in Chicago and Minneapolis prioritize standardized fleet configurations that simplify maintenance contractor dispatch and parts inventory.
Contractor influence retains volume in distress replacements; builder and property manager specification is tilting toward connected-system platforms with remote diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast Corridor from Boston to Philadelphia concentrates the densest cluster of hydronic heating retrofits in North America, driven by century-old housing stock and stringent building efficiency codes.
United States
Homeowners across New York, Pennsylvania, and Massachusetts are replacing aging steam systems with modulating condensing boilers. The U.S. Department of Energy's pending AFUE standards are accelerating inventory turnover among distributors in the Northeast. Chicago and Minneapolis represent the strongest Midwestern demand nodes for connected-system platforms with utility demand response integration.
Canada
Ontario and Quebec utilities are deploying point-of-sale rebates that compress payback periods for condensing boiler installations in Toronto and Montreal. Natural Resources Canada's Office of Energy Efficiency coordinates with provincial programs to accelerate cold-climate heat pump and boiler deployment. Vancouver's building electrification mandates are shifting specification toward electric resistance and electrode boilers in new construction.
Mexico
Natural gas infrastructure expansion in the Bajío Region and Northern Border States is enabling condensing boiler adoption in Guadalajara and Monterrey residential developments. Mexico's national energy efficiency standards for appliances are gradually tightening minimum performance thresholds. Mexico City Metro area contractors are specifying compact system boilers for multifamily retrofits in dense urban neighborhoods.
North America Residential Boiler Market Vendor Landscape
Premium-margin players sit above commodity-margin players across engineering heritage and certification complexity. The North American residential boiler market exhibits tiered concentration with German-engineered specialists commanding specification share in high-efficiency segments while North American volume manufacturers dominate emergency replacement channels. Three strategic archetypes define competitive positioning: heritage European engineering houses, integrated HVAC conglomerates with contractor training networks, and Asian-origin efficiency specialists. Dominant competitive moves include portfolio diversification into heat pump-boiler hybrid systems and vertical integration into smart-thermostat connectivity platforms.
Within the heritage engineering tier, Viessmann Manufacturing Company Inc. and Vaillant Group exemplify German-origin positioning anchored to condensing technology leadership. Bosch Thermotechnology occupies a position bridging European engineering credibility with integrated system architectures. Among North American volume players, Carrier Global Corporation and Lennox International Inc. represent the contractor-channel archetype with extensive distribution networks and aftermarket parts availability. A.O. Smith Corporation anchors the water heating crossover segment where combi boiler specification intersects with traditional tank replacement cycles.
| Leading Market Players |
|---|
| Viessmann Manufacturing Company Inc. |
| Bosch Thermotechnology |
| Carrier Global Corporation |
| Lennox International Inc. |
| Johnson Controls |
| Weil-McLain |
| Navien |
| A.O. Smith Corporation |
| Vaillant Group |
| Others |
Supply Flow & Price Mechanics
Copper and stainless steel commodity benchmarks cascade through heat exchanger fabrication costs into three distinct pricing tiers across the North American residential boiler channel. Material volatility compresses margin predictability for condensing unit manufacturers while reinforcing procurement power for vertically integrated producers with captive metallurgical supply.
Pricing Analysis
AFUE-based value pricing anchors manufacturer positioning, with 90-98% efficiency ratings commanding premium positioning against 80-85% commodity units. Price differentiation separates ENERGY STAR-certified condensing systems from non-certified legacy models, with brand heritage and contractor training networks adding secondary tier separation. Pricing pressure stems from utility rebate compression and federal tax credit phase-down schedules, accelerating payback-period sensitivity among replacement buyers. Emergency replacement homeowners in rural markets exhibit highest price sensitivity, while urban retrofit buyers prioritize footprint minimization over first cost.
Supply Chain Analysis
Single-source vulnerability sits with German-engineered heat exchanger specialists for premium condensing combustion systems. Manufacturing concentration centers on Germany, China, and Mexico for core components, with final assembly distributed across U.S. Midwest and Ontario production facilities. Raw material dependencies include copper tubing, stainless steel alloys, and electronic control modules sourced from Asian semiconductor foundries. Tariff exposure on Chinese-sourced control electronics creates margin volatility for modulating burner systems. Distribution runs through HVAC wholesale distributors with contractor credit terms determining specification outcomes in emergency replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America residential boiler market functions as a vertical-integration race where control over heat exchanger metallurgy and smart-thermostat connectivity platforms determines margin capture. Players are pursuing backward integration into copper and stainless steel processing to secure cost predictability.
For Market Incumbents: Deploy captive heat exchanger production capacity to defend margin position against commodity metal volatility. Incumbents should consolidate contractor training certification programs to lock specification loyalty ahead of DOE efficiency standard deadlines. Air-source heat pump substitution in Vermont and Maine represents the primary technology threat requiring hybrid system portfolio expansion.
For New Entrants and Emerging Players: Heat pump-boiler hybrid convergence offers the most penetrable technology wedge for specification share capture. New entrants should target Toronto and Montreal urban retrofit markets where space-constrained multifamily dwellings favor combi boiler configurations. A direct-to-consumer platform bundling equipment with certified installer matching provides the optimal go-to-market angle against legacy distributor channels.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with condensing combustion expertise and utility demand response integration capabilities. Long-term viability hinges on regulatory compliance trajectory and electrification mandate intensity across Northeastern U.S. jurisdictions. The signal to watch is cold-climate heat pump performance threshold improvements that could accelerate substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump-Boiler Hybrid Development | Dual-fuel systems qualify for IRA incentives while addressing capacity gaps in extreme cold. |
| Smart-Thermostat Platform Integration | Connected load modulation programs in New York create recurring revenue for fleet operators. |
| Condensing Combustion R&D Expansion | Secondary heat exchanger redesign secures DOE certification ahead of grandfathering deadlines. |
| Utility Rebate Portal Partnership | Direct channel access fragments traditional distributor-contractor control in replacement cycles. |
| Backward Integration into Metallurgy | Captive copper and stainless supply insulates margin from commodity price volatility. |
Methodological Framework
Multi-period observation of AFUE standard adoption timelines, utility rebate program structures, and condensing technology deployment rates anchored the trend analysis, supplemented by interviews with HVAC contractors, distributor inventory managers, manufacturer product managers, and utility demand response program administrators. Secondary validation drew from DOE efficiency standard filings, EPA ENERGY STAR certification databases, Natural Resources Canada program disclosures, and provincial utility rebate documentation. Bottom-up equipment shipment data triangulated against top-down construction permit and housing stock age demographics.
Input-output matrices mapped fuel type, technology tier, and end-user segment interactions across the projection horizon. Segmentation dimensions included product configuration, combustion efficiency class, fuel source, and buyer decision authority. CAGRs were derived from regression analysis of historical replacement cycles and regulatory compliance schedule impacts. Forecast inputs incorporated housing stock age demographics, building code adoption timelines, and cold-climate heat pump performance trajectories.
Several conditions sit outside the modeled scope, including extreme weather event frequency impacts on emergency replacement timing and federal incentive program legislative renewal uncertainty. Forecasts reflect assumptions about technician certification pipeline expansion and condensate neutralization infrastructure deployment rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
GCC Electric Water Heater Market
Boilers
Marine Boiler Burner Market
Boilers
Industrial Boiler MRO Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
North America Industrial Boiler Market
Boilers
Field Erected Boiler Market
Boilers
District Heating Market
Boilers
Germany Combined Heat and Power Market
Boilers
Reformer Unit Market
Boilers
Boiler Control Solutions Market
Boilers
Advanced Utility Boilers Market
Boilers
Superheater Tubes Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Steam Boiler Market