
 Chromium Phosphate Market | 2026-2036
Chromium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Phosphate Market Analysis
Chinese inorganic chemical producers is realigning capacity toward higher-purity chromium(III) phosphate grades. American Elements leverages its rare and advanced materials portfolio to supply specialty ceramic and electronics grades. Oxkem sustains long-standing relationships with European coating formulators through consistent technical-grade output. Lanxess AG dominates the corrosion-resistant pretreatment segment with its Chemetall surface treatment chemistry expertise.
Chromium phosphate denotes a family of inorganic compounds with the general formula CrPO₄, typically synthesized via precipitation of chromium salts with phosphoric acid at controlled pH to yield crystalline or amorphous products with particle sizes between 1 and 50 micrometers. The material functions primarily as a corrosion inhibitor, pigment opacifier, and ceramic binder across industrial formulations. Powder form occupies the largest volume share due to its direct incorporation into solvent-borne and water-borne coating systems. Flame retardants application represents the fastest-expanding demand pool as building codes tighten across multiple jurisdictions. Chromium(III) phosphate product type captures widening preference as hexavalent restrictions proliferate.
EPA regulates hexavalent chromium emissions under the Clean Air Act and Safe Drinking Water Act, compelling U.S. coating manufacturers to reformulate with trivalent phosphate systems. ECHA administers REACH authorization requirements for chromium(VI) compounds, creating structural headroom for compliant alternatives in European supply chains. China's MEE enforces dual carbon goals that elevate energy and waste standards for inorganic pigment production. Stakeholders must monitor regulatory divergence between trivalent acceptance thresholds and emerging state-level chemical disclosure mandates.
Market Dynamics
REACH authorization requirements for chromium(VI) compounds are forcing European coating formulators to rebuild supply chains around trivalent phosphate systems, compressing reformulation timelines and rewiring procurement relationships.
Growth Catalysts
- Corrosion-resistant coatings demand:Automotive OEMs in Germany specify high-performance anti-corrosive pretreatments for chassis and underbody applications. This specification cascade pulls volume through European supply chains.
- REACH authorization pressure:ECHA's sunset date enforcement for hexavalent chromium creates structural substitution mandates. Trivalent phosphate systems capture displaced volume in industrial coating formulations.
- Flame retardant building codes:Tightening fire safety standards across North American and European construction jurisdictions elevate chromium phosphate deployment in intumescent coatings and polymer additives.
Market Restraints
- Input cost volatility:Chromium metal price swings and phosphoric acid supply tightness compress margin stability for pigment manufacturers. Energy-intensive calcination steps amplify exposure.
- Supply concentration risk:Chinese inorganic chemical producers control intermediate chromium salt capacity. Geographic clustering creates vulnerability to export license adjustments and carbon policy enforcement.
- Substitution threat from organic inhibitors:Benzotriazole and other organic corrosion inhibitors advance in water-borne systems where phosphate compatibility limits apply.
Strategic Opportunities
- Underpenetrated ceramic binder applications:Electronics-grade chromium(III) phosphate for high-temperature refractory binders remains undersupplied outside German and Japanese specialty channels.
- Regulatory tailwind from EPA Safe Drinking Water Act:Maximum contaminant level reviews for hexavalent chromium accelerate U.S. coating house migration to compliant trivalent systems.
- Technology convergence in powder coatings:Electrostatic spray efficiency gains combine with phosphate pigment dispersion advances to displace solvent-borne alternatives in appliance finishes.
Industry Challenges
- Formulation requalification timelines:OEM corrosion test protocols demand 1,000+ hour salt spray validation. Trivalent phosphate reformulations face extended approval cycles with automotive and aerospace primes.
- Technical-grade to electronics-grade purification:Trace iron and calcium removal requires ion exchange and recrystallization infrastructure. Capital intensity constrains mid-scale producer expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Phosphate Market |
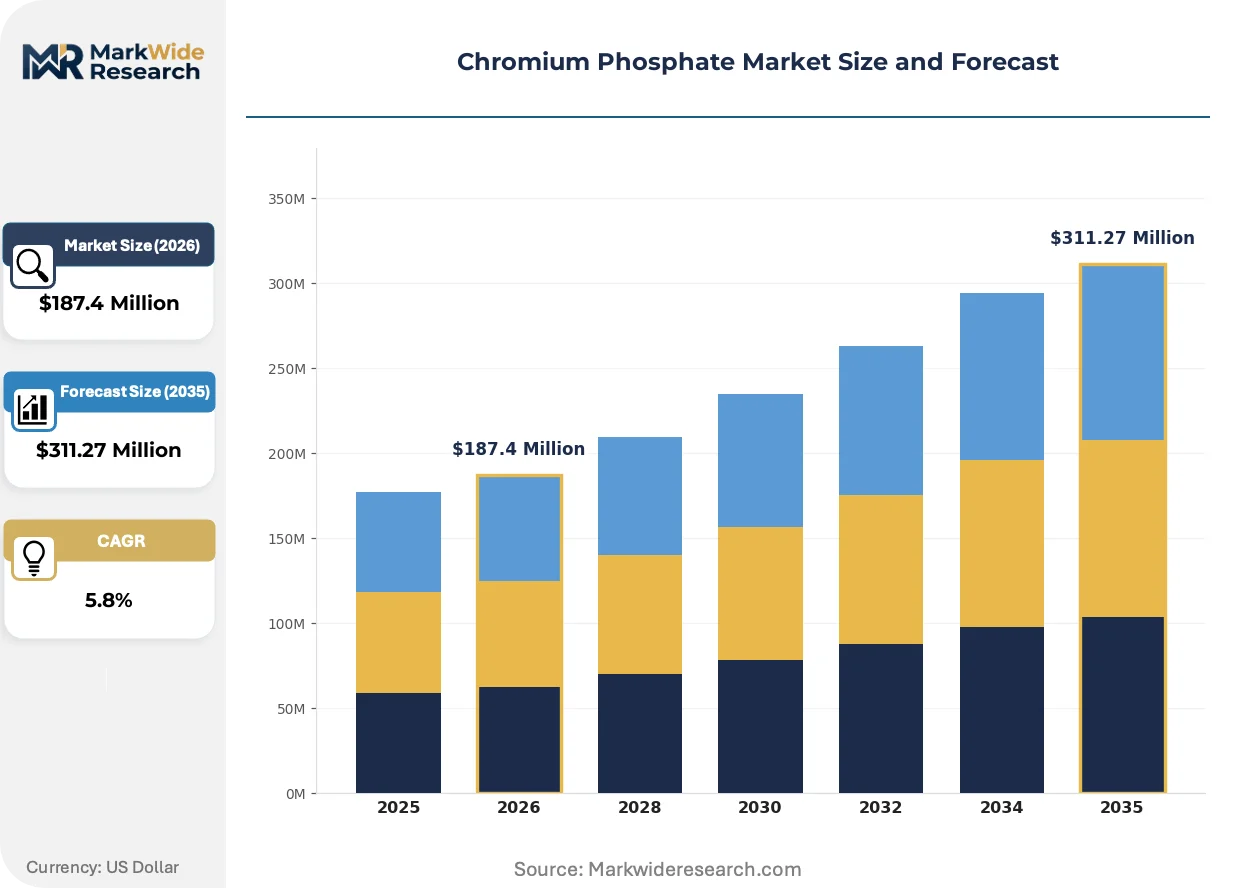
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromium(III) Phosphate, Chromium(VI) Phosphate, Mixed Chromium Phosphates, Hydrated Chromium Phosphate Form: Powder, Granules, Pellets, Liquid Suspensions, Coated Particles Application: Ceramics, Flame Retardants, Catalysts, Corrosion Resistance, Pigments End Use Industry: Coatings & Paints, Electronics Manufacturing, Construction Materials, Adhesives & Sealants |
| Companies Covered | American Elements, Oxkem, Nippon Chemical Industrial Co., Ltd., BASF (Chemetall GmbH), Merck KGaA, Bayer AG, Brenntag, CHEMOS GmbH & Co. KG, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Phosphate Market Emerging Trajectories
Active reformulation across coating houses is compressing product development cycles and elevating technical service intensity as buyers navigate trivalent system qualification.
Nano-scale chromium(III) phosphate synthesis via controlled precipitation is decentralizing pigment performance from traditional bulk manufacturing. Specialty coating formulators in Germany and the United States adopt these grades for thin-film pretreatment layers. The technology is decentralizing supply chain power toward regional compounders with dispersion expertise.
EPA's tightening hexavalent chromium emissions standards under the Clean Air Act are compelling U.S. metal finishing operations to convert pretreatment lines. Industrial consequence includes accelerated capital deployment in trivalent conversion coating equipment. The automotive supplier tier in Michigan and Ohio faces the most compressed compliance timelines, driving technical-grade phosphate procurement.
Direct technical engagement between pigment producers and end-user formulators is displacing distributor-centric purchasing in high-specification segments. Coating houses now demand batch-specific corrosion performance data and salt spray documentation. This shift is most visible in German automotive OEM supply chains where Chemetall-specified pretreatments require validated raw material certificates.
Chromium Phosphate Market Segmentation
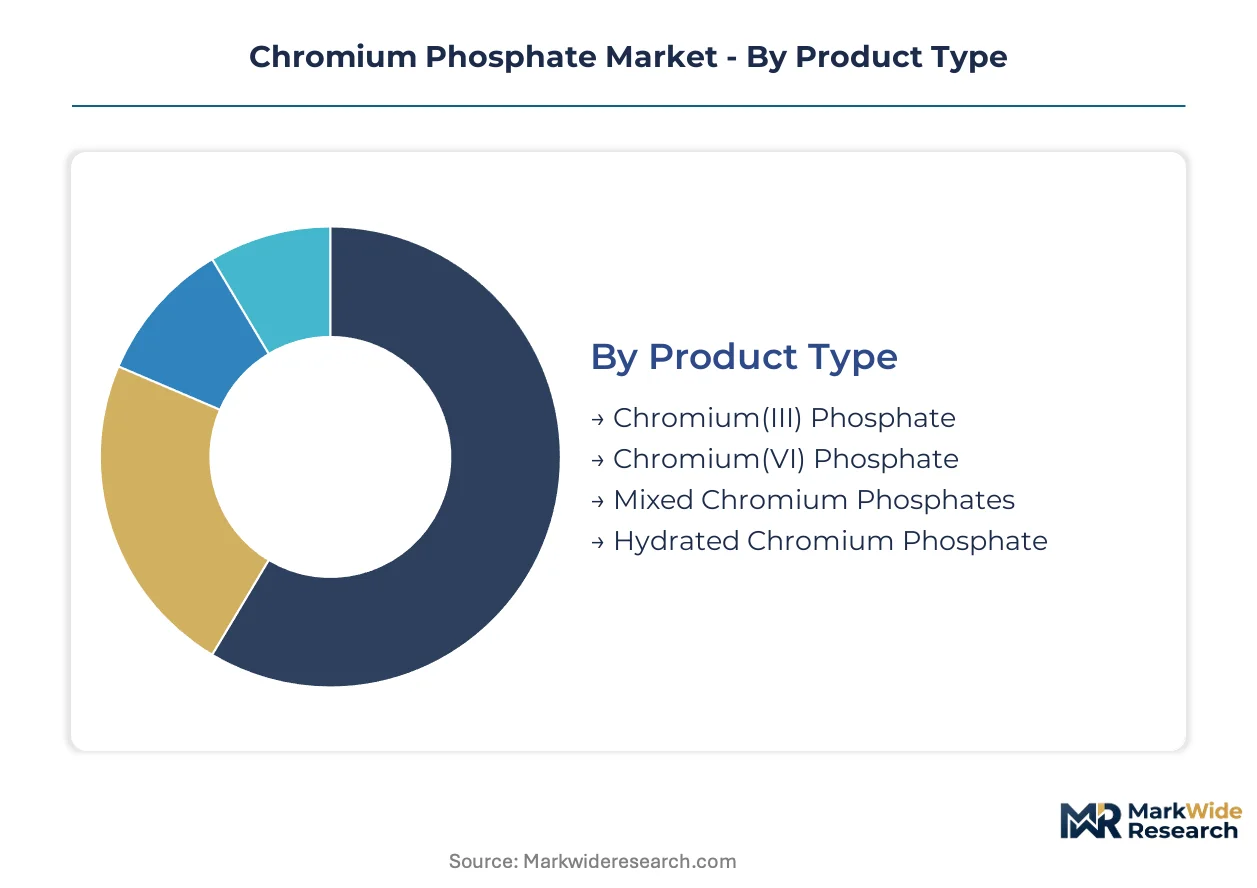
Chromium phosphate segmentation reflects divergent technical specifications across regulatory environments and end-use performance requirements. Product chemistry, physical form, and application intensity determine pricing tiers and supplier qualification protocols. Understanding these segment boundaries clarifies where reformulation investments concentrate versus where legacy volumes persist.
Product Type:
Integration depth varies sharply: Chromium(III) phosphate functions as a direct hexavalent replacement in most coating systems, while mixed and hydrated grades require more complex formulation embedding.
- Chromium(III) Phosphate:Trivalent compound synthesized via controlled precipitation of chromium salts with phosphoric acid, yielding crystalline products with particle sizes between 1 and 50 micrometers. German automotive OEMs specify this grade for chassis pretreatments as REACH authorization deadlines for hexavalent compounds compress reformulation timelines. EPA Safe Drinking Water Act reviews accelerate parallel substitution in U.S. coating houses.
- Chromium(VI) Phosphate:Hexavalent formulation delivering superior corrosion inhibition in salt spray testing but facing structural phase-out across European and North American supply chains. Remaining demand concentrates in aerospace legacy specifications and export-oriented Chinese coating production not yet subject to equivalent regulatory constraints.
- Mixed Chromium Phosphates:Hybrid oxidation state compounds offering intermediate performance characteristics for industrial coating applications.
- Hydrated Chromium Phosphate:Water-containing crystalline forms deployed in ceramic binder and catalyst support applications requiring controlled thermal decomposition profiles.
Chromium(III) phosphate leads volumes today; mixed chromium phosphates are gaining share fastest as formulators seek transitional performance bridges.
Form:
Physical form selection maps directly to coating system architecture: powder and granule grades integrate into solvent-borne and water-borne matrices, while liquid suspensions serve continuous pretreatment lines.
- Powder:Dry particulate with direct incorporation into electrostatic spray and conventional coating systems, dominating volume share through established dispersion infrastructure. Lanxess AG's Chemetall specifications in Germany require validated particle size distributions for automotive pretreatment certification.
- Granules:Agglomerated particles reducing dust exposure and improving handling characteristics in high-volume coating operations.
- Pellets:Compressed forms for controlled-release applications in ceramic processing and specialty catalyst manufacturing.
- Liquid Suspensions:Pre-dispersed aqueous systems eliminating in-plant milling steps for metal finishing operations converting hexavalent pretreatment lines under EPA Clean Air Act enforcement.
- Coated Particles:Encapsulated grades for enhanced compatibility in polymer masterbatches and intumescent flame retardant formulations.
Powder form retains the largest installed base; liquid suspensions are climbing the fastest as U.S. metal finishers accelerate line conversions.
Application:
Application segmentation reveals where performance premiums justify specialized grade qualification versus where commodity specifications dominate procurement.
- Corrosion Resistance:Anti-corrosive pretreatments for automotive chassis, underbody components, and industrial metal finishing. German OEM specification cascades pull volume through European supply chains demanding 1,000+ hour salt spray validation.
- Flame Retardants:Intumescent coating and polymer additive applications expanding most quickly as North American and European building codes tighten fire safety standards.
- Ceramics:High-temperature refractory binders and electronics-grade ceramic processing requiring trace iron and calcium removal through ion exchange purification.
- Catalysts:Support materials and active phase precursors in chemical process industries.
- Pigments:Opacifier and color stabilization functions in coating formulations.
Corrosion resistance anchors current revenue; flame retardants show the steepest expansion trajectory as regulatory tailwinds intensify.
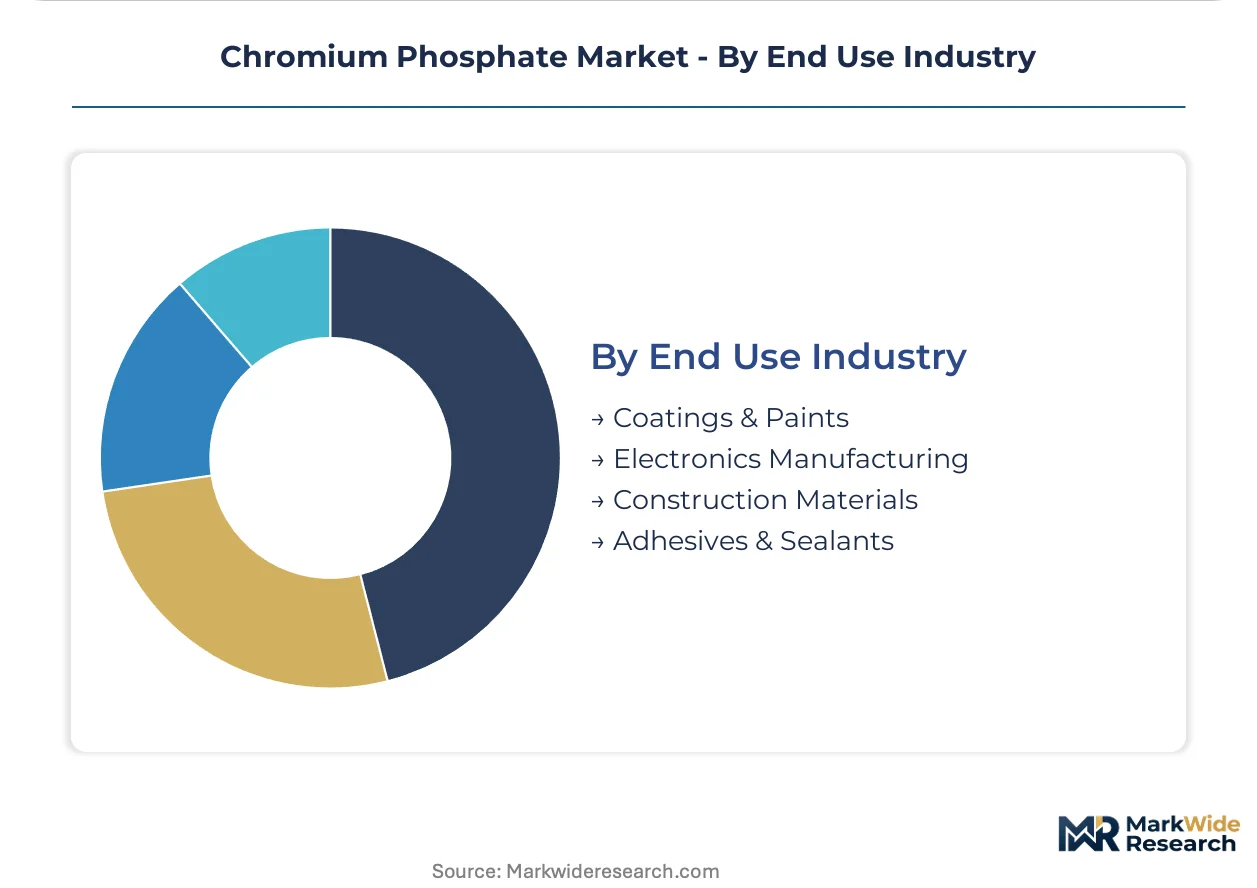
End Use Industry:
End-use concentration determines technical service intensity: coatings and paints demand batch-specific performance documentation, while electronics manufacturing imposes purity thresholds that constrain supplier pools.
- Coatings & Paints:Primary demand channel encompassing automotive OEM specifications, industrial metal finishing, and architectural applications. Direct technical engagement between pigment producers and formulators displaces distributor-centric purchasing in high-specification segments.
- Electronics Manufacturing:Specialty ceramic and refractory binder applications requiring electronics-grade purity with limited qualified supply outside German and Japanese channels.
- Construction Materials:Flame retardant and corrosion protection integration into structural coatings and polymer composites.
- Adhesives & Sealants:Niche incorporation for high-temperature performance and substrate adhesion enhancement.
Coatings and paints command the dominant volume position; electronics manufacturing exhibits the fastest share gain as semiconductor fabrication capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward jurisdictions with lower compliance costs as REACH authorization deadlines compress European reformulation timelines. Chinese inorganic chemical producers capture displaced intermediate demand while German coating houses absorb premium-grade premiums.
United States
Automotive suppliers in Michigan and Ohio face compressed EPA Clean Air Act compliance timelines for pretreatment line conversions. The Safe Drinking Water Act maximum contaminant level reviews accelerate trivalent phosphate procurement from industrial coating manufacturers. Metal finishing clusters around Detroit and Cleveland drive technical-grade volume absorption.
Germany
Automotive OEMs specify Chemetall-validated pretreatments for chassis and underbody applications with 1,000+ hour salt spray requirements. ECHA REACH authorization sunset dates for hexavalent compounds force coating formulators into supply chain rewiring. The North Rhine-Westphalia industrial corridor concentrates qualified pigment qualification and batch-specific documentation capacity.
China
MEE dual carbon goals elevate energy and waste standards for inorganic pigment production while export license adjustments create supply uncertainty. Chromium salt intermediate capacity clusters in Shandong and Jiangsu provinces serve both domestic coating production and international technical-grade demand. Higher-purity chromium(III) phosphate grades attract capacity realignment from commodity producers.
Japan
Electronics-grade ceramic binder applications require trace impurity removal infrastructure concentrated in specialty chemical channels. METI industrial standards for high-temperature refractory materials sustain qualified supplier relationships with limited qualified sources outside domestic production. The Kansai and Chubu industrial regions maintain precision purification capabilities for semiconductor fabrication supply chains.
India
BIS standards for industrial chemical purity create qualification barriers for imported trivalent phosphate grades in corrosion-resistant coating formulations. Construction sector flame retardant demand expands as building code enforcement tightens across Maharashtra and Gujarat industrial zones. Domestic coating formulators navigate technical-grade procurement from Chinese intermediate sources with variable documentation standards.
Chromium Phosphate Market Vendor Landscape
Chinese producers anchor the intermediate and technical-grade tier; German and American specialists hold premium-grade and validated-supply positions. The vendor base splits between scale-driven inorganic chemical conglomerates and dispersion-compounding regional experts. Three archetypes dominate: integrated chromium salt-to-pigment manufacturers, specialty ceramics-grade purifiers, and surface-treatment chemistry formulators. Capacity expansion and strategic technical service partnerships constitute the dominant competitive moves as coating houses demand batch-specific performance documentation.
Within the specialty ceramics-grade tier, American Elements and Nippon Chemical Industrial Co., Ltd. occupy positions exemplifying rare and advanced materials portfolio depth. Lanxess AG anchors the surface-treatment chemistry archetype through its Chemetall specification relationships with German automotive OEMs. Oxkem represents the consistent technical-grade European supplier model sustaining long-standing coating formulator relationships. These three named entities illustrate how geographic specialization and regulatory proximity shape competitive positioning without comprehensive market share concentration.
| Leading Market Players |
|---|
| American Elements |
| Oxkem |
| Nippon Chemical Industrial Co., Ltd. |
| BASF (Chemetall GmbH) |
| Merck KGaA |
| Bayer AG |
| Brenntag |
| CHEMOS GmbH & Co. KG |
| Lanxess AG |
| Others |
Supply Flow & Price Mechanics
EPA Safe Drinking Water Act maximum contaminant level reviews gate both qualified trivalent phosphate supply and premium-tier pricing access for U.S. coating manufacturers converting pretreatment lines. Chinese MEE dual carbon goals simultaneously constrain intermediate chromium salt capacity, compressing technical-grade availability while elevating electronics-grade premiums.
Pricing Analysis
Distributor margins in European coating supply chains compress as direct technical engagement between pigment producers and automotive OEMs displaces traditional procurement channels. Three-tier pricing structure across electronics-grade, automotive-validated, and industrial technical levels reflects ion exchange purification depth and batch-specific salt spray documentation. Pricing pressure stems from chromium metal price volatility and phosphoric acid supply tightness eroding pigment manufacturer margins. Industrial coating formulators exhibit highest price sensitivity due to commodity-grade interchangeability, while German automotive OEMs absorb premium tiers for Chemetall-validated certification.
Supply Chain Analysis
Chromium salt intermediate supply rests on Shandong and Jiangsu province producers in China, with downstream purification capacity clustering in Germany and Japan. Raw material dependencies span chromium metal, phosphoric acid, and ion exchange resins for trace impurity removal. Single-source vulnerability concentrates in Chinese intermediate exports subject to MEE carbon policy enforcement and license adjustments. Distribution runs through direct technical service relationships with coating formulators, displacing distributor-centric models in high-specification segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromium phosphate procurement arbitrage opportunities emerge between Chinese technical-grade production costs and German automotive OEM premium validation requirements. REACH authorization deadlines compress reformulation timelines, rewarding suppliers with established ECHA-compliant supply chains.
For Market Incumbents: Deepen ion exchange and recrystallization infrastructure to capture electronics-grade ceramic binder demand from semiconductor fabrication expansion. Secure backward integration into chromium salt intermediates to mitigate Shandong export license volatility threatening margin stability. Lanxess AG's Chemetall specification relationships demonstrate how validated raw material certificates defend position against emerging dispersion-compounding regional experts. For New Entrants and Emerging Players: Specialty coating compounders in Michigan and Ohio represent the most penetrable channel partner type for liquid suspension grades serving EPA-driven pretreatment line conversions. Target U.S. metal finishing clusters with pre-dispersed aqueous systems eliminating in-plant milling steps. Electronics-grade purity for high-temperature refractory binders remains undersupplied outside German and Japanese channels, offering white-space entry through regional technical service partnerships. For Investors and Strategic Acquirers: Roll-up economics work for regional dispersion-compounding specialists because automotive OEM specification cascades demand validated batch documentation that fragments procurement relationships. Five-to-ten year viability hinges on trivalent substitution permanence as hexavalent regulatory phase-outs structurally displace legacy formulations. Acquisition targets should demonstrate ion exchange purification capability and existing automotive salt spray validation archives. Watch EPA maximum contaminant level enforcement timing as inflection indicator for U.S. technical-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromium Salt Intermediates | Captive supply from Shandong province producers mitigates MEE export license volatility. |
| Ion Exchange Purification Capacity Expansion | Electronics-grade output serves semiconductor fabrication demand from Kansai industrial region. |
| Direct Technical Service Partnerships | Chemetall-validated documentation displaces distributor-centric procurement in German automotive supply chains. |
| Liquid Suspension Product Line Launch | Pre-dispersed aqueous systems accelerate EPA-compliant pretreatment line conversions in Michigan metal finishing clusters. |
| Long-term Supply Agreement with Coating Formulators | Batch-specific salt spray performance data locks in automotive OEM specification cascades. |
Methodological Framework
Multiple input streams — primary interviews with coating formulators and automotive OEM procurement teams, customs and trade data reconciliation, and SEC 10-K filings from specialty chemical producers — were synthesized with ECHA REACH authorization timelines and EPA enforcement disclosures. Plant managers at chromium salt facilities, technical R&D directors at pigment manufacturers, and distribution channel partners across German industrial corridors provided operational validation. Bottom-up volume modeling from end-use application intensity combined with top-down value reconciliation against trade flow data.
Data-stream reconciliation across product chemistry tiers, physical form factors, and end-use industry penetration rates anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed grade purity levels, coating system architecture requirements, and regional regulatory compliance clusters. CAGRs derived from application-specific demand elasticity and substitution pace for hexavalent alternatives. Forecast inputs incorporated automotive production schedules for chassis pretreatment specifications and building code enforcement timelines for flame retardant deployment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE dual carbon policy enforcement intensity and REACH authorization sunset date adjustments. Forecasts reflect documented assumptions regarding trivalent phosphate substitution permanence and automotive OEM qualification protocol stability. Chromium metal price volatility, phosphoric acid supply disruptions, and organic corrosion inhibitor technological advances constitute specific revision triggers. A small set of regulatory enforcement and raw material availability indicators warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Lentein Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Organoclay Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Toner Resins Market