
 Cholesterol Testing Services Market | 2026-2036
Cholesterol Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cholesterol Testing Services Market Analysis
Enzymatic assay chemistry is shifting toward more precise immunoassay and mass spectrometry platforms that reduce interference from abnormal bilirubin or hemoglobin levels. Quest Diagnostics Incorporated leverages its national laboratory network to sustain high-throughput cholesterol panels across employer wellness contracts. Laboratory Corporation of America Holdings anchors its position through extensive payer relationships and patient service center density. Eurofins Scientific competes by extending its clinical diagnostics footprint into direct-to-consumer lipid monitoring channels.
Cholesterol testing services encompass clinical diagnostic procedures that quantify total cholesterol, LDL, HDL, and triglyceride concentrations in blood serum or plasma, typically requiring 8-12 hour fasting protocols and enzymatic colorimetric detection with spectrophotometric readout at 500-550 nm wavelength. These services enable cardiovascular risk stratification, statin therapy monitoring, and metabolic syndrome management across primary care and specialty cardiology settings. Laboratory Testing dominates service type revenue due to reimbursement reliability and physician referral patterns, while Point-of-Care Testing occupies the fastest-expanding segment as urgent care clinics and retail pharmacies install CLIA-waived lipid analyzers. Immunoassays lead technology deployment for routine panels, though Mass Spectrometry differentiates in reference laboratories requiring definitive LDL particle subfractionation for familial hypercholesterolemia workups.
The US FDA oversees in vitro diagnostic device clearance and CLIA complexity categorization that determines where testing may occur, while the Centers for Medicare and Medicaid Services shapes demand through its National Coverage Determination for lipid panels in cardiovascular screening. The Clinical Laboratory Improvement Amendments framework mandates proficiency testing and quality control standards that constrain market entry for uncertified operators. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device for algorithm-driven cardiovascular risk calculators that integrate cholesterol results with other biomarkers.
Market Dynamics
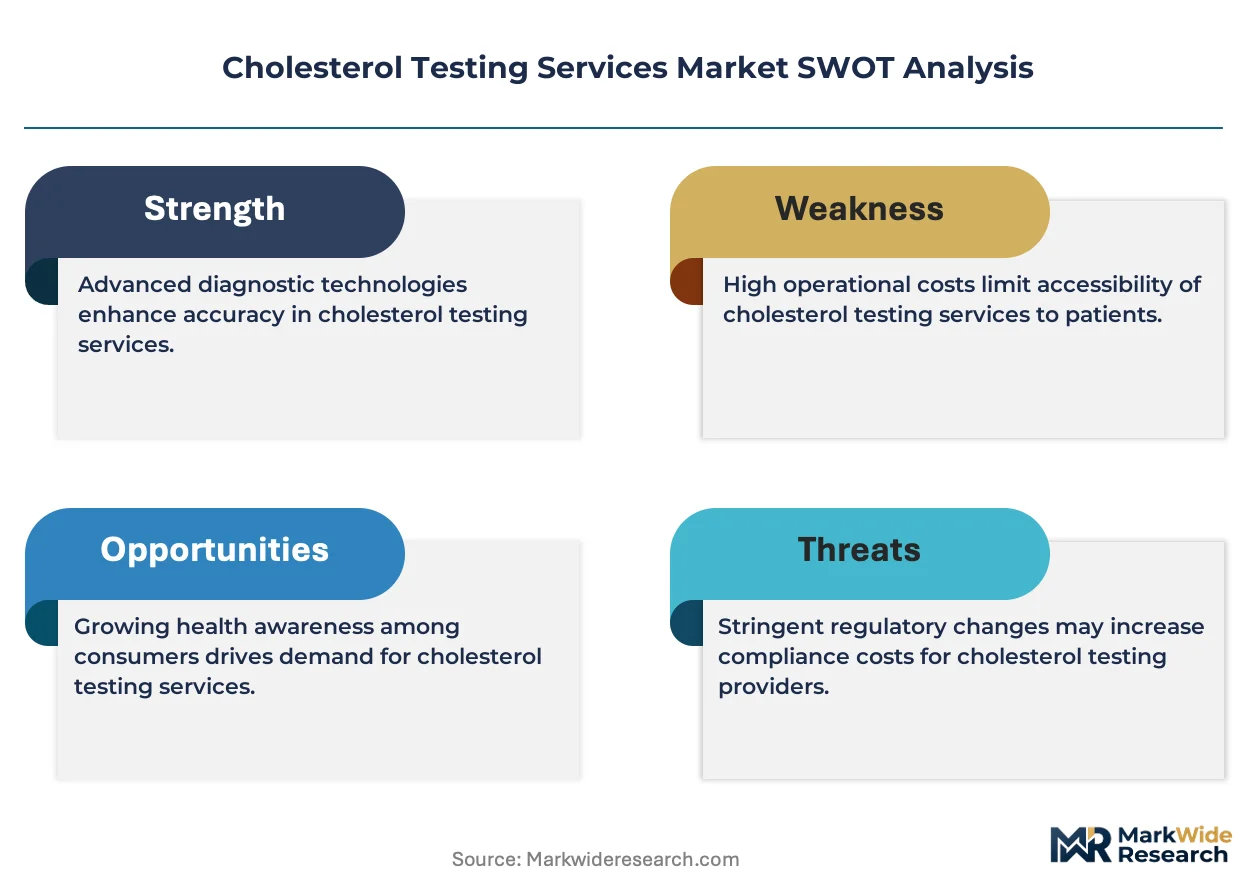
CLIA complexity categorization is fragmenting where cholesterol testing occurs, pushing high-complexity lipid panels into centralized reference laboratories while waiving simpler total cholesterol assays for retail pharmacies and urgent care clinics.
Growth Catalysts
- Employer wellness mandates:Large self-insured employers in the United States now require annual lipid screening as a condition of premium discounts, creating predictable recurring demand for high-throughput testing contracts.
- Mass spectrometry platforms:Definitive LDL particle subfractionation capabilities are expanding diagnostic yield for familial hypercholesterolemia cases that enzymatic methods miss entirely.
- Home-based specimen collection:Dry blood spot cards and mail-in kits are extending testing access to rural populations without proximity to patient service centers.
Market Restraints
- Reagent supply concentration:Three manufacturers control the global supply of high-purity cholesterol oxidase enzymes, creating vulnerability to batch-to-batch variability and price volatility.
- CLIA certification timelines:The 12-18 month proficiency testing validation period for laboratory-developed tests delays market entry for novel lipid biomarker assays.
- Point-of-care accuracy limitations:Capillary whole blood methods demonstrate coefficient of variation exceeding 5% versus 2-3% for venous serum processed through central laboratories.
Strategic Opportunities
- Direct-to-consumer lipid monitoring:Subscription-based platforms integrating continuous glucose monitors with quarterly mail-in lipid panels are capturing health-conscious consumers outside traditional care pathways.
- AI-driven risk calculators:Software-as-a-medical-device algorithms that combine cholesterol results with polygenic risk scores are creating new reimbursement categories for integrated cardiovascular assessments.
- India's diagnostic expansion:Tier-2 and tier-3 cities present underpenetrated demand as private laboratory chains extend specimen logistics networks beyond metropolitan centers.
Industry Challenges
- Mass spectrometry technologist scarcity:Reference laboratories struggle to recruit clinical chemists with LC-MS/MS method development expertise for specialized lipoprotein(a) quantification.
- Interoperability with EHR systems:Point-of-care lipid analyzers require HL7 FHIR integration investments that strain capital budgets for retail pharmacy operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholesterol Testing Services Market |
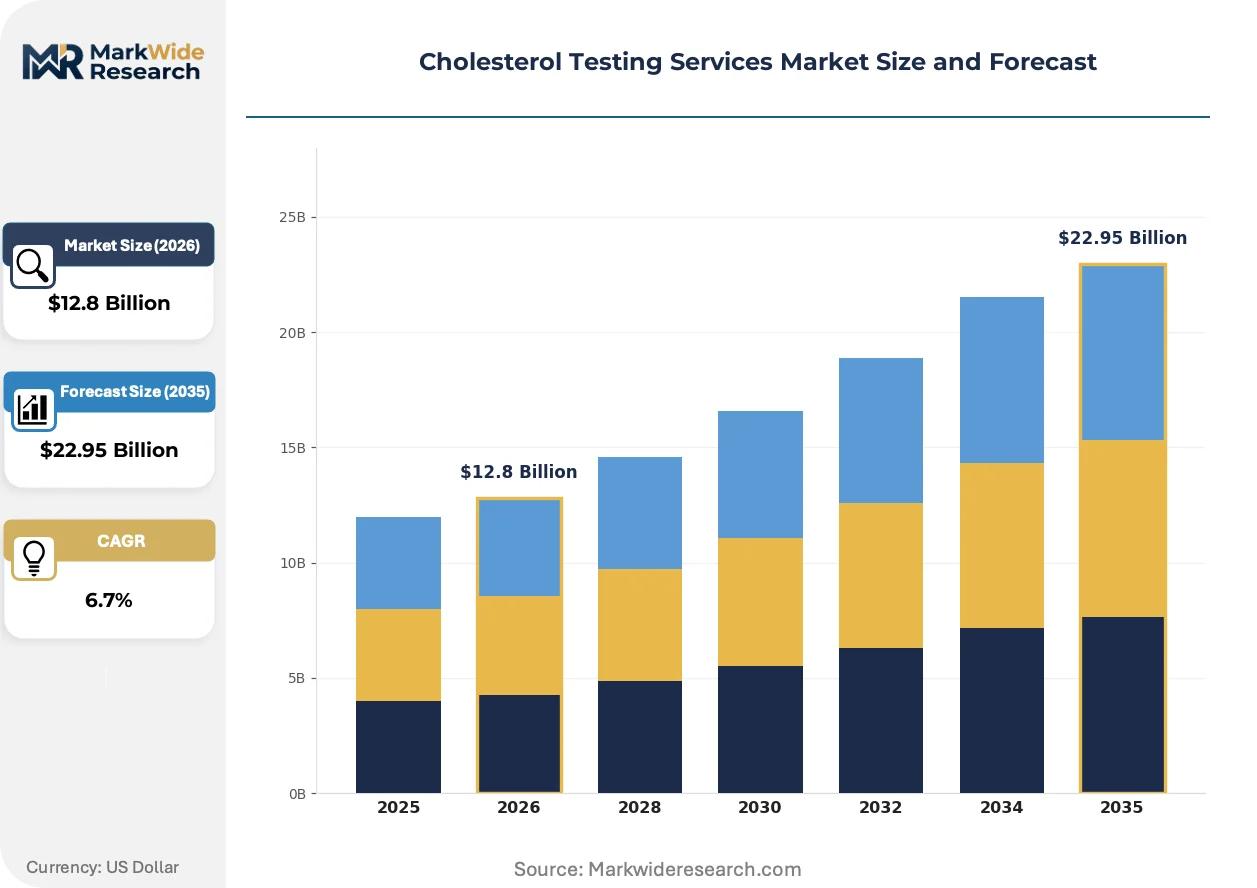
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laboratory Testing, Home Testing, Point-of-Care Testing, Telehealth Services Technology: Enzymatic Assays, Chromatography, Immunoassays, Mass Spectrometry End User: Hospitals, Clinics, Home Users, Diagnostic Laboratories Delivery Mode: In-Lab Testing, At-Home Kits, Mobile Testing Units, Remote Monitoring |
| Companies Covered | Quest Diagnostics Incorporated, Laboratory Corporation of America Holdings, Eurofins Scientific, SYNLAB International GmbH, Spectra Laboratories Inc., Bio-Reference Laboratories Inc., Clinical Reference Laboratory, Inc., Unilabs, ACM Medical Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholesterol Testing Services Market Emerging Trajectories
Digital connectivity is collapsing the distance between specimen collection and result interpretation, enabling real-time cardiovascular risk counseling that was previously confined to synchronous clinic visits.
Multiplexed immunoassay platforms are unifying cholesterol quantification with inflammatory biomarkers such as high-sensitivity C-reactive protein and lipoprotein-associated phospholipase A2. Cardiology practices with in-office laboratories are adopting these consolidated panels to reduce patient touchpoints. This convergence is compressing reimbursement into bundled cardiovascular risk assessment codes rather than discrete test payments.
The FDA's evolving guidance on software-as-a-medical-device is reclassifying algorithmic cardiovascular risk calculators as regulated diagnostic tools. Developers must now submit premarket notifications for AI models that integrate cholesterol values with demographic and clinical variables. Reference laboratories deploying these tools face quality system documentation requirements that extend validation timelines by 6-9 months.
Retail pharmacies are displacing physician offices as the primary site for routine lipid screening among insured populations without established primary care relationships. CVS Health and Walgreens Boots Alliance have installed CLIA-waived analyzers capable of total cholesterol and glucose results within 5 minutes. This channel shift is most pronounced in the United States, where copay structures incentivize pharmacy-based testing over laboratory draws for wellness screenings.
Cholesterol Testing Services Market Segmentation
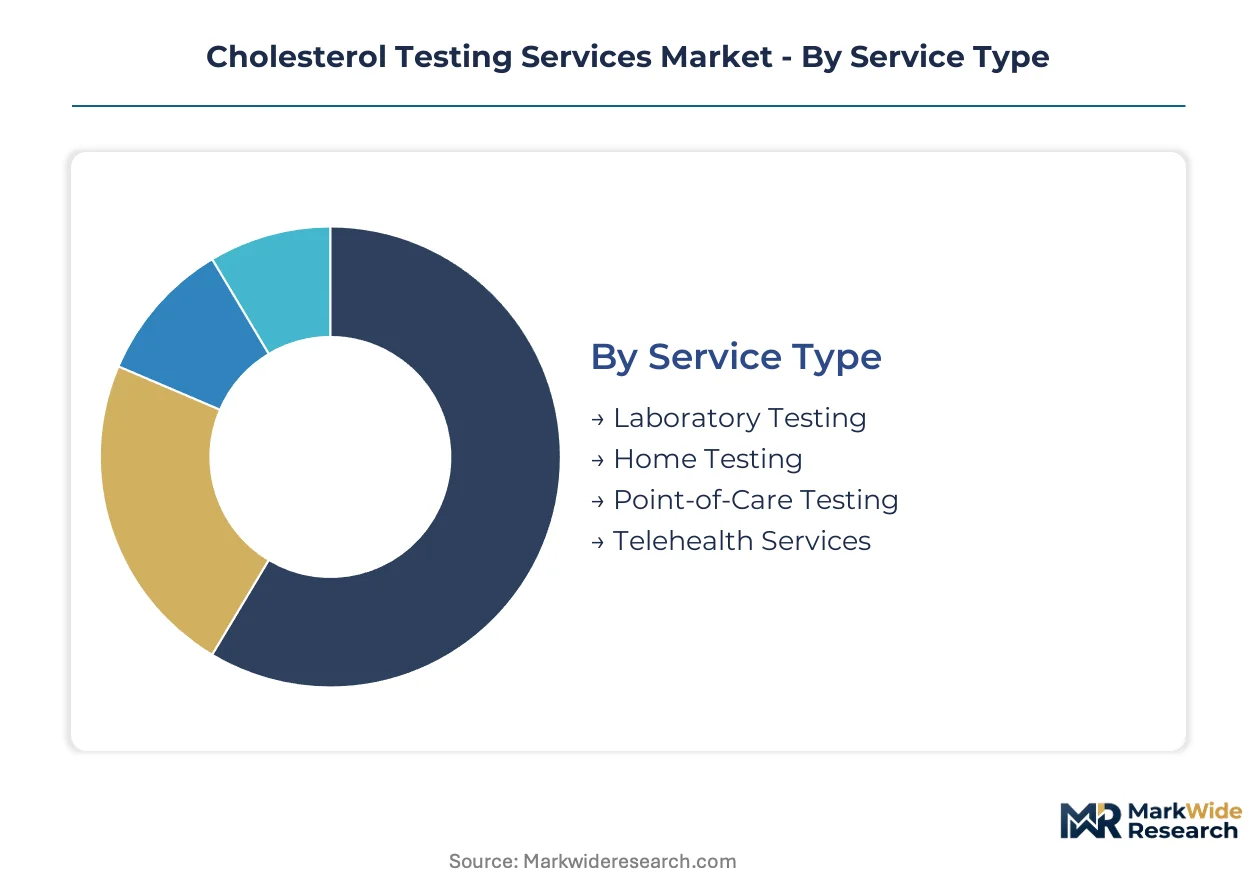
Cholesterol testing services fragment across four distinct dimensions that shape capital deployment, regulatory pathways, and customer acquisition economics. Each segmentation axis reveals divergent margin profiles and infrastructure requirements that determine competitive viability.
Service Type:
Laboratory Testing demands the heaviest upfront capital outlay for CLIA-certified facilities, automated analyzers, and proficiency testing infrastructure. Home Testing and Point-of-Care Testing require lighter fixed-asset bases but carry higher per-unit logistics or consumable costs.
- Laboratory Testing:Centralized facilities process venous serum through high-throughput enzymatic analyzers with spectrophotometric detection at 500-550 nm. Demand concentrates in employer wellness contracts across the United States, where self-insured plans mandate annual lipid panels for premium discounts. CLIA high-complexity certification creates substantial barriers to entry for new operators.
- Home Testing:Dry blood spot cards and mail-in kits eliminate patient service center visits. Expansion is steepest in rural United States counties lacking proximity to Quest Diagnostics or Laboratory Corporation patient access points. FDA 510(k) clearance timelines for collection devices average 180 days.
- Point-of-Care Testing:CLIA-waived lipid analyzers in retail pharmacies and urgent care clinics deliver total cholesterol results within five minutes using capillary whole blood. CVS Health and Walgreens Boots Alliance dominate installed base.
- Telehealth Services:Virtual consultation platforms integrate remote specimen collection with asynchronous result interpretation. Platform economics depend on HL7 FHIR interoperability investments with EHR systems.
Most installed capacity flows through Laboratory Testing. Expansion is steepest in Home Testing.
Technology:
Technology selection determines sensitivity thresholds, interference resistance, and reimbursement coding. Mass Spectrometry and Chromatography command premium pricing for definitive quantification, while Enzymatic Assays and Immunoassays dominate routine screening volumes.
- Enzymatic Assays:Cholesterol oxidase-peroxidase coupled reactions with colorimetric endpoints remain the workhorse for routine panels. Abnormal bilirubin or hemoglobin levels introduce interference that limits accuracy in hemolyzed specimens.
- Chromatography:High-performance liquid chromatography separates cholesterol fractions with superior resolution for reference laboratory validation protocols. Method development expertise constrains deployment to specialized clinical chemistry laboratories.
- Immunoassays:Antibody-based detection platforms unify cholesterol quantification with inflammatory biomarkers such as high-sensitivity C-reactive protein. Cardiology practices with in-office laboratories adopt these multiplexed panels to compress patient touchpoints.
- Mass Spectrometry:LC-MS/MS platforms enable definitive LDL particle subfractionation for familial hypercholesterolemia workups that enzymatic methods miss entirely. Clinical chemist scarcity limits reference laboratory expansion.
Enzymatic Assays anchor routine screening volumes. Mass Spectrometry commands the steepest expansion trajectory for specialized diagnostics.
End User:
End user segmentation reveals divergent procurement patterns and reimbursement reliability. Hospitals and Diagnostic Laboratories secure favorable contracted rates, while Home Users and Clinics navigate more fragmented payment mechanisms.
- Hospitals:Inpatient and emergency department protocols require stat lipid panels for acute cardiovascular events. Laboratory information system integration with EHR platforms drives vendor selection criteria.
- Clinics:Primary care and cardiology practices balance in-office testing convenience against send-out economics for complex panels. CLIA certificate of waiver eligibility determines point-of-care adoption.
- Home Users:Direct-to-consumer subscription platforms bypass traditional care pathways. Health-conscious consumers outside established primary care relationships drive demand for quarterly monitoring regimens.
- Diagnostic Laboratories:National reference laboratories leverage specimen logistics networks and payer contracts for high-throughput processing. Eurofins Scientific extends clinical diagnostics footprint into direct-to-consumer channels.
Diagnostic Laboratories process the highest specimen volumes. Home Users represent the most quickly expanding customer category.
Delivery Mode:
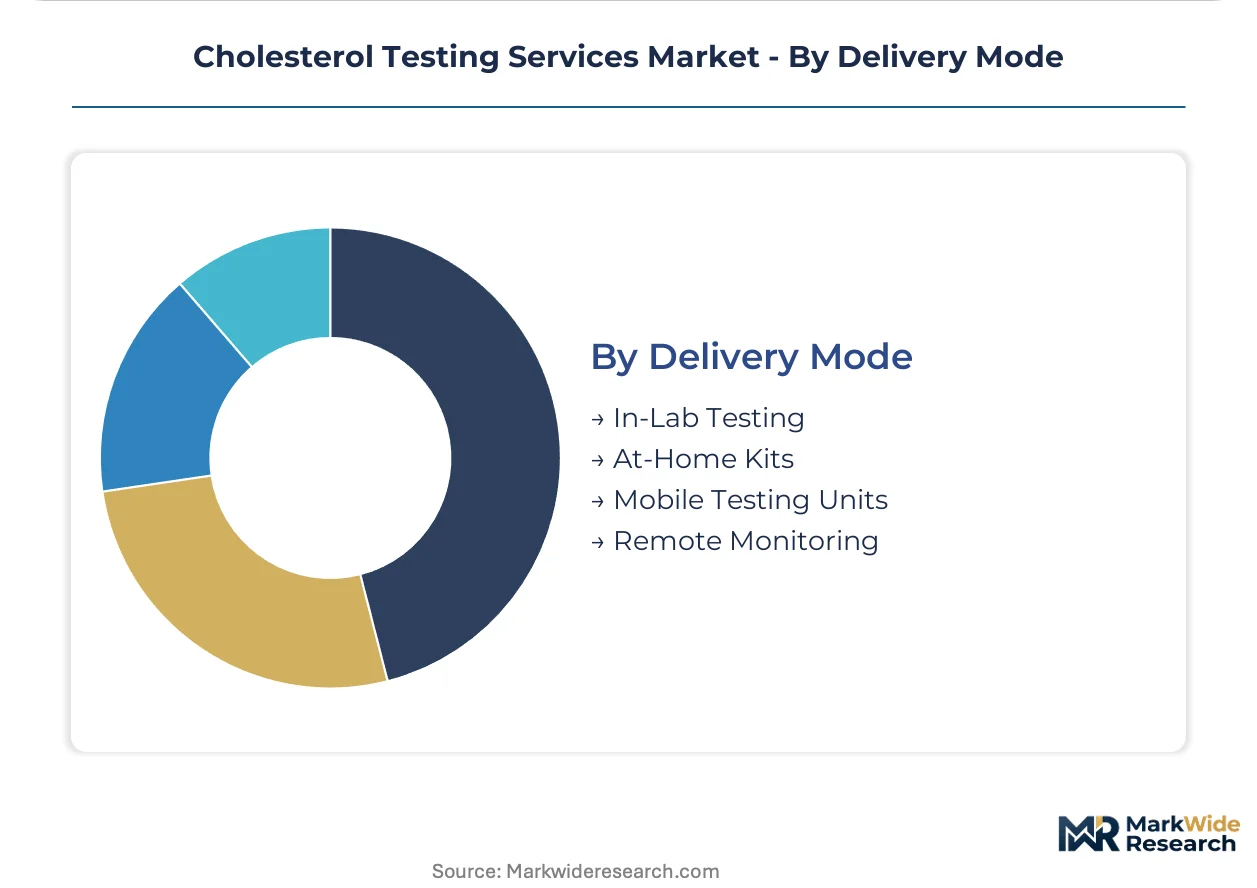
Delivery mode determines patient friction, result turnaround, and regulatory classification. In-Lab Testing and At-Home Kits occupy opposite poles of infrastructure intensity, while Mobile Testing Units and Remote Monitoring occupy emerging intermediate positions.
- In-Lab Testing:Venipuncture at patient service centers ensures specimen integrity through controlled processing chains. United States metropolitan markets exhibit dense network coverage from national laboratory operators.
- At-Home Kits:Finger-stick collection devices with stabilizing matrices enable ambient temperature shipping. Dry blood spot technology extends access to rural populations without laboratory proximity.
- Mobile Testing Units:Employer wellness fairs and community health screenings deploy temporary phlebotomy capacity. Seasonal demand concentration creates utilization challenges for fleet operators.
- Remote Monitoring:Continuous data streams from connected devices integrate with algorithmic risk calculators. FDA software-as-a-medical-device guidance reclassifies these tools as regulated diagnostic products.
In-Lab Testing maintains dominant installed capacity. At-Home Kits are gaining share fastest among delivery modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quest Diagnostics Incorporated anchors laboratory network density across the United States, where employer wellness contracts and aging demographics concentrate testing demand. National reference laboratories leverage CLIA-certified infrastructure to process high-throughput cholesterol panels for self-insured health plans.
United States
Self-insured employers mandate annual lipid screening as a condition of premium discounts, creating predictable recurring demand. The FDA's CLIA complexity categorization determines where testing may occur, pushing high-complexity panels into centralized reference laboratories. Phoenix and Dallas metropolitan markets exhibit dense patient service center coverage from national laboratory operators.
Germany
SYNLAB International GmbH leverages its European laboratory network to process cardiovascular risk panels for statutory health insurance contracts. The EMA's In Vitro Diagnostic Regulation mandates conformity assessment procedures for cholesterol testing devices entering the market. Berlin and Munich host reference laboratory clusters specializing in lipoprotein(a) quantification for familial hypercholesterolemia diagnostics.
United Kingdom
NHS England's cardiovascular disease prevention program drives population-scale lipid screening through primary care networks. The MHRA enforces UKCA marking requirements for in vitro diagnostic devices post-Brexit. London's Harley Street medical district concentrates private diagnostic laboratories serving direct-to-consumer wellness segments.
India
Private laboratory chains extend specimen logistics networks into tier-2 and tier-3 cities beyond metropolitan centers. The CDSCO regulates import and manufacture of diagnostic reagents under the Medical Devices Rules framework. Hyderabad and Bangalore emerge as diagnostic hub cities where national chains establish processing facilities for southern Indian markets.
Japan
Aging demographics sustain demand for cardiovascular risk monitoring through employer-mandated health checkup programs. The PMDA oversees pharmaceutical and medical device approval pathways including cholesterol testing platforms. Tokyo and Osaka metropolitan areas concentrate clinical laboratory capacity for high-throughput enzymatic assay processing.
Cholesterol Testing Services Market Vendor Landscape
Global majors compete with regional champions across laboratory network density and payer contract access. The vendor base clusters around three tiers: national reference laboratories with integrated logistics networks, regional diagnostic chains with concentrated geographic presence, and point-of-care operators deploying CLIA-waived analyzers in retail channels. Strategic archetypes include high-throughput processors, specialized lipid subfractionation providers, and direct-to-consumer platform operators. Competitive moves center on employer wellness contract capture and point-of-care channel expansion into pharmacy retail.
Within the national reference laboratory tier, Quest Diagnostics Incorporated and Laboratory Corporation of America Holdings exemplify scale-driven operators with extensive patient service center networks. Eurofins Scientific occupies a position bridging clinical diagnostics with direct-to-consumer channel development. SYNLAB International GmbH represents European regional champion archetype with statutory insurance contract density. These three entities anchor competitive positioning across distinct geographic and service model vectors.
| Leading Market Players |
|---|
| Quest Diagnostics Incorporated |
| Laboratory Corporation of America Holdings |
| Eurofins Scientific |
| SYNLAB International GmbH |
| Spectra Laboratories Inc. |
| Bio-Reference Laboratories Inc. |
| Clinical Reference Laboratory, Inc. |
| Unilabs |
| ACM Medical Laboratory |
| Others |
Supply Flow & Price Mechanics
Cholesterol oxidase enzyme costs cascade through three pricing tiers, with high-purity reagent batches from United States and German manufacturers commanding premium positioning in CLIA-certified reference laboratories while standard-grade enzymes feed point-of-care consumables at compressed margins.
Pricing Analysis
Input-cost pass-through from reagent manufacturers to testing service providers operates on contract-based long-term offtake structures with annual price adjustment clauses. Price differentiation centers on CLIA certification tier and specimen throughput volume, with high-complexity laboratories capturing premium rates for mass spectrometry panels while retail pharmacy CLIA-waived assays face commoditization. Cost compression in the point-of-care tier is intensifying because capillary whole blood methods compete on convenience rather than analytical precision. Employer wellness contracts demonstrate the lowest price sensitivity due to premium discount mandates, whereas direct-to-consumer home testing users exhibit acute responsiveness to subscription pricing.
Supply Chain Analysis
Dual-sourcing requirements for cholesterol oxidase enzymes mandate qualification of at least two suppliers among the three dominant manufacturers concentrated in the United States, Germany, and Japan. Raw material dependencies center on high-purity cholesterol oxidase, peroxidase stabilizers, and spectrophotometric calibration standards. Single-source vulnerability persists for specialized lipoprotein(a) assay reagents used in familial hypercholesterolemia diagnostics. Distribution runs through national laboratory logistics networks for centralized processing, while retail pharmacy channels rely on direct consumable shipments from device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cholesterol testing services rests on automation-driven cost reduction in high-throughput reference laboratories and premium-tier capture through mass spectrometry subfractionation capabilities.
For Market Incumbents: Hedge against point-of-care commoditization by deepening automation investments in enzymatic assay processing and securing exclusive mass spectrometry technologist pipelines through university partnerships. CLIA certification backlogs for novel lipid biomarkers threaten first-mover advantage in next-generation cardiovascular risk panels. Capacity addition in India's tier-2 and tier-3 cities offers geographic diversification from United States reimbursement compression. For New Entrants and Emerging Players: FDA software-as-a-medical-device guidance in the United States opens a window for algorithm-driven cardiovascular risk platforms that integrate cholesterol results with polygenic scores. Home-based specimen collection in rural United States counties presents the most penetrable white space, bypassing entrenched patient service center networks. Direct-to-consumer subscription models with quarterly monitoring regimens offer the clearest go-to-market angle outside traditional physician referral pathways. For Investors and Strategic Acquirers: Consolidation pressure builds where regional diagnostic chains lack CLIA high-complexity certification for specialized lipoprotein assays. Long-term viability over the coming decade favors operators with integrated logistics networks and payer contract density. Acquisition targets should demonstrate installed mass spectrometry capacity and existing employer wellness relationships. The signal to watch is FDA premarket notification volume for AI-integrated cardiovascular risk calculators, which would indicate regulatory pathway clarity for platform differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | Unlocks mass spectrometry panels for familial hypercholesterolemia diagnostics at premium reimbursement rates. |
| Direct-to-Consumer Platform Launch | Captures health-conscious consumers outside traditional primary care referral channels through subscription models. |
| Employer Wellness Contract Capture | Secures predictable recurring volume from self-insured plans mandating annual lipid screening for premium discounts. |
| Mass Spectrometry Technologist Pipeline Development | Addresses LC-MS/MS expertise scarcity constraining reference laboratory expansion for specialized lipoprotein quantification. |
| AI Risk Calculator Regulatory Submission | Positions software-as-a-medical-device offerings for bundled cardiovascular assessment reimbursement categories. |
Methodological Framework
Multiple input streams — primary interviews with laboratory directors and CLIA compliance officers, regulatory filing analysis, and hospital procurement database review — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed reference laboratory executives, point-of-care device manufacturers, retail pharmacy clinical services leads, and payer medical policy directors. Secondary validation drew from FDA 510(k) clearances, CMS National Coverage Determinations, CLIA proficiency testing records, and employer wellness program disclosures.
Historical volume trajectories were cross-referenced against panel-based growth assumptions across service type, technology platform, end user category, and delivery mode segmentation. The analytical framework modeled expansion across laboratory testing, home testing, point-of-care, and telehealth modalities. CAGRs were derived from regression analysis of specimen volume trends and reimbursement rate evolution. Forecast inputs incorporated employer wellness mandate penetration rates, CLIA certification pipeline timelines, and mass spectrometry platform adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software-as-a-medical-device reclassification delays or cholesterol oxidase supply disruptions. Deviation in employer wellness program participation rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
North America Newborn Screening Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Home Menopause Testing Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Tuberculosis Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Adiponectin Testing Market