
 Processed Peanut Market | 2026-2036
Processed Peanut Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Peanut Market Analytics
The capital-intensity gap between integrated processors and commodity traders is collapsing as automated roasting and oil extraction equipment becomes more accessible. Archer Daniels Midland leverages its crushing network and origination infrastructure to control upstream peanut supply across multiple growing belts. Hampton Farms sustains family-owned brand equity in regional retail channels while competing with national private-label programs. John B. Sanfilippo & Son differentiates through vertical integration into tree nut and peanut blending for foodservice accounts.
Processed peanuts encompass shelled, roasted, blanched, ground, or pressed legumes transformed through thermal, mechanical, or chemical methods for human consumption, with oil content typically ranging from 44% to 56% by weight depending on cultivar and growing conditions. The primary commercial purpose centers on delivering shelf-stable protein, lipid, and flavor inputs to branded food manufacturers and foodservice operators. Peanut butter occupies the largest value share within product type segmentation due to household penetration and institutional procurement contracts, while peanut oil commands premium positioning in high-heat frying applications across Asian and North American foodservice. Confectionery end-use represents a concentrated margin pool where specialized blanching and sizing specifications create supplier stickiness with chocolate manufacturers.
The FDA enforces aflatoxin limits under the Food Safety Modernization Act, requiring hazard analysis and preventive controls for domestic and imported peanut shipments, while the USDA grades raw peanuts for flavor, maturity, and damage to establish pricing baselines for contract negotiations. The F-Gas Regulation in Europe constrains refrigeration choices in cold storage and processing facilities, indirectly affecting peanut butter manufacturing lines that require controlled temperature environments for grinding and filling operations. Stakeholders must monitor evolving mycotoxin testing protocols and energy transition compliance costs as dual pressures that will reshape processor capital allocation and geographic sourcing strategies.
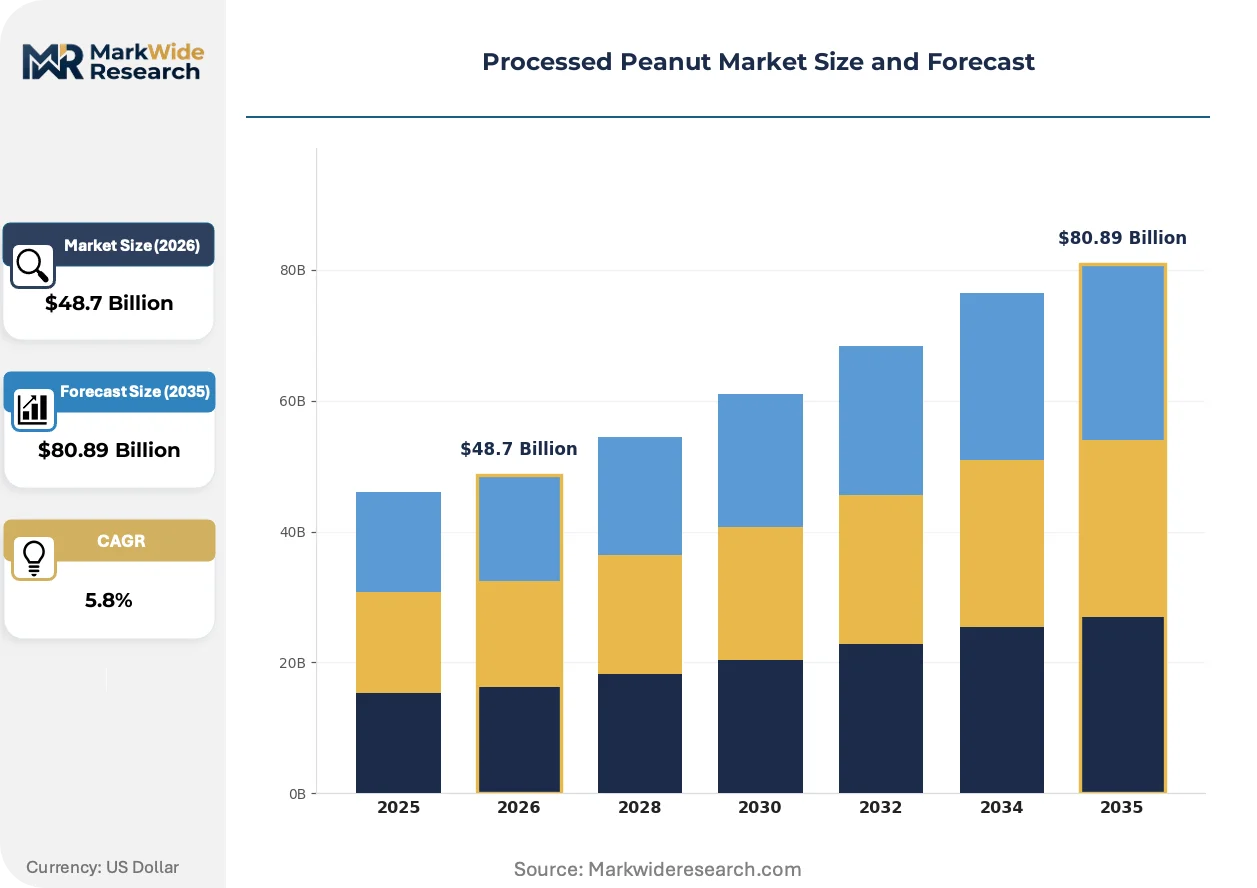
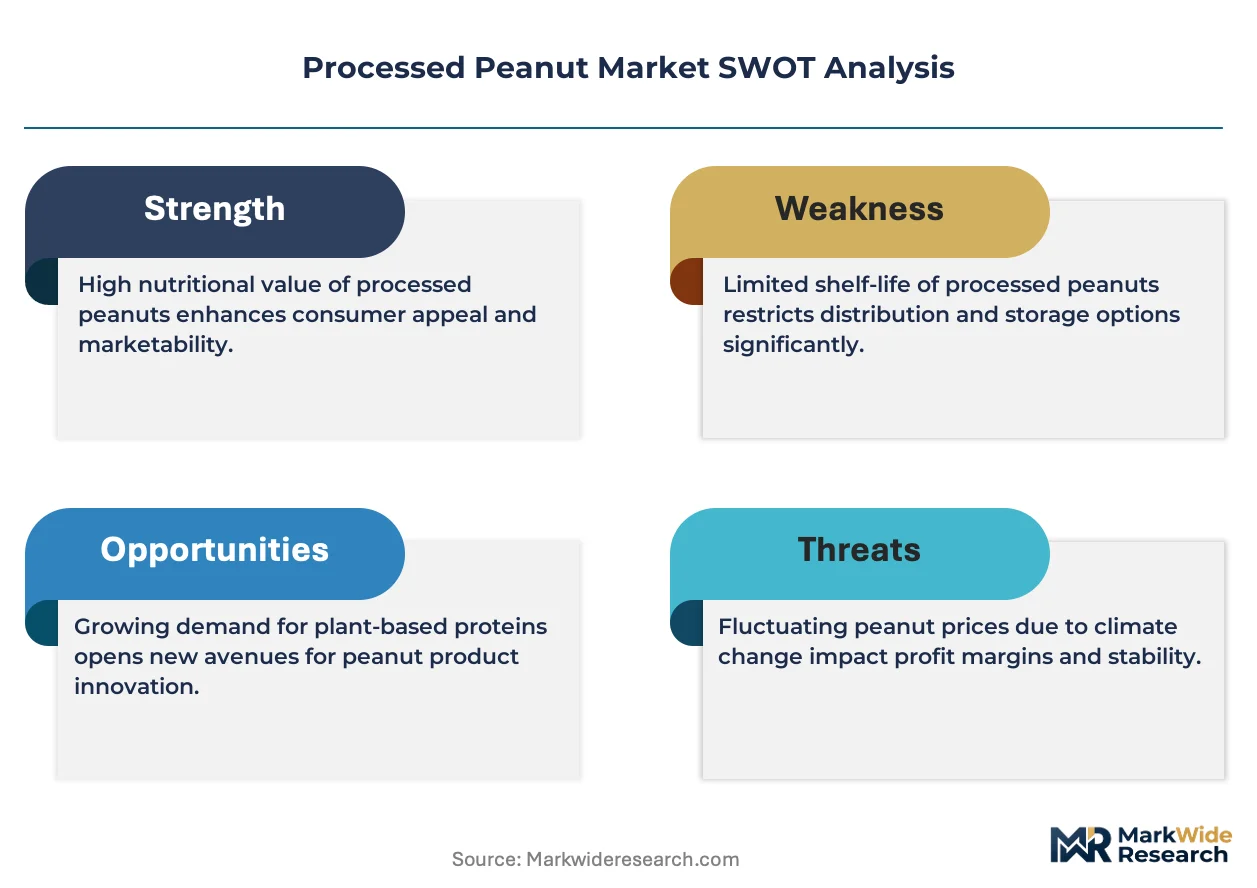
Market Dynamics
The collapse of capital barriers between integrated processors and commodity traders is compressing margin structures as automated roasting and optical sorting equipment becomes accessible to mid-scale operators. This democratization of processing technology is forcing incumbents to defend position through supply chain control rather than scale economies alone.
Growth Catalysts
- Plant-Based Protein Mandates:Foodservice procurement contracts for peanut-derived protein isolates are expanding as institutional buyers meet sustainability targets through legume substitution.
- FDA's FSMA Testing Protocols:Stricter aflatoxin surveillance is accelerating replacement of manual inspection with hyperspectral imaging systems in shelling facilities.
- Peanut Butter Per Capita Consumption:United States household penetration rates sustain baseline demand while roasting capacity investments in Georgia and Texas expand domestic supply security.
Market Restraints
- Input Cost Volatility:Drought cycles in Argentina and Brazil concentrate raw peanut pricing power among origin traders, compressing processor margins during deficit years.
- Aflatoxin Technical Limitation:Pre-harvest contamination from Aspergillus flavus remains irreversible through post-harvest intervention, capping achievable food safety yields.
- F-Gas Refrigeration Constraints:European cold storage facilities face retrofit costs under EU F-Gas Regulation, raising peanut butter manufacturing overhead in controlled-temperature grinding operations.
Strategic Opportunities
- Asian Foodservice Peanut Oil Demand:High-heat frying applications in China and Vietnam create premium positioning for refined peanut oil outside traditional commodity channels.
- Confectionery Blending Specifications:Specialized blanching and sizing protocols for chocolate manufacturers generate supplier stickiness through technical qualification barriers.
- USDA Grade-Based Contracting:Flavor and maturity grading standards enable price discovery mechanisms that reward quality-differentiated sourcing investments.
Industry Challenges
- Optical Sorting Technician Scarcity:Operation of hyperspectral and color-sorting equipment requires specialized calibration expertise that outpaces vocational training pipeline output.
- Legacy ERP Integration Friction:Traceability requirements under FSMA preventive controls rules force peanut processors to reconcile batch-level data with decades-old inventory management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Peanut Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peanut Butter, Roasted Peanuts, Peanut Oil, Peanut Flour End Use Industry: Food & Beverage, Bakery, Snacks, Confectionery Packaging Type: Jars, Pouches, Cans, Tubs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Hormel Foods, PepsiCo Inc., John B. Sanfilippo & Son, The Kraft Heinz Company, Archer Daniels Midland Company, Frito-Lay North America, Whitley's Peanut Factory, Hampton Farms, Haldiram's India Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Peanut Market Evolving Landscape
Processing technology convergence with food safety automation is restructuring competitive advantage around contamination prevention rather than detection. Equipment vendors and processor operators are co-developing integrated systems that embed hazard analysis directly into production workflows.
Hyperspectral imaging systems paired with AI-driven defect classification are supplanting manual kernel inspection and legacy color-sorting machines in high-volume shelling operations. Major peanut butter manufacturers in the United States are adopting these systems at replacement cycle intervals. The technology is compressing labor costs while tightening aflatoxin compliance margins that previously required multiple processing stages.
The EU F-Gas Regulation is forcing refrigeration-dependent processing lines toward ammonia and CO2 cascade systems in cold storage and grinding facilities. European peanut butter manufacturers face capital reallocation toward alternative refrigeration architectures. Blanching and pasteurization equipment suppliers in Germany and the Netherlands are responding with integrated heat-recovery designs that reduce refrigeration load.
Foodservice operators are consolidating procurement through direct contracts with regional roasters, bypassing traditional distributor intermediaries that previously aggregated peanut butter and peanut oil supply. Institutional buyers in K-12 and healthcare channels are negotiating multi-year supply agreements with specified origin and roasting profiles. This concentration is most visible in the southeastern United States, where roasting capacity expansion enables geographic proximity contracting with end-users.
Processed Peanut Market Segmentation
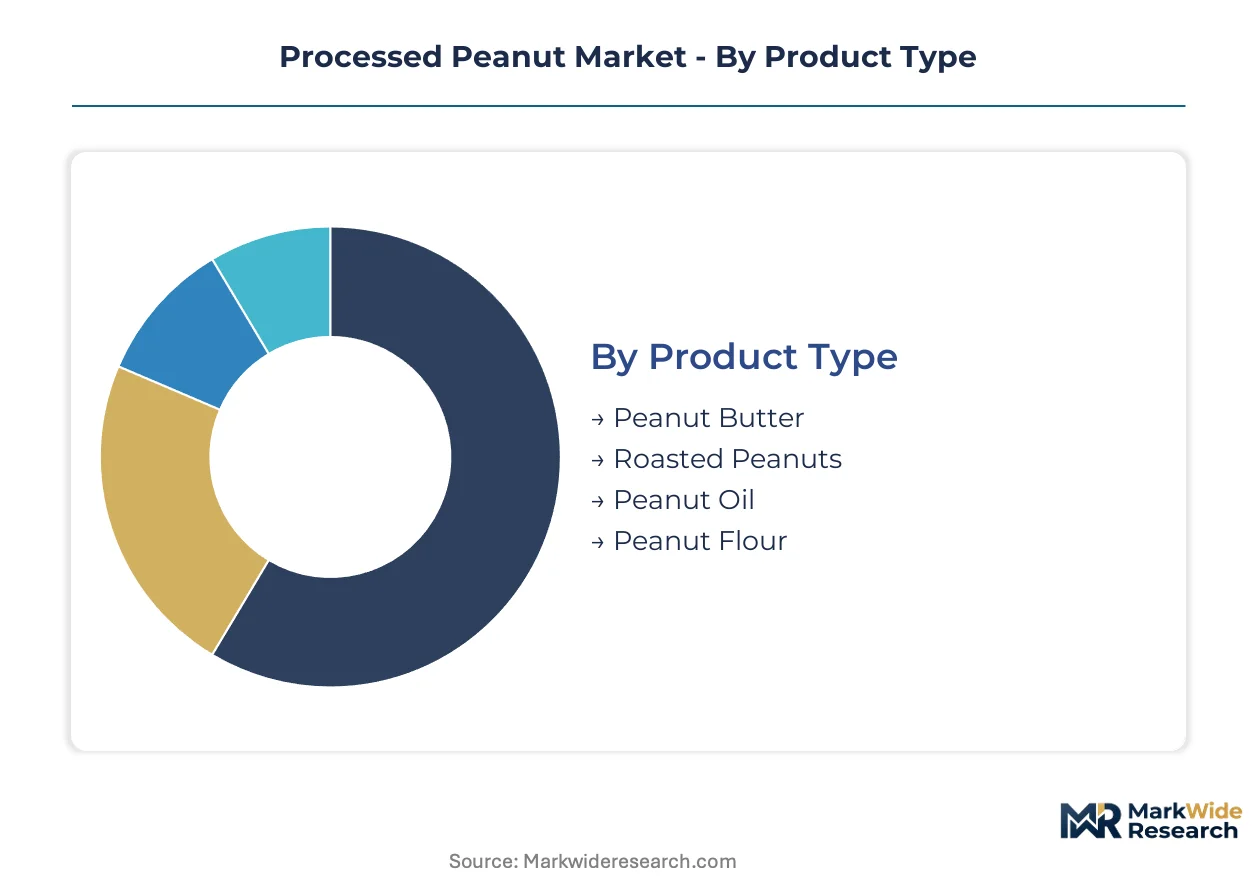
Processed peanut segmentation reveals divergent margin structures across product formats and channel access. Manufacturers configure production assets around specific end-use specifications rather than generic commodity output.
Product Type:
Peanut butter and peanut oil anchor domestic consumption in the United States, while roasted peanuts and flour concentrate in export-oriented processing corridors.
- Peanut Butter:Ground paste with 44-56% oil content stabilized through hydrogenation or natural separation protocols. United States household penetration sustains baseline demand while institutional procurement contracts with K-12 and healthcare foodservice operators expand volume.
- Peanut Oil:Refined high-oleic and conventional varieties differentiated by smoke point specifications. Asian foodservice operators in China and Vietnam drive premium positioning for high-heat frying applications outside commodity channels.
- Roasted Peanuts:Thermal-treated kernels for direct consumption and ingredient applications. Snack manufacturers source specified roast profiles for private-label programs.
- Peanut Flour:Defatted powder with 12-28% residual oil content for protein fortification. Plant-based protein formulators specify particle size distributions for beverage and bakery integration.
Peanut butter commands the established base. The steepest expansion runs through peanut oil.
End Use Industry:
Cost tier differentiation separates commodity ingredient supply from technical specification markets with qualification barriers.
- Food & Beverage:Broad-category procurement spanning peanut butter spreads, protein isolates, and beverage emulsions. CPG manufacturers consolidate supplier lists under FSMA preventive controls compliance requirements.
- Confectionery:Specialized blanching, sizing, and moisture specifications for chocolate enrobing and inclusion applications. Technical qualification protocols create supplier stickiness with Mars Wrigley and Ferrero procurement systems.
- Bakery:Peanut flour and paste applications in cookies, crackers, and bread formulations. Artisan and industrial channels diverge on aflatoxin certification requirements.
- Snacks:Roasted in-shell and flavored kernel products for retail and foodservice distribution. Regional roasters compete with national private-label programs on origin transparency claims.
Food and beverage absorbs the volume base. Confectionery captures the margin premium.
Packaging Type:
Volume concentration favors single-serve and bulk formats for institutional channels, with retail premiumization driving material specification divergence.
- Jars:Glass and PET containers for retail peanut butter with tamper-evident closures. United States supermarkets specify recycled content thresholds under corporate sustainability mandates.
- Pouches:Flexible film structures for single-serve peanut butter and resealable roasted peanut formats. Foodservice distributors favor portion-control packaging for K-12 and healthcare channels.
- Cans:Tinplate and composite containers for peanut oil and bulk roasted peanut export shipments. Ocean freight efficiency drives standardization around 20-liter and 200-liter capacities.
- Tubs:Polypropylene and paperboard structures for foodservice peanut butter and industrial ingredient volumes. Commercial bakeries specify wide-mouth designs for scooping efficiency.
Jars dominate retail shelf presence. Pouches gain share fastest in foodservice contracting.
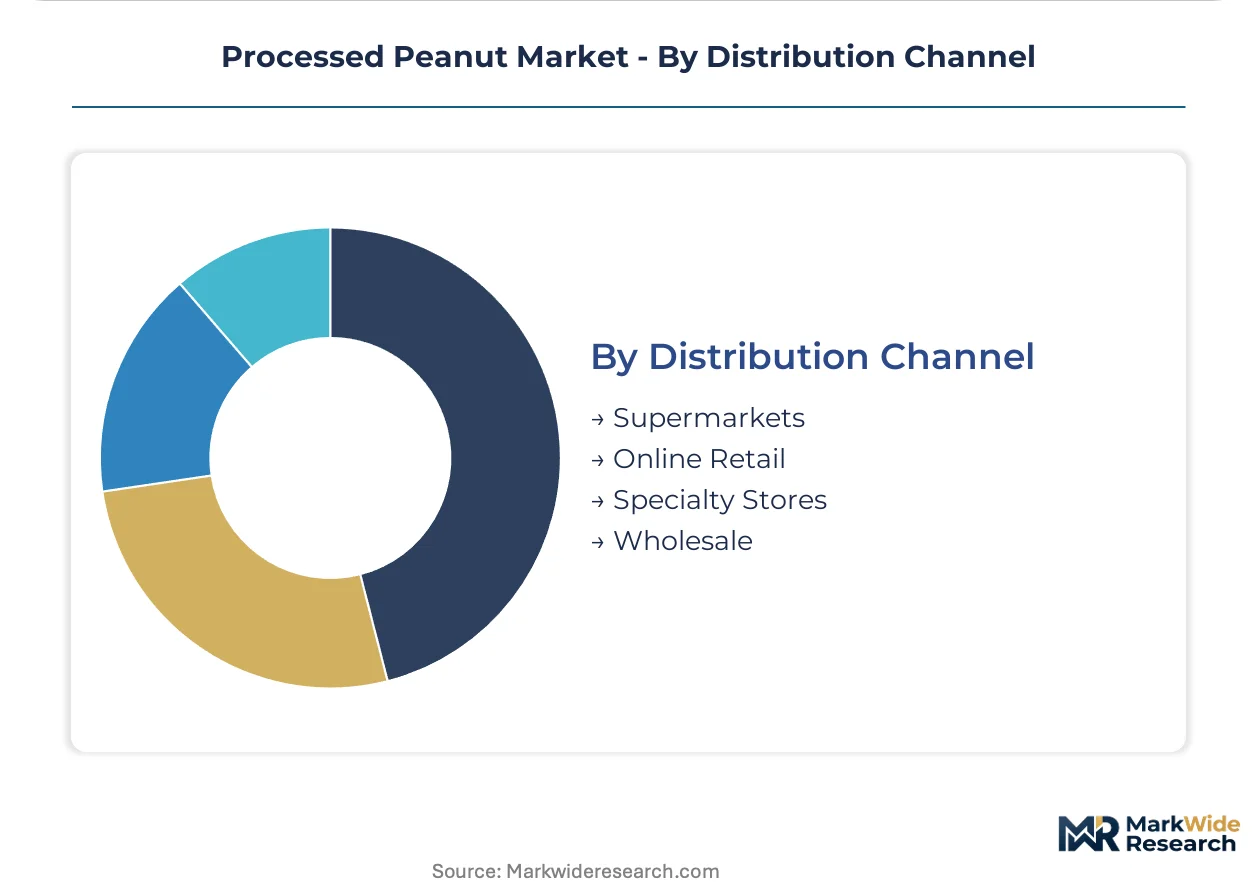
Distribution Channel:
Customer type fragmentation separates procurement decision-makers with divergent specification authority and volume consolidation patterns.
- Supermarkets:Retail grocery and mass merchandiser shelf placement governed by slotting fees and category management protocols. Regional peanut butter brands compete for private-label manufacturing contracts.
- Wholesale:Broadline and specialty foodservice distributors aggregating peanut oil and butter for restaurant and institutional accounts. Sysco and US Foods specify origin documentation and roast profile consistency.
- Online Retail:Direct-to-consumer and marketplace platforms for specialty and subscription peanut products. Amazon and Thrive Market certification requirements filter supplier participation.
- Specialty Stores:Natural products and ethnic grocery channels for organic, heirloom variety, and import-labeled peanuts. Whole Foods Market regional buyers enforce non-GMO and fair trade verification standards.
Supermarkets and wholesale together anchor volume throughput. Online retail expands most quickly in premium and specialty positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Argentine and Brazilian origin traders during drought cycles, while United States processors absorb margin compression through vertical integration into roasting and retail distribution networks.
United States
Peanut butter per capita consumption sustains the world's highest household penetration rates, while the FDA's Food Safety Modernization Act tightens aflatoxin testing protocols for domestic shelling operations. Georgia and Texas roasting capacity expansions enable geographic proximity contracting with K-12 and healthcare foodservice operators.
Argentina
Raw peanut export volumes fluctuate with drought-induced yield volatility, concentrating pricing power among Rosario-based origin traders during deficit years. The country's national food safety regulator enforces EU-aligned mycotoxin standards for export-bound shipments. Córdoba Province shelling facilities deploy hyperspectral imaging systems to maintain access to European confectionery markets.
China
High-heat frying demand in foodservice channels drives premium positioning for refined peanut oil, particularly in Guangdong and Sichuan provincial markets. The National Health Commission maintains aflatoxin limits under GB standards for domestic and import shipments. Shandong Province processing clusters integrate crushing capacity with regional snack manufacturing corridors.
India
Peanut oil consumption in traditional cooking applications sustains baseline demand, while Gujarat and Maharashtra processors expand blanching capacity for export-oriented confectionery supply. The Food Safety and Standards Authority of India enforces pesticide residue and mycotoxin surveillance for domestic distribution and overseas shipments. Saurashtra region shelling operations concentrate around Rajkot and Junagadh industrial zones.
Netherlands
European peanut butter manufacturing faces refrigeration retrofit costs under the EU F-Gas Regulation, raising controlled-temperature grinding overheads in Rotterdam and Amsterdam processing corridors. The European Food Safety Authority coordinates aflatoxin monitoring across import channels from South American and African origins. Dutch facilities pioneer ammonia and CO2 cascade systems for cold storage integration.
Processed Peanut Market Competitive Landscape
Concentration sits with integrated agribusiness conglomerates that control upstream origination and downstream roasting infrastructure. The vendor base spans multinational food manufacturers, regional roasting specialists, and commodity trading houses with crushing network extensions. Three archetypes dominate: vertically integrated oilseed processors with multi-belt sourcing networks; family-owned regional brands with retail channel equity; and private-label manufacturers serving supermarket consolidation programs. Competitive moves center on supply chain control through origination infrastructure and technology licensing for optical sorting compliance.
Within the integrated processor tier, Archer Daniels Midland Company exemplifies upstream control through multi-belt peanut origination networks. Hampton Farms occupies a position in family-owned regional brand equity, while John B. Sanfilippo & Son sits within the specialty blending segment for foodservice and confectionery technical specifications. These three anchors illustrate how competitive positioning diverges between scale-driven commodity supply and specification-driven premium channels.
| Leading Market Players |
|---|
| Hormel Foods |
| PepsiCo Inc. |
| John B. Sanfilippo & Son |
| The Kraft Heinz Company |
| Archer Daniels Midland Company |
| Frito-Lay North America |
| Whitley's Peanut Factory |
| Hampton Farms |
| Haldiram's India Pvt Ltd |
| Others |
Value Network & Pricing Analysis
High-oleic cultivar substitution for conventional runner varieties simultaneously redraws procurement geography toward southeastern United States growing belts and compresses the premium spread for aflatoxin-compliant export grades. This varietal shift rewards processors with captive shelling infrastructure while penalizing traders dependent on spot-market Argentine supply during drought cycles.
Pricing Analysis
The customization-premium spread between USDA Grade No. 1 contract specifications and standard commercial lots determines processor margin capture in United States spot markets. Pricing stratifies across premium, standard, and economy tiers based on aflatoxin certification thresholds and organic verification status. Cost compression in standard-grade roasted kernels is intensifying because Brazilian origin traders concentrate export supply during Argentine drought deficits. Foodservice distributors with multi-year origin contracts exhibit lowest price sensitivity, while commodity traders facing margin calls demonstrate highest responsiveness to spot price movements.
Supply Chain Analysis
Rosario port terminal congestion underwrites seasonal volatility in Argentine export availability, forcing European confectionery processors to maintain dual-sourcing relationships with United States and Brazilian shelling facilities. Raw peanut supply draws from Argentina, the United States, and Brazil as the three dominant origin markets. Critical dependencies include high-oleic seed stock, hyperspectral sorting equipment, and controlled-atmosphere cold storage infrastructure. Single-source vulnerability concentrates in Córdoba Province shelling capacity during South American harvest windows. Distribution runs through Rotterdam and Hamburg port clusters for European food manufacturing, with Savannah and Houston anchoring North American inland routing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional foodservice operators consolidating procurement through direct regional roaster contracts, fragmenting traditional distributor intermediaries that previously aggregated peanut butter and peanut oil supply.
For Market Incumbents: Secure upstream origination infrastructure in Georgia and Texas growing belts to defend against Argentine supply volatility and private-label margin compression. Invest in FSMA-compliant optical sorting certification to maintain access to K-12 and healthcare procurement channels. Channel control through geographic proximity roasting contracts represents the critical defensive lever against national private-label programs. For New Entrants and Emerging Players: Lead with specialized blanching and sizing capabilities targeting confectionery technical specifications where Mars Wrigley and Ferrero procurement systems create qualification barriers. The most penetrable white space sits in organic and heirloom variety peanut butter for specialty retail channels. A direct-to-foodservice go-to-market angle bypasses entrenched supermarket slotting fee structures. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors mid-scale processors with optical sorting compliance and regional roasting infrastructure over pure commodity traders. Long-term viability hinges on backward integration into shelling and captive supply of high-oleic cultivars. The signal to watch is FSMA enforcement intensity driving consolidation among sub-scale shelling operations unable to fund hyperspectral imaging retrofit.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Technology Deployment | FSMA compliance requirements reward early adopters of hyperspectral imaging with reduced aflatoxin rejection rates. |
| Backward Integration into Shelling | Captive shelling infrastructure insulates processors from Argentine supply volatility and origin trader pricing power. |
| High-Oleic Cultivar Conversion | Extended shelf-life specifications command premium positioning in Asian foodservice peanut oil channels. |
| Direct Foodservice Contracting | K-12 and healthcare procurement consolidation favors regional roasters with geographic proximity and origin documentation. |
| Cold Storage Refrigeration Retrofit | EU F-Gas Regulation compliance in European manufacturing enables continued access to confectionery export markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA crop reports, FDA enforcement disclosures, and EU import trade statistics to validate volume and value estimates. Primary interviews engaged peanut shelling facility managers, foodservice procurement directors at institutional distributors, confectionery technical specification leads, and optical sorting equipment vendors. Secondary validation drew from USDA National Agricultural Statistics Service data, FDA FSMA inspection records, and EU F-Gas Regulation implementation guidance. Bottom-up triangulation across processor capacity utilization and top-down reconciliation against end-use consumption patterns anchored forecast integrity.
Segmentation dimensions modeled include product type, end-use industry, packaging format, and distribution channel across the analysis window. CAGRs were derived from regression analysis of historical price-volume relationships and projected capacity expansion schedules. Industry-specific forecast inputs incorporated aflatoxin testing protocol evolution and high-oleic cultivar adoption curves in United States growing regions.
Forecasts assume regulatory continuity in FDA FSMA enforcement and EU F-Gas implementation; material policy shifts would require re-modeling of compliance cost structures and geographic sourcing strategies. Revision becomes warranted when Argentine drought severity or FSMA inspection intensity crosses thresholds that alter processor margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Porridge Market
Processed Foods
Pizza Market
Processed Foods
Africa Soup Market
Processed Foods
Block Margarine Market
Processed Foods
Fermented Foods Market
Processed Foods
Europe Soup Market
Processed Foods
Potato Soup Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
North America Ice Cream Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Tomato Puree Market
Processed Foods
Low Moisture Food Market
Processed Foods
Apple Butter Market
Processed Foods
Tomato Paste Market
Processed Foods
China Freeze-Dried Food Market