
 Processed Beef Market | 2026-2036
Processed Beef Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Beef Market Analysis
Brazilian beef processors is restructuring capacity allocation across export-oriented facilities. JBS S.A. leverages integrated cattle-feedlot-plant operations to control cost structures. Tyson Foods anchors North American supply through extensive cold-chain distribution networks. Marfrig Global Foods competes in premium grass-fed segments with specialized South American sourcing.
Processed beef comprises muscle tissue subjected to grinding, curing, smoking, or thermal treatment to extend shelf life and standardize eating quality, with fat content typically controlled between 15% and 30% depending on end-use application. Ground beef occupies the largest volume position across retail and food service channels due to its formulation flexibility and lower per-unit cost. Beef jerky demonstrates the fastest expansion trajectory among product types, driven by protein-snacking trends and extended shelf stability without refrigeration. Sausages and deli meats concentrate margin pools in branded, case-ready formats distributed through supermarket deli counters.
USDA Food Safety and Inspection Service mandates pathogen reduction performance standards and Hazard Analysis Critical Control Point systems throughout slaughter and further processing stages. FDA oversees ingredient additives and labeling claims under Federal Food, Drug, and Cosmetic Act provisions. Stakeholders must monitor evolving antibiotic residue thresholds and alternative protein labeling disputes that threaten conventional processed beef positioning in contested retail space.
Market Dynamics
Fast food chains are restructuring procurement specifications around extended shelf-life formulations and pathogen-reduction guarantees, pressuring processors to absorb compliance costs while maintaining volume commitments.
Growth Catalysts
- USDA Grading Standards:Prime and Choice grade premiums incentivize feedlot investment in marbling genetics, expanding the addressable premium processed beef pool.
- Protein-Snacking Formats:Shelf-stable jerky and sticks penetrate convenience retail and direct-to-consumer channels without cold-chain dependency.
- Brazil-Argentina-Australia Supply Zones:Integrated cattle-feedlot-plant complexes in these geographies compress unit costs through captive raw material access.
Market Restraints
- Feed Grain Price Volatility:Corn and soybean meal input costs swing with climate-induced harvest variability, compressing processor margins during price spikes.
- Antibiotic Residue Thresholds:FSIS zero-tolerance enforcement and EU import bans on hormone-treated cattle restrict sourcing flexibility for export-oriented plants.
- Plant-Based Substitution:Pea and mycoprotein analogs capture flexitarian trial in food service accounts, forcing defensive pricing in ground beef categories.
Strategic Opportunities
- Grass-Fed Certification Premiums:Pasture-raised protocols unlock margin expansion in European and North American natural retail channels.
- High-Pressure Processing:Cold-pasteurization technology extends refrigerated case-ready shelf life without thermal degradation of texture.
- E-Commerce Direct Fulfillment:Subscription box models bypass traditional distributor markups while capturing consumer preference data.
Industry Challenges
- HACCP Specialist Shortage:Qualified food safety plan developers command premium compensation, constraining smaller processor expansion timelines.
- Legacy Equipment Retrofit Costs:Automated trimming and grinding lines require capital deployment that mid-tier operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Beef Market |
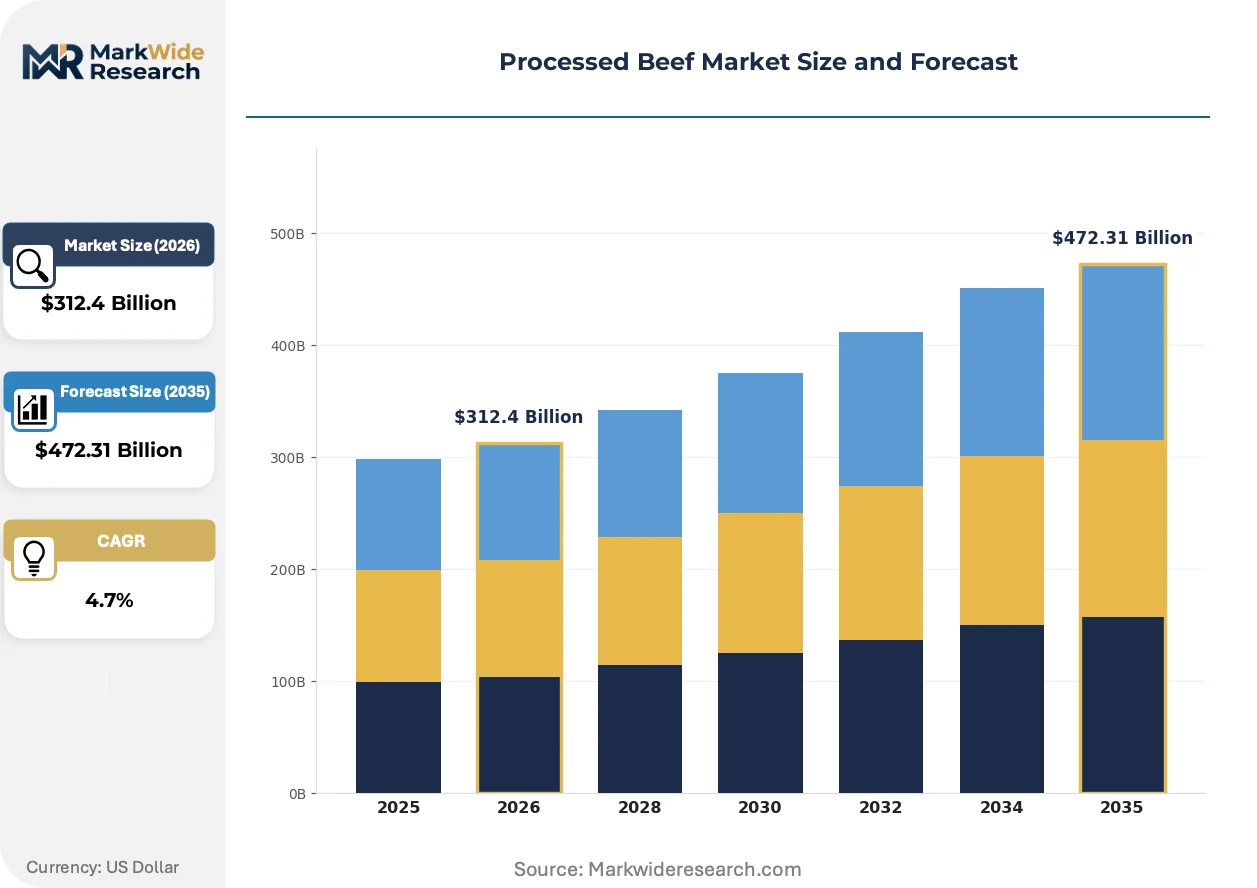
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $472.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Beef, Beef Jerky, Sausages, Deli Meats Customer Type: Retail Consumers, Food Service, Meat Processors, Wholesalers Packaging Type: Vacuum Packs, Canned, Modified Atmosphere, Chilled Packs End Use Sector: Restaurants, Supermarkets, Fast Food Chains, Catering Services |
| Companies Covered | JBS S.A., Tyson Foods, Marfrig Global Foods, Cargill, Kraft Heinz Company, National Beef Packing, Hormel Foods, WH Group, BRF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Beef Market Emerging Trajectories
Automation and alternative preservation methods are compressing labor dependency and extending distribution reach, while regulatory scrutiny of labeling claims intensifies formulation transparency requirements.
High-pressure processing technology is consolidating quality assurance protocols across case-ready beef operations. Retail chains and institutional food service buyers are adopting HPP-treated ground beef and sliced deli formats to eliminate Listeria and E. coli risks without sodium-laden chemical preservatives. This consolidation is compressing the competitive set to processors with capital-intensive cold-pasteurization infrastructure, marginalizing smaller plants dependent on thermal-only interventions.
EFSA novel food regulations and EU Green Deal farm-to-fork targets are tightening residue monitoring and carbon footprint disclosure obligations for South American exporters. Processors serving European Union member states must now document deforestation-free supply chains and embedded emissions through third-party verification. Grass-fed and organic certified product lines face the steepest compliance burden, with documentation costs absorbed disproportionately by premium segment operators.
Food service distributors are unbundling traditional broadline contracts to source processed beef through specialized protein purveyors with dedicated cold-chain assets. Regional restaurant chains are bypassing national broadliners to contract directly with single-source grinders capable of custom fat specification and lot-level traceability. This disintermediation is most pronounced in Texas, California, and Florida metro markets where independent processor networks have achieved sufficient scale to meet volume minimums without distributor intermediation.
Processed Beef Market Segmentation
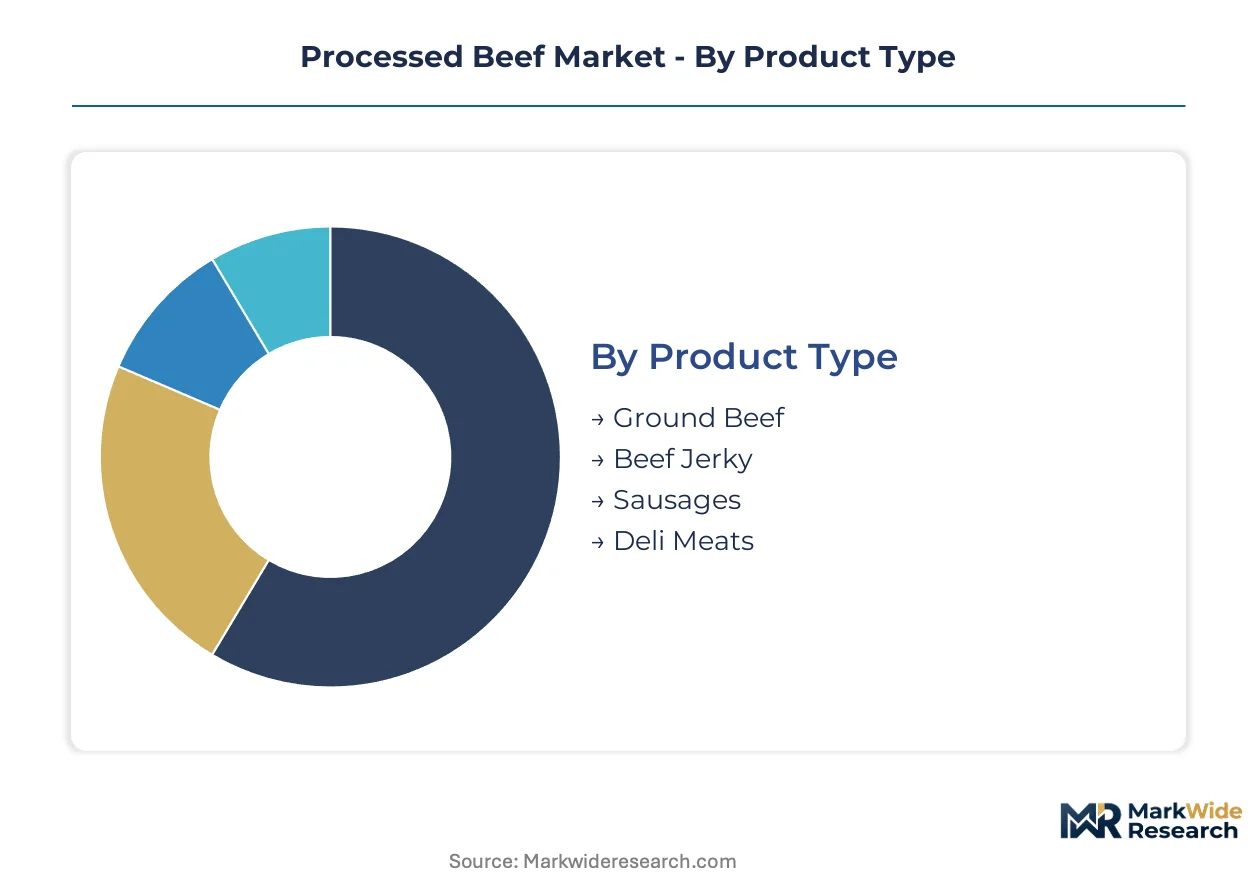
Processed beef procurement patterns diverge sharply across customer workflows, packaging requirements, and shelf-life demands. Formulation specifications and cold-chain dependencies create distinct margin pools that reward specialized production configurations over commodity scale.
Product Type:
Reformulation cycles accelerate where protein-snacking trends and convenience retail expansion create specification turnover every 18-24 months.
- Ground Beef:Finely textured muscle tissue with controlled fat content between 15% and 30% enables flexible portioning across retail and food service channels. Fast food chains in the United States and Brazil dominate procurement volumes, though price compression from plant-based alternatives constrains branded premium positioning.
- Beef Jerky:Dehydrated lean cuts with water activity below 0.85 achieve shelf stability without refrigeration, opening convenience retail and direct-to-consumer channels. Protein-snacking adoption in North American natural food stores and airport retail drives the steepest expansion trajectory among all product types.
- Sausages:Encased ground beef with spice and curing formulations concentrates margin in branded, case-ready supermarket formats.
- Deli Meats:Sliced and shaved cooked beef products serve institutional catering and premium supermarket deli counters with shorter production runs.
Volume placements concentrate in Ground Beef; the faster expansion belongs to Beef Jerky.
Customer Type:
Procurement sophistication varies with scale, driving tiered service requirements from spot-market purchasing to integrated supply contracts.
- Retail Consumers:Individual households purchasing through supermarkets and e-commerce platforms demand transparent labeling and portion-controlled formats. USDA grading familiarity and price sensitivity in suburban United States markets shape private-label versus branded trade-offs.
- Food Service:Restaurants, cafeterias, and institutional kitchens require consistent fat specifications and lot-level traceability for HACCP documentation. Direct contracting with single-source grinders in Texas and California metro markets is displacing traditional broadline distributor relationships.
- Meat Processors:Secondary manufacturers purchasing intermediate cuts for further value-added production seek backward integration opportunities to secure captive raw material access.
- Wholesalers:Inventory aggregation and break-bulk distribution functions face margin compression as regional chains bypass intermediaries for direct processor relationships.
Contract volumes cluster with Food Service; margin expansion is climbing the fastest among Retail Consumers through subscription and direct-fulfillment models.
Packaging Type:
Capital deployment in preservation technology separates processors capable of extended distribution reach from those confined to regional cold-chain radii.
- Vacuum Packs:Oxygen exclusion through barrier films extends refrigerated shelf life to 21-28 days, supporting case-ready retail programs. Walmart and Kroger distribution centers in the United States mandate this format for ground beef and sliced deli categories.
- Canned:Thermal sterilization in retort pouches or metal containers enables ambient storage for emergency preparedness and military procurement channels.
- Modified Atmosphere:Controlled gas mixtures of nitrogen and carbon dioxide preserve color and inhibit spoilage organisms in premium chilled retail formats.
- Chilled Packs:Basic overwrap configurations with limited shelf life serve food service accounts with rapid inventory turnover and localized sourcing.
Equipment investment concentrates in Vacuum Packs; technology adoption is expanding most quickly in Modified Atmosphere as European retailers impose carbon footprint disclosure requirements.
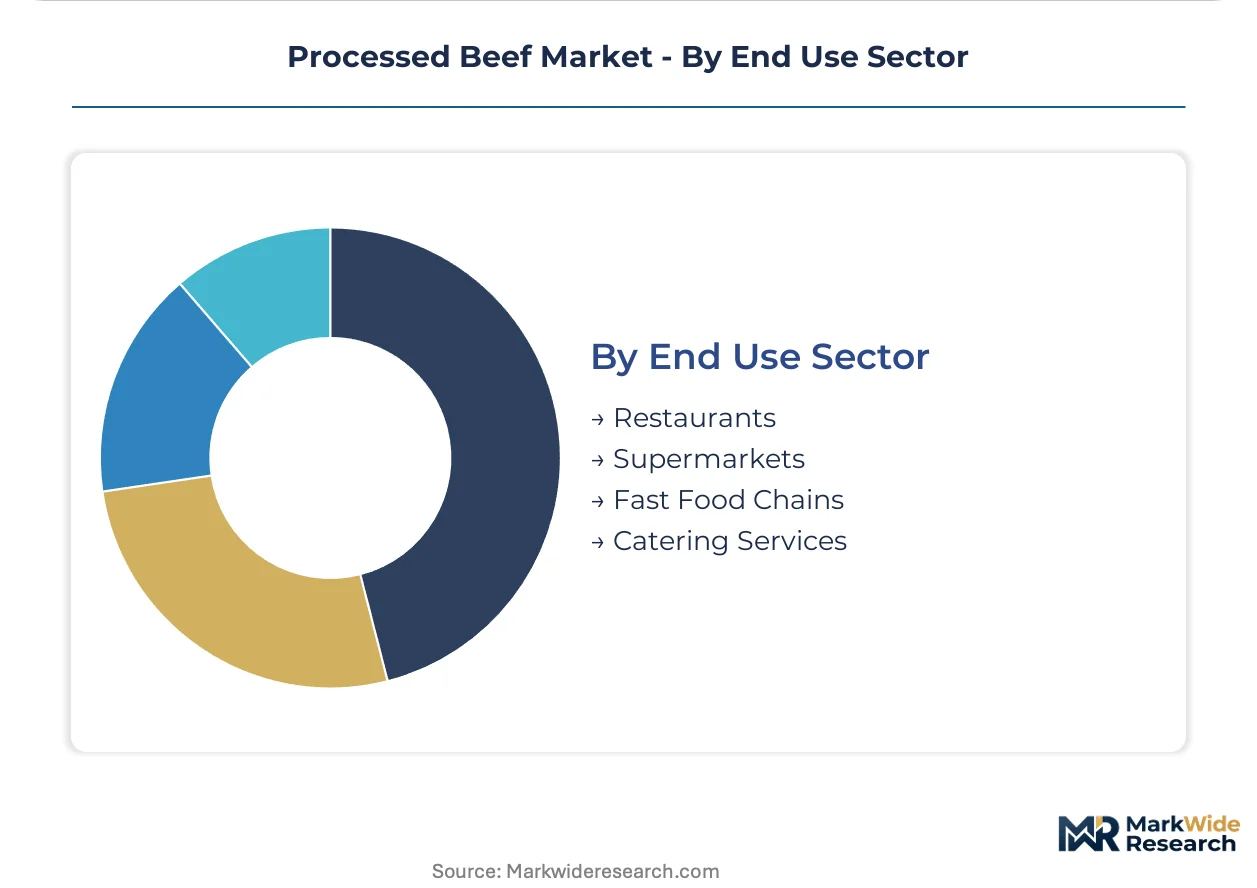
End Use Sector:
Menu innovation velocity and procurement centralization create divergent specification demands across eating occasions.
- Restaurants:Full-service establishments demand custom grind specifications and chef-driven premium cuts with provenance documentation. Independent steakhouse chains in São Paulo and Buenos Aires source grass-fed certified product for differentiation.
- Supermarkets:Retail deli counters and meat cases require case-ready formats with consistent appearance and extended code dates for labor reduction. High-pressure processing adoption is consolidating supplier relationships to processors with capital-intensive cold-pasteurization infrastructure.
- Fast Food Chains:Centralized procurement specifications around extended shelf-life formulations and pathogen-reduction guarantees pressure processors to absorb compliance costs while maintaining volume commitments.
- Catering Services:Event and institutional feeding operations prioritize portion control and holding stability over premium grading.
Procurement scale aggregates with Fast Food Chains; margin recovery is gaining share fastest in Supermarkets through branded, value-added format penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grassland cattle-rearing territories in Brazil, Argentina, and Australia anchor raw material flows for processed beef conversion. USDA grading infrastructure in the United States and EFSA residue protocols in Europe shape finished product specifications. Processing capacity concentrates near port logistics corridors in São Paulo, Buenos Aires province, and Queensland.
United States
Fast food procurement centralization drives volume demand for standardized ground beef formulations. USDA FSIS enforces zero-tolerance pathogen standards and HACCP documentation across slaughter and further processing stages. Nebraska and Kansas feedlot corridors supply captive raw material to integrated processors in Greeley, Colorado, and Dakota Dunes, South Dakota.
Brazil
Export-oriented plants in São Paulo state process grass-fed cattle for European Union and Middle East destinations. ANVISA monitors antibiotic residue thresholds while MAPA enforces export certification for deforestation-free supply chains under EU Green Deal requirements. JBS S.A. and Marfrig Global Foods operate integrated feedlot-plant complexes in Mato Grosso and Goiás.
Argentina
Pampas pasture-raised cattle supply premium grass-fed segments for natural retail channels in North America and Europe. SENASA administers export health certification and hormone-free verification for EU market access. Buenos Aires province packing plants specialize in chilled vacuum-packed cuts for supermarket deli programs.
Australia
Queensland and New South Wales feedlots supply grain-finished cattle for Japanese and Korean import quotas. FSANZ mandates nutrition labeling and residue testing for domestic retail and export certification. Brisbane and Townsville processing corridors concentrate HPP-equipped facilities for extended shelf-life case-ready formats.
Germany
Discount supermarket chains drive private-label processed beef procurement with strict cost specifications. EFSA enforces novel food regulations and farm-to-fork carbon disclosure under EU Green Deal targets. Lower Saxony meat processing clusters specialize in sausage and deli formats for central European distribution.
Processed Beef Market Vendor Landscape
Global majors compete with regional champions across integrated supply chain control and cold-chain distribution reach. The market structures around three tiers: multinational protein conglomerates with feedlot-to-retail integration, mid-scale regional processors with specialized certification access, and commodity grinders serving spot-market food service accounts. Dominant competitive moves include backward integration into cattle feeding operations and HPP technology licensing for pathogen reduction guarantees.
Within the multinational tier, JBS S.A. and Tyson Foods exemplify divergent geographic anchoring strategies. JBS S.A., a Brazilian S.A.-structured entity, occupies a position centered on South American grass-fed supply access and European premium segment penetration. Tyson Foods, an American Inc.-structured processor, anchors North American volume through extensive refrigerated distribution infrastructure. Marfrig Global Foods, another Brazilian S.A., sits within the specialty certification tier with pasture-raised product lines targeting deforestation-free supply chain requirements.
| Leading Market Players |
|---|
| JBS S.A. |
| Tyson Foods |
| Marfrig Global Foods |
| Cargill |
| Kraft Heinz Company |
| National Beef Packing |
| Hormel Foods |
| WH Group |
| BRF |
| Others |
Supply Flow & Price Mechanics
EU Green Deal deforestation-free supply chain mandates gate qualified raw material access and premium-tier pricing eligibility for South American exporters serving European supermarket accounts. Processors lacking third-party verification documentation face automatic exclusion from contract bidding pools regardless of cost competitiveness.
Pricing Analysis
Pathogen-reduction warranty bundling separates processors offering HPP-treated case-ready formats from commodity suppliers selling unenhanced chilled packs. Three-tier pricing structure across premium grass-fed, standard grain-finished, and economy blended formulations reflects certification grade and cold-chain service inclusion. Pricing pressure stems from plant-based ground beef alternatives forcing defensive positioning in fast food procurement tenders. Food service distributors exhibit highest price sensitivity due to volume consolidation leverage, while natural retail channels absorb premiums for traceability documentation.
Supply Chain Analysis
Slaughterhouse labor availability constraints in Nebraska, Kansas, and São Paulo state processing corridors compress operating rates during peak cattle supply windows. Raw material flows draw from Mato Grosso feedlots, Pampas pasture operations, and Queensland grain-finishing facilities. Supply chain risk centers on single-source vulnerability to ANVISA antibiotic residue enforcement actions disrupting Brazilian export certification. Distribution runs through refrigerated consolidation hubs serving Walmart and Kroger case-ready programs in the United States, plus direct fulfillment networks bypassing traditional broadline intermediaries in Texas and California metro markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing technology is displacing thermal pasteurization legacy systems, compressing the qualified supplier set to capital-equipped processors and restructuring procurement relationships around extended shelf-life guarantees.
For Market Incumbents: Extend HPP infrastructure licensing to captive regional processors, converting capital-light competitors into fee-paying technology adoptees while defending volume position against plant-based substitution threats in ground beef categories. Deepen backward integration into Mato Grosso and Goiás feedlot operations to secure deforestation-free supply chain documentation required for EU Green Deal compliance. For New Entrants and Emerging Players: The mid-market price-point gap between JBS S.A. premium grass-fed lines and commodity economy blends offers white-space targeting for pasture-raised certified products with direct-to-consumer subscription fulfillment. Penetrate airport retail and convenience channels with shelf-stable jerky formats requiring no cold-chain investment. Pursue co-manufacturing partnerships with underutilized HPP-equipped facilities to bypass capital barriers. For Investors and Strategic Acquirers: ANVISA enforcement actions triggering temporary export suspensions are the leading indicator that integrated feedlot-plant assets with captive supply documentation will command scarcity premiums. The five-to-ten year viability window favors processors with verified deforestation-free supply chains and HPP technology licensing revenue streams. Target acquisition candidates include mid-scale Brazilian operators with MAPA export certification and underexploited European supermarket relationships.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Licensing | Converts capital-constrained competitors into revenue-generating technology licensees while expanding pathogen-reduction standard adoption. |
| Backward Integration into Feedlots | Captures deforestation-free supply chain documentation required under EU Green Deal farm-to-fork disclosure mandates. |
| Direct-to-Consumer Subscription Launch | Bypasses distributor markups while capturing consumer preference data for formulation optimization in protein-snacking formats. |
| Grass-Fed Certification Investment | Unlocks premium positioning in European and North American natural retail channels with margin expansion potential. |
| Co-Manufacturing Partnership Expansion | Utilizes excess HPP capacity at regional processors to serve emerging brands without capital-intensive facility construction. |
Methodological Framework
Multi-period observation of cattle futures pricing, feed grain input costs, and export certification volumes anchored the trend analysis, supplemented by interviews with plant operations managers, FSIS compliance officers, supermarket category buyers, and food service procurement directors. Secondary validation drew from USDA NASS livestock reports, MAPA export statistics, ANVISA residue monitoring disclosures, and EU TRACES certification databases. Bottom-up processor capacity modeling and top-down consumption demand estimation were triangulated against trade flow data.
Input-output matrix construction mapped feedlot placement rates, slaughter capacity utilization, and further processing conversion yields across product type, packaging format, and end-use sector dimensions over the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating protein-snacking adoption curves and fast food procurement contract renewal patterns. Forecast inputs included climate-induced feed grain harvest variability assumptions and evolving EU Green Deal carbon disclosure compliance cost estimates.
Inputs from MAPA certification registries and USDA FSIS enforcement disclosures were available through the study window; gaps in private processor margin data introduce uncertainty bands around profitability projections. Forecasts reflect documented assumptions regarding antibiotic residue threshold enforcement continuity and HPP technology adoption rates. Material deviation in EU deforestation-free supply chain verification requirements or ANVISA suspension triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
US Tomato Paste Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
United States Egg Powder Market
Processed Foods
Spray Cheese Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Africa Soup Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
United States Processed Meat Market
Processed Foods
Egg Powder Market
Processed Foods
Coffee Creamer Market
Processed Foods
Fruit Processing Market
Processed Foods
United States Food Spread Market
Processed Foods
Butter Crisco Market