
 Chlorocyclopentane Market | 2026-2036
Chlorocyclopentane Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorocyclopentane Market Insights
The chlorocyclopentane market is shifting along a widening gap between high-purity grades bound for pharmaceutical intermediates and commodity volumes serving solvent applications. Haltermann Carless Group GmbH leverages its European refinery integration to sustain premium-grade supply chains. Junyuan Petroleum Group anchors its position through captive cyclopentane feedstock access in Shandong Province. INEOS competes on scale, operating multi-site chlorination capacity that extends across its European and North American manufacturing footprint.
Chlorocyclopentane is a halogenated cycloalkane with the molecular formula C5H9Cl, produced via direct chlorination of cyclopentane or hydrohalogenation of cyclopentene, and serves primarily as a reactive intermediate in organic synthesis and as a specialty solvent in precision cleaning applications. The intermediates segment dominates value capture due to stringent purity thresholds imposed by downstream pharmaceutical and agrochemical manufacturers, while the solvents application faces margin compression from regulatory limits on halogenated volatile organic compounds. Laboratory grade products command premium pricing relative to industrial grade volumes, reflecting divergent certification burdens and lot-traceability requirements that chemical manufacturers and research labs impose through their procurement specifications.
The EPA regulates chlorocyclopentane under the Toxic Substances Control Act, requiring pre-manufacture notifications that shape market entry timelines for new suppliers. REACH registration obligations in Europe impose full substance dossiers on importers above one tonne annually, elevating compliance costs that favor established producers with dedicated regulatory affairs capacity. ECHA's persistent organic pollutant screening criteria further constrain formulation flexibility in coatings applications. Stakeholders must monitor evolving restrictions on halogenated solvents under the EU Green Deal's chemical sustainability strategy and position their grade portfolios accordingly.
Market Dynamics
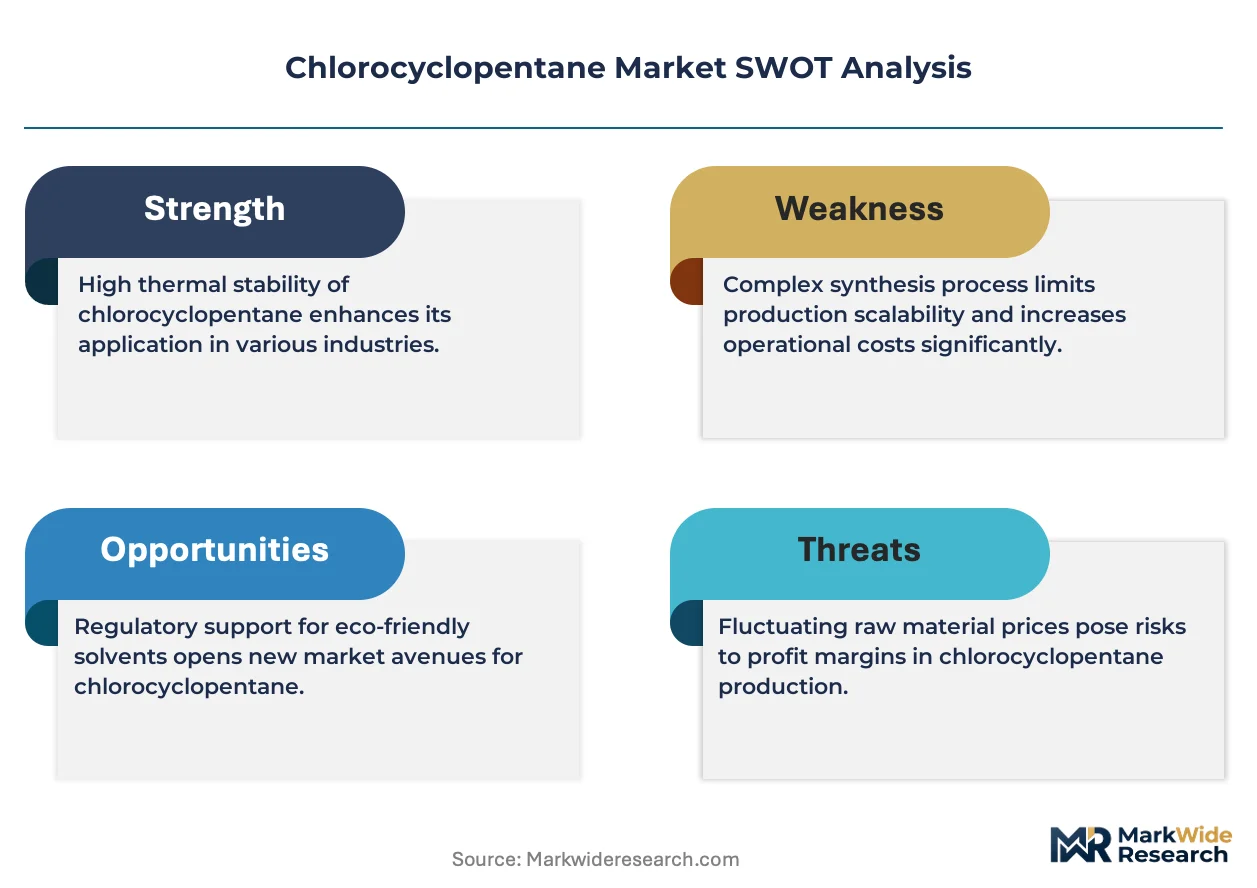
Specialty chemical manufacturers face a structural squeeze between tightening purity mandates for pharmaceutical intermediates and margin erosion in solvent applications, forcing grade portfolio reconfiguration across production networks.
Growth Catalysts
- Agrochemical intermediate demand:Specialty manufacturers are expanding procurement of chlorocyclopentane for crop protection synthesis, driven by patent cliff pressures on legacy active ingredients.
- REACH compliance elevation:Full substance dossier requirements above one tonne annually favor established producers with dedicated regulatory affairs capacity, consolidating supply relationships.
- Shandong petrochemical integration:Captive cyclopentane feedstock access through integrated refining corridors is compressing production costs for Chinese pharmaceutical synthesis capacity.
Market Restraints
- Feedstock volatility:Cyclopentane supply concentration in refinery byproduct streams exposes margins to crude slate shifts and alkylation unit economics.
- VOC regulatory friction:EPA Toxic Substances Control Act pre-manufacture notifications and EU volatile organic compound limits extend new supplier entry timelines by 18-36 months.
- Halogenated solvent substitution:Precision cleaning applications face displacement from aqueous and supercritical CO2 systems in aerospace and electronics sectors.
Strategic Opportunities
- Laboratory grade premium capture:Lot-traceability requirements from research institutions and CROs support three-tier pricing stratification across certification levels.
- EU Green Deal chemical sustainability:Persistent organic pollutant screening criteria create first-mover advantage for producers with halogen recovery and circular process credentials.
- Continuous chlorination technology:Convergence of flow chemistry with membrane separation is enabling modular unit operations that reduce batch-to-batch variability.
Industry Challenges
- Pharmaceutical certification timelines:GMP compliance and API starting material qualification require 12-24 month validation cycles that strain working capital.
- Analytical chemist scarcity:Gas chromatography method development and impurity profiling expertise gaps constrain quality control throughput at mid-scale producers.
- Multi-site regulatory harmonization:Cross-border substance dossier maintenance between EPA and ECHA jurisdictions duplicates compliance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorocyclopentane Market |
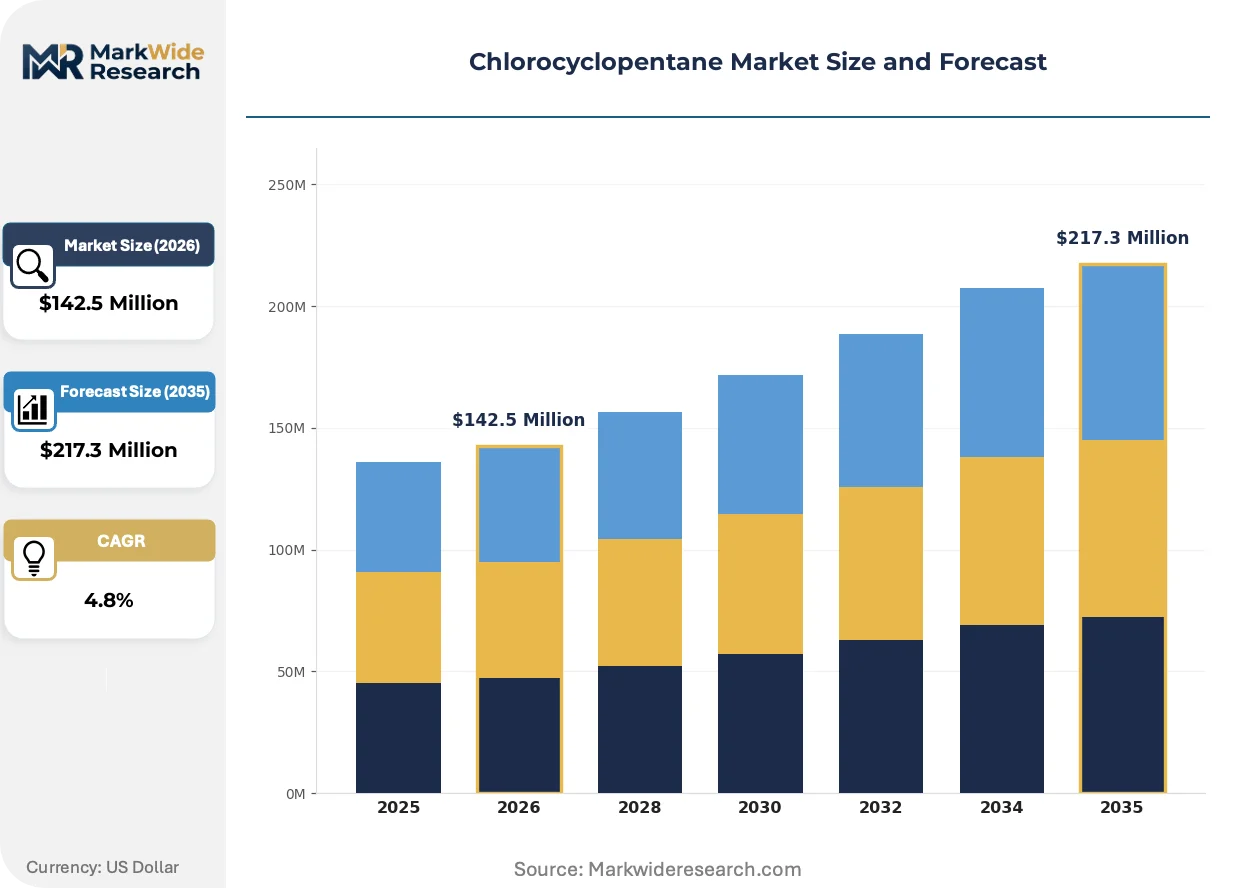
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Refrigerants, Solvents, Intermediates, Coatings Product Type: Industrial Grade, Laboratory Grade, Research Grade, Commercial Grade End User: Chemical Manufacturers, Pharmaceutical Companies, Academic Institutions, Research Labs Form: Liquid, Solid, Powder, Gas |
| Companies Covered | Haltermann Carless Group GmbH, Junyuan Petroleum Group, INEOS, Zeon Corporation, Puyang Zhongwei Fine Chemical Co., Ltd., Chevron Phillips Chemical Company LLC, Maruzen Petrochemical, SK Geo Centric Co., Ltd., Haldia Petrochemicals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorocyclopentane Market Trends and Innovations
Process intensification and regulatory transparency requirements are compressing batch sizes while fragmenting grade specifications, creating pressure for flexible manufacturing architectures.
Continuous flow chlorination reactor systems are modularizing production footprints by replacing conventional batch vessels with skid-mounted reaction-separation units. Pharmaceutical intermediate manufacturers in Germany and Switzerland are adopting these configurations to reduce solvent inventory and accelerate campaign changeovers. The technology is modularizing capital deployment, allowing producers to scale capacity in 500-tonne increments rather than committing to dedicated multi-kilotne trains.
ECHA's persistent organic pollutant screening criteria under the EU Green Deal chemical sustainability strategy are tightening formulation flexibility for coatings applications. Industrial solvent distributors face portfolio rationalization pressures as downstream formulators seek pre-approved substance lists. Laboratory grade suppliers with established substance dossiers are capturing share from commodity traders lacking regulatory affairs infrastructure.
Contract research organizations and virtual pharmaceutical developers are consolidating procurement through qualified supplier programs that bundle starting materials with analytical method packages. Traditional merchant chemical distributors face disintermediation as direct manufacturer relationships offer lot-level documentation and faster technical response. The shift is most visible in Massachusetts and North Carolina biotech clusters where CMOs specify captive supply agreements over spot market purchasing.
Chlorocyclopentane Market Segmentation
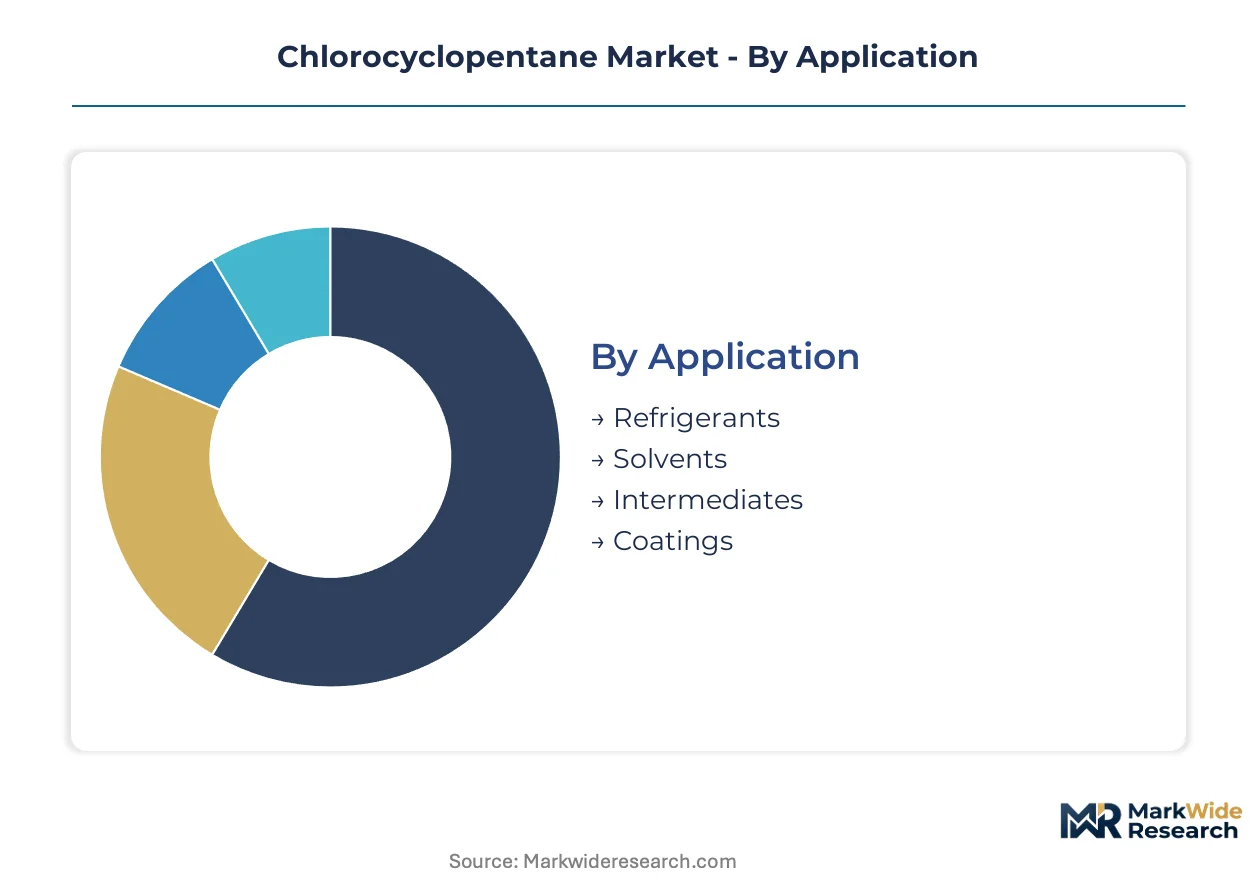
Chlorocyclopentane demand fragments across purity tiers and application requirements that reshape procurement patterns. Pharmaceutical intermediates command lot-level traceability while solvent applications face regulatory displacement, creating divergent margin architectures within the same molecular backbone.
Application:
Supply concentration in cyclopentane feedstock corridors determines which applications capture priority allocation from chlorination capacity.
- Intermediates:Reactive building blocks for agrochemical and pharmaceutical synthesis require 99.5%+ purity with full impurity profiling documentation. Demand concentrates in Shandong Province's integrated petrochemical corridors where captive cyclopentane access supports pharmaceutical synthesis scale-up.
- Solvents:Precision cleaning formulations for aerospace and electronics manufacturing face margin compression from EPA volatile organic compound limits and EU halogenated solvent restrictions. Substitution pressure from aqueous and supercritical CO2 systems is accelerating in Massachusetts and North Carolina manufacturing clusters.
- Refrigerants:Heat transfer fluids in specialized cooling systems.
- Coatings:Industrial formulations confronting ECHA persistent organic pollutant screening criteria under EU Green Deal chemical sustainability mandates.
Intermediates absorb the bulk of installed capacity; coatings is expanding most quickly as formulators seek pre-approved substance lists.
Product Type:
Cost tier stratification separates certification burdens from volume commodity positioning.
- Laboratory Grade:Stringent lot-traceability requirements from contract research organizations and academic institutions support premium pricing tiers. Gas chromatography method development and impurity profiling expertise constraints at mid-scale producers limit qualified supply.
- Industrial Grade:Bulk volumes serving solvent and coatings applications operate on thinner margins with reduced documentation burdens. REACH registration obligations above one tonne annually favor established producers with dedicated regulatory affairs infrastructure.
- Research Grade:Small-batch production for exploratory synthesis with flexible specification windows.
- Commercial Grade:Standardized volumes for established industrial processes with defined performance thresholds.
Laboratory grade commands the steepest price premium; industrial grade moves the largest absolute volumes.
End User:
Customer type determines procurement modality and technical service intensity.
- Pharmaceutical Companies:GMP compliance and API starting material qualification require 12-24 month validation cycles that strain working capital. Virtual pharmaceutical developers in Massachusetts and North Carolina biotech clusters consolidate procurement through qualified supplier programs bundling materials with analytical method packages.
- Chemical Manufacturers:Specialty chemical producers face structural pressure between tightening purity mandates for pharmaceutical intermediates and margin erosion in solvent applications, forcing grade portfolio reconfiguration.
- Academic Institutions:Research-driven procurement with flexible volume requirements and extended payment terms.
- Research Labs:Fragmented demand with high specification variability and documentation requirements.
Pharmaceutical companies dominate value capture; research labs are gaining share fastest as contract research organization outsourcing expands.
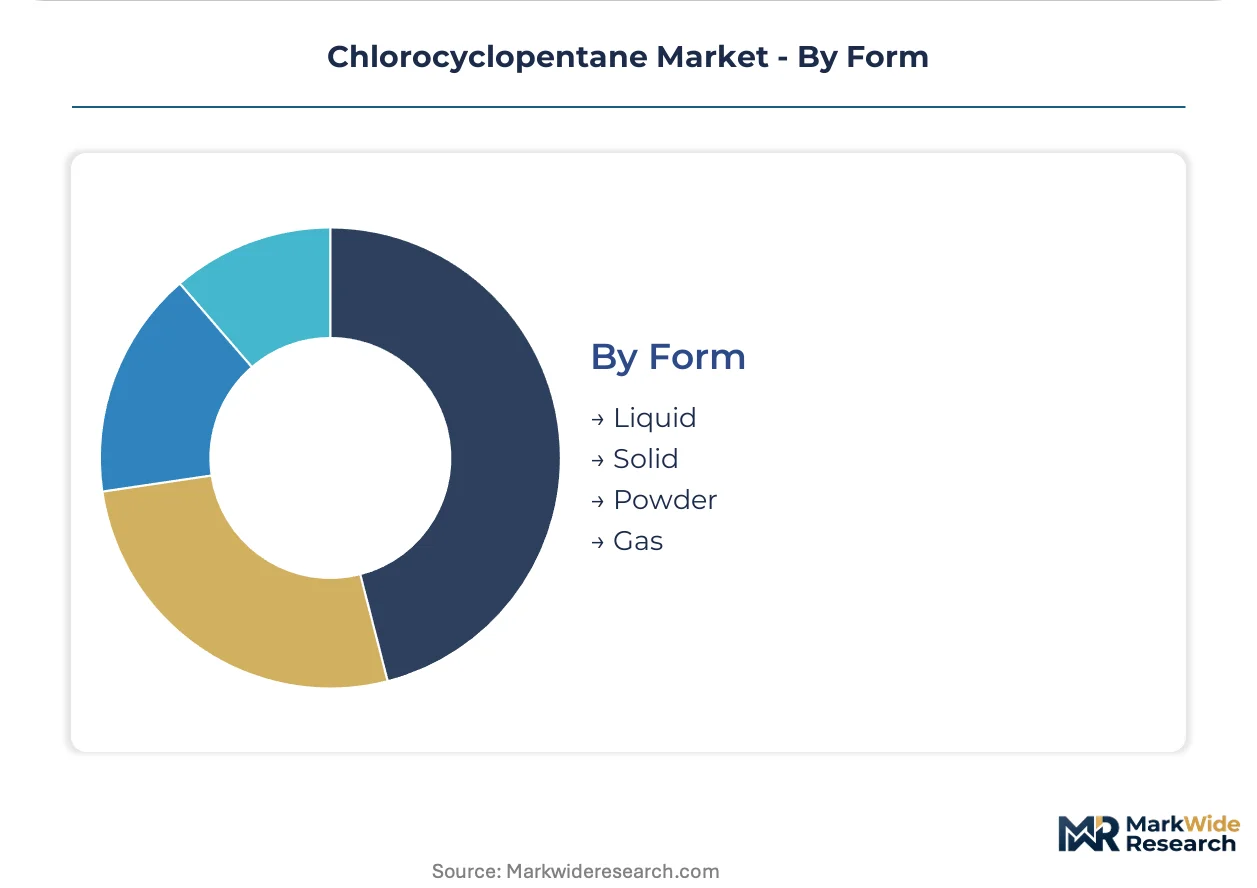
Form:
Physical state constrains handling infrastructure and distribution economics.
- Liquid:Standard bulk delivery format for industrial and laboratory applications with established drum and tote logistics networks.
- Solid:Specialized handling for specific synthesis protocols requiring precise dosing control.
- Powder:Niche formulations for research applications with moisture sensitivity requirements.
- Gas:Limited applications in specialized vapor-phase processes with containment infrastructure demands.
Liquid form absorbs the bulk of installed capacity; solid form is climbing the fastest as process intensification reduces solvent inventory requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's integrated petrochemical corridors anchor chlorocyclopentane production gravity, with captive cyclopentane feedstock access supporting pharmaceutical synthesis scale-up across China's northern coastal manufacturing belt.
United States
Massachusetts and North Carolina biotech clusters drive pharmaceutical intermediate procurement through qualified supplier programs bundling starting materials with analytical method packages. EPA Toxic Substances Control Act pre-manufacture notifications extend new supplier entry timelines by 18-36 months, consolidating established producer relationships. Houston's petrochemical complex sustains multi-site chlorination capacity serving agrochemical synthesis demand.
Germany
Pharmaceutical intermediate manufacturers in Germany and Switzerland adopt continuous flow chlorination reactor systems to reduce solvent inventory and accelerate campaign changeovers. REACH registration obligations above one tonne annually favor established producers with dedicated regulatory affairs infrastructure. The country's national chemical regulator enforces full substance dossier requirements that elevate compliance costs for importers.
China
Junyuan Petroleum Group leverages captive cyclopentane feedstock access in Shandong Province to compress production costs for expanding domestic pharmaceutical synthesis capacity. The Ministry of Ecology and Environment implements dual carbon goals that constrain halogenated solvent formulation flexibility. Yangtze River Delta contract research organizations consolidate procurement through direct manufacturer relationships offering lot-level documentation.
Japan
Zeon Corporation and Maruzen Petrochemical anchor domestic cyclopentane derivative supply chains serving precision electronics cleaning applications. METI industrial standards shape volatile organic compound limits that accelerate substitution pressure from aqueous and supercritical CO2 systems. Osaka-Kobe manufacturing clusters face margin compression as downstream formulators seek pre-approved substance lists.
South Korea
SK Geo Centric Co., Ltd. operates integrated petrochemical capacity supporting chlorocyclopentane intermediate production for regional agrochemical export markets. The Ministry of Trade, Industry and Energy enforces chemical management frameworks aligned with OECD guidelines. Busan-Ulsan industrial corridors concentrate specialty chemical manufacturing serving pharmaceutical contract manufacturing organizations across Northeast Asia.
Chlorocyclopentane Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with laboratory-grade suppliers capturing three-tier pricing advantages over industrial-grade volume operators. The vendor base organizes around regulatory dossier depth rather than manufacturing scale alone, creating tiered entry barriers that consolidate supply relationships with pharmaceutical and agrochemical end-users. Three archetypes dominate: integrated petrochemical majors with captive feedstock access, specialty chemical houses with dedicated regulatory affairs capacity, and regional distributors facing disintermediation pressure from direct manufacturer relationships. Capacity expansion and portfolio diversification toward high-purity grades constitute the dominant competitive moves as solvent applications face regulatory displacement.
Within the integrated petrochemical tier, Haltermann Carless Group GmbH and Junyuan Petroleum Group exemplify contrasting geographic anchoring strategies, with the former leveraging European refinery integration and the latter exploiting Shandong Province's captive cyclopentane corridors. INEOS occupies a position spanning multi-site chlorination capacity across European and North American manufacturing footprints, representing scale-driven competitive positioning.
| Leading Market Players |
|---|
| Haltermann Carless Group GmbH |
| Junyuan Petroleum Group |
| INEOS |
| Zeon Corporation |
| Puyang Zhongwei Fine Chemical Co., Ltd. |
| Chevron Phillips Chemical Company LLC |
| Maruzen Petrochemical |
| SK Geo Centric Co., Ltd. |
| Haldia Petrochemicals Limited |
| Others |
Pricing and Supply Chain Analysis
Cyclopentane spot price volatility at refineries in Shandong Province and Rotterdam cascades through chlorination economics, compressing margins for commodity-grade solvent producers while amplifying premium capture for laboratory-grade suppliers with REACH dossier depth.
Pricing Analysis
Yield-based pricing anchors pharmaceutical intermediate contracts, with lot-traceability premiums scaling to impurity specification stringency. Three-tier pricing structure across laboratory, industrial, and research grades separates certification-burdened volumes from commodity spot transactions. Cost compression in industrial-grade solvents intensifies because EPA volatile organic compound limits accelerate substitution toward aqueous systems. Contract research organizations exhibit lowest price sensitivity; bulk coatings formulators face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Shandong Province's integrated petrochemical corridors, where Junyuan Petroleum Group and Puyang Zhongwei Fine Chemical Co., Ltd. anchor cyclopentane feedstock access. Chlorocyclopentane production draws from cyclopentane refinery bystreams, chlorine gas supply contracts, and hydrohalogenation catalyst inventories. Tariff exposure on halogenated solvent imports into the European Union constrains formulation flexibility for coatings distributors. Distribution runs through qualified supplier programs bundling materials with analytical method packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration obligations above one tonne annually erect regulatory moats favoring established producers with dedicated dossier maintenance capacity.
For Market Incumbents: Anticipate displacement pressure from supercritical CO2 precision cleaning systems in Massachusetts and North Carolina aerospace clusters by deepening captive cyclopentane integration in Shandong Province. Accelerate continuous flow chlorination deployment to reduce batch-to-batch variability and compress GMP validation cycles for pharmaceutical intermediate customers.
For New Entrants and Emerging Players: Begin with laboratory-grade supply to contract research organizations in the Yangtze River Delta, where lot-traceability requirements and gas chromatography method development gaps constrain qualified supply. Pursue direct manufacturer relationships offering bundled analytical packages rather than competing through commodity distributors facing disintermediation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European specialty chemical houses with dormant REACH dossiers and underutilized chlorination capacity in Germany. Monitor ECHA persistent organic pollutant screening criteria implementation as the inflection signal for coatings application viability and portfolio rationalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclopentane Feedstock | Captive supply from Shandong refining corridors compresses production costs for pharmaceutical synthesis scale-up. |
| Continuous Flow Chlorination Technology Deployment | Modular reaction-separation units reduce solvent inventory and accelerate campaign changeovers for German pharmaceutical manufacturers. |
| REACH Dossier Expansion and Maintenance | Full substance dossiers above one tonne annually consolidate supply relationships with agrochemical and pharmaceutical end-users. |
| Laboratory Grade Certification Investment | Lot-traceability capabilities capture premium pricing tiers from contract research organizations and academic institutions. |
| Halogen Recovery and Circular Process Credentials | EU Green Deal chemical sustainability alignment creates first-mover advantage in coatings formulation pre-approval lists. |
Research Methodology
Independent corroboration across plant managers at chlorination facilities, procurement leads at downstream agrochemical manufacturers, and distribution channel partners underwrites the qualitative findings. Technical R&D directors and regulatory affairs specialists at specialty chemical houses provided primary perspective on purity mandate evolution. Secondary validation drew from customs and trade data, Cefic sector reports, SEC 10-K filings from petrochemical majors, and ECHA substance dossier repositories. Bottom-up capacity modeling and top-down demand segmentation were triangulated to anchor volume estimates.
Comparable-period anchoring to historical refinery byproduct economics and pharmaceutical intermediate procurement cycles shaped the projection horizon. The analytical framework modeled grade tier, end-use industry, and regional production hub segmentation throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating cyclopentane feedstock cost trajectories and regulatory compliance cost escalations. Pharmaceutical synthesis capacity expansion in China and agrochemical patent cliff pressures served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; laboratory-grade volumes carry tighter precision than commodity solvent applications given consolidated supplier concentration. Forecasts reflect assumptions on REACH implementation timing, EPA volatile organic compound enforcement intensity, and substitution rates for halogenated cleaning systems. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
US Humate Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Phenol Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Dioxolane Market